
 North America BPA Free Plastic Market | 2026-2036
North America BPA Free Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
North America BPA Free Plastic Market Analytics
Multi-source resin procurement is realigning how North American packaging converters manage polymer supply security. Amcor plc leverages its continental manufacturing footprint to sustain consistent feedstock access across multiple polymer categories. Eastman Chemical Company anchors its position through specialty copolyester capacity that serves brands seeking heat-resistant, BPA-free alternatives. Dow Inc. competes on polyethylene scale, while LyondellBasell Industries N.V. controls polypropylene supply chains that feed bottle and container molding operations.
BPA free plastic denotes thermoplastic formulations manufactured without bisphenol A monomer, typically substituting with polyethylene terephthalate glycol-modified (PETG), tritan copolyesters, or polypropylene resins processed below degradation thresholds to prevent residual contamination. These materials serve food-contact, medical-device, and consumer-product applications where endocrine-disruptor avoidance is specified. Bottles and containers occupy the largest product-type position, though medical-device applications within the healthcare end-user segment represent the fastest-expanding margin pool due to sterilization-grade certification requirements. Polypropylene and polyethylene together dominate the material mix, with polycarbonate alternatives receding as regulatory scrutiny intensifies.
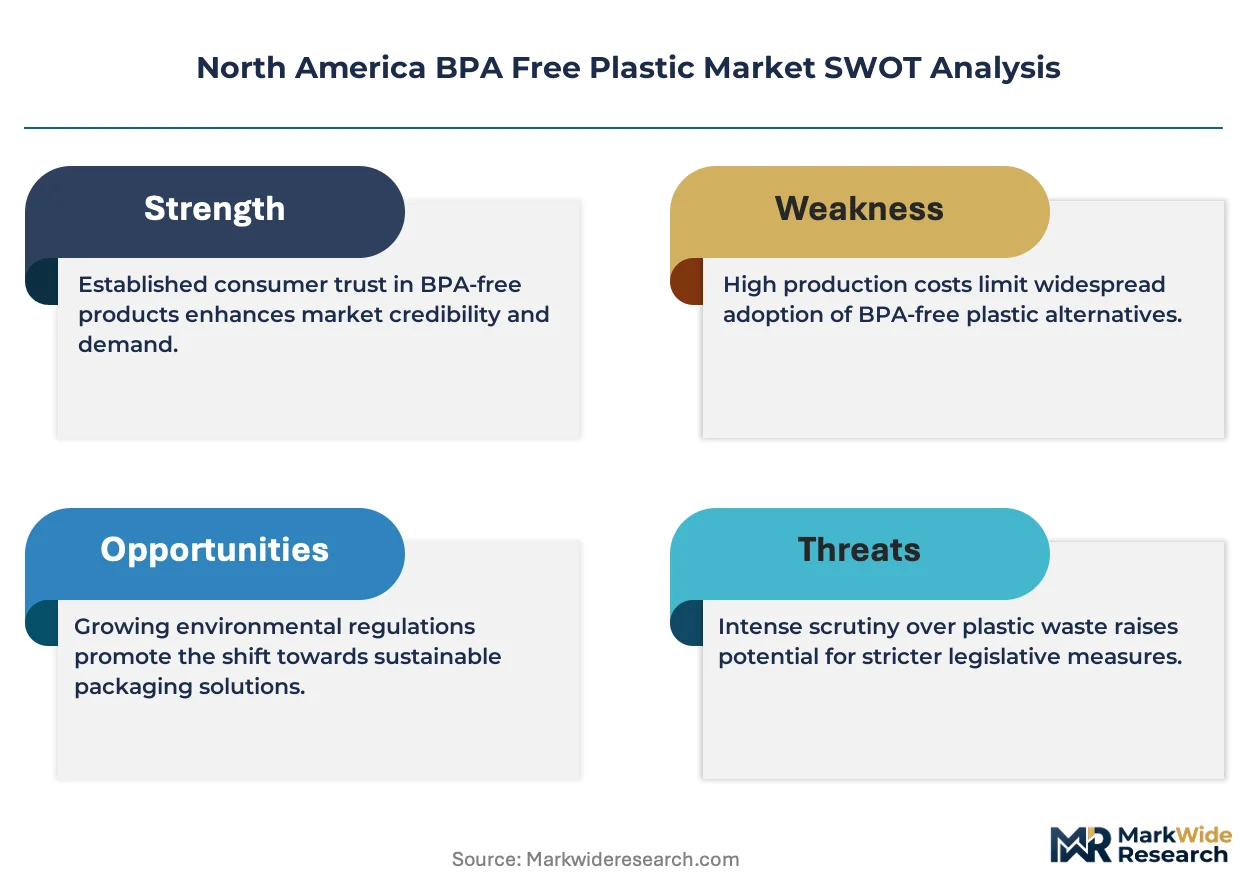
FDA food-contact notification protocols, EPA chemical assessment frameworks, and California's Proposition 65 disclosure mandates collectively determine which resin formulations achieve commercial viability across U.S. states and Canadian provinces. Health Canada and PMRA guidelines further condition cross-border product registration for packaging destined for infant nutrition and pharmaceutical segments. Stakeholders must monitor evolving state-level chemical restriction bills and polymer recycling-content mandates that will reshape raw-material qualification criteria and capital allocation priorities.
Market Dynamics
California Proposition 65 enforcement actions against food-contact plastics are compelling converters to requalify resin suppliers ahead of 2025 disclosure deadlines. This regulatory compression is accelerating capital redeployment toward copolyester and polypropylene capacity while marginalizing polycarbonate alternatives.
Growth Catalysts
- Proposition 65 Litigation Surge:Private enforcement actions against bisphenol-containing packaging are creating immediate substitution demand. Food brands are preemptively reformulating to avoid warning label requirements.
- Infant Nutrition Segment Specifications:Major formula manufacturers have instituted BPA-free mandates across all contact layers. This specification cascade is pulling through medical-device and pharmaceutical packaging standards.
- PETG Capacity Expansion:Eastman Chemical and SK Chemicals have added glycol-modified polyester lines serving heat-fill applications. This material availability is unlocking hot-fill juice and ready-to-drink coffee formats previously blocked from BPA-free conversion.
Market Restraints
- Propylene Feedstock Volatility:Polypropylene resin prices track propylene monomer costs from Gulf Coast crackers. Hurricane-season supply disruptions create 15-30 day procurement freezes that stall converter operations.
- Specialty Copolyester Supply Concentration:Heat-resistant Tritan and PETG formulations rely on limited Eastman and SK Chemicals capacity. Single-source dependency creates allocation risk during demand spikes.
- Polycarbonate Incumbency in Reusable Applications:Baby bottles and sports water bottles retain polycarbonate for clarity and dishwasher durability. BPA-free alternatives struggle to match optical properties at equivalent cost points.
Strategic Opportunities
- Mexico Manufacturing Corridor:Querétaro and Guanajuato packaging clusters lack qualified BPA-free resin suppliers. Early entrants can capture automotive and electronics export packaging demand as NAFTA rules-of-origin tighten.
- Sterilizable Medical Device Applications:Gamma and autoclave-stable copolyesters are penetrating surgical instrument trays and pharmaceutical vials. FDA 510(k) pathways for polymer substitutions create first-mover certification advantages.
- Post-Consumer Recycled Content Mandates:California and New York packaging EPR legislation is creating demand for BPA-free PCR streams. Mechanical recycling of polypropylene without bisphenol contamination unlocks closed-loop food packaging.
Industry Challenges
- Migration Testing Protocol Complexity:FDA food-contact notification submissions require 6-12 month analytical validation. Accelerated solvent extraction and simulant testing bottlenecks delay product launches.
- Extrusion Equipment Retrofit Requirements:Converting polycarbonate lines to PETG or polypropylene demands screw and die modifications. Capital allocation conflicts with short payback period expectations from brand customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America BPA Free Plastic Market |
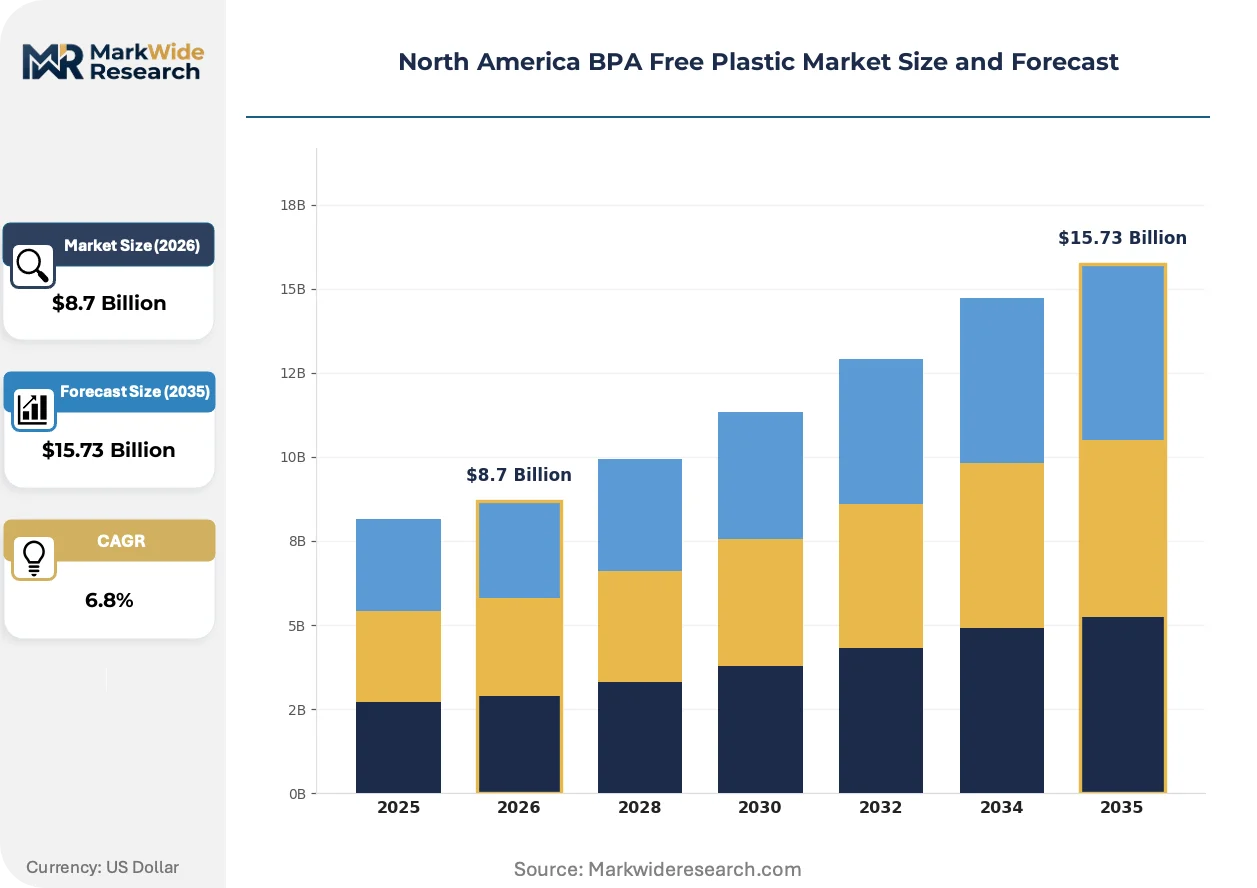
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Utensils, Packaging End User: Food & Beverage, Healthcare, Consumer Goods, Automotive Material: Polyethylene, Polypropylene, Polycarbonate, PVC Application: Food Storage, Medical Devices, Household Products, Industrial Uses |
| Companies Covered | Altium Packaging, Amcor plc, Plastipak Packaging, Inc., Eastman Chemical Company, Dow Inc., PPG Industries, Inc., BASF SE, LyondellBasell Industries N.V., SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America BPA Free Plastic Market Evolving Landscape
Material science advances are collapsing the performance gap between BPA-free alternatives and incumbent polymers. Three developments are restructuring competitive positioning across packaging and medical segments.
High-clarity tritan copolyesters are electrifying premium reusable bottle and infant care applications. Hydro Flask and Contigo have converted entire product lines to this material. The technology is compressing polycarbonate's remaining stronghold in dishwasher-durable consumer goods.
FDA has issued updated guidance on food-contact notification thresholds for bisphenol analogs including BPS and BPF. This regulatory expansion is forcing suppliers to validate entire additive packages rather than single-monomer exclusions. Infant formula and baby food packaging segments are responding with blanket bans on all bisphenol chemistries.
Brand technical buyers are consolidating supplier panels around resin producers with integrated analytical testing capabilities. This specification behavior is displacing distributor-centric procurement in favor of direct mill relationships. The shift is most visible in Great Lakes automotive supply chains and Ontario pharmaceutical packaging clusters.
North America BPA Free Plastic Market Segmentation
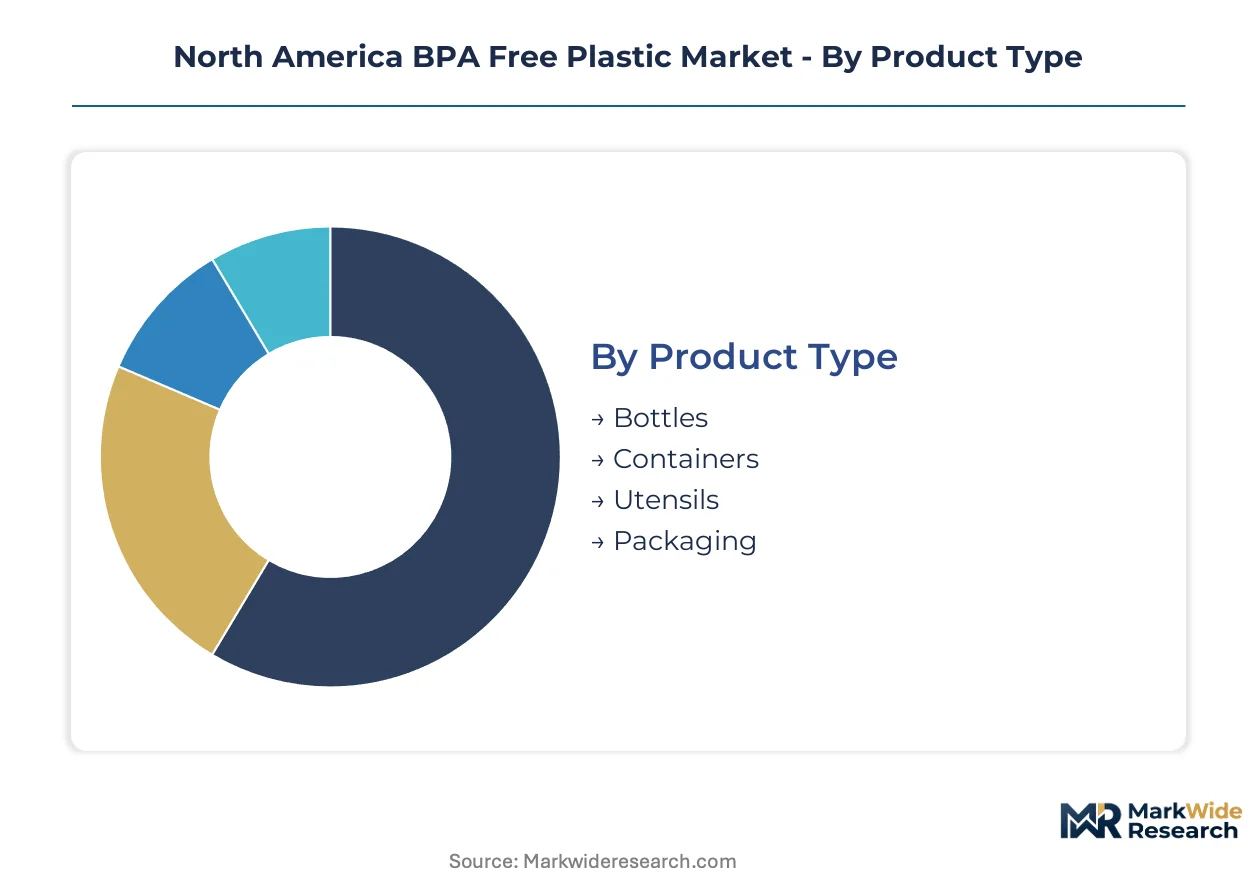
Segmentation in the North America BPA Free Plastic Market reveals how regulatory pressure and performance specifications fragment procurement decisions. Material substitution patterns differ sharply across end-use contexts, creating distinct margin pools and qualification barriers.
Product Type:
Thermoforming and blow-molding capabilities determine which formats converters can supply at scale.
- Bottles:Extrusion blow-molded PETG and polypropylene formulations dominate infant nutrition and beverage segments. FDA food-contact notification requirements for migration testing concentrate converter relationships with Eastman Chemical and SK Chemicals resin supply. Demand clusters in Ontario's packaging corridor near Toronto and the U.S. Great Lakes manufacturing belt.
- Containers:Injection-molded polypropylene tubs and clamshells serve ready-meal and fresh produce applications. California Proposition 65 disclosure mandates are accelerating polycarbonate displacement in favor of clarified random copolymer alternatives.
- Utensils:Thin-wall polypropylene cutlery and serving implements compete on unit economics against polylactic acid bioplastics.
- Packaging:Flexible polyethylene films and rigid thermoformed trays span diverse food-contact and medical sterilization applications.
Mature deployment sits with bottles. Newer deployment is concentrated in packaging formats integrating post-consumer recycled content streams.
End User:
Customer specification intensity varies dramatically across regulated and consumer-driven segments.
- Food & Beverage:Brand owners are consolidating supplier panels around resin producers with integrated analytical testing capabilities. Hot-fill juice and ready-to-drink coffee formats previously blocked from BPA-free conversion are now unlocking through expanded PETG capacity.
- Healthcare:Gamma and autoclave-stable copolyesters are penetrating surgical instrument trays and pharmaceutical vials. FDA 510(k) pathways for polymer substitutions create first-mover certification advantages for medical-device packaging converters.
- Consumer Goods:Premium reusable bottle brands have converted entire product lines to high-clarity tritan copolyesters.
- Automotive:Interior trim and electronics housing specifications in Mexico's Querétaro and Guanajuato clusters lack qualified BPA-free resin suppliers.
Volume concentration remains in food and beverage. Steepest expansion trajectory belongs to healthcare as sterilization-grade certification requirements proliferate.
Material:
Polymer selection hinges on heat resistance, optical clarity, and migration compliance thresholds.
- Polyethylene:Linear low-density grades dominate flexible food packaging and film applications. Mechanical recycling without bisphenol contamination unlocks closed-loop supply chains under California and New York packaging EPR legislation.
- Polypropylene:Random copolymer clarity improvements are displacing polycarbonate in food storage containers. Propylene feedstock volatility from Gulf Coast crackers creates procurement freeze risks during hurricane season disruptions.
- Polycarbonate:Residual demand concentrates in reusable sports bottles and baby bottles where dishwasher durability and optical properties resist substitution.
- PVC:Phthalate and residual BPA concerns are marginalizing this material in food-contact applications across FDA-regulated categories.
Supply security favors polyethylene. Performance specification intensity is climbing fastest in polypropylene as heat-fill applications expand.
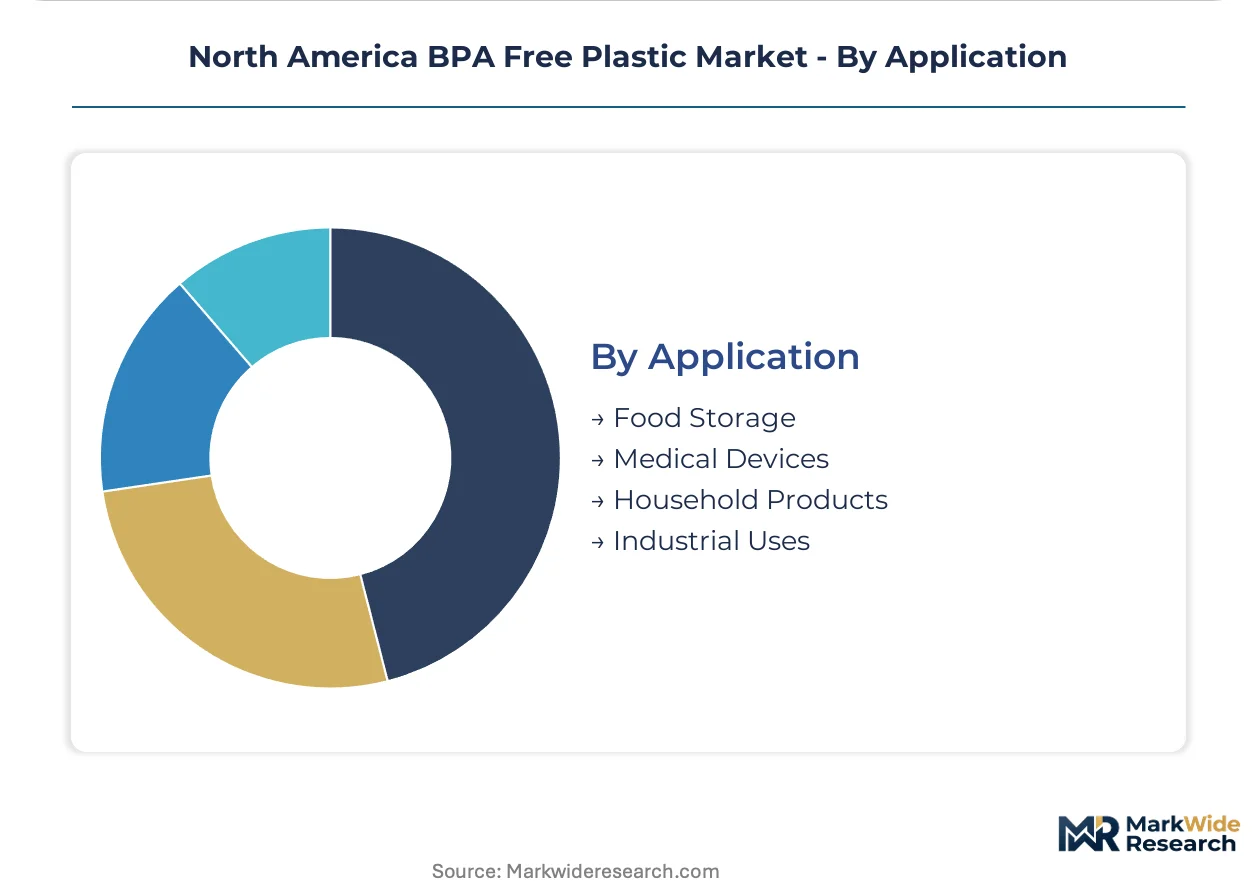
Application:
Use-case thermal and sterilization demands dictate resin qualification complexity.
- Food Storage:Refrigerated and frozen formats tolerate lower-cost polyethylene and polypropylene formulations. Migration testing protocol complexity through FDA food-contact notification submissions extends product launch timelines.
- Medical Devices:Gamma and autoclave sterilization requirements favor specialty copolyester formulations with limited Eastman and SK Chemicals capacity concentration.
- Household Products:Dishwasher durability specifications in premium reusable segments sustain polycarbonate incumbency despite regulatory pressure.
- Industrial Uses:Automotive and electronics export packaging from Mexico faces NAFTA rules-of-origin tightening that favors regional resin qualification.
Regulatory maturity is highest in food storage. Technical barrier expansion is most pronounced in medical devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most acutely in the U.S. Great Lakes manufacturing corridor and Ontario's packaging hub near Toronto, with procurement patterns diverging sharply across regulatory jurisdictions.
United States
Food and beverage packaging lines across the Great Lakes belt are accelerating procurement of non-bisphenol materials. FDA guidance on food-contact substances and California's Proposition 65 disclosure mandates are reshaping supplier qualification requirements. The Midwest automotive supply chains and Southeast food processing clusters are driving specification intensity.
Canada
Ontario's packaging corridor near Toronto anchors North American infant nutrition and pharmaceutical packaging demand. Health Canada and PMRA guidelines condition cross-border product registration for packaging destined for sensitive segments. Quebec's chemical processing infrastructure supports resin distribution networks serving Atlantic provinces.
Mexico
Querétaro and Guanajuato packaging clusters lack qualified BPA-free resin suppliers despite automotive and electronics export growth. NAFTA rules-of-origin tightening favors regional resin qualification for integrated supply chains. Early entrants capture demand as brand technical specifications migrate southward.
California
Proposition 65 enforcement actions are compelling converters to requalify resin suppliers ahead of disclosure deadlines. State-level chemical restriction bills exceed federal thresholds, creating a laboratory for stricter packaging mandates. Los Angeles and Central Valley food processing hubs drive premium copolyester specification.
New York
State-level chemical disclosure laws parallel California's regulatory intensity, with packaging EPR legislation creating demand for BPA-free post-consumer recycled streams. The Northeast pharmaceutical packaging corridor leverages FDA 510(k) pathways for polymer substitutions. Hudson Valley and Long Island manufacturing zones concentrate medical-device converter capacity.
North America BPA Free Plastic Market Competitive Landscape
Capacity expansion dominates the current landscape as resin producers add glycol-modified polyester lines to serve heat-fill applications. The market structures around three tiers: integrated chemical majors with captive resin supply, specialized packaging converters with direct mill relationships, and regional distributors facing margin compression. Strategic archetypes include polymer-scale players competing on feedstock security, specialty-copolyester specialists commanding premium positioning, and diversified packaging conglomerates leveraging continental manufacturing footprints. M&A activity and backward integration into resin production represent the dominant competitive vectors reshaping supplier relationships.
Among integrated chemical majors, Eastman Chemical Company and Dow Inc. anchor the supply base through distinct positioning archetypes. Eastman occupies the specialty-copolyester tier where heat-resistant formulations command specification premiums. Dow exemplifies scale-driven polyethylene supply serving flexible packaging converters. LyondellBasell Industries N.V. represents the polypropylene concentration that feeds bottle and container molding operations across the Great Lakes corridor. Amcor plc sits within the diversified packaging conglomerate tier, leveraging multi-source resin procurement to sustain consistent feedstock access across polymer categories.
| Leading Market Players |
|---|
| Altium Packaging |
| Amcor plc |
| Plastipak Packaging, Inc. |
| Eastman Chemical Company |
| Dow Inc. |
| PPG Industries, Inc. |
| BASF SE |
| LyondellBasell Industries N.V. |
| SABIC |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up packaging specialists have consolidated converter capacity across the Great Lakes corridor, tightening pricing discipline through captive resin sourcing agreements and volume-commitment contracts with Eastman Chemical and SK Chemicals. This ownership pattern concentrates procurement leverage among fewer buyers while forcing independent distributors into margin-compressing spot market purchases.
Pricing Analysis
Volume-heavy polyethylene and polypropylene formulations trade on thin margins through Gulf Coast contract structures, while specialty copolyester grades command premiums through limited Eastman and SK Chemicals capacity. Price differentiation hinges on FDA food-contact notification status and heat-fill certification tiers, with sterilization-grade medical formulations carrying the widest spreads. Cost compression in standard food packaging intensifies as brand owners consolidate supplier panels and demand integrated analytical testing. Small-to-mid converters exhibit the highest price sensitivity, while infant nutrition and pharmaceutical segments absorb premium positioning for migration-compliant materials.
Supply Chain Analysis
Workforce availability constraints in Ontario's packaging corridor and Michigan's manufacturing belt are pushing resin qualification timelines toward Mexico's Querétaro and Guanajuato clusters, where technical labor pools remain underdeveloped for BPA-free processing. Supply concentrates in the United States, Canada, and Mexico under NAFTA rules-of-origin tightening. Raw material flows draw from Gulf Coast propylene crackers, Eastman's Tennessee copolyester facilities, and Alberta polyethylene feedstock. Single-source dependency on Eastman and SK Chemicals for heat-resistant grades creates allocation vulnerability during demand spikes. Distribution runs through direct mill relationships with brand technical buyers, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as converters pursue backward control over resin supply to secure allocation priority during Eastman and SK Chemicals capacity constraints. Captive compounding capabilities or exclusive offtake agreements represent the decisive upstream lever separating sustainable margin pools from commodity compression.
For Market Incumbents: Hedge polycarbonate exposure through accelerated PETG and clarified polypropylene line conversions ahead of California Proposition 65 disclosure deadlines. Secure multi-year resin offtake agreements with Eastman Chemical or SK Chemicals to lock in specialty copolyester allocation. Defend against margin erosion by integrating in-house migration testing laboratories that shorten FDA food-contact notification timelines. For New Entrants and Emerging Players: Enter via Mexico's Querétaro and Guanajuato automotive packaging corridors, where qualified BPA-free resin suppliers remain scarce despite NAFTA rules-of-origin tightening. Target sterilizable medical device applications where FDA 510(k) certification barriers create first-mover advantages for gamma-stable copolyester formulations. Pursue direct technical sales relationships with brand R&D teams rather than distributor channel builds. For Investors and Strategic Acquirers: FDA issuance of updated bisphenol analog guidance covering BPS and BPF is the leading indicator that blanket bisphenol chemistry bans will cascade through infant formula and pharmaceutical packaging segments, expanding addressable premium resin demand. Position for five-to-ten-year viability by acquiring converters with established Health Canada and PMRA cross-border registration capabilities. Monitor California and New York packaging EPR legislation progression as the signal for post-consumer recycled content mandate timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply secures allocation priority during Eastman and SK Chemicals capacity constraints. |
| FDA 510(k) Certification Investment | First-mover sterilization-grade status unlocks surgical instrument tray and pharmaceutical vial contracts. |
| Mexico Manufacturing Footprint Expansion | Querétaro and Guanajuato positioning captures automotive export packaging under NAFTA rules-of-origin tightening. |
| In-House Migration Testing Laboratory Build | Integrated analytical capabilities compress FDA food-contact notification timelines from 12 months toward 6 months. |
| Post-Consumer Recycled Content Stream Development | California and New York EPR mandates create closed-loop qualification requirements for BPA-free mechanical recycling. |
Research Methodology
Multi-period observation of resin capacity additions, FDA food-contact notification submission rates, and California Proposition 65 enforcement actions anchored the trend analysis, supplemented by interviews with polymer procurement directors at packaging converters, regulatory affairs leads at resin producers, brand technical buyers in infant nutrition, and plant managers across the Great Lakes manufacturing belt. Secondary validation drew from FDA food-contact substance inventories, Health Canada PMRA guidance documents, SEC 10-K resin segment disclosures, and American Chemistry Council trade flow data. Bottom-up converter capacity estimates triangulated against top-down resin production figures.
Input-output matrices modeled demand drivers across material grade tiers, end-use segments spanning food-contact to medical sterilization, packaging format types, and regional production hub clusters. CAGRs were derived from segment-level elasticity estimates and substitution rate assumptions. Forecast inputs incorporated propylene feedstock cost volatility patterns, hurricane-season supply disruption frequencies, and state-level chemical restriction bill progression timelines.
Revisions become necessary when FDA expands bisphenol analog guidance scope, when Eastman or SK Chemicals announces material capacity additions or constraints, or when California and New York EPR implementation timelines accelerate. Material deviation in these named triggers warrants pause and re-evaluation of resin allocation and substitution assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Global Post-Consumer Recycled Plastics Market
Recycled Plastics
Aluminum Recycling Market