
 North America Plastic Waste Management Market | 2026-2036
North America Plastic Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Waste Management Market Insights
Extended Producer Responsibility legislation is consolidating operational requirements across state and provincial jurisdictions. Waste Management Inc leverages its landfill-gas-to-energy infrastructure to anchor long-term service contracts in the Upper Midwest. Republic Services Inc competes through automated materials recovery facilities that reduce sortation labor costs. Veolia Environnement SA positions its chemical recycling pilot operations to capture post-industrial film streams from automotive suppliers.
Plastic waste management encompasses the systematic collection, sorting, processing, and valorization of discarded polymer materials through mechanical reprocessing, pyrolysis, or controlled thermal treatment to recover feedstock energy or reusable resin. The mechanical recycling segment dominates current tonnage throughput but faces contamination-rate ceilings that limit output purity for food-contact applications. Chemical recycling technologies attract capital allocations from petrochemical end users seeking circular feedstock alternatives to virgin naphtha. The municipal application channel generates the highest collection volume yet operates on compressed budget cycles that constrain technology upgrades.
The EPA oversees hazardous waste classifications affecting plastic co-processing in cement kilns, while Environment and Climate Change Canada administers the federal plastics registry mandating producer reporting obligations. State-level bottle deposit expansions in New York and Oregon reshape collection economics by concentrating high-value polyethylene terephthalate streams. Stakeholders must monitor regulatory divergence between California's SB 54 implementation schedule and Canada's proposed recycled content mandates to align capital deployment with enforceable compliance timelines.
Market Dynamics
Extended Producer Responsibility mandates across California, Oregon, and Canada's federal plastics registry are compressing compliance timelines and forcing capital reallocation toward chemical recycling infrastructure and automated sortation systems.
Growth Catalysts
- California SB 54 implementation:The state's plastic pollution reduction law mandates 30% recycled content thresholds by 2028, pulling investment into food-grade mechanical recycling capacity and pyrolysis pilots.
- Automotive supplier circularity targets:Detroit-area original equipment manufacturers are contracting dedicated post-industrial film recovery streams, creating anchor demand for chemical recycling operations in Michigan and Ontario.
- Great Lakes industrial corridor concentration:Proximity to resin production, automotive stamping, and packaging manufacturing generates dense, high-purity waste streams that reduce collection logistics costs.
Market Restraints
- Natural gas price volatility:Pyrolysis and gasification operations depend on competitive energy economics; feedstock energy arbitrage collapses when Henry Hub prices spike above thermal substitution thresholds.
- Contamination rate ceilings:Mechanical recycling output purity plateaus at 95-97% for polyethylene terephthalate, blocking food-contact approval pathways and compressing resin premiums.
- Landfill tipping fee fragmentation:Subnational jurisdictions maintain divergent disposal costs, undermining the economic case for recycling in states with suppressed landfill rates.
Strategic Opportunities
- Mexico border-state integration:Baja California and Chihuahua manufacturing zones lack formal recovery infrastructure, creating first-mover potential for cross-border collection networks serving California compliance markets.
- Deposit-return expansion:New York and Oregon bottle bill modernization concentrates high-value polyethylene terephthalate streams, enabling bottle-to-bottle mechanical recycling at scale.
- Chemical recycling feedstock arbitrage:Pyrolysis oil qualifies as recycled content under California's forthcoming rules, allowing petrochemical buyers to substitute circular naphtha for virgin feedstock.
Industry Challenges
- Optical sortation technician scarcity:Near-infrared sensor calibration and AI-driven contamination detection require specialized maintenance skills that outpace vocational training pipeline output in the Upper Midwest.
- Food-contact certification timelines:FDA letters of no objection for recycled polyolefins stretch 18-24 months, delaying revenue recognition for mechanical recycling expansions targeting beverage packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Waste Management Market |
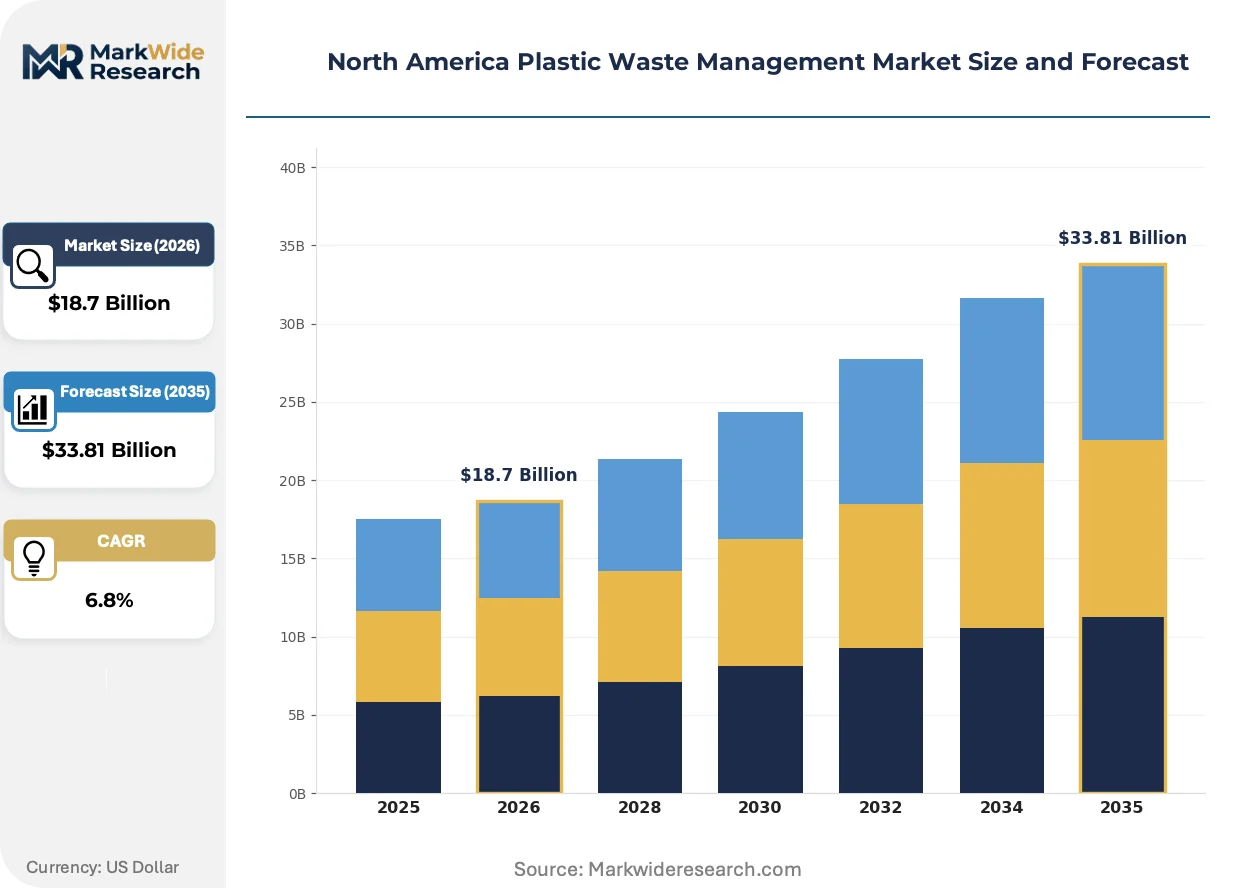
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Treatment, Disposal Technology: Mechanical, Chemical, Thermal, Biodegradable Application: Residential, Industrial, Commercial, Municipal End User: Manufacturers, Government, NGOs, Environmental Groups |
| Companies Covered | Waste Management Inc, Republic Services Inc, Veolia Environnement SA, Waste Connections, Clean Harbors Inc, GFL Environmental, SUEZ, Radius Recycling Inc, Casella Waste Systems Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Waste Management Market Trends and Innovations
Technology convergence between AI-driven sortation and pyrolysis refining is compressing the cost gap between mechanical and chemical recycling pathways. Regulatory fragmentation across subnational jurisdictions is forcing modular facility designs. Demand signals from automotive and food packaging verticals are pulling investment toward resin-to-resin circularity rather than energy recovery.
Pyrolysis-based chemical recycling is absorbing stranded mixed-polymer streams that mechanical processes cannot valorize. Petrochemical end-users in Texas and Louisiana are contracting offtake agreements for circular naphtha substitutes at scale. This technology is absorbing capital allocations previously directed toward virgin cracker expansions, reshaping Gulf Coast petrochemical investment patterns.
Canada's federal plastics registry mandates producer reporting obligations that exceed California's SB 54 disclosure requirements. Environment and Climate Change Canada enforcement timelines accelerate compliance investment for US-based multinationals with Canadian sales exposure. Consumer goods companies with North American distribution footprints are consolidating reporting systems to satisfy both jurisdictions simultaneously.
Automotive procurement teams are unbundling waste management from general facility services and contracting dedicated circularity providers. Tier-one suppliers in Ohio and Michigan are selecting processors based on mass-balance certification rather than lowest-cost disposal. This pattern concentrates volume with vertically integrated operators capable of documenting chain-of-custody from plant floor to resin reintegration.
North America Plastic Waste Management Market Segmentation
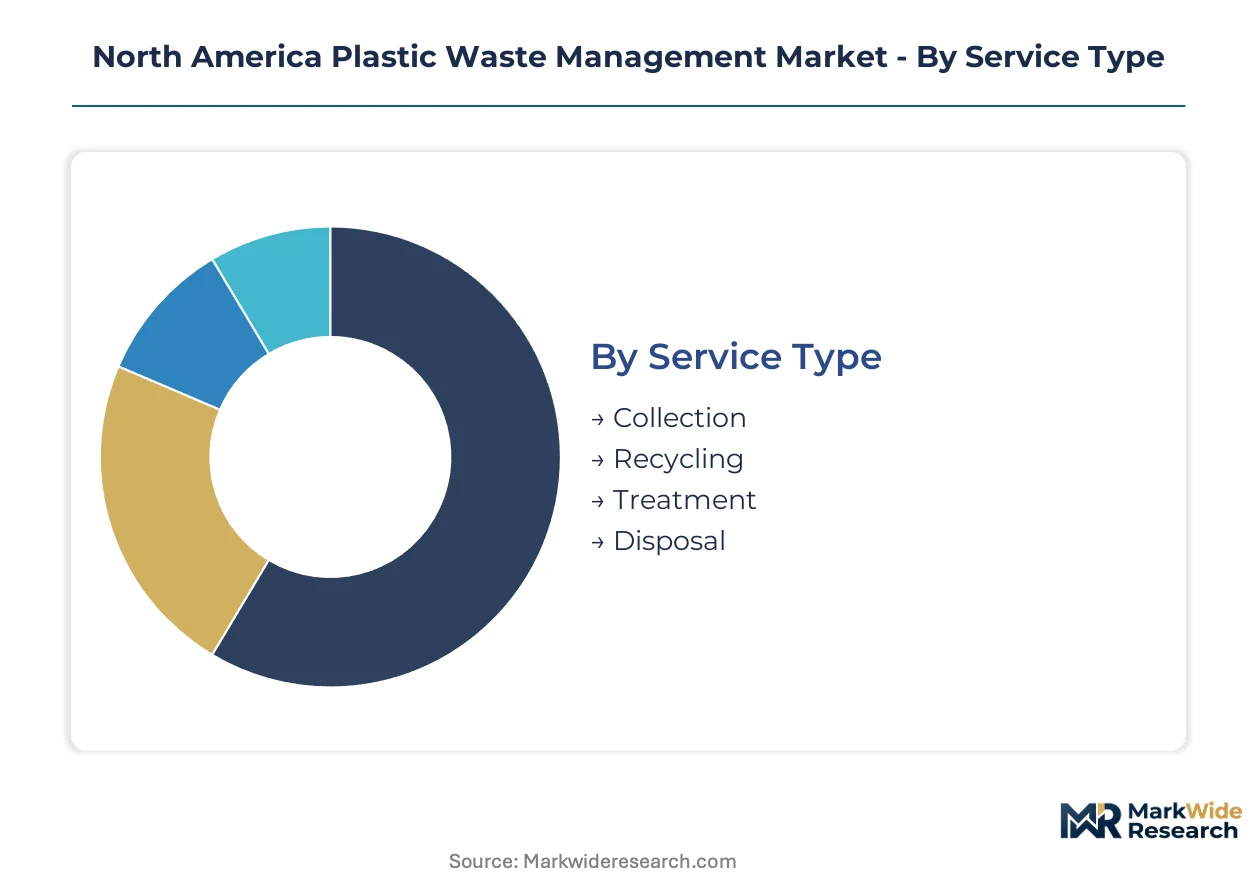
Plastic waste management operators configure service portfolios around four distinct axes: service delivery mode, processing technology, waste source type, and contracting entity. Each axis carries divergent margin profiles and capital intensity requirements that reshape competitive positioning across the Great Lakes corridor and California compliance markets.
Service Type:
Collection services command volume dominance but compress margins through route density economics, while recycling and treatment operations capture premium pricing through purity certification and regulatory credit generation.
- Collection:Curbside and commercial pickup operations aggregate mixed polymer streams for downstream sortation. Dense urban corridors in Toronto and Chicago generate route efficiencies that offset labor cost inflation, though contamination rates at 15-25% erode feedstock value for mechanical recyclers.
- Recycling:Mechanical reprocessing and emerging chemical conversion facilities convert collected materials into resin feedstock or pyrolysis oil. California SB 54 compliance pulls investment toward food-grade mechanical capacity and pyrolysis pilots serving automotive suppliers in Michigan and Ohio.
- Treatment:Pre-processing operations including shredding, washing, and optical sortation prepare waste streams for final valorization. EPA hazardous waste classifications for co-processing in cement kilns constrain operational flexibility in jurisdictions with stringent air quality enforcement.
- Disposal:Landfill operations and waste-to-energy incineration serve as residual pathways for non-recyclable fractions. Tipping fee fragmentation across subnational jurisdictions undermines recycling economics in states with suppressed landfill rates.
Mature deployment sits with Collection. Newer deployment is concentrated in Recycling.
Technology:
Capital allocation splits between proven mechanical systems with constrained output purity and emerging chemical pathways requiring longer payback periods but qualifying for circular content credits.
- Mechanical:Grinding, washing, and extrusion systems reprocess single-polymer streams into pelletized resin. Contamination rate ceilings at 95-97% purity for polyethylene terephthalate block food-contact approvals and compress resin premiums in beverage packaging applications.
- Chemical:Pyrolysis and gasification operations depolymerize mixed plastics into circular naphtha or syngas. Petrochemical end-users in Texas and Louisiana are contracting offtake agreements for pyrolysis oil substitutes at scale, redirecting capital from virgin cracker expansions.
- Thermal:Waste-to-energy incineration and cement kiln co-processing recover energy value from residual streams. Natural gas price volatility erodes feedstock energy arbitrage when Henry Hub spikes above thermal substitution thresholds.
- Biodegradable:Industrial composting and anaerobic digestion handle certified bio-based polymers and food-contaminated films. Limited infrastructure penetration and ASTM certification gaps constrain market development outside California and the Pacific Northwest.
Mechanical systems anchor current tonnage throughput. Chemical pathways are expanding most quickly.
Application:
Contracting structures diverge between municipal procurement cycles with compressed technology budgets and industrial accounts demanding mass-balance certification.
- Residential:Single-family and multi-unit curbside programs generate the highest collection volumes but operate on municipal budget cycles that constrain sortation technology upgrades. Deposit-return expansion in New York and Oregon concentrates high-value polyethylene terephthalate streams for bottle-to-bottle recycling.
- Industrial:Post-industrial film and scrap from automotive stamping and packaging manufacturing yield dense, high-purity waste streams. Tier-one suppliers in Ohio and Michigan select processors based on chain-of-custody documentation rather than lowest-cost disposal.
- Commercial:Retail, hospitality, and office waste management contracts bundle collection with sustainability reporting services. Canada's federal plastics registry mandates producer reporting obligations that exceed California SB 54 disclosure requirements, forcing reporting system consolidation.
- Municipal:City and county contracts for public buildings, parks, and event venues operate on compressed procurement timelines. Extended Producer Responsibility frameworks are transferring operational responsibility to producers, reducing direct municipal capital burden.
Residential channels dominate collection volume. Industrial applications are gaining share fastest through dedicated circularity contracting.
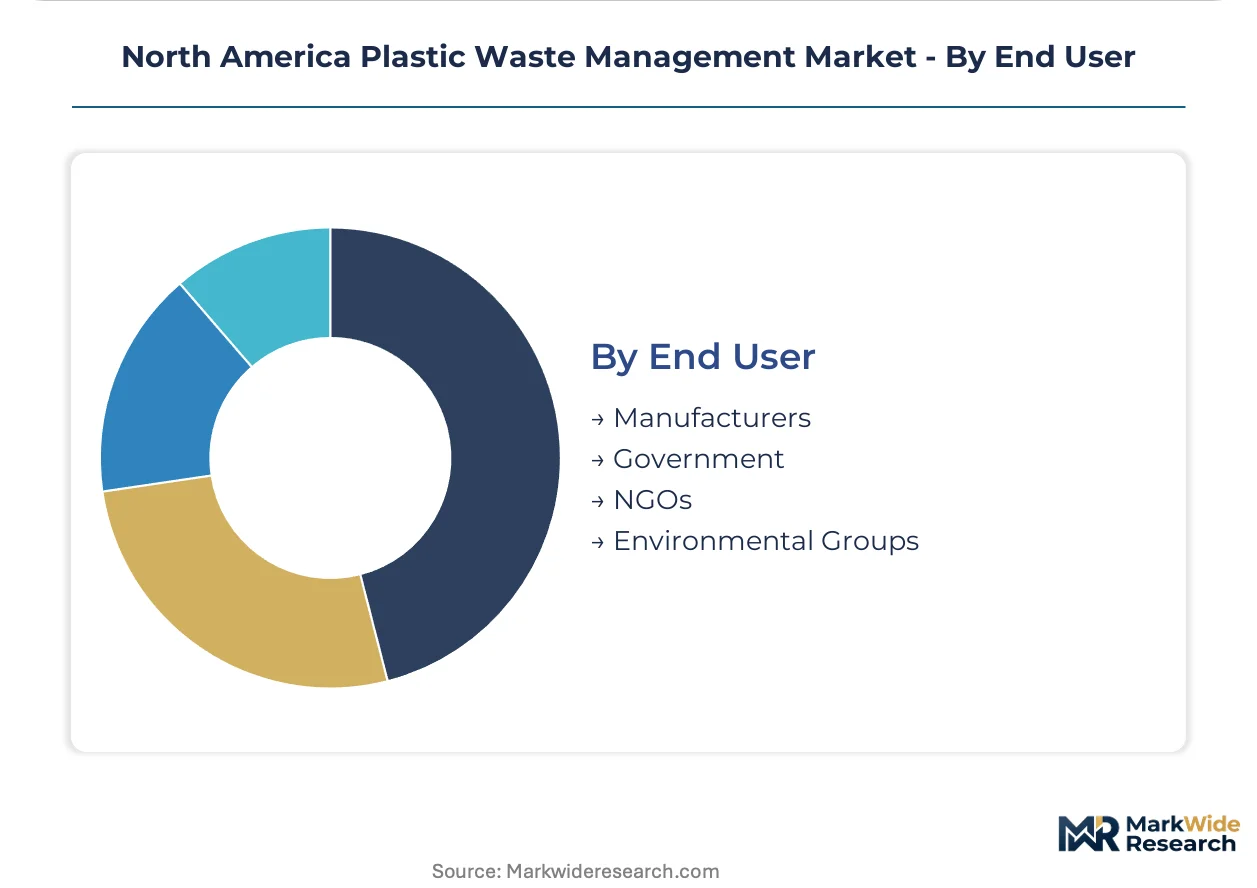
End User:
Procurement authority concentrates with manufacturers seeking circular feedstock security and government entities enforcing compliance timelines.
- Manufacturers:Automotive OEMs and consumer goods companies contract dedicated recovery streams to satisfy circularity targets. Detroit-area original equipment manufacturers are unbundling waste management from general facility services and selecting providers based on resin-to-resin mass-balance certification.
- Government:Federal, state, and municipal agencies regulate classification standards and procurement policy. EPA oversees hazardous waste classifications affecting plastic co-processing, while Environment and Climate Change Canada administers enforcement timelines accelerating compliance investment.
- NGOs:Environmental advocacy organizations influence policy design and certification standards. Extended Producer Responsibility legislation consolidation across California, Oregon, and Canada reflects sustained advocacy pressure on compliance thresholds.
- Environmental Groups:Community-based organizations monitor facility siting and emissions compliance. Local opposition to pyrolysis facility permitting in the Upper Midwest creates project development delays despite offtake demand from petrochemical buyers.
Manufacturer procurement is concentrating volume with vertically integrated operators. Government enforcement timelines are forcing capital reallocation across all service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor functions as a de facto special economic zone for circular feedstock flows, with resin production, automotive stamping, and packaging manufacturing generating dense waste streams that reduce collection logistics costs across Michigan, Ohio, and Ontario.
United States
California SB 54 mandates 30% recycled content thresholds by 2028, pulling investment into food-grade mechanical recycling capacity and pyrolysis pilots. The EPA oversees hazardous waste classifications affecting plastic co-processing in cement kilns, constraining operational flexibility in jurisdictions with stringent air quality enforcement. Detroit-area original equipment manufacturers contract dedicated post-industrial film recovery streams, creating anchor demand for chemical recycling operations in Michigan and Ohio.
Canada
Environment and Climate Change Canada administers the federal plastics registry mandating producer reporting obligations that exceed California SB 54 disclosure requirements. Enforcement timelines accelerate compliance investment for US-based multinationals with Canadian sales exposure. The Toronto-Windsor corridor concentrates collection infrastructure serving automotive suppliers and consumer goods distribution networks.
Mexico
Baja California and Chihuahua manufacturing zones lack formal recovery infrastructure, creating first-mover potential for cross-border collection networks serving California compliance markets. The country's national environmental regulator oversees industrial waste classifications, though enforcement capacity varies by state. Maquiladora operations generate post-industrial film streams that currently flow to informal recovery channels or landfill disposal.
North America Plastic Waste Management Market Competitive Landscape
United States-based integrated waste operators anchor one tier; Canadian and European specialists hold positions in chemical recycling and hazardous materials processing. The market exhibits consolidated structure at the collection and landfill level, with fragmentation emerging in recycling technology deployment. Three archetypes dominate: vertically integrated waste-to-energy operators, automated materials recovery facility specialists, and chemical recycling technology licensors. Competitive moves concentrate on landfill-gas-to-energy infrastructure anchoring and automated sortation system deployment.
Among US-based integrated operators, Waste Management Inc and Republic Services Inc exemplify the scale-driven archetype, while Veolia Environnement SA represents European-headquartered technology specialists positioning chemical recycling pilots to capture post-industrial film streams. These three entities occupy positions across the service spectrum from collection through advanced recycling, reflecting the market's bifurcation between volume-based collection economics and premium recovery technology.
| Leading Market Players |
|---|
| Waste Management Inc |
| Republic Services Inc |
| Veolia Environnement SA |
| Waste Connections |
| Clean Harbors Inc |
| GFL Environmental |
| SUEZ |
| Radius Recycling Inc |
| Casella Waste Systems Inc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between food-contact mechanical resin and mixed-polymer pyrolysis oil manifests in both contract structures and feedstock sourcing patterns across California compliance markets and Great Lakes automotive corridors. Premium mechanical recyclers command long-term offtake agreements tied to FDA letters of no objection, while commodity chemical recyclers absorb spot-priced mixed films from informal collection networks.
Pricing Analysis
Short lead-time premiums for food-grade polyethylene terephthalate pellets run 15-25% above spot resin in California SB 54 compliance markets. Contract-based long-term offtake agreements dominate, with price differentiation resting on FDA certification tier and mass-balance audit trail completeness. Cost compression in mixed-polymer pyrolysis feedstock is intensifying because petrochemical buyers arbitrage circular naphtha against virgin cracker economics. Municipal procurement teams show highest price sensitivity; automotive OEMs demonstrate lowest sensitivity due to circularity target compliance requirements.
Supply Chain Analysis
Regional distribution centers in Toronto, Chicago, and Detroit anchor hub-and-spoke collection patterns serving automotive stamping and packaging manufacturing clusters. Geographic supply concentration centers on the United States, Canada, and Mexico border states. Raw material dependencies include post-industrial film scrap, curbside mixed bales, and automotive tier-one supplier offcuts. Single-source vulnerability sits with pyrolysis oil offtake agreements concentrated among Gulf Coast petrochemical buyers. Distribution runs through vertically integrated operators capable of chain-of-custody documentation from plant floor to resin reintegration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American plastic waste management operates as a supply-constrained market where optical sortation technician scarcity and pyrolysis capacity bottlenecks prop pricing premiums for certified circular feedstock.
For Market Incumbents: Cement landfill-gas-to-energy infrastructure anchoring in the Upper Midwest to defend against chemical recycling entrants targeting automotive film streams. Prioritize backward integration into automated materials recovery facilities to reduce sortation labor exposure and capture California SB 54 compliance premiums.
For New Entrants and Emerging Players: AI-driven contamination detection technology offers first-mover positioning in Mexico border-state collection networks serving California compliance markets. Target Baja California and Chihuahua maquiladora zones with cross-border logistics partnerships and mass-balance certification capabilities.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated operators given Environment and Climate Change Canada enforcement timeline acceleration forcing compliance investment across US multinationals. Monitor FDA letter of no objection approval velocity as inflection indicator for food-grade mechanical recycling revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Capacity Buildout | Captures mixed-polymer streams mechanical processes cannot valorize for petrochemical offtake. |
| Automated Sortation Deployment | Reduces contamination rates below 5% threshold required for food-contact mechanical recycling. |
| Cross-Border Collection Network | Links Mexico manufacturing zones to California SB 54 compliance markets via certified chain-of-custody. |
| Mass-Balance Certification Investment | Enables automotive OEM procurement teams to satisfy circularity targets with documented resin-to-resin flows. |
| Landfill-Gas-to-Energy Expansion | Anchors long-term municipal service contracts through renewable energy credit generation in EPA-regulated jurisdictions. |
Research Methodology
Document review covered EPA hazardous waste classifications, Environment and Climate Change Canada federal plastics registry filings, California SB 54 implementation schedules, and SEC 10-K disclosures from integrated waste operators, complemented by interviews with materials recovery facility plant managers, automotive tier-one supplier procurement leads, petrochemical offtake contract managers, and municipal sustainability officers. Secondary validation drew from customs trade data, American Chemistry Council reports, and state-level bottle deposit program statistics. Bottom-up tonnage estimates triangulated against top-down market value projections.
Segmented outputs across service type, processing technology, waste source category, and contracting entity dimensions calibrated price and volume trajectories across the projection horizon. CAGRs derived from regression analysis against regulatory compliance timeline enforcement and petrochemical feedstock substitution elasticity. Forecast inputs included natural gas price volatility coefficients and FDA certification approval queue lengths.
Several conditions sit outside the modeled scope, including informal sector recovery rates in Mexico and potential revisions to California recycled content thresholds. Forecasts reflect stated assumptions around EPR legislation implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
India Plastic Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market