
 Plastic Drums Market | 2026-2036
Plastic Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Drums Market Intelligence
India's plastics manufacturing corridor is reshaping regional supply dynamics for industrial packaging. Greif, Inc. leverages its closed-loop reconditioning network to sustain material recovery rates across North American chemical corridors. Mauser Packaging Solutions anchors European pharmaceutical drum supply through ISO-certified blow-molding facilities in Germany and the Netherlands. Time Technoplast Ltd. dominates Asian export channels with specialized barrier-coated designs for agrochemical containment.
Plastic drums are cylindrical industrial containers typically manufactured through extrusion blow-molding or injection blow-molding processes using high-density polyethylene resins rated between 0.941 and 0.965 g/cm³ density, designed primarily for the safe transport and storage of liquids, powders, and semi-solids across regulated supply chains. Tight head drums command the largest volume share in chemical storage applications where vapor retention and UN-certified stacking strength prove critical. Recycled plastics represent the fastest-expanding material category as FDA and EFSA guidance on post-consumer content in food-contact applications gradually clarifies compliance pathways for drum converters.
EPA hazardous waste container standards and UN Model Regulations on dangerous goods packaging shape minimum wall-thickness and closure-testing protocols that drum manufacturers must certify before market entry. OSHA workplace chemical exposure limits indirectly drive drum specification through secondary containment and spill-prevention mandates in manufacturing facilities. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and individual US states to anticipate retrofit costs for circular collection infrastructure.
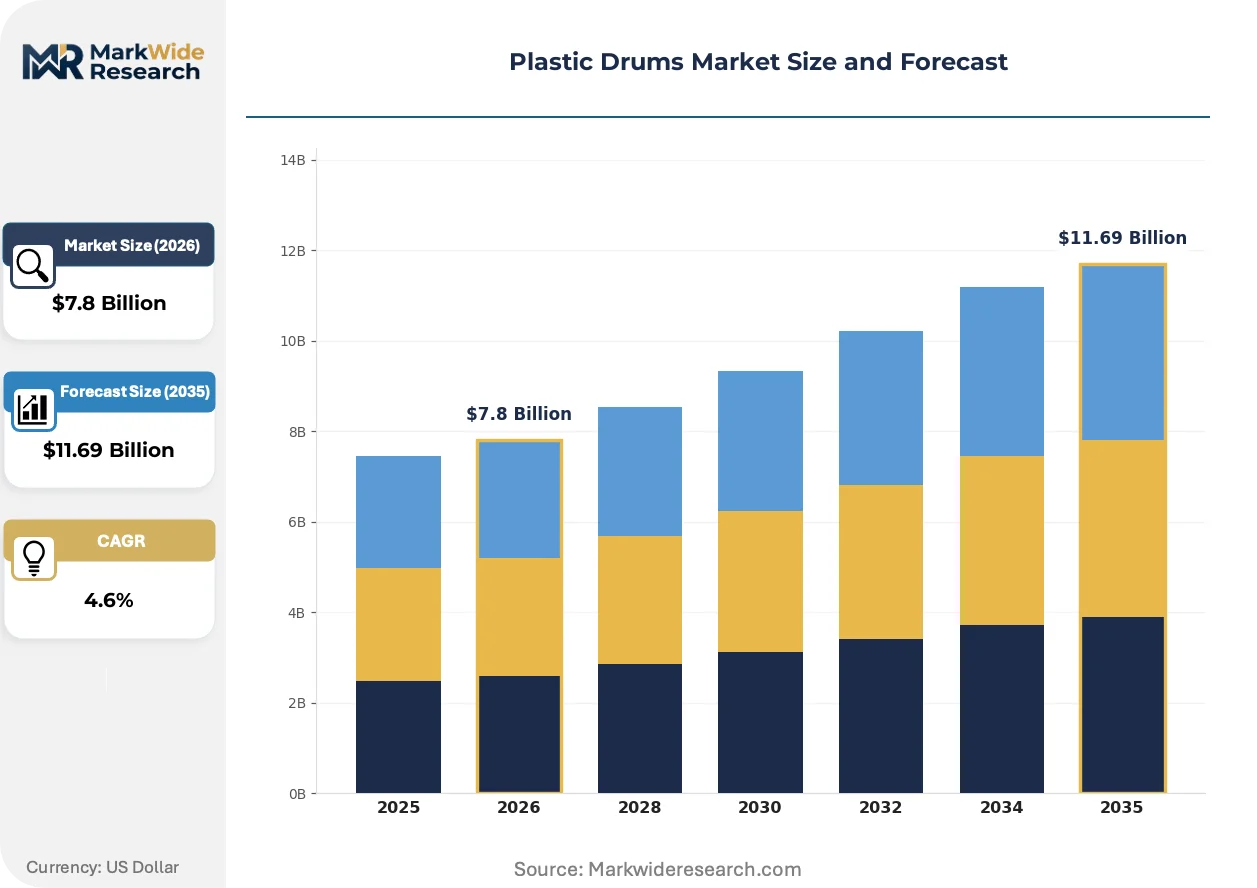
Market Dynamics
REACH compliance deadlines in Europe are forcing drum converters to re-engineer resin formulations and accelerate recycled content integration, compressing product development cycles while reshaping supplier qualification protocols across chemical supply chains.
Growth Catalysts
- Pharmaceutical cold-chain expansion:India's pharmaceutical export corridors are driving specialized barrier-coated drum demand for temperature-sensitive active pharmaceutical ingredients requiring UN-certified stacking integrity.
- REACH recycled content mandates:European chemical handlers must document post-consumer resin percentages in packaging procurement specifications, creating compliance-driven replacement cycles.
- Hazardous waste container standards:EPA wall-thickness and closure-testing protocols for secondary containment are mandating drum upgrades at US petrochemical and agrochemical facilities.
Market Restraints
- HDPE resin price volatility:Feedstock fluctuations tied to naphtha cracking economics create margin compression for extrusion blow-molders serving price-locked industrial contracts.
- Single-source geography risk:High-density polyethylene pellet supply concentrates around Gulf Coast petrochemical complexes, exposing drum manufacturers to hurricane-disruption vulnerability.
- Steel drum substitution in heavy chemicals:Sulfuric acid and hydrofluoric acid handlers specify carbon steel or stainless steel for pH extremes beyond polyethylene chemical resistance thresholds.
Strategic Opportunities
- Brazilian agrochemical formulators:ANVISA-aligned packaging requirements for crop protection exports create certified drum demand from multinational agrichemical distributors establishing local blending operations.
- RFID-embedded track-and-trace convergence:Integration of blow-molded drums with IoT-enabled logistics platforms allows chemical shippers to monetize real-time location and tamper-evidence data.
- EU Green Deal circularity incentives:Extended producer responsibility frameworks reward closed-loop reconditioning networks with reduced waste-handling fees and preferential public procurement status.
Industry Challenges
- Blow-molding technician scarcity:Specialized extrusion die maintenance and parison programming skills are retiring faster than vocational programs replenish qualified operators.
- UN certification timeline compression:Stacking load and drop-test validation for new drum geometries requires 12-18 month approval windows that misalign with customer product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Drums Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Head Drums, Tight Head Drums, Double Wall Drums, Lined Drums Material: High-Density Polyethylene, Low-Density Polyethylene, Polypropylene, Recycled Plastics Application: Chemical Storage, Food & Beverage Storage, Pharmaceutical Packaging, Agricultural Products Containment, Waste Management End User: Chemical Manufacturers, Food Processors, Pharmacies, Farming Operations, Environmental Services |
| Companies Covered | CL Smith, Orlando Drum & Container Corporation, Greif, Inc., U.S. Coexcell Inc., AST Plastic Containers, Mauser Packaging Solutions, Time Technoplast Ltd., Great Western Containers Inc., Schutz Container Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Drums Market Strategic Shifts & Innovations
Material science advances and digital integration are redefining drum performance specifications, with regulatory pressure and supply chain visibility demands converging to accelerate specification upgrades across chemical handling networks.
Barrier-coated multilayer polyethylene is hybridizing conventional single-resin drum construction by embedding ethylene vinyl alcohol or polyamide interlayers that block oxygen and solvent permeation. Specialty chemical and fragrance compounders in Germany and Switzerland are specifying these designs for odor-sensitive and oxidation-prone contents. The technology is hybridizing procurement criteria by merging food-contact compliance pathways with industrial chemical resistance standards.
REACH SCIP database requirements for Substances of Concern in articles are compelling drum manufacturers to document full material composition down to 0.1% weight thresholds. European chemical distributors now reject suppliers unable to provide machine-readable disclosure files. Pharmaceutical and cosmetics end-uses face the steepest compliance burden, with many converters investing in dedicated regulatory affairs functions to manage SVHC candidate list updates.
Leasing and pooling models for intermediate bulk containers are displacing traditional drum purchase patterns among multinational chemical manufacturers seeking to outsource packaging asset management. Third-party logistics providers in the Netherlands and Belgium are consolidating drum fleets under circular service contracts that bundle cleaning, inspection, and redeployment. Food-grade and pharmaceutical applications show strongest adoption, where traceability and condition verification justify per-use pricing premiums over capital ownership.
Plastic Drums Market Segmentation
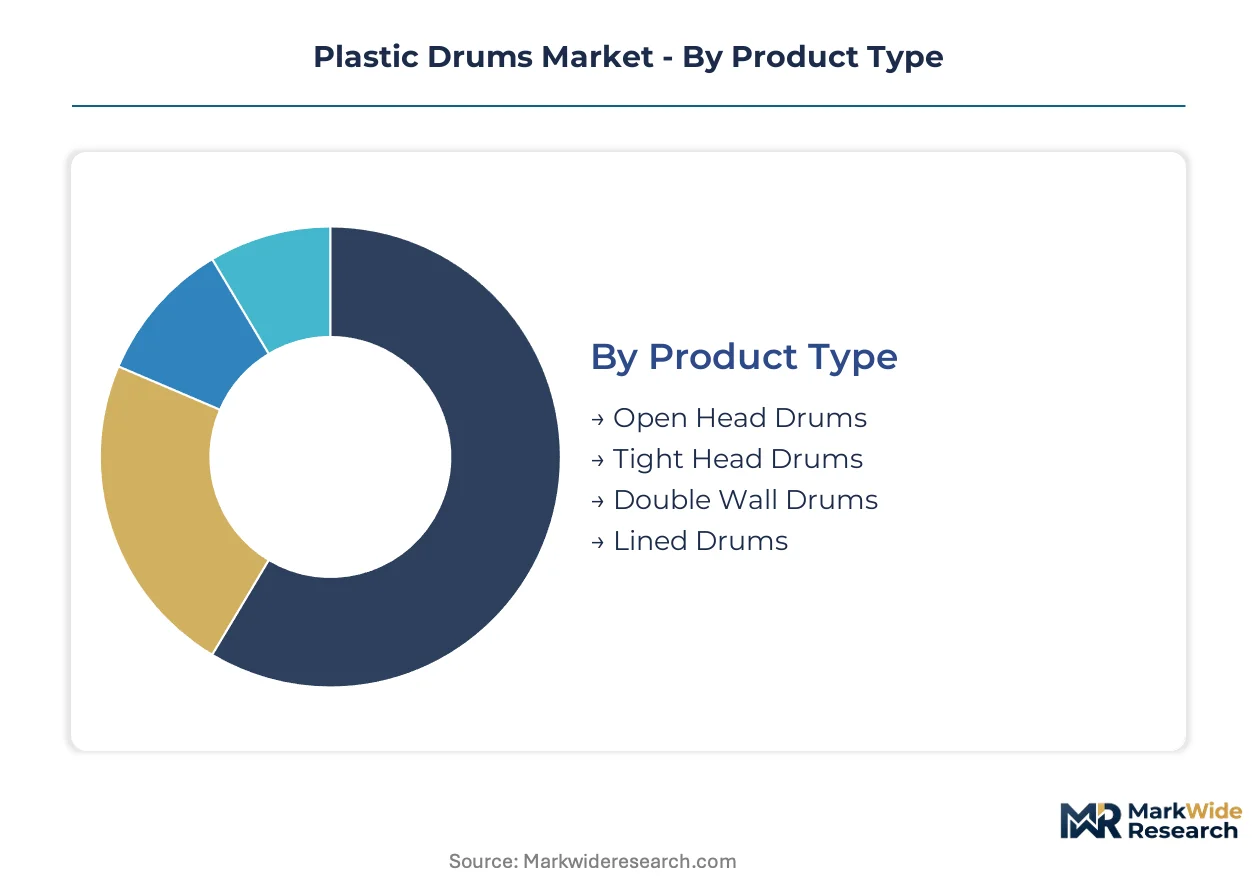
Segmentation in the plastic drums market reveals how container specifications diverge across regulatory environments and handling requirements. Each dimension—product architecture, resin chemistry, application severity, and end-user operational scale—creates distinct procurement criteria that reshape supplier positioning.
Product Type:
Open-head configurations dominate hazardous material handling where frequent access and residue removal prove essential; tight-head designs anchor continuous-flow chemical operations demanding vapor integrity.
- Open Head Drums:Removable lids with bolt-ring or lever-lock closures enable complete interior access for cleaning and residue extraction. Chemical manufacturers in India specify these for agrochemical blending operations where batch-to-batch contamination risks mandate thorough sanitization between fills.
- Tight Head Drums:Fixed top construction with integrated bung openings creates superior vapor retention and stacking stability under UN certification protocols. Pharmaceutical exporters in Germany and the Netherlands prefer these for temperature-sensitive active ingredients requiring hermetic seals throughout cold-chain distribution.
- Double Wall Drums:Nested polyethylene shells with insulating air gaps buffer temperature-sensitive contents against ambient fluctuations.
- Lined Drums:Internal fluoropolymer or epoxy coatings extend chemical resistance into pH extremes beyond base polyethylene tolerance.
Established volume favors tight-head construction; emerging adoption favors open-head reconditioning networks.
Material:
Resin selection balances chemical resistance, regulatory compliance, and circularity mandates across divergent supply chain priorities.
- High-Density Polyethylene:Density ratings between 0.941 and 0.965 g/cm³ deliver the stiffness and impact resistance required for UN-certified stacking loads. Blow-molders serving US Gulf Coast petrochemical corridors rely on HDPE for standardized drum geometries that minimize wall-thickness variation during extrusion.
- Low-Density Polyethylene:Greater flexibility and elongation at break suit applications requiring drum deformation without catastrophic failure. Swiss fragrance compounders specify LDPE-lined containers for viscosity-sensitive essential oils that demand gentle handling.
- Polypropylene:Higher melting point and rigidity suit hot-fill operations and steam sterilization cycles common in pharmaceutical processing.
- Recycled Plastics:Post-consumer resin integration accelerates under ECHA SCIP database requirements and FDA draft guidance on food-contact applications.
Cost engineering favors virgin polyethylene grades; regulatory pressure favors recycled content integration.
Application:
Severity of contents—corrosivity, toxicity, perishability—drives specification divergence across industrial, food, and life-science supply chains.
- Chemical Storage:Concentrated acids, solvents, and reactive intermediates demand wall-thickness and closure integrity certified under UN Model Regulations. EPA secondary containment mandates at US manufacturing facilities are replacing legacy drums with upgraded specifications.
- Food & Beverage Storage:Edible oils, syrups, and liquid ingredients require FDA and EFSA compliance for direct food contact. Barrier-coated multilayer designs from German converters are penetrating this segment as post-consumer resin pathways clarify.
- Pharmaceutical Packaging:Active pharmaceutical ingredients and excipients demand documented traceability and tamper-evidence features.
- Agricultural Products Containment:Pesticide concentrates and fertilizer solutions require resistance to UV degradation and fertilizer salt corrosion.
- Waste Management:Hazardous waste generators specify drums meeting EPA 40 CFR standards for container integrity and closure testing.
Regulatory intensity favors pharmaceutical and chemical segments; volume scale favors food and agricultural applications.
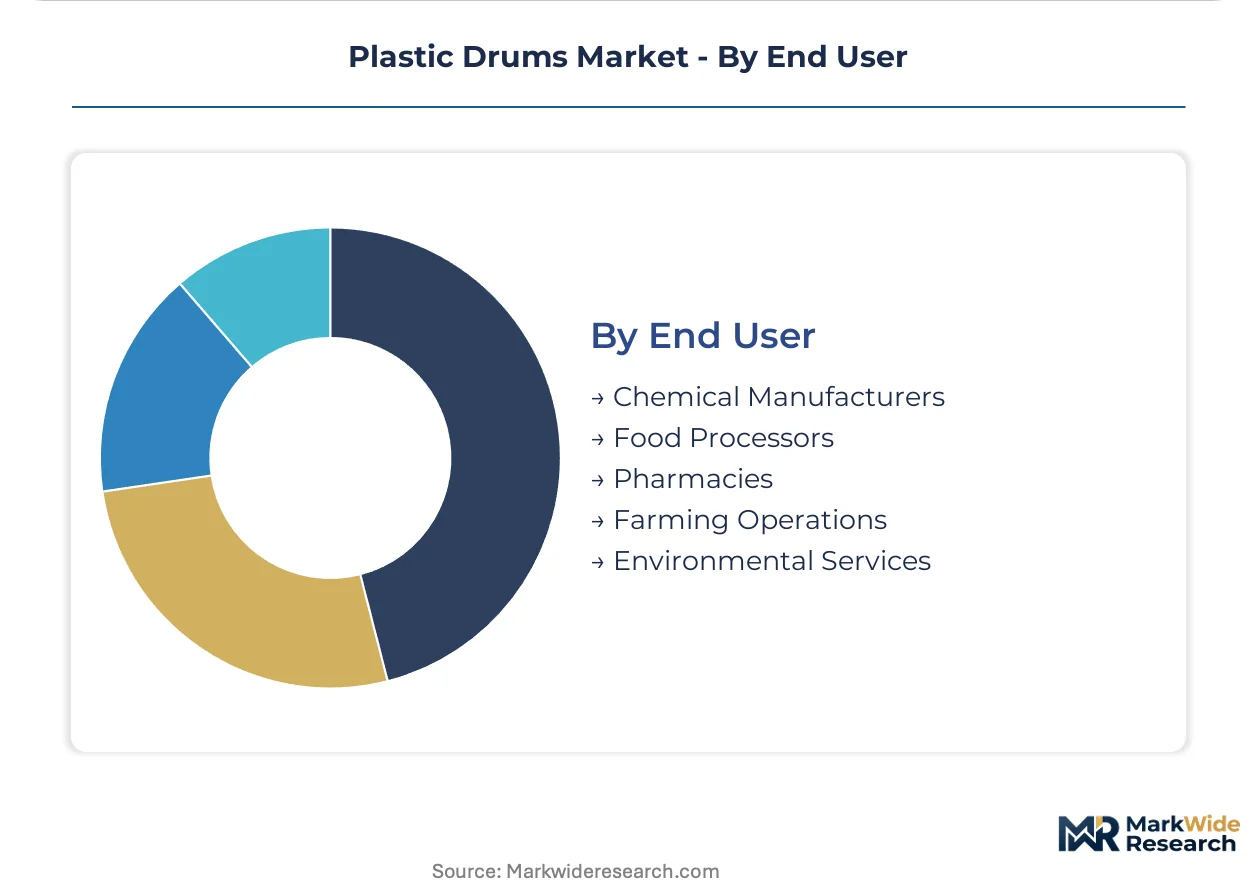
End User:
Operational scale and regulatory exposure create procurement stratification between multinational chemical handlers and dispersed agricultural operators.
- Chemical Manufacturers:Integrated petrochemical and specialty chemical producers specify drum fleets under long-term supply agreements with closed-loop reconditioning clauses. REACH compliance documentation requirements in Europe are consolidating procurement around suppliers with dedicated regulatory affairs capabilities.
- Food Processors:Edible oil refiners and ingredient blenders prioritize lot traceability and kosher/halal certification compatibility.
- Pharmacies:Hospital and retail pharmacy distribution networks require unit-of-use sizing and child-resistant closure integration.
- Farming Operations:Cooperative and individual agricultural buyers in Brazil's Mato Grosso soybean belt purchase through agrichemical distributor networks with ANVISA-aligned certification.
- Environmental Services:Hazardous waste transporters and treatment facilities specify drums with documented chain-of-custody features.
Contract consolidation favors chemical manufacturers; service-model innovation favors environmental services operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American chemical logistics, channeling HDPE resin feedstock from Gulf Coast crackers to extrusion blow-molders serving petrochemical corridors. Rotterdam's Europoort complex functions as Europe's primary drum import gateway, handling reconditioned container flows from Mediterranean reprocessing hubs. Jawaharlal Nehru Port Trust processes India's largest pharmaceutical export volumes, driving specialized UN-certified drum demand for temperature-sensitive active ingredients.
United States
Gulf Coast petrochemical complexes supply virgin HDPE pellets to extrusion blow-molders concentrated along the Houston-Baytown corridor. EPA hazardous waste container standards under 40 CFR mandate wall-thickness upgrades at Texas and Louisiana chemical facilities. The Permian Basin's expanding specialty chemical production is drawing drum converters toward Midland-Odessa distribution nodes.
Germany
REACH SCIP database requirements are forcing drum manufacturers to document full material composition for chemical distributors in the Rhine-Ruhr industrial zone. ECHA's SVHC candidate list updates are compressing product development cycles for converters serving pharmaceutical compounders in Basel's tri-national metro area. Bavarian automotive chemical suppliers are specifying barrier-coated drums for oxidation-sensitive coating intermediates.
India
Pharmaceutical export corridors from Hyderabad and Ahmedabad are driving specialized cold-chain drum demand for temperature-sensitive APIs. CDSCO's evolving packaging guidelines for drug exports are consolidating procurement around converters with dedicated regulatory affairs capabilities. Gujarat's plastics manufacturing belt in Vadodara-Ankleshwar is expanding blow-molding capacity for agrochemical containment.
Brazil
ANVISA-aligned packaging requirements for crop protection exports are creating certified drum demand from multinational agrichemical distributors. Mato Grosso's soybean belt is driving open-head drum adoption for fertilizer blending operations requiring frequent residue removal. São Paulo state's petrochemical complex in Cubatão supplies virgin polyethylene to southeast converters.
Netherlands
EU Green Deal circularity incentives are rewarding closed-loop reconditioning networks with reduced waste-handling fees. Rotterdam-Antwerp chemical logistics corridors are consolidating drum fleets under third-party circular service contracts bundling cleaning and redeployment. Eindhoven's packaging technology cluster is pioneering RFID-embedded track-and-trace integration for pharmaceutical supply chains.
Plastic Drums Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in resin formulation and closure hardware. The market exhibits moderate consolidation, with multinational packaging conglomerates operating closed-loop reconditioning networks alongside regional blow-molding specialists serving single-country chemical corridors. Three archetypes dominate: integrated reconditioning platforms, virgin resin extrusion specialists, and barrier-coating technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with players securing long-term resin supply agreements and ISO certification for pharmaceutical-grade production.
Among North American reconditioning platforms, Greif, Inc. and Orlando Drum & Container Corporation exemplify the integrated service model, while Mauser Packaging Solutions anchors European pharmaceutical drum supply through ISO-certified facilities. Time Technoplast Ltd. represents Asian export-channel specialization, with barrier-coated designs for agrochemical containment occupying a distinct tier.
| Leading Market Players |
|---|
| CL Smith |
| Orlando Drum & Container Corporation |
| Greif, Inc. |
| U.S. Coexcell Inc. |
| AST Plastic Containers |
| Mauser Packaging Solutions |
| Time Technoplast Ltd. |
| Great Western Containers Inc. |
| Schutz Container Systems |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors transmit HDPE pellet cost volatility directly into drum converter margins, concentrating pricing power among Gulf Coast resin suppliers while forcing downstream tiering between certified pharmaceutical-grade and commodity chemical handlers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UN-certified pharmaceutical drums with full SCIP documentation from commodity chemical containers and reconditioned open-head agricultural units. Price differentiation hinges on certification grade—REACH-compliant SCIP disclosure commands substantial premiums over basic chemical-grade specifications—and volume scale, with multinational chemical manufacturers securing multi-year offtake discounts unavailable to dispersed farming cooperatives. Cost compression in the standard tier is intensifying because Gulf Coast resin suppliers leverage hurricane-disruption vulnerability to extract term premiums. Agricultural buyers in Brazil's Mato Grosso soybean belt exhibit highest price sensitivity, while pharmaceutical exporters in Germany and the Netherlands prioritize compliance assurance over unit cost.
Supply Chain Analysis
Tariff exposure between US Gulf Coast petrochemical complexes and European drum converters dominates supply chain risk planning, with resin flows drawing from concentrated naphtha cracking capacity in Texas and Louisiana. Raw material dependencies center on virgin HDPE pellets, recycled post-consumer resin streams, and barrier-coating interlayers of ethylene vinyl alcohol. Single-source geography risk concentrates around Houston Ship Channel logistics nodes vulnerable to weather disruption. Distribution runs through closed-loop reconditioning networks in the Netherlands and third-party logistics bundling in Belgium, with pharmaceutical cold-chain corridors bypassing traditional wholesale channels for direct converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational chemical manufacturers consolidating drum procurement under long-term circular service contracts, fragmenting price discovery for smaller agricultural and environmental services operators.
For Market Incumbents: Harden regulatory affairs capabilities against REACH SCIP database expansion and SVHC candidate list volatility. Secure backward integration into Gulf Coast resin supply through captive offtake agreements or equity stakes in naphtha cracking capacity. Defensive priority centers on insulating pharmaceutical-grade certification tiers from commodity price erosion.
For New Entrants and Emerging Players: Pursue Brazilian agrochemical formulators establishing ANVISA-aligned local blending operations, where certified drum demand outpaces established converter presence. Target barrier-coated multilayer technology licensing for Swiss fragrance compounders seeking odor-sensitive containment solutions. Go-to-market leverage rests on regulatory affairs outsourcing partnerships with incumbent distributors lacking dedicated compliance staff.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core industrial container assets with stranded reconditioning infrastructure. Long-term viability favors converters with proven circular collection networks and pharmaceutical certification moats. Monitor ECHA SVHC candidate list expansion velocity as inflection signal for compliance-driven replacement cycle intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive HDPE pellet access from Gulf Coast crackers insulates margin compression from naphtha volatility. |
| REACH SCIP Compliance Investment | Machine-readable material disclosure capability unlocks European pharmaceutical distributor procurement panels. |
| RFID-Embedded Track-and-Trace Deployment | IoT-enabled drum fleets allow chemical shippers to monetize real-time logistics data streams. |
| Brazilian Manufacturing Footprint Expansion | ANVISA-aligned local production captures agrichemical formulator demand from multinational distributors. |
| Closed-Loop Reconditioning Network Scale-Up | EU Green Deal circularity incentives reward cleaning-redeployment bundling with preferential waste-handling fees. |
Research Approach
The analysis maps extrusion blow-molding capacity tiers, reconditioning network coverage zones, and barrier-coating technology licensing arrangements, each validated through plant managers at Gulf Coast petrochemical facilities, procurement leads at downstream chemical manufacturers, distribution channel partners in Rotterdam-Antwerp corridors, and technical R&D directors at multilayer packaging specialists. Secondary validation draws from customs and trade data flows, American Chemistry Council and Cefic industry reports, SEC 10-K filings from listed packaging conglomerates, and ECHA SCIP database disclosure filings. Bottom-up capacity tallies triangulate against top-down demand estimates from chemical production and pharmaceutical export statistics.
Assumptions held fixed include REACH regulatory enforcement intensity and UN Model Regulations certification protocols, while variables tested encompass HDPE resin price trajectories, recycled content integration rates, and pharmaceutical cold-chain expansion velocity across the projection horizon. Segmentation dimensions modeled span product architecture, resin chemistry grade, application severity, and end-user operational scale. CAGRs derive from regression analysis of historical capacity additions against downstream chemical production growth, with pharmaceutical export volume indices and agrochemical formulation capacity buildouts as industry-specific demand drivers.
Sensitivities concentrate around ECHA SVHC candidate list expansion, Gulf Coast hurricane disruption frequency, and Brazilian real currency volatility affecting agrichemical export competitiveness. Forecasts reflect documented assumptions regarding regulatory timeline adherence and resin supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market