
 South Korea Recycled Plastics Market | 2026-2036
South Korea Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Recycled Plastics Market Intelligence
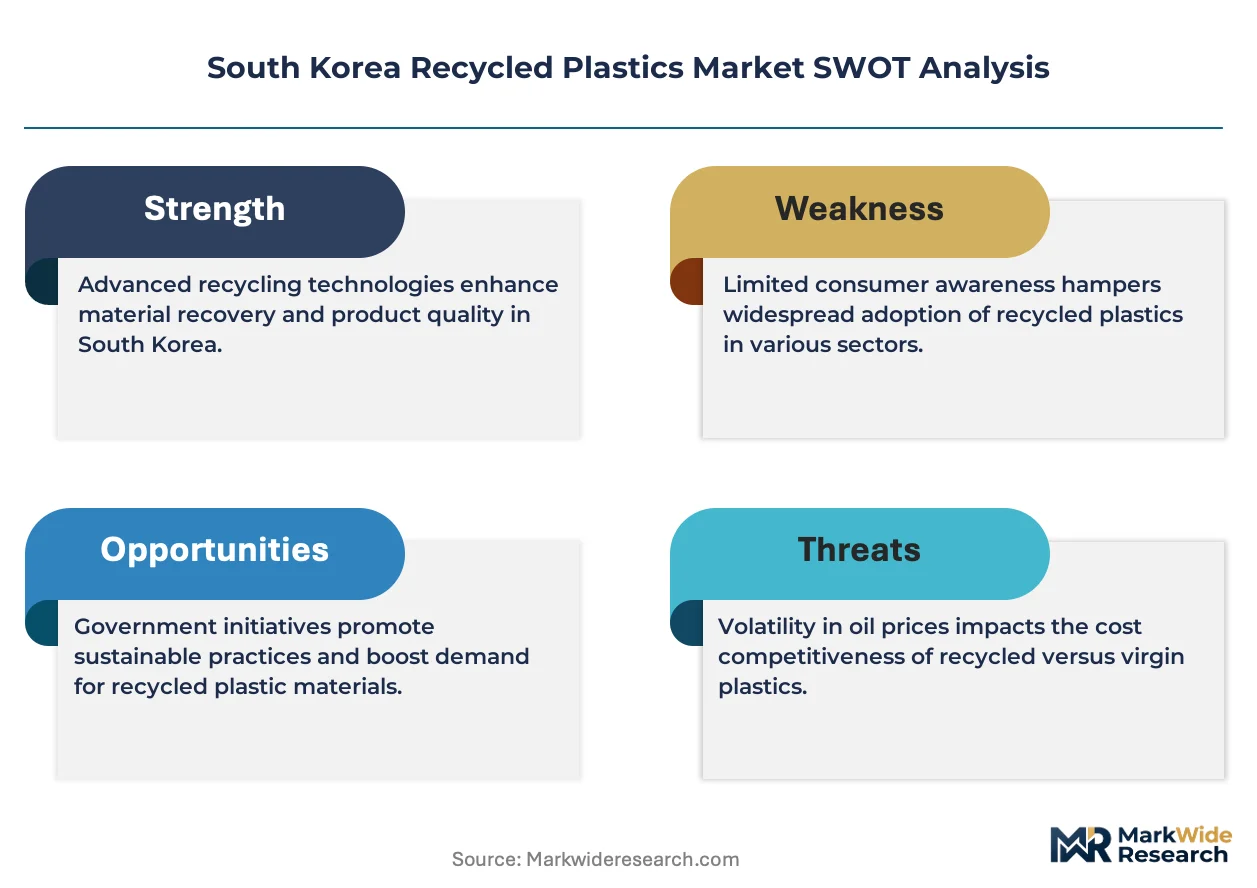
Green bond issuance and project finance structures tied to circular economy targets is rewriting competitive entry barriers for mid-scale recyclers in South Korea. BGF Eco Cycle leverages its integrated collection-sorting-reprocessing network to sustain cost advantages across the Seoul metropolitan area. LG Chem anchors its position through chemical recycling R&D alliances that position the firm for high-purity automotive-grade resin supply. Hanwha Solutions competes on photovoltaic backsheet and construction film applications where certified recycled content commands procurement preference.
South Korea recycled plastics comprise thermoplastic polymers recovered from post-industrial and post-consumer waste streams, reprocessed through mechanical shredding, washing, extrusion, or chemical depolymerization to achieve melt flow indices and contamination thresholds suitable for re-injection molding or fiber spinning. The primary commercial purpose is to displace virgin petrochemical feedstocks in durable goods and packaging where OEMs face Scope 3 emissions reduction mandates. Polyethylene Terephthalate dominates volume flows due to established bottle-to-fiber and bottle-to-sheet collection infrastructure, while Polypropylene exhibits the fastest structural expansion as automotive manufacturers specify recycled grades for interior trim and under-hood components. Packaging applications absorb the largest share of output value, though Construction Materials segments concentrate margin pools where BIS-certified recycled aggregates and waterproofing membranes attract public infrastructure tenders.
Korea's Ministry of Environment enforces extended producer responsibility schemes that obligate brand owners to finance collection and reprocessing of designated packaging materials, directly shaping recycler offtake agreements and facility licensing. MFDS food-contact safety standards and KOLAS accreditation requirements for recycled content verification determine which reprocessors qualify for premium consumer goods supply contracts. The Korea Resource Circulation Society's eco-label program and municipal pay-as-you-throw enforcement further tighten feedstock quality standards. Stakeholders must monitor how chemical recycling mass-balance accounting rules evolve against mechanical recycling's established carbon footprint methodology, as this divergence will determine capital allocation between pyrolysis investments and conventional reprocessing expansion.
Market Dynamics
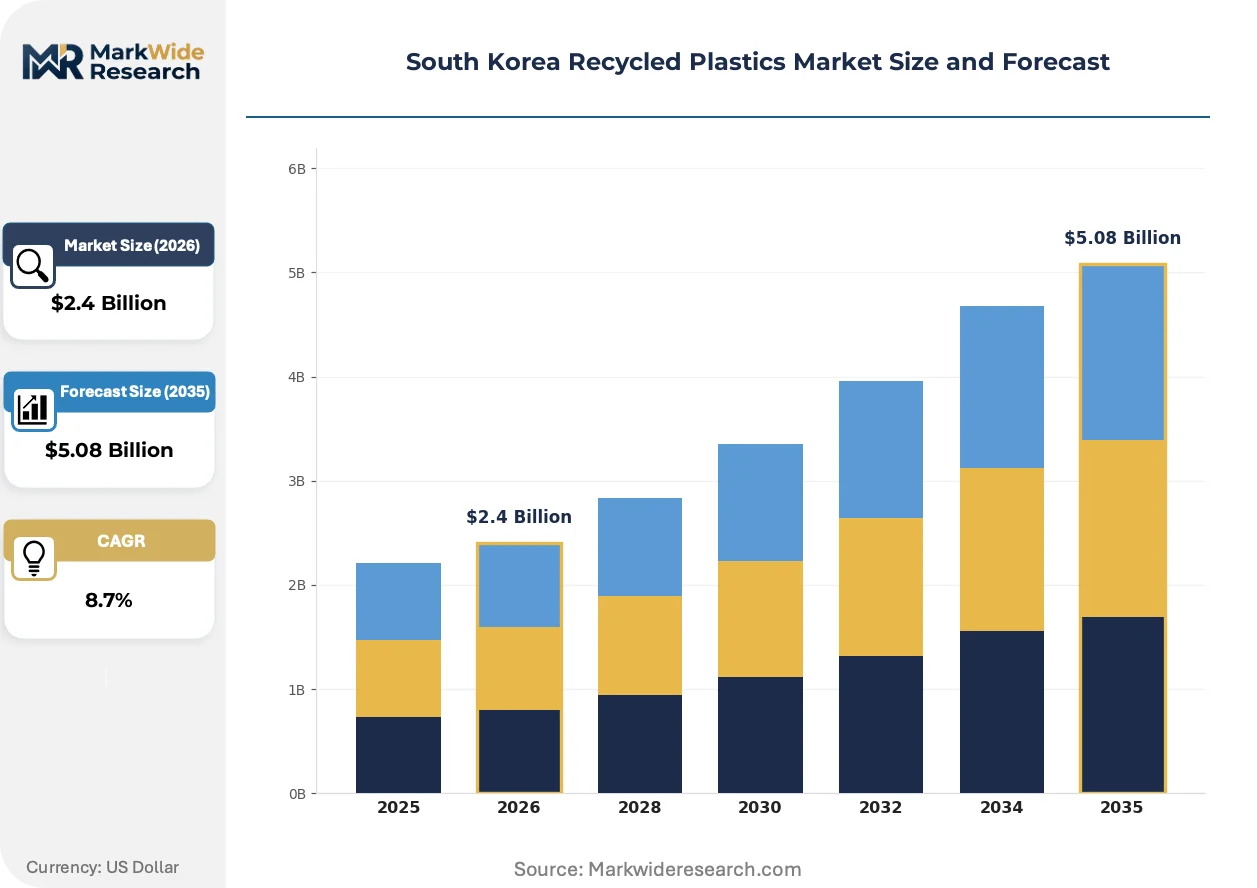
Korea's mandatory recycled content quotas are compressing virgin resin demand while redirecting capital toward pyrolysis infrastructure. The tension between mechanical reprocessing margins and chemical recycling scale economics now governs facility investment decisions across the Seoul-Incheon corridor.
Growth Catalysts
- Extended Producer Responsibility Schemes:Korea's Ministry of Environment obligates brand owners to finance collection and reprocessing of designated packaging materials. This creates guaranteed offtake streams for qualified recyclers.
- Automotive Interior Specifications:OEMs in the Seoul metropolitan cluster enforce supplier sustainability scorecards requiring recycled polypropylene grades for under-hood components and interior trim.
- Chemical Recycling R&D Alliances:Partnerships between petrochemical majors and technology licensors are advancing pyrolysis-based output purity to automotive-grade resin thresholds.
Market Restraints
- Feedstock Quality Volatility:Municipal pay-as-you-throw enforcement varies across district governments, creating inconsistent post-consumer PET bale contamination levels that disrupt extrusion line yields.
- Mass-Balance Accounting Uncertainty:Korea Resource Circulation Society has yet to finalize certification rules for chemical recycling content claims, freezing project finance for pyrolysis investments.
- Mechanical Reprocessing Margin Compression:Energy-intensive washing and extrusion stages face electricity tariff escalation under Korea's carbon pricing mechanism for industrial power users.
Strategic Opportunities
- Photovoltaic Backsheet Applications:Hanwha Solutions and module manufacturers are specifying certified recycled content for construction films where public tender preferences reward circular economy credentials.
- Construction Materials Certification:BIS-certified recycled aggregates and waterproofing membranes attract premium pricing in public infrastructure procurement governed by green building mandates.
- Seoul Metropolitan Collection Density:Integrated collection-sorting-reprocessing networks achieve route optimization and labor productivity advantages unavailable in dispersed provincial markets.
Industry Challenges
- Pyrolysis Feedstock Preprocessing:Chemical recycling facilities require chlorine and silicone removal capabilities that mechanical recyclers lack, demanding capex for auxiliary purification equipment.
- KOLAS Accreditation Timelines:Recycled content verification for food-contact applications faces testing backlogs at accredited laboratories, delaying contract awards for qualified reprocessors.
- Legacy Mechanical Recycling Asset Stranding:Conventional shredding and washing lines face obsolescence risk if chemical recycling achieves cost parity at scale, complicating mid-cycle equipment financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Recycled Plastics Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polystyrene Application: Packaging, Automotive Components, Construction Materials, Textiles End User: Consumer Goods, Automotive Manufacturers, Construction Firms, Textile Producers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | INEOS Styrolution Korea, BGF Eco Cycle, Kumho Petrochemical, HD Hyundai Chemical, DL Chemical, Lotte Chemical, Hanwha Solutions, LG Chem, Samyang Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Recycled Plastics Market Strategic Shifts & Innovations
Technology trajectories in South Korean recycled plastics are converging on purity thresholds that unlock automotive and food-contact applications previously reserved for virgin resin. This shift is compressing the historical quality gap between mechanical reprocessing and petrochemical output.
Pyrolysis-based chemical recycling is migrating from pilot-scale demonstration to commercial feedstock substitution for automotive-grade polypropylene. Hyundai Motor Group and Kia Corporation are qualifying pyrolysis output for interior trim specifications that mechanical recycling cannot satisfy. The technology is migrating from specialty chemical applications toward high-volume automotive supply contracts that absorb plant-scale output.
Korea's Ministry of Environment is tightening enforcement of extended producer responsibility schemes for multi-layer packaging and flexible films previously exempt from collection mandates. Reprocessors must now demonstrate compliance with expanded material coverage to retain operating licenses. The policy shift most affects flexible packaging converters in the Seoul-Incheon corridor who face new financing obligations for collection infrastructure.
Automotive OEMs are consolidating supplier sustainability scorecards into binding procurement specifications with recycled content minimums and carbon intensity ceilings. Tier-1 component manufacturers must certify Scope 3 reductions through accredited verification bodies to maintain preferred supplier status. This behavioral shift is most visible in the Gyeonggi-do province cluster where Hyundai, Kia, and their supplier parks concentrate purchasing power.
South Korea Recycled Plastics Market Segmentation
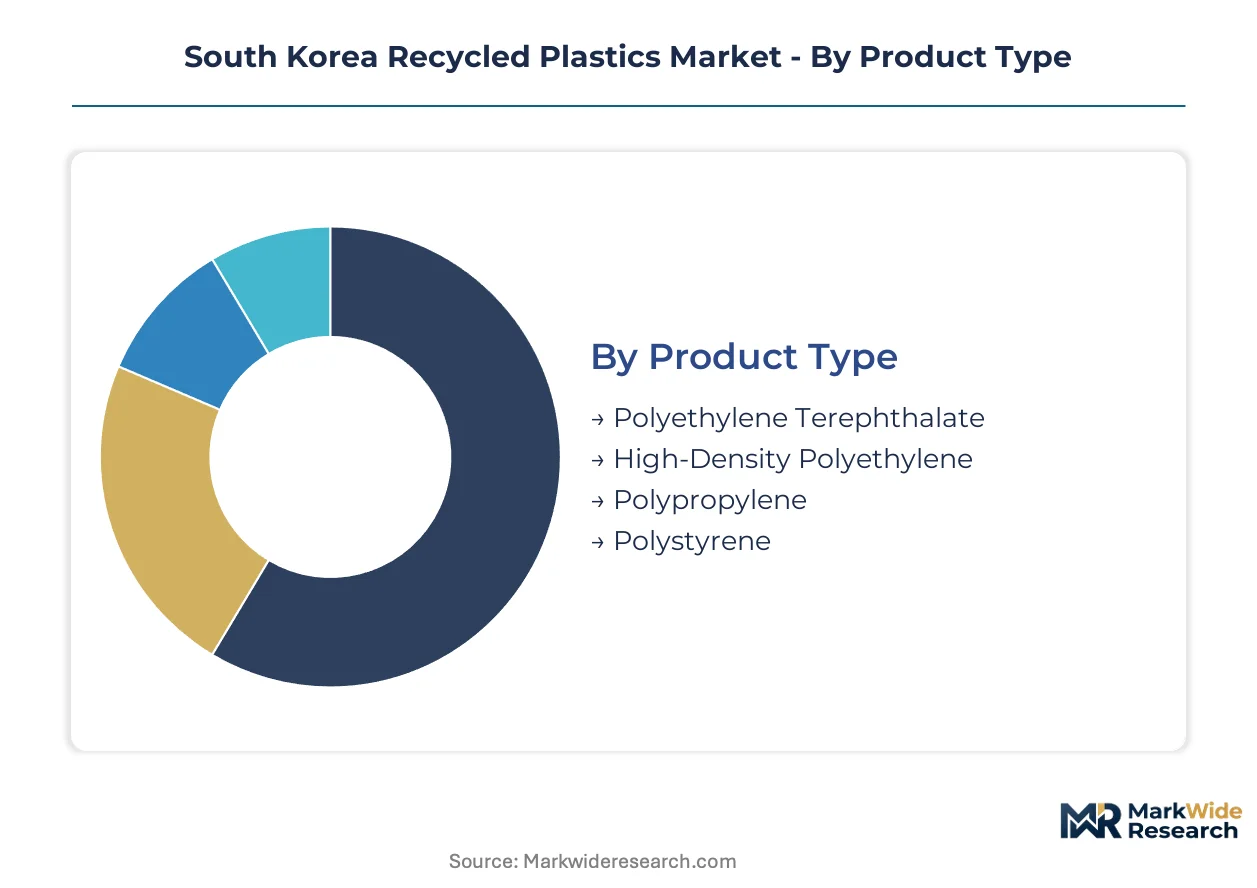
Segmentation in South Korea's recycled plastics market reveals how regulatory mandates and OEM procurement specifications concentrate demand across polymer grades and end-use applications. Understanding these divisions exposes where capital investments in reprocessing capacity yield the highest compliance value and margin capture.
Product Type:
Mature mechanical reprocessing infrastructure dominates commodity thermoplastics, while emerging chemical recycling technologies target purity thresholds that unlock premium automotive and food-contact applications.
- Polyethylene Terephthalate:Post-consumer bottle collection networks in Seoul-Incheon supply feedstock for fiber spinning and thermoformed sheet applications. The Korea Resource Circulation Society's eco-label program certifies rPET for beverage packaging where MFDS food-contact standards apply, concentrating demand among consumer goods manufacturers facing extended producer responsibility quotas.
- Polypropylene:Automotive OEMs in Gyeonggi-do province specify recycled grades for interior trim and under-hood components where heat resistance and dimensional stability requirements exceed mechanical recycling capabilities. Chemical recycling investments by petrochemical majors target pyrolysis-based output purity to qualify for these binding procurement specifications.
- High-Density Polyethylene:Post-consumer containers and industrial drums supply extrusion-grade material for construction film and pipe applications.
- Polystyrene:Expanded and crystalline grades from packaging waste face limited reprocessing economics due to contamination sensitivity and downcycling constraints.
Polyethylene Terephthalate retains volume leadership; Polypropylene holds the steepest expansion curve.
Application:
Application demand splits between compliance-driven packaging substitution and performance-specified durable goods where recycled content verification commands procurement preference.
- Packaging:Rigid containers and flexible films absorb the largest output share as Korea's Ministry of Environment tightens mandatory recycled content quotas for brand owners. Extended producer responsibility schemes obligate financing of collection and reprocessing infrastructure, creating guaranteed offtake streams for qualified recyclers serving consumer goods manufacturers.
- Automotive Components:Tier-1 suppliers in the Seoul metropolitan cluster must certify Scope 3 emissions reductions through accredited verification bodies to maintain preferred supplier status with Hyundai Motor Group and Kia Corporation. Recycled polypropylene grades for interior panels and engine bay components carry sustainability scorecard weight that influences contract awards.
- Construction Materials:BIS-certified recycled aggregates and waterproofing membranes attract premium pricing in public infrastructure tenders governed by green building mandates.
- Textiles:rPET fiber spinning for industrial and apparel applications leverages established bottle-to-fiber collection infrastructure with KOLAS-accredited content verification.
Packaging commands the largest value absorption; Automotive Components are climbing the fastest toward specification-grade purity thresholds.
End User:
End user procurement power concentrates in industrial clusters where sustainability scorecards have hardened into binding contract terms with recycled content minimums.
- Consumer Goods:Brand owners face direct financing obligations under extended producer responsibility schemes for designated packaging materials, creating immediate demand for KOLAS-verified recycled resins.
- Automotive Manufacturers:OEM sustainability mandates cascade through supplier parks in Gyeonggi-do province where Tier-1 component makers must demonstrate certified Scope 3 reductions.
- Construction Firms:Public infrastructure contractors source BIS-certified recycled materials where green procurement preferences apply to waterproofing membranes and structural aggregates.
- Textile Producers:Fiber spinners in the Seoul-Incheon corridor specify rPET chip with verified post-consumer content for industrial and apparel applications.
Consumer Goods retains volume leadership; Automotive Manufacturers hold the steepest expansion curve.
Distribution Channel:
Channel structure reflects the technical service requirements of recycled resin procurement where contamination thresholds and lot-to-lot consistency demands favor direct technical relationships over arm's-length transactions.
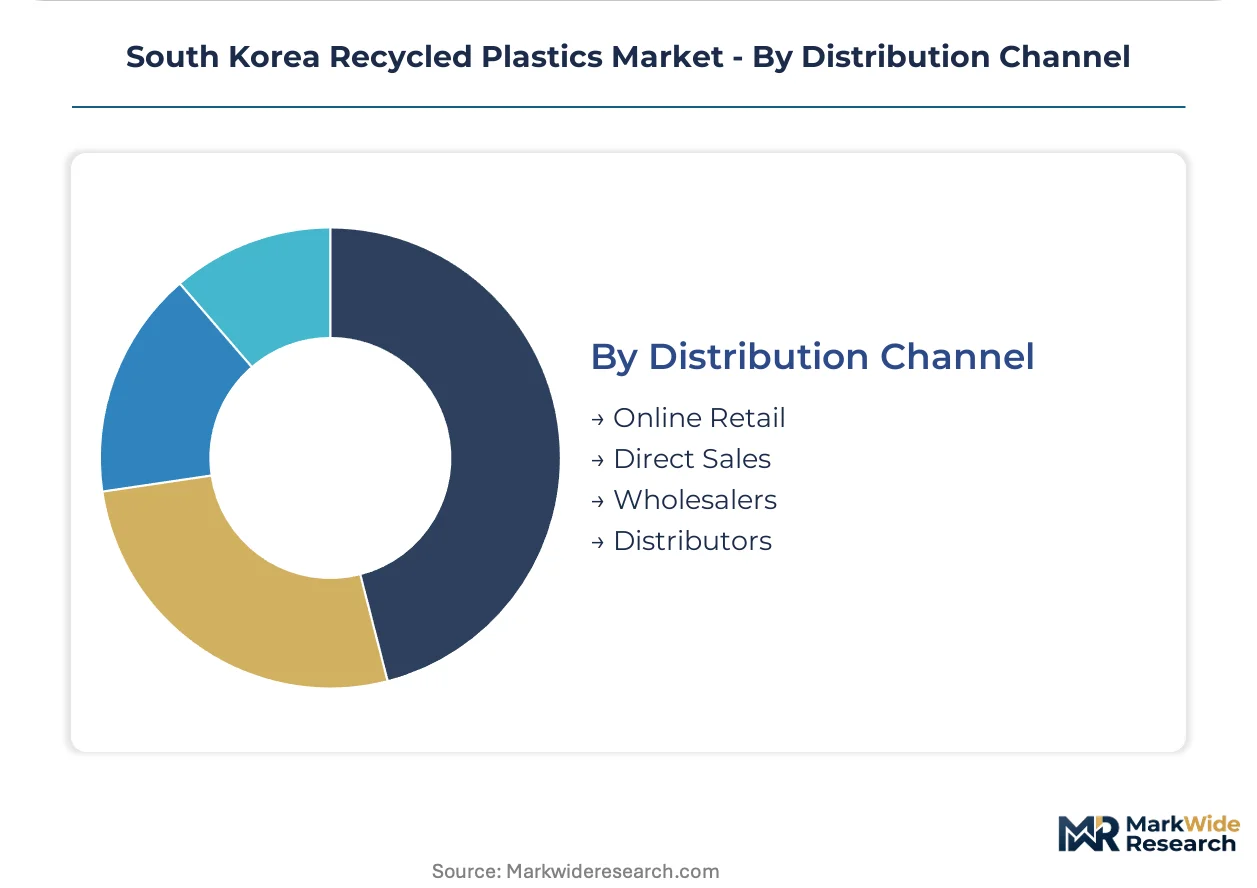
- Direct Sales:Petrochemical majors and integrated recyclers supply automotive OEMs and consumer goods brand owners through long-term offtake agreements with certified recycled content guarantees and carbon intensity documentation.
- Distributors:Regional distributors stock standard grades for construction film and packaging converters in provincial markets outside the Seoul metropolitan density.
- Wholesalers:Volume aggregators serve mid-scale processors with commoditized post-industrial regrind where specification tolerance is wider.
- Online Retail:Digital platforms facilitate spot transactions for small-lot specialty grades and experimental material sampling.
Direct Sales retains volume leadership; Distributors hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's recycled plastics trade balance tilts toward domestic reprocessing capacity expansion, with the Seoul-Incheon corridor absorbing the majority of feedstock flows. Import substitution for virgin petrochemical resins is accelerating as mandatory recycled content quotas tighten across consumer goods and automotive supply chains.
Seoul Capital Area
Packaging manufacturers and automotive Tier-1 suppliers concentrate demand for certified recycled resins under extended producer responsibility enforcement. The Ministry of Environment's pay-as-you-throw schemes in Seoul, Incheon, and Gyeonggi-do generate high-density post-consumer PET collection. Samsung Electronics and LG Electronics supplier parks in Suwon and Gwangmyeong enforce sustainability scorecards requiring KOLAS-verified recycled content.
Busan-Ulsan
Petrochemical majors operate integrated chemical recycling pilot facilities targeting pyrolysis-based automotive-grade resin output. The Korea Resource Circulation Society's mass-balance accounting rules remain unresolved, freezing full-scale commercial deployment. Hyundai Motor Group's nearby supplier network in Gyeongsangnam-do is qualifying chemically recycled polypropylene for interior trim specifications.
Daegu-Gyeongbuk
Textile fiber spinners source rPET chip from established bottle-to-fiber collection infrastructure serving industrial and apparel applications. Daegu's manufacturing base lacks the Seoul metropolitan density for route-optimized collection economics. Provincial recyclers face feedstock quality volatility as municipal enforcement of contamination standards varies across district governments.
Daejeon-Sejong
Government research institutes and standards bodies anchor certification and testing infrastructure for recycled content verification. KOLAS-accredited laboratories face testing backlogs that delay food-contact safety approvals for qualified reprocessors. The Sejong administrative complex houses policy formulation for extended producer responsibility scheme expansion to multi-layer packaging.
Gwangju-Honam
Construction materials manufacturers source BIS-certified recycled aggregates and waterproofing membranes for public infrastructure tenders. Green building mandates in the Honam region create procurement preference for circular economy credentials. Smaller reprocessors struggle to achieve scale economies against integrated collection-sorting-reprocessing networks in the Seoul corridor.
South Korea Recycled Plastics Market Key Industry Players
On the supply side, the industry is consolidating around petrochemical majors with chemical recycling R&D capabilities and integrated recyclers with captive collection infrastructure. Two strategic archetypes dominate: vertically integrated chaebol-affiliated chemical producers and specialized mechanical reprocessors with metropolitan collection density. Competitive moves center on pyrolysis capacity licensing and KOLAS accreditation acquisition for food-contact resin qualification.
Within the integrated recycler tier, BGF Eco Cycle occupies a position exemplifying metropolitan collection-sorting-reprocessing network advantages. Among petrochemical-affiliated producers, LG Chem and Hanwha Solutions represent the chemical recycling investment trajectory targeting automotive-grade resin purity thresholds. Kumho Petrochemical anchors the conventional mechanical reprocessing segment serving construction film and packaging applications.
| Leading Market Players |
|---|
| INEOS Styrolution Korea |
| BGF Eco Cycle |
| Kumho Petrochemical |
| HD Hyundai Chemical |
| DL Chemical |
| Lotte Chemical |
| Hanwha Solutions |
| LG Chem |
| Samyang Packaging |
| Others |
Cost & Logistics Intelligence
The Seoul-Incheon corridor's concentrated reprocessing capacity grants integrated recyclers pricing leverage over provincial competitors who face feedstock logistics penalties. MFDS food-contact certification and KOLAS accreditation create tiered resin valuations where automotive-grade polypropylene commands substantial premiums over construction film grades.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale and certification-grade differentiation. Pricing stratifies across automotive-grade, food-contact, and industrial-tier resin levels. Cost compression in mechanical reprocessing is intensifying because electricity tariff escalation under Korea's carbon pricing mechanism squeezes washing and extrusion margins. Tier-1 automotive suppliers exhibit lowest price sensitivity due to binding sustainability scorecard requirements, while provincial construction film converters face acute margin pressure.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates raw material flow risk for virgin resin substitutes and specialty additives. The supply chain draws from domestic municipal collection, imported post-industrial scrap, and pyrolysis output from Busan-Ulsan pilot facilities. Single-source vulnerability concentrates in chlorine and silicone removal equipment for chemical recycling preprocessing. Distribution runs through direct technical sales to automotive OEMs and consumer goods brand owners, with regional distributors serving provincial packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's recycled plastics sector represents a high-growth disruption as mandatory recycled content quotas and chemical recycling scale economics simultaneously reshape competitive boundaries.
For Market Incumbents: Entrench position through backward integration into Seoul metropolitan collection-sorting infrastructure and accelerated KOLAS accreditation for food-contact resin qualification. Chemical recycling R&D alliances with automotive OEMs provide defensive moats against mechanical reprocessing margin compression from carbon-priced electricity tariffs. For New Entrants and Emerging Players: Build out specialized pyrolysis feedstock preprocessing capabilities for chlorine and silicone removal that mechanical recyclers lack, targeting the Gyeonggi-do automotive supplier park with certified automotive-grade polypropylene. Photovoltaic backsheet applications offer the most penetrable entry point given Hanwha Solutions' procurement preferences for circular economy credentials. For Investors and Strategic Acquirers: Carve-out targets emerge from chaebol-affiliated petrochemical parents seeking to monetize non-core mechanical reprocessing assets stranded by chemical recycling scale economics. Long-term viability hinges on mass-balance accounting rule finalization by the Korea Resource Circulation Society. The signal to watch is Hyundai Motor Group and Kia Corporation qualification timelines for pyrolysis-based interior trim specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | BGF Eco Cycle's metropolitan route density creates feedstock cost advantages unavailable to dispersed competitors. |
| Chemical Recycling Capacity Licensing | LG Chem and SK Geo Centric pyrolysis investments target automotive-grade purity thresholds mechanical reprocessing cannot satisfy. |
| KOLAS Accreditation Acquisition | Food-contact safety certification unlocks premium consumer goods supply contracts under extended producer responsibility enforcement. |
| Automotive Supplier Park Proximity | Gyeonggi-do clustering enables just-in-time resin delivery with carbon intensity documentation for Scope 3 compliance. |
| Photovoltaic Backsheet Specification | Hanwha Solutions' certified recycled content mandates create guaranteed offtake for construction film grades. |
Research Approach
A spread of perspectives from plant managers at integrated recyclers, procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors at petrochemical majors converged on the working assumptions. Secondary validation drew from Korea Resource Circulation Society eco-label program data, MFDS food-contact safety filings, customs and trade statistics, and KOLAS accreditation records. Bottom-up capacity modeling and top-down demand projection from OEM sustainability scorecard analysis were triangulated.
Demand-supply-balance dynamics across the analysis window were modeled through polymer grade, end-use application, and regional production cluster segmentation. CAGRs were derived from installed capacity expansion schedules, mandatory recycled content quota phase-in timelines, and automotive procurement specification adoption curves. Industry-specific inputs included pyrolysis yield rates, extrusion line contamination thresholds, and electricity tariff escalation under Korea's carbon pricing mechanism.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese chemical recycling entrants or accelerated mass-balance rule finalization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Global Post-Consumer Recycled Plastics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Aluminum Recycling Market