
 US Recycled Plastics Market | 2026-2036
US Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
US Recycled Plastics Market Insights
Multi-source feedstock aggregation is hardening as the dominant sourcing pattern across the US recycled plastics value chain. KW Plastics anchors its position through captive control over bale supply networks across the Southeast. Envision Plastics Industries LLC differentiates via proprietary decontamination systems that sustain food-grade rPET output. MBA Polymers, Inc. specializes in engineering-grade recycled ABS and PP compounds for automotive tier suppliers.
Recycled plastics comprise reprocessed thermoplastic polymers recovered from post-industrial and post-consumer waste streams, typically re-melted and pelletized to achieve melt flow indices between 2 and 30 g/10min for injection molding or extrusion compatibility. Their primary purpose is to displace virgin resin in applications where performance specifications permit lower-cost, lower-carbon material inputs. Polyethylene Terephthalate dominates packaging applications due to established bottle-to-bottle recycling infrastructure and FDA letter of no objection protocols. Chemical Recycling represents the fastest-expanding processing technology segment as pyrolysis and depolymerization units scale to handle mixed-flexible films that mechanical systems reject. Mechanical Recycling retains margin concentration in rigid HDPE and PP streams where sortation purity exceeds 95 percent.
The EPA guides national recycling goal-setting while state regulators in California and Oregon enforce extended producer responsibility frameworks that mandate post-consumer resin minimums. FDA letters of no objection govern food-contact recycled material approvals, creating a bottleneck that shapes which processors can access premium packaging contracts. OSHA and state environmental agencies layer workplace and emissions standards onto facility siting decisions. Stakeholders must monitor how pending state legislation beyond the West Coast reshapes bale economics and offtake obligations.
Market Dynamics
State-level extended producer responsibility mandates in California and Oregon are compressing compliance timelines for packaging converters. These frameworks force rapid resin substitution decisions while bale quality standards tighten across municipal recovery facilities.
Growth Catalysts
- Pyrolysis infrastructure:Chemical recycling units are unlocking value from mixed-flexible film streams that mechanical systems previously rejected. Automotive and construction offtake agreements are scaling accordingly.
- California SB 54 mandates:Post-consumer resin minimums of 25 percent by 2025 and 50 percent by 2030 are forcing brand-owner procurement reallocation toward domestic rPET and rHDPE sources.
- Midwest packaging hub concentration:Converters in Ohio, Michigan, and Illinois are expanding captive offtake capacity to serve CPG demand from Chicago and Detroit metropolitan clusters.
Market Restraints
- Feedstock cost volatility:Post-consumer bale prices swing with virgin resin indices and export demand fluctuations, compressing processor margins during polyethylene oversupply cycles.
- FDA letter of no objection backlog:Food-contact approvals for recycled content face 18-24 month review timelines, bottlenecking premium packaging contract access for non-captive processors.
- Optical sortation contamination limits:Current near-infrared systems struggle with black plastics and multi-layer films, forcing manual secondary sorting that raises unit processing costs.
Strategic Opportunities
- Southeast bale aggregation:Underdeveloped collection infrastructure in Georgia, Alabama, and Tennessee offers first-mover advantage for vertically integrated processors securing long-term municipal contracts.
- Construction-grade rPP compounds:Infrastructure spending is pulling engineering-specification recycled polypropylene into drainage systems, geomembranes, and concrete reinforcement applications.
- Blockchain-enabled provenance tracking:Digital chain-of-custody systems are unlocking premium pricing for certified ocean-bound and agricultural film streams with verified origin documentation.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for recycled-content compounds with consistent melt flow indices commands salary premiums that strain mid-cap processor P&Ls.
- Depolymerization unit capex intensity:Pyrolysis and glycolysis facilities require $50-150 million per installation, concentrating investment capacity among integrated petrochemical players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Recycled Plastics Market |
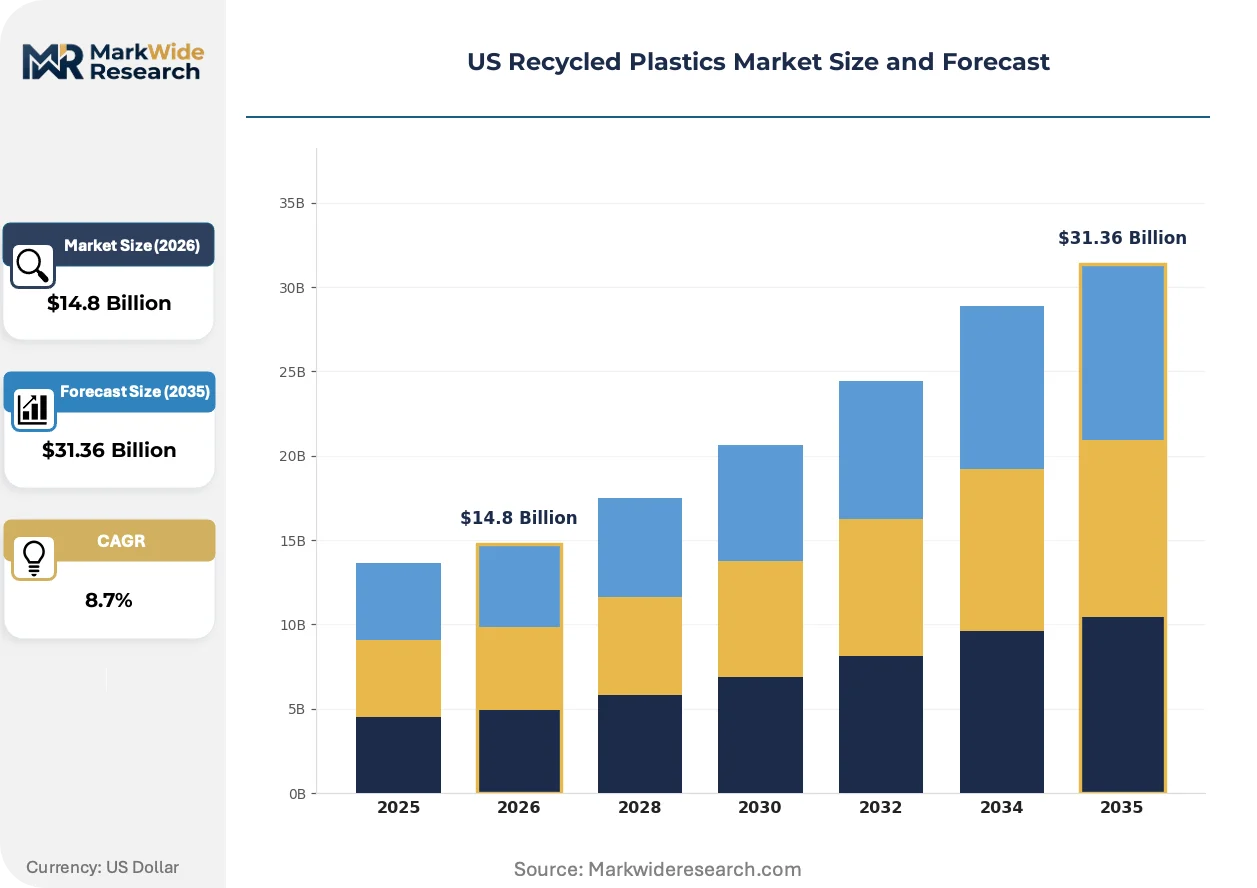
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polyvinyl Chloride Application: Packaging, Automotive Parts, Construction Materials, Consumer Goods End User: Manufacturers, Retailers, Waste Management Companies, Distributors Processing Technology: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Extrusion |
| Companies Covered | Plastipak Holdings, Inc., Envision Plastics Industries LLC, KW Plastics, Merlin Plastics Supply Inc., MBA Polymers, Inc., B&B Plastics Recycling Inc., Custom Polymers, Inc., CarbonLite Industries, LLC, Clear Path Recycling, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Recycled Plastics Market Trends and Innovations
Advanced sortation and decontamination technologies are collapsing the purity-performance tradeoff that historically constrained recycled resin to downcycled applications. Processors are now targeting bottle-to-bottle and food-contact specifications previously reserved for virgin material.
AI-powered robotic sorting is expanding into mixed-waste facilities previously limited to manual pick lines. MRF operators in Texas and Florida are deploying computer-vision systems that identify resin codes through contamination layers at 120 picks per minute. This throughput acceleration is enabling single-stream programs to achieve the 95 percent purity thresholds required for food-grade rPET output.
Oregon's 2025 EPR implementation deadlines are forcing brand-owners to pre-register with state-approved producer responsibility organizations. The Oregon Department of Environmental Quality is enforcing material-specific recovery targets that escalate annually, compelling converters to document chain-of-custody from bale to finished article. Packaging procurement teams are responding by consolidating supplier panels to processors with verified post-consumer resin throughput.
Automotive tier suppliers are embedding recycled-content specifications into resin purchase agreements with penalty clauses for virgin substitution. Tier 1 injection molders serving Detroit-area OEMs now require 30-50 percent post-industrial or post-consumer polypropylene in interior trim components. This contractual embedding is locking in multi-year offtake commitments that de-risk processor capacity expansion decisions.
US Recycled Plastics Market Segmentation
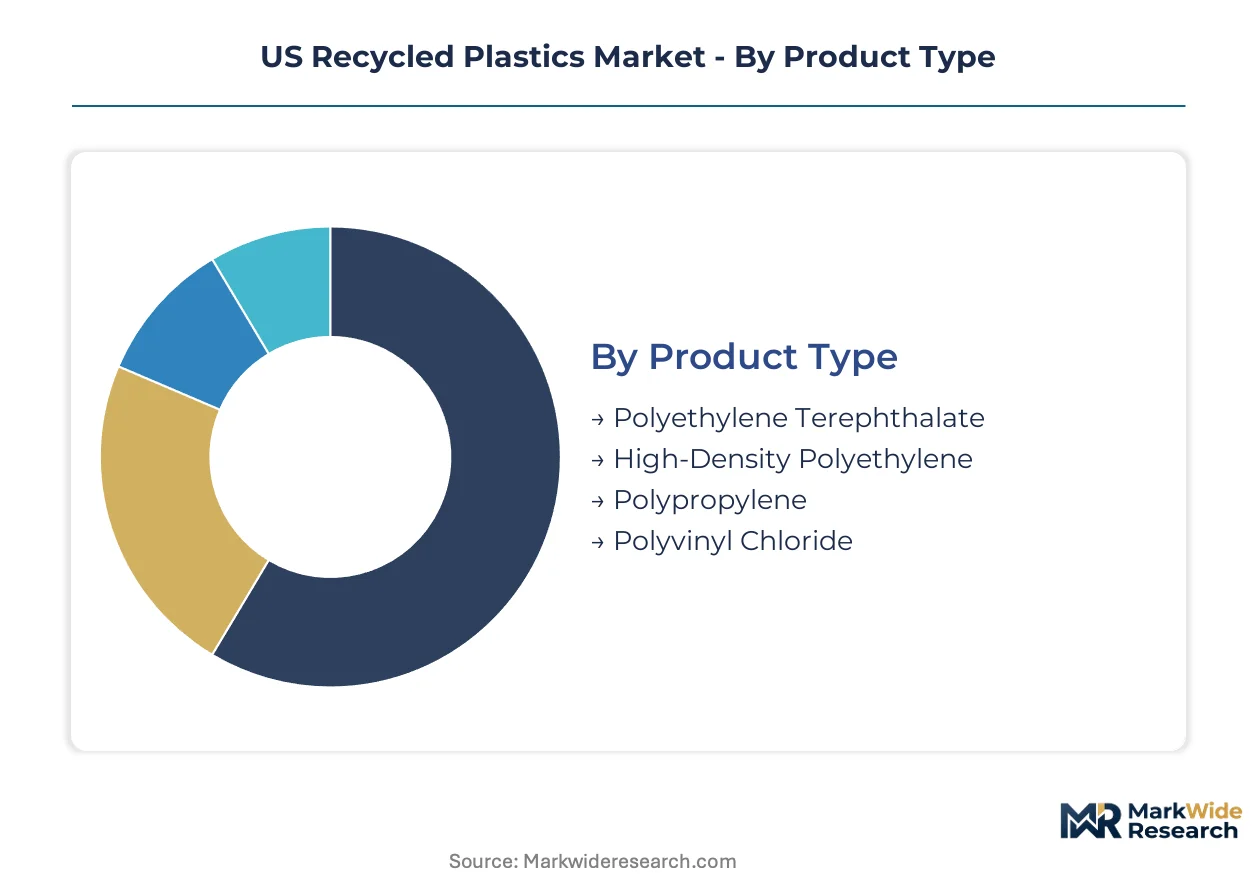
Segmentation in the US recycled plastics market reveals how regulatory pressure and technical specifications fragment procurement patterns. FDA letters of no objection, state EPR mandates, and automotive material certifications create distinct commercial corridors that processors must navigate.
Product Type:
FDA food-contact approvals and automotive OEM material qualifications impose tiered compliance burdens across polymer categories.
- Polyethylene Terephthalate:Bottle-grade flake and pellet achieve melt viscosities of 0.72-0.82 dL/g through solid-state polymerization. California and Oregon brand-owners are locking in long-term offtake contracts for rPET with verified chain-of-custody documentation. FDA letters of no objection for food-contact applications command 15-25 percent price premiums over non-certified material.
- High-Density Polyethylene:Post-consumer milk jug and detergent bottle streams deliver melt flow indices of 4-10 g/10min after extrusion and pelletization. Midwest packaging converters in Ohio and Illinois are expanding captive washing and extrusion lines to meet CPG procurement specifications. HDPE mechanical recycling retains margin leadership where bale contamination stays below 5 percent.
- Polypropylene:Automotive interior specifications demand consistent melt flow and impact resistance from recycled battery cases and bumpers.
- Polyvinyl Chloride:Window profile and pipe reclaim streams face restricted end-use applications due to historical additive concerns.
Polyethylene Terephthalate sits at the top of the volume ranking, with Polypropylene climbing the fastest.
Application:
Cost tier differentiation separates premium food-contact contracts from construction-grade commodity offtake.
- Packaging:Bottle-to-bottle and thermoformed tray applications command the strictest decontamination protocols. California SB 54 mandates are forcing brand-owners to document 25 percent post-consumer resin content in beverage containers. Premium pricing attaches to FDA non-objection letters and third-party ocean-bound plastic certification.
- Automotive Parts:Tier 1 suppliers serving Detroit-area OEMs now embed 30-50 percent recycled-content clauses in resin purchase agreements. Interior trim, under-hood components, and structural reinforcements pull engineering-grade rPP and rABS compounds. Penalty clauses for virgin substitution lock processors into multi-year supply commitments.
- Construction Materials:Drainage pipe, geomembrane, and concrete fiber applications absorb lower-specification recycled feedstock at volume scale.
- Consumer Goods:Durable houseware and furniture applications prioritize aesthetic consistency over mechanical performance thresholds.
Packaging captures the largest revenue pool, while Automotive Parts is gaining share fastest on OEM sustainability mandates.
End User:
Customer type determines contract structure, with captive processors securing municipal bale supply against merchant competitors.
- Manufacturers:Injection molders and extruders serving CPG and automotive verticals specify melt flow indices and contamination limits in master supply agreements. Vertical integration into bale aggregation is hardening as a competitive requirement for food-grade rPET access.
- Retailers:Private-label brand-owners are consolidating supplier panels to processors with verified post-consumer resin throughput and blockchain-enabled provenance tracking.
- Waste Management Companies:MRF operators in Texas and Florida are deploying AI-powered robotic sorting to achieve 95 percent purity thresholds.
- Distributors:Merchant resin brokers face margin compression as direct brand-owner contracts bypass traditional wholesale channels.
Manufacturers dominate procurement volume, with Retailers expanding fastest on EPR pre-registration requirements.
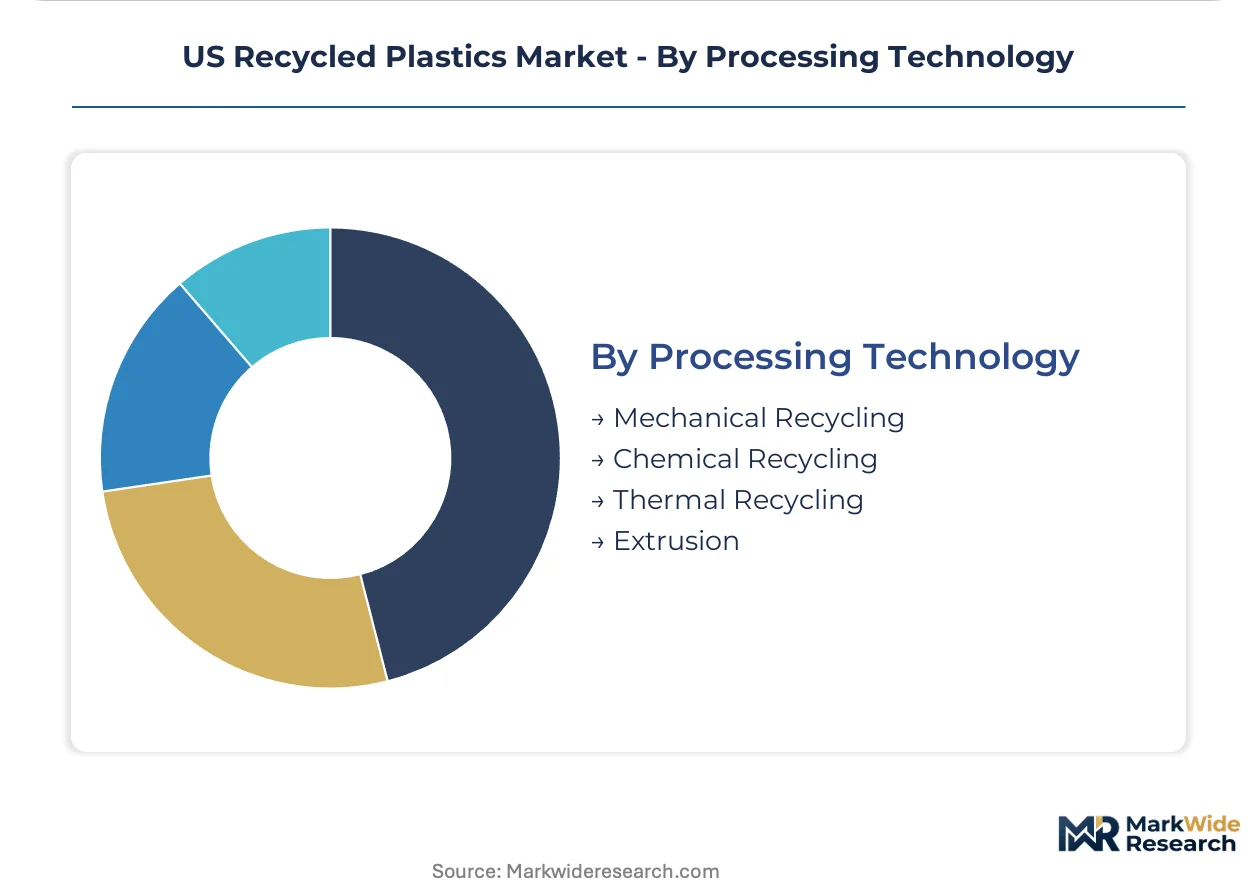
Processing Technology:
Capital intensity and feedstock flexibility separate mechanical from chemical recycling investment profiles.
- Mechanical Recycling:Washing, sorting, extrusion, and pelletization of rigid HDPE and PP streams achieves 95 percent purity at unit costs below chemical alternatives. Near-infrared optical sortation and sink-float density separation remain standard for post-consumer bale processing. Margin concentration persists where municipal contracts lock in feedstock supply.
- Chemical Recycling:Pyrolysis and depolymerization units unlock value from mixed-flexible films and contaminated streams that mechanical systems reject. Automotive and construction offtake agreements are scaling as pyrolysis output achieves virgin-equivalent specifications. Capex requirements of $50-150 million per installation concentrate capacity among integrated petrochemical players.
- Thermal Recycling:Energy recovery applications face declining acceptance as circular economy frameworks prioritize material retention.
- Extrusion:Profile and sheet extrusion of recycled compounds serves construction and industrial packaging end-uses with lower purity requirements.
Mechanical Recycling retains the largest installed base, with Chemical Recycling expanding most quickly on flexible film feedstock access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midwest packaging corridor anchors domestic recycled plastics demand through concentrated converter capacity in Ohio, Michigan, and Illinois serving Detroit and Chicago metropolitan demand clusters.
California
Beverage brand-owners face SB 54 mandates requiring 25 percent post-consumer resin in containers by 2025, escalating to 50 percent by 2030. CalRecycle enforcement timelines compress procurement decisions for rPET and rHDPE. Los Angeles and San Francisco Bay Area processors are expanding decontamination capacity to capture food-grade certification premiums.
Oregon
EPR pre-registration deadlines in 2025 force packaging converters to document chain-of-custody through state-approved producer responsibility organizations. Oregon Department of Environmental Quality material-specific recovery targets escalate annually. Portland-area municipal recovery facilities are deploying AI-powered optical sortation to meet 95 percent purity thresholds.
Ohio
Midwest CPG procurement clusters pull rigid HDPE and PP streams into captive washing and extrusion lines. Ohio EPA worksite standards layer onto facility emissions compliance. Toledo and Cleveland processors are locking in long-term municipal bale contracts to secure feedstock against export competition.
Texas
Single-stream MRF operators deploy computer-vision robotic sorting at 120 picks per minute to identify resin codes through contamination layers. Texas Commission on Environmental Quality permitting shapes facility siting decisions. Houston and Dallas-Fort Worth material recovery facilities are achieving bottle-grade rPET output previously limited to manual sort lines.
Southeast
Underdeveloped collection infrastructure in Georgia, Alabama, and Tennessee offers first-mover aggregation advantages for vertically integrated processors. State environmental agencies in the region are drafting EPR frameworks following West Coast precedents. Atlanta and Birmingham municipal contracts are becoming contested territory for bale supply network control.
US Recycled Plastics Market Competitive Landscape
Global majors compete with regional champions across feedstock access and certification capabilities. The US recycled plastics market fragments across three tiers: integrated petrochemical players with chemical recycling assets, mid-cap mechanical processors with captive bale networks, and specialized compounders serving automotive material specifications. Strategic differentiation concentrates on backward integration into municipal supply contracts and FDA food-contact approval acquisition. Competitive moves center on pyrolysis capacity expansion and blockchain-enabled provenance system deployment.
Among Southeast-based aggregators, KW Plastics occupies a position exemplifying captive bale network control across Alabama and Tennessee. Envision Plastics Industries LLC represents the decontamination technology archetype with proprietary systems sustaining food-grade rPET output. MBA Polymers, Inc. anchors the engineering-grade compounder tier, specializing in recycled ABS and PP formulations for automotive tier suppliers.
| Leading Market Players |
|---|
| Plastipak Holdings, Inc. |
| Envision Plastics Industries LLC |
| KW Plastics |
| Merlin Plastics Supply Inc. |
| MBA Polymers, Inc. |
| B&B Plastics Recycling Inc. |
| Custom Polymers, Inc. |
| CarbonLite Industries, LLC |
| Clear Path Recycling |
| Others |
Pricing and Supply Chain Analysis
Polymer chemist concentration in the Ohio-Michigan corridor widens pricing-tier spreads between food-grade certified rPET and non-certified commodity flake. Labor-cost differentials between formulation specialists commanding salary premiums and general production staff compress margins at mid-cap mechanical processors while concentrating pricing power among integrated players with captive technical talent.
Pricing Analysis
Post-consumer bale cost pass-through dominates processor margin structures, with virgin polyethylene indices directly tracking recycled resin spot pricing. Three-tier pricing structure across FDA food-contact, automotive-specification, and construction-grade tiers separates premium rPET with chain-of-custody documentation from standard HDPE pipe regrind and economy-grade mixed-polyolefin compounds. Pricing pressure stems from export demand fluctuations for post-consumer bales, particularly when Asian buyers compete for Southeast municipal supply. Brand-owners in California and Oregon exhibit lowest price sensitivity due to SB 54 compliance mandates, while construction material distributors remain most cost-responsive.
Supply Chain Analysis
Dual-sourcing requirements from automotive Tier 1 suppliers mandate qualified backup processors for engineering-grade rPP and rABS compounds, forcing brand-owners to maintain relationships with at least two FDA-cleared food-grade rPET providers. Feedstock supply concentrates in the US Southeast, Midwest, and West Coast collection corridors, with bale quality varying by regional MRF investment levels. Raw material dependencies include post-consumer bottle streams, post-industrial automotive scrap, and agricultural film recovery. Tariff exposure on virgin resin imports amplifies recycled content cost competitiveness during polyethylene oversupply cycles. Distribution runs through direct long-term offtake contracts from processors to CPG converters, bypassing traditional merchant resin brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through decontamination technology deployment that unlocks food-contact certification premiums. Operational leverage from automated optical sortation collapses unit processing costs while redirecting previously landfilled streams into bottle-grade output.
For Market Incumbents: Deploy proprietary decontamination systems as the primary defensive lever against emerging chemical recycling entrants. Lock in 10-15 year municipal bale supply contracts in Georgia, Alabama, and Tennessee before state EPR frameworks activate. Preempt FDA letter of no objection acquisition to bottleneck premium packaging contract access for non-captive processors.
For New Entrants and Emerging Players: Capture underdeveloped collection infrastructure in the Southeast as the most penetrable white-space opportunity. Target construction-grade rPP compound supply to infrastructure contractors with lower purity thresholds and faster qualification timelines. Pursue blockchain-enabled provenance tracking as a differentiated go-to-market angle for ocean-bound and agricultural film certification premiums.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap mechanical processors lacking backward bale network integration. Long-term viability centers on feedstock security and regulatory compliance capabilities rather than scale alone. Watch California SB 54 enforcement intensity and Oregon EPR pre-registration compliance rates as the critical inflection signal for domestic rPET demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bale Aggregation | Captures municipal supply security ahead of state EPR mandate expansion. |
| FDA Letter of No Objection Acquisition | Unlocks 15-25 percent pricing premiums in beverage container contracts. |
| Pyrolysis Capacity Expansion | Processes mixed-flexible films rejected by mechanical sortation systems. |
| Blockchain Provenance System Deployment | Verifies ocean-bound plastic origin for brand-owner sustainability procurement. |
| Automotive Tier 1 Supply Agreement | Locks multi-year offtake through recycled-content penalty clauses. |
Research Methodology
Coverage spans the US West Coast, Midwest, Southeast, and Southwest, with primary inputs from each regional cluster. The analysis combines structured interviews with MRF operations directors, polymer procurement managers at CPG brand-owners, automotive Tier 1 supplier material engineers, and FDA regulatory compliance officers with secondary validation. Secondary sources include EPA recycling rate databases, CalRecycle SB 54 implementation reports, FDA food-contact submission records, and municipal contract award documents. Bottom-up bale flow modeling and top-down resin demand estimation were triangulated to anchor volume projections.
Rate-of-change decomposition across the analysis window isolates feedstock availability trends, regulatory compliance cost trajectories, and technology adoption curves. Segmentation dimensions modeled include polymer type, application tier, processing technology, and end-user procurement structure. CAGRs were derived from installed capacity expansion schedules, state EPR implementation timelines, and automotive OEM sustainability target embedding. Industry-specific forecast inputs incorporate pyrolysis unit commissioning announcements and FDA letter of no objection approval pipelines.
Feedstock cost volatility, regulatory enforcement intensity, and chemical recycling technology yield rates are the dominant revision risks to the outlook. Deviation in California SB 54 compliance penalty implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Plastic Lumber Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market