
 Plastics-To-Fuel (PTF) Market | 2026-2036
Plastics-To-Fuel (PTF) Market Size, Share, and Industry Trends Forecast 2026-2036
Plastics-To-Fuel (PTF) Market Intelligence
New capacity additions in the United States and Northern Europe is narrowing the gap between feedstock availability and processing capability. Agilyx specializes in polystyrene chemical recycling, converting it back to a monomer for circular production. Brightmark operates large-scale pyrolysis plants designed to handle mixed plastic waste streams. Neste leverages its extensive refining expertise to integrate renewable fuels produced from waste plastics into its existing supply chains.
Plastics-to-fuel technology encompasses a range of thermal and chemical processes that convert non-recycled plastic waste into liquid or gaseous fuels. These processes, such as pyrolysis, break down long-chain polymer molecules into shorter-chain hydrocarbons, producing a synthetic crude oil or syngas. Pyrolysis technology dominates the current installed base due to its maturity and feedstock flexibility. Petrochemical production represents the fastest-growing end-use application, as chemical companies seek circular feedstocks derived from mixed plastics.
Regulatory frameworks, including the EU's REACH and Circular Economy Action Plan, create strong incentives for chemical recycling. In parallel, directives from the US EPA on waste management and China's dual carbon goals are mandating higher recycling rates and waste diversion. Consequently, project developers must navigate complex permitting processes and secure long-term feedstock agreements to ensure plant viability and profitability.
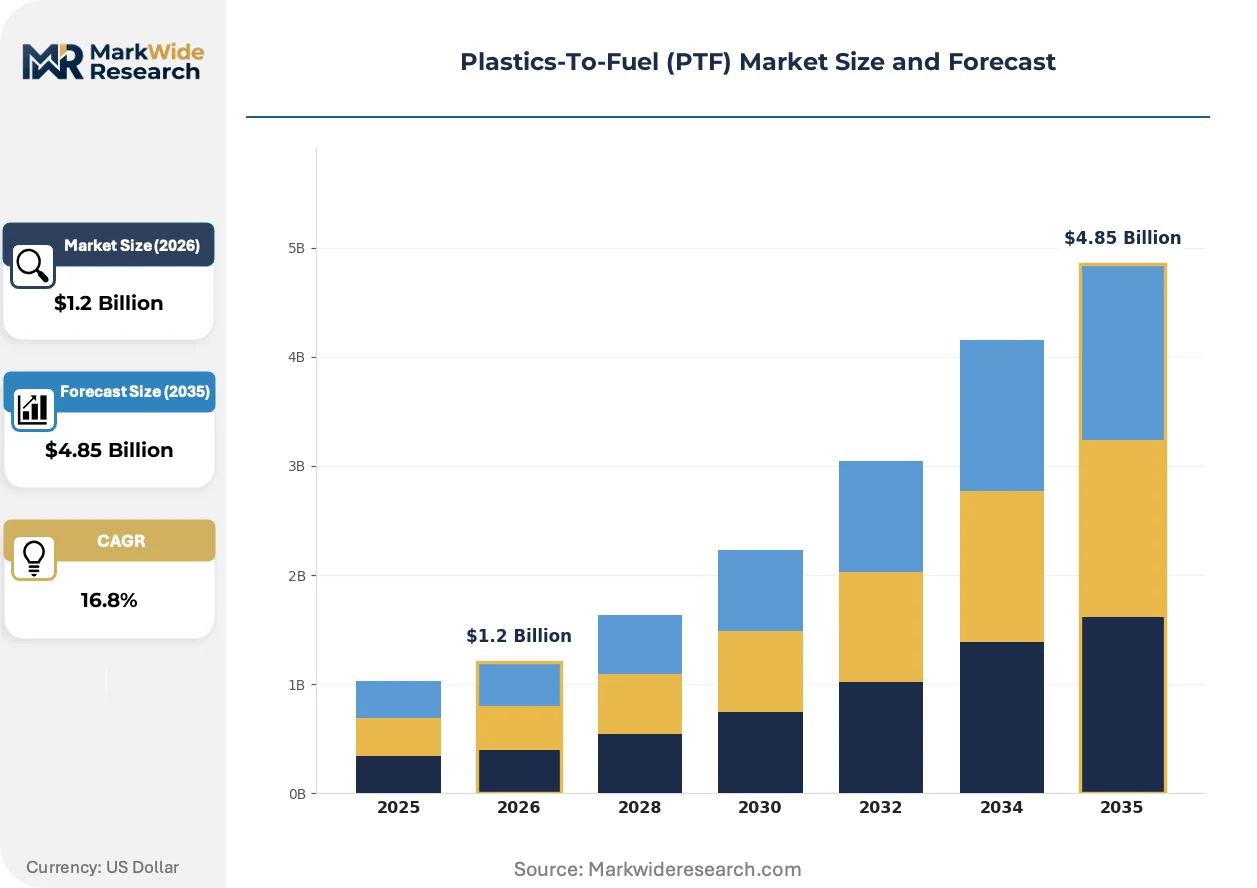
Market Dynamics
The central force shaping the Plastics-To-Fuel market is the dual pressure from regulatory mandates demanding circularity and the petrochemical industry's strategic shift toward recycled feedstocks. This creates a powerful demand-pull that outpaces current processing capacity additions.
Growth Catalysts
- Regulatory Frameworks:The EU Green Deal and directives from the US EPA are establishing economic incentives and recycled content mandates, creating a compliance-driven basis for project investment and offtake agreements.
- Circular Feedstock Demand:Petrochemical manufacturers, particularly in industrial clusters within Germany and the United States, require circular feedstocks derived from mixed plastics to meet sustainability targets for polymer production.
- Technology Maturation:Advances in pyrolysis technology have improved its efficiency and feedstock flexibility, making it a more commercially viable solution for converting non-recycled plastic waste into synthetic crude oil.
Market Restraints
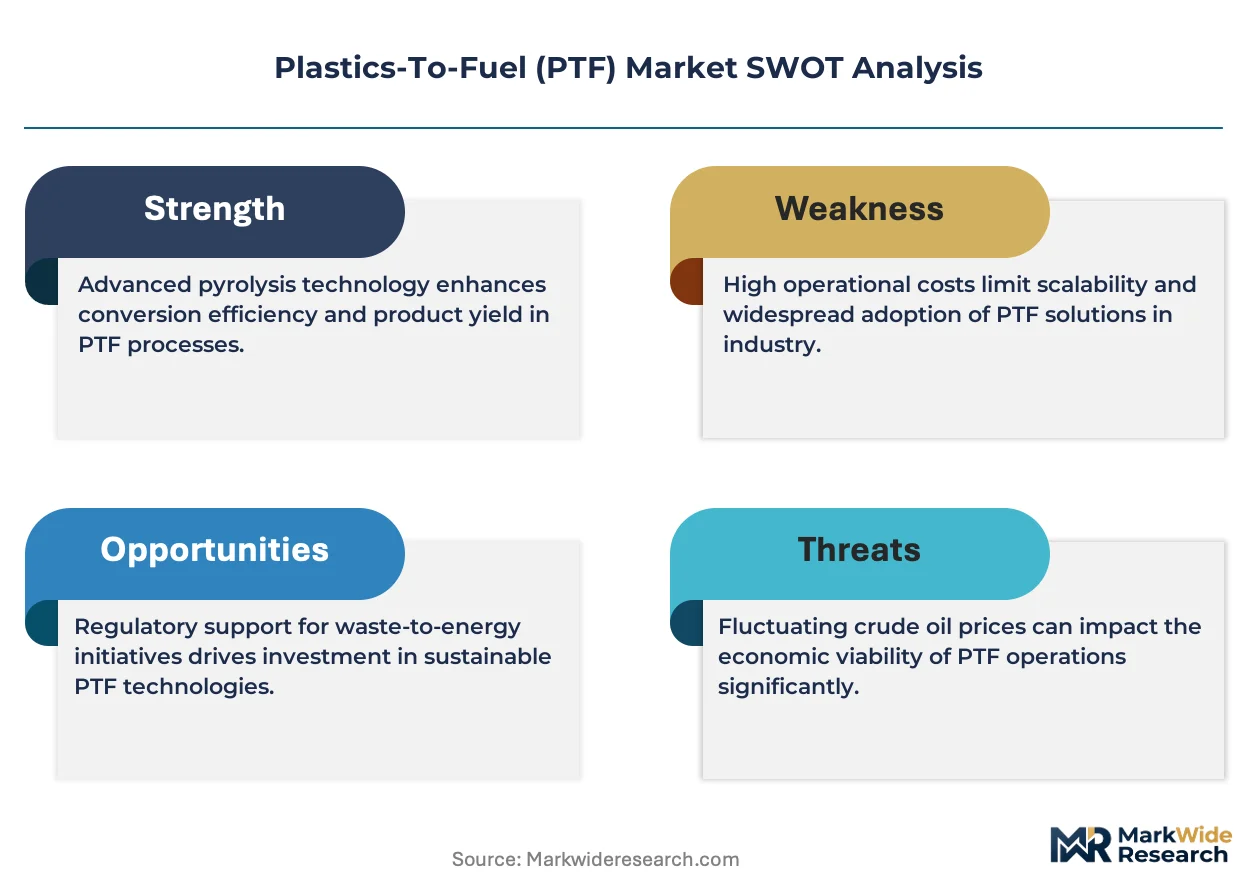
- Feedstock Variability:The inconsistent composition and contamination levels in post-consumer mixed plastic waste streams present significant operational challenges, impacting pyrolysis reactor stability and the quality of the final fuel product.
- High Capital Intensity:The substantial upfront capital expenditure required to construct large-scale chemical recycling facilities, including complex purification systems, acts as a major barrier to entry for new project developers.
- Complex Permitting Processes:Developers face lengthy and intricate environmental permitting timelines, particularly in the United States and Europe, which can delay project execution and increase development costs.
Strategic Opportunities
- Co-location with Chemical Plants:Establishing PTF facilities adjacent to existing petrochemical complexes offers significant logistical and economic advantages, enabling the direct pipeline transfer of synthetic crude as a circular feedstock.
- Specialized Polymer Recycling:Focusing on single-stream feedstocks like polystyrene allows for the production of high-purity monomers, which command a price premium over mixed hydrocarbon fuels and oils.
- Expansion into Asia-Pacific:Growing regulatory pressure on waste management in countries like China, driven by policies such as the dual carbon goals, creates opportunities for deploying proven PTF technologies.
Industry Challenges
- Securing Long-Term Feedstock:Project viability depends on securing stable, long-term agreements for non-recycled plastic waste, a market characterized by fragmented suppliers and fluctuating prices.
- Operational Expertise Scarcity:A persistent shortage of chemical engineers and plant technicians with specialized experience in operating and maintaining high-temperature pyrolysis and syngas systems constrains growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastics-To-Fuel (PTF) Market |
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $4.85 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pyrolysis, Gasification, Hydrocracking, Catalytic Depolymerization, Thermal Depolymerization Feedstock Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride, Mixed Plastics End Use Industry: Power Generation, Petrochemical Production, Marine Fuel, Aviation Fuel, Road Transportation Deployment Model: Centralized Facility, Decentralized Plant, Mobile Unit, On-Site Processing |
| Companies Covered | Neste, Klean Industries, Plastic2Oil, Vadxx, Nexus Fuel, Agilyx, ALTERRA ENERGY, Brightmark, Peel L&P Holdings (UK) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastics-To-Fuel (PTF) Market Strategic Shifts & Innovations
The market's evolution is defined by the drive to produce higher-value outputs beyond basic fuels. This involves integrating advanced sorting with sophisticated chemical processing to create specification-grade feedstocks for circular polymer production, directly meeting the needs of chemical manufacturers.
Advanced pyrolysis process controls, which utilize AI and sensor feedback, allow for real-time adjustments within the reactor. Petrochemical producers are the primary adopters, as the technology ensures the consistent quality of synthetic crude oil required for their steam crackers. This level of precision is collapsing the quality and performance gap between virgin naphtha and circular feedstocks derived from plastic waste.
China's national dual carbon goals are creating a powerful domestic driver for waste-to-value technologies, including PTF. This policy framework compels provincial governments and industrial enterprises to invest in infrastructure that diverts waste from landfills and supports a circular economy. The policy most directly impacts municipal waste management operators and state-owned energy firms, which are now tasked with developing large-scale chemical recycling projects.
A notable shift in commercial strategy involves PTF operators moving away from selling output on commodity markets. Instead, they are forming dedicated offtake partnerships directly with chemical companies, often through multi-year contracts that guarantee supply. This disintermediates traditional fuel brokers and is most prevalent in the chemical manufacturing hubs of the US Gulf Coast and Germany.
Plastics-To-Fuel (PTF) Market Segmentation
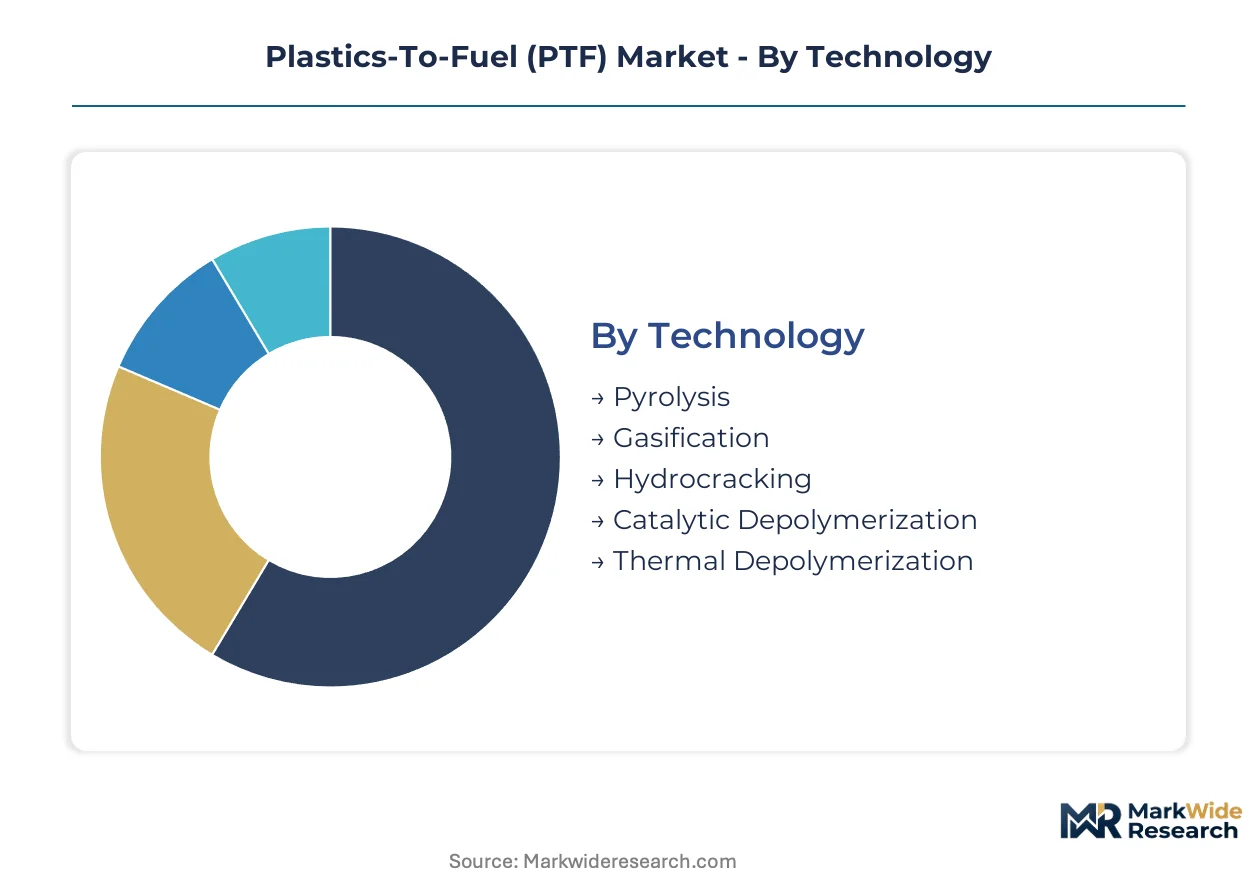
The Plastics-To-Fuel market segments across various technological approaches, feedstock types, end-use applications, and deployment models. Understanding these categories reveals where innovation concentrates and where established processes drive market volume. This granular view highlights the diverse pathways for converting plastic waste into valuable resources.
Technology:
The technology dimension delineates the primary processes employed for converting plastic waste into fuel products.
- Pyrolysis:Pyrolysis involves heating plastic waste in the absence of oxygen, breaking down long-chain polymers into shorter hydrocarbons. Its maturity and feedstock flexibility drive widespread adoption across Europe and the United States.
- Catalytic Depolymerization:This advanced chemical recycling method utilizes catalysts to selectively break down polymers into monomers or specific hydrocarbon fractions. Demand concentrates in Germany, where chemical manufacturers seek high-purity circular feedstocks.
- Gasification:Gasification converts carbonaceous materials, including plastics, into a synthetic gas (syngas) through high-temperature reactions.
- Hydrocracking:Hydrocracking employs hydrogen and catalysts to break down large hydrocarbon molecules in plastic-derived oils.
- Thermal Depolymerization:This process uses heat to break down polymers into their constituent monomers or smaller molecules.
Pyrolysis commands the established base. The steepest expansion runs through Catalytic Depolymerization.
Feedstock Type:
The market's feedstock composition directly influences processing technology selection and the quality of the derived fuel products.
- Mixed Plastics:Mixed plastic waste streams consist of various polymer types, often with contaminants, requiring robust pre-treatment. Processing mixed plastics is crucial for waste diversion efforts in China and the United States.
- Polystyrene:Polystyrene feedstock is typically processed via chemical recycling to yield high-purity styrene monomer, enabling circular production. Specialized demand for this high-value output is strong among polymer producers.
- Polyethylene:Polyethylene offers a relatively clean feedstock for conversion into liquid hydrocarbons or waxes.
- Polypropylene:Polypropylene waste is a valuable feedstock for pyrolysis, yielding oils for fuels or chemical intermediates.
- Polyvinyl Chloride:PVC feedstock presents challenges due to chlorine content, requiring specific processing to manage emissions.
Mixed plastics currently account for the largest processing volume. Polystyrene recycling demonstrates significant growth potential.
End Use Industry:
Demand for PTF outputs is differentiated by the specific industrial applications requiring alternative fuel sources or circular feedstocks.
- Petrochemical Production:This segment represents the fastest-growing end-use, as chemical companies integrate synthetic crude into steam crackers. This provides circular feedstocks for new polymer manufacturing in Germany and the US Gulf Coast.
- Power Generation:PTF-derived fuels, such as syngas or synthetic crude, can replace fossil fuels in industrial boilers for electricity generation. This application provides a stable market for waste plastic conversion.
- Marine Fuel:PTF-derived fuels can serve as lower-sulfur alternatives for shipping, meeting environmental regulations.
- Aviation Fuel:Synthetic fuels from plastic waste offer a pathway to sustainable aviation fuels.
- Road Transportation:Road transport can utilize PTF-derived gasoline or diesel, contributing to fossil fuel displacement.
Petrochemical production is the primary growth engine. Power generation provides a stable baseline demand.
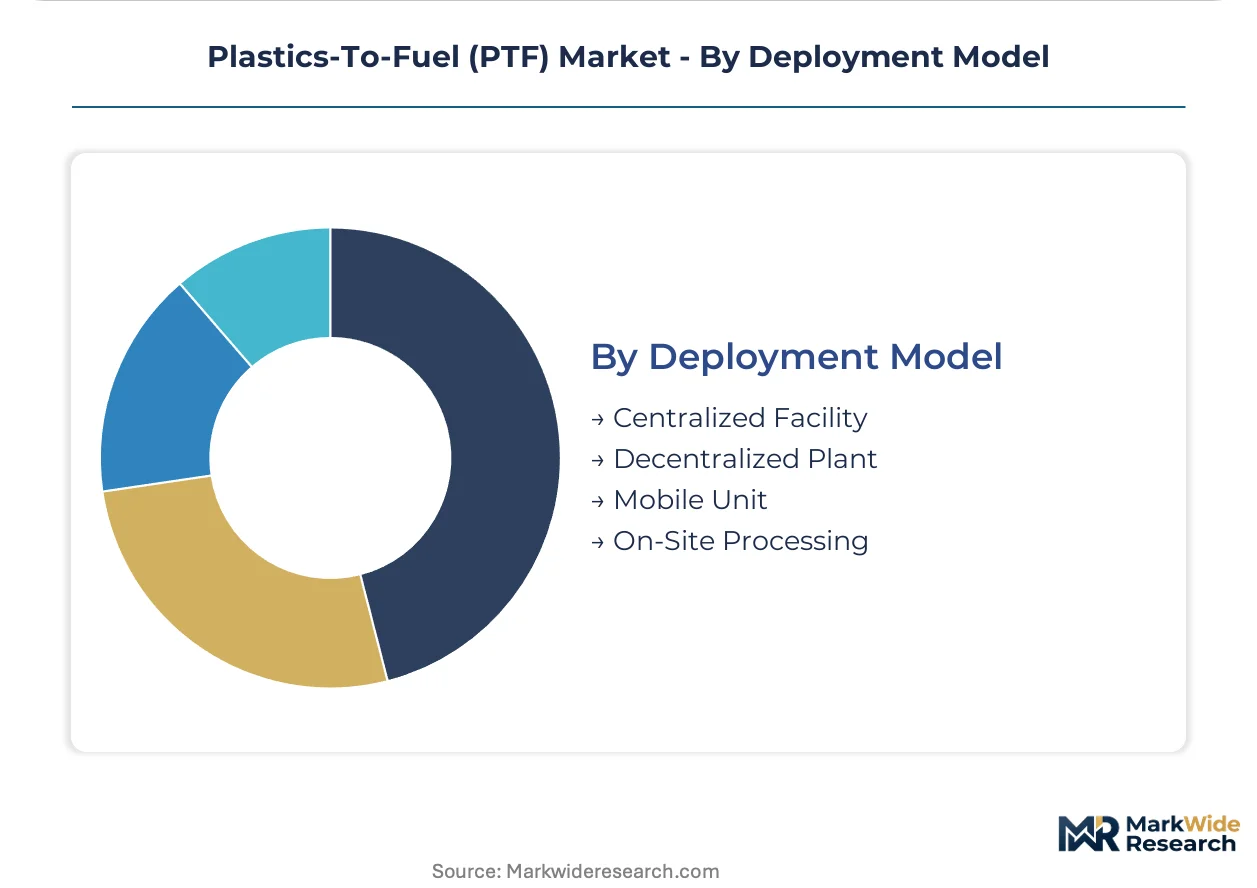
Deployment Model:
The operational scale and location of PTF facilities dictate logistical requirements and integration with waste management infrastructure.
- Centralized Facility:Large-scale centralized facilities process significant volumes of plastic waste from broad catchment areas, benefiting from economies of scale. They often co-locate with petrochemical complexes.
- On-Site Processing:This model involves smaller PTF units located directly at waste generators, minimizing transportation costs. It enables immediate conversion of specific plastic waste streams.
- Decentralized Plant:Decentralized plants serve smaller regional waste streams, offering flexibility and reducing long-distance waste transport.
- Mobile Unit:Mobile PTF units can be deployed to various locations for temporary processing of plastic waste.
Centralized facilities process substantial waste volumes. On-site processing models are gaining traction for specific waste streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration in the Plastics-To-Fuel market is emerging in regions with robust petrochemical industries and stringent waste management regulations. These areas offer both the necessary feedstock infrastructure and a strong demand for circular feedstocks. Significant investment is targeting industrial clusters within the United States, Germany, China, and the Netherlands.
United States
Demand for circular feedstocks from petrochemical producers drives PTF project development. The US EPA directives on waste management and potential incentives from the Inflation Reduction Act (IRA) support new capacity. Industrial clusters along the US Gulf Coast, particularly in Texas and Louisiana, are integrating PTF facilities into existing chemical complexes.
Germany
Chemical manufacturers in Germany seek high-purity circular feedstocks to meet sustainability targets. The EU Green Deal and REACH regulations provide strong incentives for chemical recycling investments. The Rhine-Ruhr region, a major chemical hub, sees significant activity in advanced catalytic depolymerization projects.
China
China's national dual carbon goals and waste diversion policies create a powerful domestic driver for PTF technologies. These policy frameworks compel industrial enterprises to invest in infrastructure supporting a circular economy. The Yangtze River Delta region is witnessing large-scale chemical recycling projects developed by state-owned energy firms.
Netherlands
The Netherlands benefits from strong European circular economy initiatives and a focus on renewable fuels integration. Directives from the EU's Circular Economy Action Plan encourage conversion of plastic waste into valuable resources. The Port of Rotterdam, a major petrochemical and logistics hub, is a key location for PTF facility co-location.
Plastics-To-Fuel (PTF) Market Key Industry Players
Specialized technology providers and large industrial conglomerates split the Plastics-To-Fuel market. This landscape exhibits a tiered structure, with established players focusing on mature pyrolysis technologies and innovators pursuing advanced chemical recycling methods for higher-value outputs. Dominant competitive moves include strategic partnerships with petrochemical companies to secure long-term offtake agreements and continuous capacity expansion to meet rising demand for circular feedstocks. Geographic expansion into new markets like Asia-Pacific also represents a significant strategic thrust.
Specialists in chemical recycling, such as Agilyx and Brightmark, occupy a position focused on converting specific plastic waste streams or deploying large-scale pyrolysis solutions. Agilyx, for instance, exemplifies expertise in polystyrene chemical recycling for high-purity monomer production. Integrated refiners like Neste, a Finland-based company, leverage their extensive refining expertise to incorporate renewable fuels from waste plastics into existing supply chains.
| Leading Market Players |
|---|
| Neste |
| Klean Industries |
| Plastic2Oil |
| Vadxx |
| Nexus Fuel |
| Agilyx |
| ALTERRA ENERGY |
| Brightmark |
| Peel L&P Holdings (UK) Limited |
| Others |
Cost & Logistics Intelligence
Commodity price volatility in crude oil and plastic waste feedstock determines both pricing tier spreads and supply chain shape within the Plastics-To-Fuel market. This market navigates the complex interplay between waste management costs and the value of refined petrochemical products.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for circular feedstocks, favoring long-term contract-based offtake agreements. Price differentiation stems from the quality grade of the output, with high-purity monomers commanding a premium over mixed synthetic crude. Pricing softness affects basic fuel outputs due to competition from virgin fossil fuels. Petrochemical producers seeking circular feedstocks demonstrate lower price sensitivity compared to power generation buyers.
Supply Chain Analysis
Upstream feedstock procurement for Plastics-To-Fuel relies heavily on securing stable supplies of non-recycled plastic waste. Geographic supply concentration for PTF facilities is evident in the United States, Germany, and China. Raw material dependencies include mixed plastics, polystyrene, and polyethylene. Feedstock variability presents a structural supply chain risk. Distribution typically involves direct pipeline transfer to co-located petrochemical complexes via multi-year offtake contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity. Long-term offtake agreements for circular feedstocks represent a recurring-revenue layer expanding faster than initial plant infrastructure investments.
For Market Incumbents:
Build operational excellence moats through continuous process optimization and advanced sorting technologies. Secure long-term feedstock agreements to mitigate supply variability, a significant threat to plant utilization. Invest in catalytic depolymerization research and capacity additions in the US Gulf Coast to meet rising demand for high-purity circular feedstocks. Enhance permitting expertise to navigate complex regulatory timelines effectively.
For New Entrants and Emerging Players:
Pursue specialized polymer recycling pathways, such as polystyrene to monomer conversion, which command higher value. Target industrial clusters in regions with less developed PTF infrastructure, like parts of Asia-Pacific, offering white-space for deployment. A viable go-to-market angle involves forming joint ventures with established waste management operators to ensure consistent feedstock access and local market penetration.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors technology integrators and feedstock aggregators. Long-term viability is strong, anchored by regulatory mandates and the petrochemical industry's decarbonization goals. Acquire companies with proven pyrolysis or catalytic depolymerization technologies and robust feedstock procurement networks. A signal to watch is the increasing number of multi-year offtake agreements signed by major chemical companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases processing volumes of plastic waste, meeting growing demand for circular feedstocks in Germany. |
| Long-term Supply Agreement | Secures consistent feedstock supply for PTF facilities, stabilizing operational costs for Brightmark. |
| Green Manufacturing Transition | Aligns production processes with sustainability goals, enhancing market positioning for Neste. |
| Strategic Partnership | Fosters collaboration between technology providers and petrochemical producers, accelerating market adoption for Agilyx. |
| Geographic Expansion | Deploys proven PTF technologies into new markets like China, leveraging dual carbon goals. |
Research Approach
A standing panel of petrochemical production executives, waste management operators, chemical engineers, and regulatory affairs specialists provided ongoing calibration for market sizing and forecasting. This primary input combined with secondary validation from EU Green Deal reports, EPA waste management directives, and company annual reports. Bottom-up and top-down triangulation ensured data integrity.
Scenario-bracketing framed the analytical framework across the analysis window, incorporating various market conditions. Segmentation dimensions modeled included technology, feedstock type, end-use industry, deployment model, and regional regulatory environment. Compound annual growth rates were derived from historical data analysis and projected future market dynamics, utilizing global plastic waste generation rates and crude oil price forecasts as key inputs.
Macroeconomic conditions sit as an overlay; deviation in energy prices or global trade policies would shift the trajectory. Forecasts reflect assumptions documented through extensive research, acknowledging that rapid technological breakthroughs or unforeseen regulatory shifts in waste management could revise projections. Cross-checking against IEA energy forecasts or World Bank economic outlooks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
North America Plastic Waste Management Market