
 Fabric Conditioner Market | 2026-2036
Fabric Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Conditioner Market Analytics
Mass retail shelf space and digital direct-to-consumer platforms are reshaping how fabric conditioner brands reach buyers. Procter & Gamble Co. leverages its vast distribution infrastructure to sustain dominant placement in North American big-box chains. Henkel AG & Co. KGaA anchors European market share through specialized concentrated formulations that reduce packaging waste. Unilever PLC competes aggressively in emerging economies via localized production and affordability-focused product lines.
Fabric conditioner comprises cationic surfactants, emulsifiers, and fragrance compounds designed to deposit lubricating films on textile fibers during the rinse cycle, reducing static cling and mechanical wear while imparting softness and scent. The primary commercial purpose centers on extending garment lifespan and enhancing consumer tactile satisfaction across washing protocols. Liquid fabric softener remains the mature volume leader with established manufacturing economies, while concentrated formulations capture expanding margin pools through reduced logistics costs and premium positioning. Organic and eco-friendly variants represent the fastest-growing segment as regulatory pressure and consumer preference converge on biodegradable chemistries.
EPA Safer Choice standards and EU REACH chemical registration frameworks shape permissible ingredient lists and disclosure requirements across major markets, directly influencing R&D allocation and reformulation cycles. India's BIS quality certification and China's GB standards for household chemicals add compliance layers for multinational suppliers targeting Asia-Pacific expansion. Stakeholders must monitor evolving fragrance allergen labeling mandates and state-level restrictions on quaternary ammonium compounds to anticipate product portfolio adjustments.
Market Dynamics
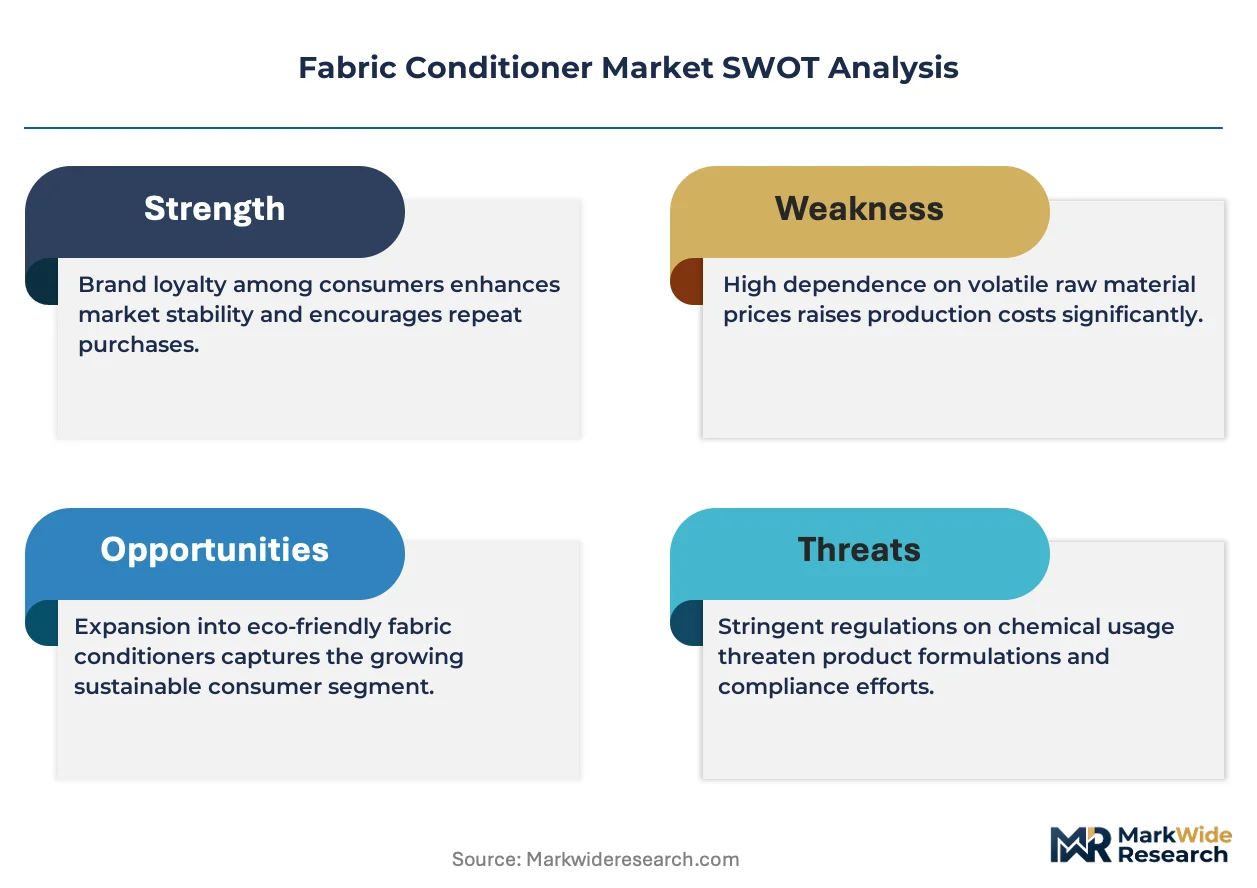
REACH chemical registration frameworks in Europe are forcing reformulation cycles across the fabric conditioner supply base, compressing product development timelines while elevating R&D spend on biodegradable cationic surfactant alternatives.
Growth Catalysts
- Concentrated chemistry:Manufacturers are reducing water content in liquid formulations to cut logistics costs and plastic packaging intensity. Commercial laundries in Brazil's urban centers are converting equipment fleets to accommodate these concentrated dosing systems.
- EPA Safer Choice certification:US retailers are prioritizing shelf placement for products meeting this voluntary standard. Formulators are re-engineering fragrance compounds to eliminate flagged phthalates and synthetic musks.
- Commercial laundry services:Industrial-scale operations in hospitality and healthcare are specifying fabric conditioners with antimicrobial additives. This end-use segment is absorbing higher per-liter pricing for specialized chemistries.
Market Restraints
- Palm-derived feedstock volatility:Quaternary ammonium compound production depends on Malaysian and Indonesian palm oil supply chains. Price swings in these geographies compress margin predictability for European formulators.
- Quaternary ammonium scrutiny:Several US states are advancing restrictions on QAC biocides in consumer products. This regulatory friction threatens standard softening agent portfolios.
- Sheet conditioner substitution:Dryer sheet formats are capturing convenience-oriented buyers who bypass rinse-cycle liquids entirely. This substitute is gaining traction in North American single-person households.
Strategic Opportunities
- India's BIS quality certification gap:Domestic formulators lag multinational compliance capabilities. Early movers can establish premium positioning ahead of enforcement tightening.
- EU Green Deal procurement mandates:Public sector laundry contracts are incorporating biodegradable chemistry requirements. This policy tailwind favors suppliers with verified bio-based surfactant supply chains.
- Direct-to-subscription channels:Refill pouch models are bypassing traditional retail markup structures. Concentrated formats enable cost-efficient last-mile delivery economics.
Industry Challenges
- Fragrance allergen labeling compliance:EU regulation requires disclosure of 26 specific fragrance compounds. Formulators face complex supply chain documentation to verify component-level transparency.
- Legacy equipment incompatibility:Older commercial washing machines lack precision dosing systems for ultra-concentrated products. Capital replacement cycles in laundromat fleets are extending due to interest rate pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Conditioner Market |
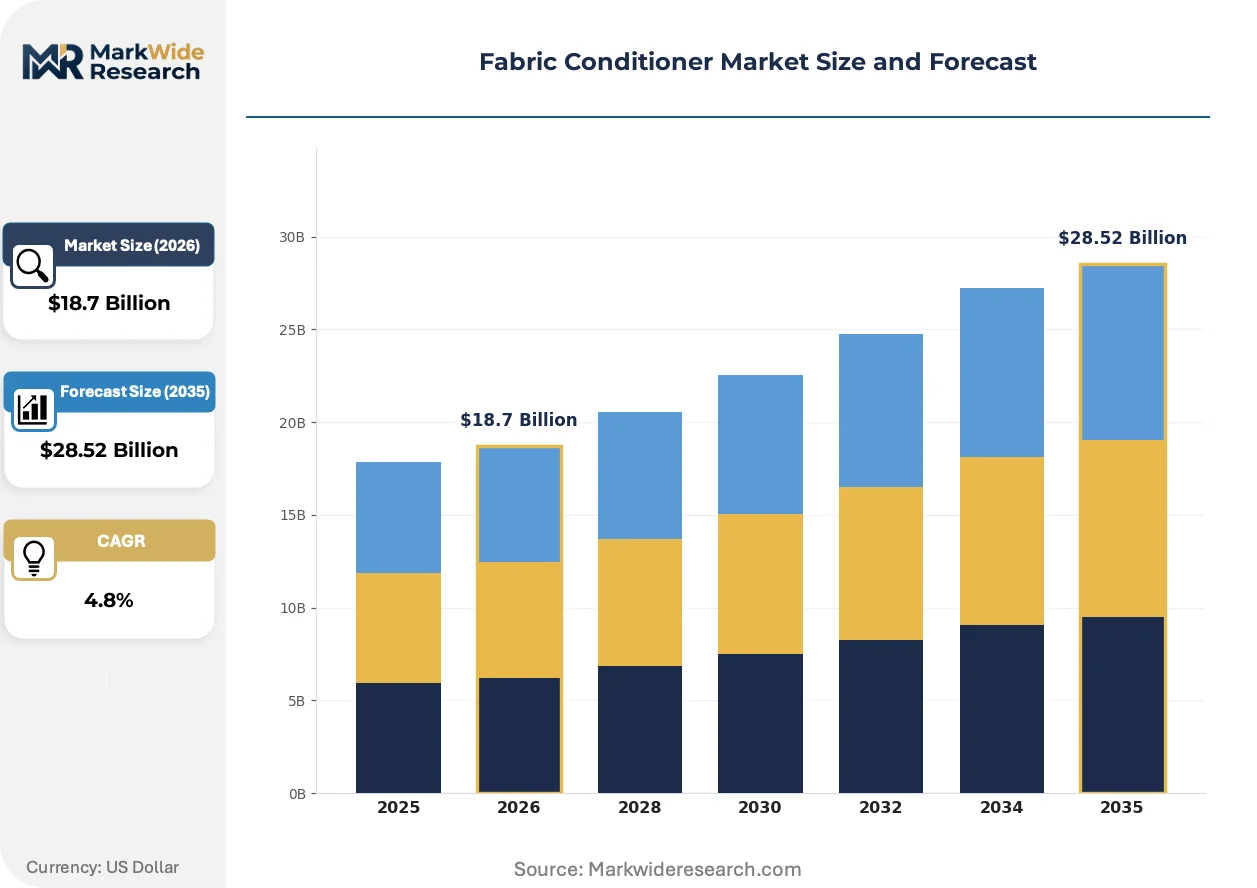
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fabric Softener, Dryer Sheets, Pods, Crystals Formulation Type: Conventional, Organic, Eco-Friendly, Concentrated End User: Households, Commercial Laundries, Hotels, Healthcare Facilities Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Church & Dwight Co., Inc, Kao Corporation, Procter & Gamble Co., Lion Corporation, Reckitt Benckiser Group plc, Unilever PLC, Colgate-Palmolive Company, LG Household and Healthcare, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Conditioner Market Evolving Landscape
Formulation science and distribution mechanics are converging to redefine competitive advantage in fabric conditioning. Three developments are compressing traditional value chain structures while opening new performance positioning opportunities.
Plant-derived esterquat surfactants are replacing petroleum-based quaternary ammonium compounds in premium formulations. European specialty chemical suppliers are scaling fermentation-derived feedstocks to meet this specification. This biotechnological shift is hybridizing conventional softening performance with compostability credentials that command shelf price premiums.
EU REACH annex revisions are expanding registration requirements for fragrance allergens and persistent organic pollutants. Formulators must now submit full substance dossiers for imported raw materials previously traded under simplified notifications. Small and mid-sized suppliers in Southern Europe are consolidating to share compliance infrastructure costs.
Subscription-based refill models are displacing single-use bottle purchases in direct channels. Urban consumers in Germany and the Netherlands are accepting longer delivery intervals in exchange for packaging waste reduction. This behavioral pivot is most visible among millennial households with combined income above national medians.
Fabric Conditioner Market Segmentation
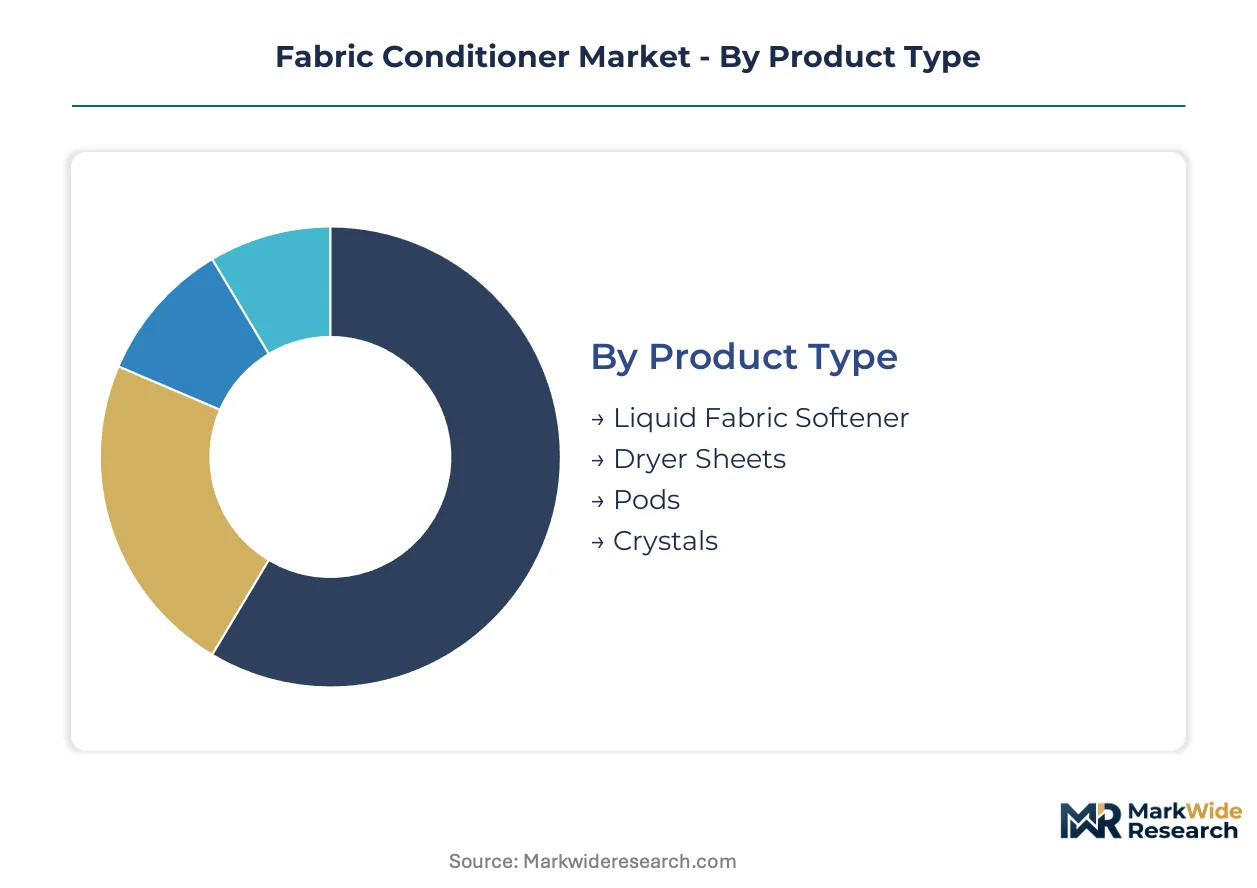
Fabric conditioner demand fragments across usage intensity, regulatory exposure, and procurement sophistication. Each segment carries distinct margin profiles and compliance burdens that reshape competitive priorities.
Product Type:
Use-case spectrum spans rinse-cycle liquids through dryer-integrated formats, with equipment compatibility and convenience preferences driving format selection.
- Liquid Fabric Softener:Cationic surfactant suspensions in aqueous base deposit lubricating films during the rinse cycle. Established manufacturing economies in the US and Germany sustain volume leadership despite higher shipping weights. Mature segment faces margin compression from concentrated alternatives.
- Dryer Sheets:Nonwoven substrates impregnated with heat-activated softening agents and fragrance microcapsules. Single-person households in US urban centers favor this format for bypassing rinse-cycle dosing entirely. Substitution threat to liquid formats is intensifying in convenience-oriented channels.
- Pods:Water-soluble film pouches containing pre-measured concentrated doses. Precision dosing reduces overuse waste in German and Dutch subscription channels.
- Crystals:Granular formulations combining softening salts with extended-release fragrance. Brazilian commercial laundries adopt this format for compatibility with automated dispensing systems.
Established volume favors liquid fabric softener; emerging adoption favors dryer sheets.
Formulation Type:
Cost tier stratification separates premium bio-based positioning from mass-market petroleum-derived chemistry.
- Conventional:Petroleum-based quaternary ammonium compounds dominate manufacturing scale. REACH registration burdens in Europe are elevating compliance costs for this legacy chemistry.
- Organic:Plant-derived esterquats from fermentation feedstocks command shelf price premiums. EU Green Deal procurement mandates in public sector laundry contracts favor suppliers with verified bio-based supply chains.
- Eco-Friendly:Biodegradable surfactant alternatives meeting EPA Safer Choice or equivalent certification. US retailers prioritize shelf placement for products eliminating flagged phthalates and synthetic musks.
- Concentrated:Reduced water content cuts logistics costs and plastic packaging intensity. Commercial laundries in Brazil's urban centers are converting equipment fleets to accommodate these dosing systems.
Margin concentration favors concentrated formulations; regulatory tailwinds favor eco-friendly variants.
End User:
Application intensity ranges from sporadic household consumption through industrial-scale continuous processing.
- Households:Individual consumers purchasing through retail or direct channels. Fragrance preference and tactile satisfaction drive repeat purchase decisions in this price-sensitive segment.
- Commercial Laundries:Industrial-scale operations processing bulk textile volumes. This segment absorbs higher per-liter pricing for specialized chemistries with antimicrobial additives.
- Hotels:Hospitality procurement specifications emphasize guest-perceived softness and signature scent branding. Linen replacement cost reduction justifies premium conditioner spend.
- Healthcare Facilities:Infection control protocols require fabric conditioners compatible with thermal disinfection cycles. Antimicrobial formulation requirements add compliance layers.
Volume scale favors commercial laundries; specification intensity favors healthcare facilities.
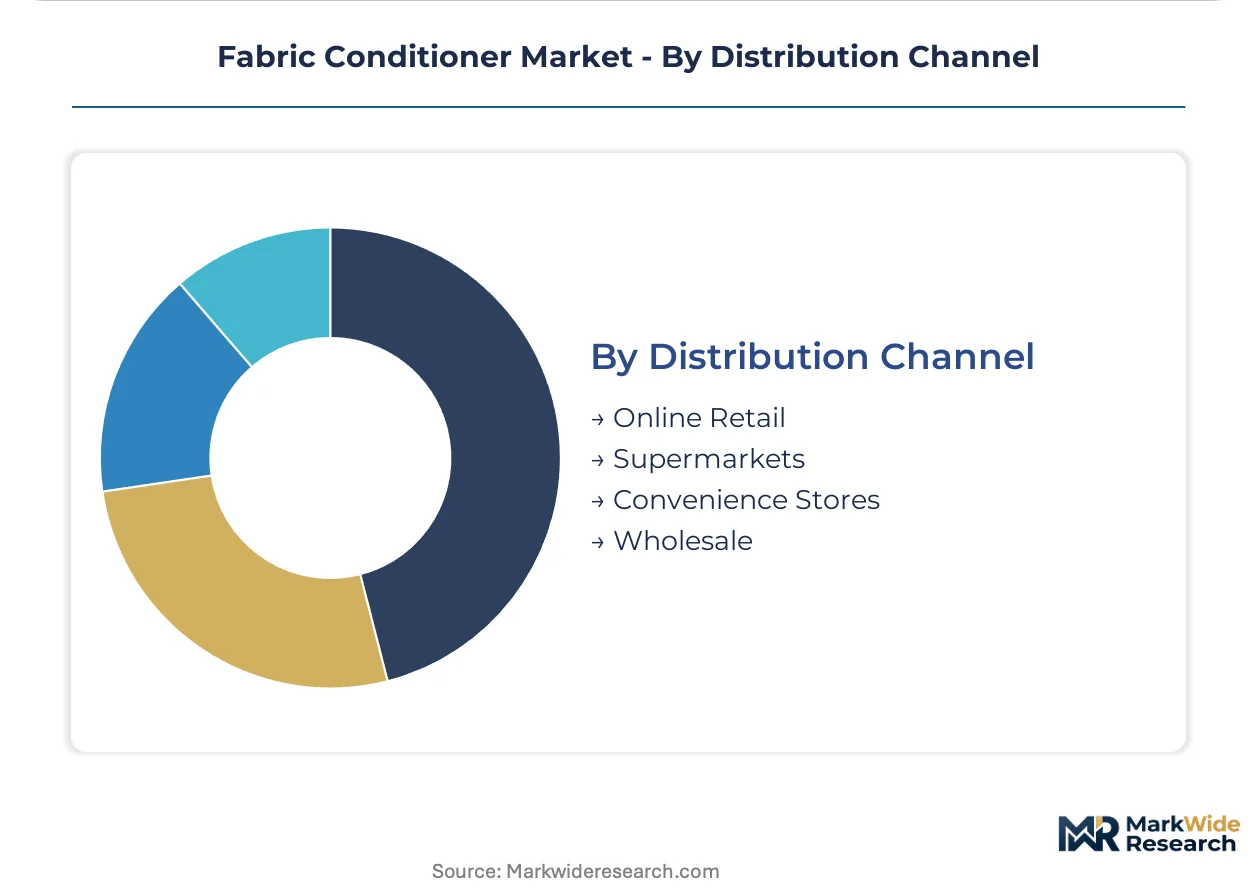
Distribution Channel:
Customer type and purchase frequency determine channel economics and working capital requirements.
- Online Retail:Direct-to-consumer platforms enable subscription refill models. Urban consumers in Germany and the Netherlands accept longer delivery intervals for packaging waste reduction.
- Supermarkets:Mass retail shelf space remains the primary discovery channel for household buyers. Procter & Gamble leverages vast distribution infrastructure to sustain dominant placement in US big-box chains.
- Convenience Stores:Impulse-oriented formats capture emergency replenishment purchases. Single-use sachets dominate this channel in emerging economies.
- Wholesale:Bulk procurement for commercial end-users and institutional buyers. Price negotiation intensity compresses margins but locks volume commitments.
Margin retention favors online retail; volume throughput favors supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands shelf premiums for concentrated bio-based formulations, while Brazilian distributors absorb margin compression from palm-derived feedstock volatility. This asymmetry redirects multinational R&D allocation toward fermentation-derived surfactant platforms.
United States
Commercial laundries in Texas and Florida drive industrial-grade absorption, while EPA Safer Choice certification gates mass retail placement. The Federal Trade Commission monitors green marketing claims for fabric care products. Procter & Gamble leverages Cincinnati-based distribution infrastructure to sustain big-box chain dominance.
Germany
Subscription refill models in Berlin and Hamburg displace single-use bottle purchases among millennial households. EU REACH annex revisions expand registration requirements for fragrance allergens and persistent organic pollutants. Henkel AG & Co. KGaA anchors European market share through Düsseldorf-centered concentrated formulation expertise.
Brazil
Urban commercial laundries in São Paulo and Rio de Janeiro convert equipment fleets to accommodate concentrated dosing systems. ANVISA regulates household chemical safety standards for imported formulations. Domestic formulators face margin pressure from Malaysian and Indonesian palm oil price swings.
India
Rising middle-class garment care intensity in Maharashtra and Gujarat expands addressable household demand. BIS quality certification requirements lag multinational compliance capabilities, creating premium positioning windows. Unilever PLC competes via localized production and affordability-focused product lines.
China
Dual carbon goals accelerate biodegradable surfactant substitution in Yangtze River Delta manufacturing clusters. GB standards for household chemicals add compliance layers for multinational suppliers. NMPA-aligned provincial regulators enforce fragrance allergen disclosure protocols.
Fabric Conditioner Market Competitive Landscape
Multinational conglomerates and regional specialists split the market between scale-driven shelf dominance and niche formulation agility. Consolidation pressure intensifies as REACH compliance costs squeeze mid-tier European suppliers. Three archetypes dominate: diversified consumer goods giants with captive distribution, fermentation-derived specialty chemical suppliers, and private-label converters serving price-sensitive emerging markets. Dominant competitive moves include backward integration into bio-based feedstock supply and geographic licensing partnerships to bypass capital-intensive manufacturing buildouts.
Within the diversified conglomerate tier, Procter & Gamble Co. and Unilever PLC exemplify scale-driven positioning, while Henkel AG & Co. KGaA occupies a specialized concentrated-formulation niche. These three anchors represent divergent strategic bets: Cincinnati-based P&G leverages vast distribution infrastructure, London-headquartered Unilever pursues emerging economy localization, and Düsseldorf-centered Henkel prioritizes European regulatory compliance leadership.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc |
| Kao Corporation |
| Procter & Gamble Co. |
| Lion Corporation |
| Reckitt Benckiser Group plc |
| Unilever PLC |
| Colgate-Palmolive Company |
| LG Household and Healthcare |
| Henkel AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Palm-derived feedstock volatility determines both pricing tier spreads and supply chain shape across the fabric conditioner industry. Malaysian and Indonesian palm oil price swings compress margin predictability for European formulators while elevating premiums for fermentation-derived alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order antimicrobial formulations for healthcare facilities from standard household liquids. A three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by certification grade and volume scale. Pricing pressure stems from dryer sheet substitution in North American convenience channels. Single-person households exhibit highest price sensitivity; healthcare procurement committees absorb premium positioning with minimal elasticity.
Supply Chain Analysis
EU REACH registration requirements function as de facto export controls on fragrance compound formulations entering European markets. Quaternary ammonium compound production draws from Malaysian and Indonesian palm oil supply chains, with cationic surfactant synthesis anchored in German and US chemical manufacturing clusters. Single-source vulnerability concentrates in Southeast Asian oleochemical feedstocks. Distribution runs through multinational consumer goods conglomerates with captive retail shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dryer sheet format substitution threatens liquid softener incumbents who must defend rinse-cycle relevance against convenience-oriented bypass behavior.
For Market Incumbents: Entrench bio-based formulation leadership through backward integration into fermentation-derived esterquat supply chains. Prioritize EPA Safer Choice certification investment to secure mass retail shelf positioning against private-label encroachment. Defend against dryer sheet substitution by embedding precision dosing systems in commercial laundry equipment partnerships.
For New Entrants and Emerging Players: India's BIS quality certification gap offers white-space positioning ahead of enforcement tightening. Target subscription refill channels in German and Dutch urban markets where millennial households accept extended delivery intervals. Pursue direct-to-consumer launch with concentrated pouch formats to bypass incumbent retail markup structures.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-derived specialty chemical suppliers with verified bio-based supply chains. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch EU REACH annex revisions on fragrance allergens as the inflection signal for forced portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive supply of palm-free esterquat feedstocks insulates margin from Malaysian price volatility. |
| Green Manufacturing Transition | EPA Safer Choice certification unlocks preferential shelf placement with US big-box retailers. |
| Direct-to-Consumer Launch | Subscription refill models in Berlin and Hamburg reduce packaging waste while retaining pricing power. |
| Long-term Supply Agreement | Fermentation-derived surfactant contracts with European specialty chemical suppliers secure bio-based credentials. |
| Joint Venture | Equipment compatibility partnerships with Brazilian commercial laundry fleets accelerate concentrated format adoption. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across documented sources. Conversations with plant managers at cationic surfactant manufacturers, procurement leads at commercial laundry operators, fragrance compound suppliers, and retail category buyers supplied operational context. Secondary sources included customs trade records for oleochemical imports, EPA Safer Choice certified product registries, ECHA REACH registration databases, and SEC filings from diversified consumer goods conglomerates. Bottom-up volume estimates triangulated against top-down market sizing.
Forecast inputs incorporated formulation type evolution, end-use intensity patterns, and channel shift dynamics across the projection horizon. Segmentation modeling captured product format, chemistry tier, application intensity, and distribution channel. CAGRs derived from slope analysis of historical trajectory adjusted for regulatory inflection points. Industry-specific inputs included REACH compliance cost absorption rates and palm oil futures curve assumptions.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending or freight cost indices would shift the trajectory. Forecasts reflect documented assumptions on substitution elasticity and regulatory enforcement timing. Material shifts in EU fragrance allergen disclosure mandates or quaternary ammonium compound restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Cleaning Chemicals Market