
 Recycled Elastomers Market | 2026-2036
Recycled Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Elastomers Market Analysis
The EU Green Deal's extended producer responsibility framework for end-of-life tires is expanding the addressable supply of crumb rubber and devulcanized feedstock. Liberty Tire Recycling leverages its North American collection network to anchor supply security for asphalt modification and molded products. Genan Holding dominates European tire-derived crumb capacity with automated cryogenic grinding lines in Denmark and Germany. American Tire Recycling specializes in sports surfacing and equine mats, occupying a defensible niche against commodity-oriented competitors.
Recycled elastomers comprise vulcanized rubber recovered from scrap tires and industrial offcuts, subsequently processed through ambient grinding, cryogenic milling, or thermochemical devulcanization to restore elastic properties and polymer chain mobility for re-compounding. These materials primarily substitute virgin synthetic rubber in applications where full performance equivalence is unnecessary but cost reduction and sustainability credentials matter. Thermoplastic elastomers and styrenic block copolymers lead product type demand due to easier reprocessing and broader compatibility with existing injection molding infrastructure. Automotive parts and construction materials represent the deepest application margin pools, with construction firms and automotive OEMs driving volume through green procurement mandates embedded in supplier scorecards.
The US EPA oversees scrap tire stockpile reduction programs while state-level regulations in California and Texas mandate recycled content minimums for public works projects. REACH and the EU F-Gas Regulation indirectly shape elastomer recycling economics by restricting certain virgin polymer chemistries and elevating lifecycle assessment scrutiny. Stakeholders must monitor devulcanization technology cost curves and OEM qualification timelines for post-consumer content claims.
Market Dynamics
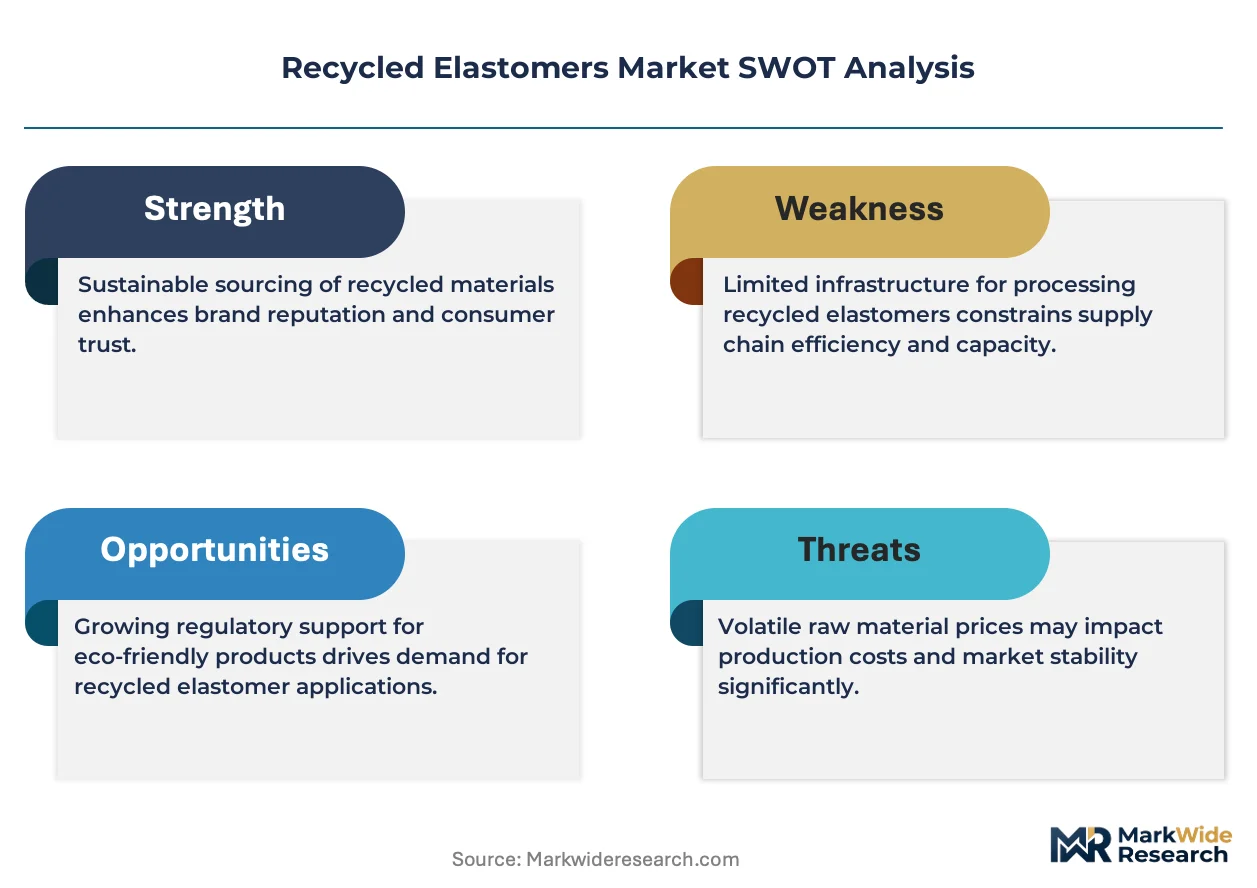
Devulcanization technology maturation is compressing the performance gap between recycled and virgin elastomers, forcing compounders to requalify supply chains around post-consumer feedstock tiers rather than traditional polymer grades.
Growth Catalysts
- EU Green Deal circular economy mandates:Extended producer responsibility frameworks in Germany and France are diverting scrap tire volumes toward qualified crumb rubber processors, expanding addressable feedstock pools for automotive compounders.
- Automotive OEM green procurement scorecards:Tier-1 suppliers to BMW and Volkswagen now face binding recycled content minimums for under-the-hood components, pulling devulcanized EPDM and NBR into specification windows previously reserved for virgin material.
- Cryogenic grinding automation:Danish and German processing facilities have cut particle size distribution variance below 5%, enabling tire-derived crumb to meet asphalt modification and molded product specifications that ambient grinding cannot achieve.
Market Restraints
- Natural rubber price volatility:RSS3 futures swings on the Singapore Exchange create margin compression for recyclers competing against virgin synthetic rubber when substitution economics invert.
- Scrap tire collection concentration:North American collection networks remain dominated by three national operators, creating feedstock security risks for independent processors lacking long-term offtake agreements.
- REACH SVHC disclosure burdens:Recovered carbon black from pyrolysis faces extended substance evaluation timelines at ECHA, delaying qualification for tire sidewall applications where full lifecycle traceability is mandatory.
Strategic Opportunities
- India's infrastructure build-out:National highway expansion programs in Maharashtra and Gujarat are adopting crumb rubber modified bitumen specifications, opening import demand for cryogenically processed material from European exporters.
- Construction sector green building certifications:LEED v4.1 and BREEAM point systems for recycled content are pushing commercial roofing membrane specifiers toward post-consumer EPDM compounds for membrane and flashing applications.
- Pyrolysis-oil upgrading convergence:Integration of tire-derived oil hydrotreating with existing refinery infrastructure is creating circular feedstock loops for synthetic rubber monomer production, bypassing virgin petrochemical dependency.
Industry Challenges
- Devulcanization chemist scarcity:Specialized expertise in selective bond scission without polymer backbone degradation remains concentrated among retiring researchers at German polymer institutes, constraining process scale-up.
- OEM qualification timeline compression:Automotive part approval cycles for recycled content claims now require 18-24 months of durability testing, locking suppliers into feedstock commitments before revenue realization.
- Legacy compounder equipment retrofit costs:Existing internal mixer and extruder lines require screw and barrel modifications to handle devulcanized material viscosity profiles, demanding capital deployment without guaranteed offtake volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Elastomers Market |
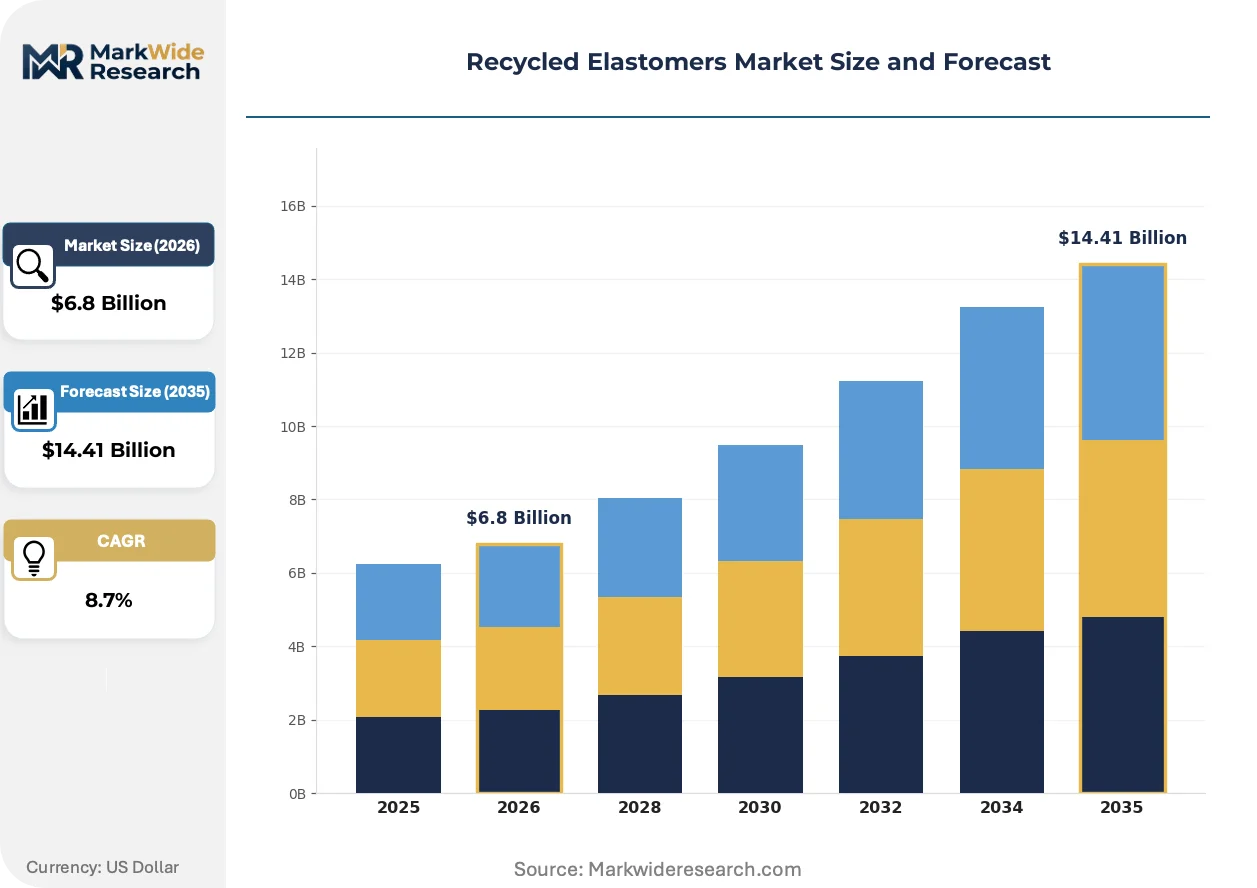
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Elastomers, Styrenic Block Copolymers, Polyurethane Elastomers, Silicone Elastomers Application: Automotive Parts, Industrial Products, Consumer Goods, Construction Materials End User: Manufacturers, Retailers, Construction Firms, Automotive OEMs Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | American Tire Recycling, Monmouth Rubber & Plastics Corp., Liberty Tire Recycling, RubberForm Recycled Products LLC, J. Allcock & Sons Limited, GRP Ltd., West Coast Rubber Recycling, Green Rubber Global, Genan Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Elastomers Market Emerging Trajectories
Mechanochemical devulcanization paired with real-time rheology monitoring is collapsing the traditional trade-off between recycled content rates and batch consistency, enabling compounders to specify post-consumer grades for performance-critical applications.
Continuous shear reactor devulcanization is overtaking batch autoclave methods in commercial tire recycling operations. The technology breaks sulfur crosslinks through controlled mechanical energy input rather than thermal degradation, preserving molecular weight distribution for automotive hose and belt compounds. German compounders serving the Rhine-Ruhr automotive cluster are adopting this approach to meet OEM sustainability scorecard requirements without sacrificing fatigue resistance specifications.
REACH restriction proposals on polycyclic aromatic hydrocarbons in recovered carbon black are tightening impurity thresholds for tire-derived filler materials. The regulatory pressure is forcing pyrolysis operators to invest in secondary vapor-phase treatment systems, raising capital intensity for new plant commissioning. Tire manufacturers in Italy and Spain are responding by accelerating qualification of alternative recovered carbon black sources from industrial rubber scrap rather than end-of-life tires.
Automotive procurement teams are consolidating supplier panels around vertically integrated recyclers capable of certifying cradle-to-gate carbon footprints. The consolidation is displacing fragmented brokers who previously aggregated crumb rubber from multiple grinding operations without chain-of-custody documentation. This pattern is most visible in Germany, where BMW and Mercedes-Benz supplier development programs now require tier-1 rubber processors to demonstrate direct feedstock partnerships with licensed tire collection schemes.
Recycled Elastomers Market Segmentation
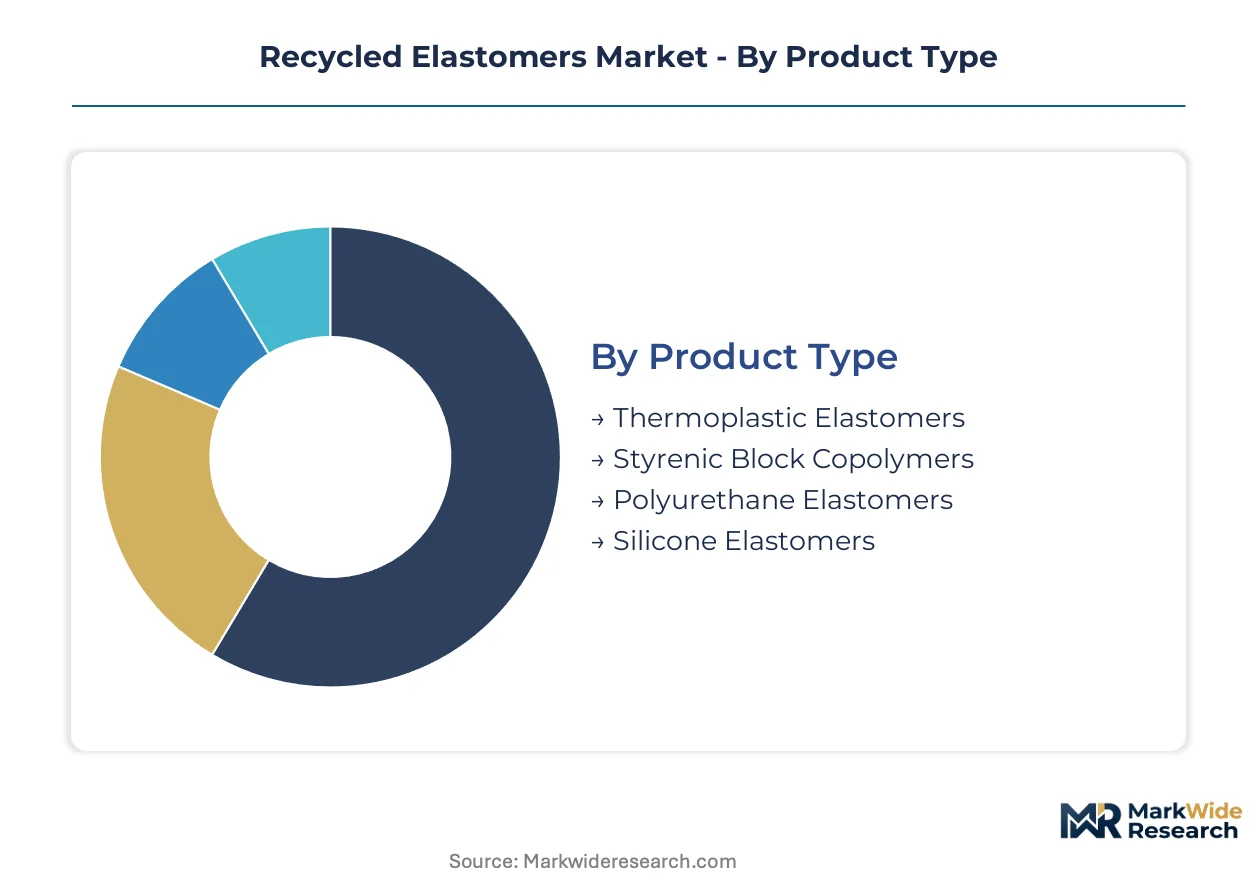
Recycled elastomer procurement patterns diverge sharply across customer types, with automotive OEMs demanding certified post-consumer grades while construction firms prioritize cost-adjusted volume. Understanding these segment-specific qualification requirements and price sensitivity profiles enables suppliers to align grinding technology investments with addressable margin pools.
Product Type:
Thermoplastic elastomers attract compounders seeking injection molding compatibility without devulcanization overhead, while silicone recyclers target premium medical and aerospace niches demanding heat resistance documentation.
- Thermoplastic Elastomers:These materials reprocess through conventional extrusion without sulfur bond scission, preserving polymer integrity for automotive under-the-hood components. German compounders serving BMW and Volkswagen procurement scorecards specify TPE grades for air duct and grommet applications where 30% post-consumer content minimums now apply.
- Styrenic Block Copolymers:SBCs offer broad compatibility with existing styrenic processing infrastructure and cleaner separation from contaminants during cryogenic grinding. Demand concentrates in footwear midsole and adhesive formulations where LEED v4.1 recycled content points drive specification shifts in US commercial construction.
- Polyurethane Elastomers:Industrial scrap from mining and material handling equipment supplies this segment.
- Silicone Elastomers:Medical device and aerospace manufacturers source certified cleanroom-recovered grades at substantial premiums.
Thermoplastic elastomers lead volumes today; silicone elastomers are gaining share fastest.
Application:
Application selection determines whether recycled content serves functional load-bearing roles or cosmetic sustainability claims, with automotive and construction representing opposing ends of this performance-certification spectrum.
- Automotive Parts:Under-the-hood hoses, belts, and grommets require devulcanized EPDM and NBR meeting OEM fatigue resistance specifications. Tier-1 suppliers to Rhine-Ruhr automakers now face binding recycled content minimums that pull post-consumer grades into specification windows previously reserved for virgin material.
- Construction Materials:Crumb rubber modified bitumen for highway surfacing and roofing membranes dominates volume consumption. India's national highway expansion in Maharashtra and Gujarat has adopted CRMB specifications, opening import demand for cryogenically processed European material.
- Industrial Products:Conveyor belts, gaskets, and anti-vibration mounts absorb steady volumes from compounders.
- Consumer Goods:Sporting surfaces and playground tiles represent price-sensitive, specification-flexible demand.
Construction materials lead volumes today; automotive parts are expanding most quickly.
End User:
End user type dictates contract structure, with automotive OEMs demanding multi-year qualification commitments while construction firms transact on spot-indexed crumb rubber pricing.
- Automotive OEMs:BMW and Mercedes-Benz supplier development programs require tier-1 rubber processors to demonstrate direct feedstock partnerships with licensed tire collection schemes. These manufacturers consolidate supplier panels around vertically integrated recyclers capable of certifying cradle-to-gate carbon footprints.
- Construction Firms:Commercial roofing membrane specifiers respond to LEED v4.1 and BREEAM point systems for recycled content, pushing post-consumer EPDM compounds for membrane and flashing applications across German and French building projects.
- Manufacturers:Industrial compounders serving diverse end-markets aggregate demand across multiple specification tiers.
- Retailers:Sports surfacing and home improvement channels move lower-specification crumb rubber products.
Construction firms lead volumes today; automotive OEMs are climbing the fastest.
Distribution Channel:
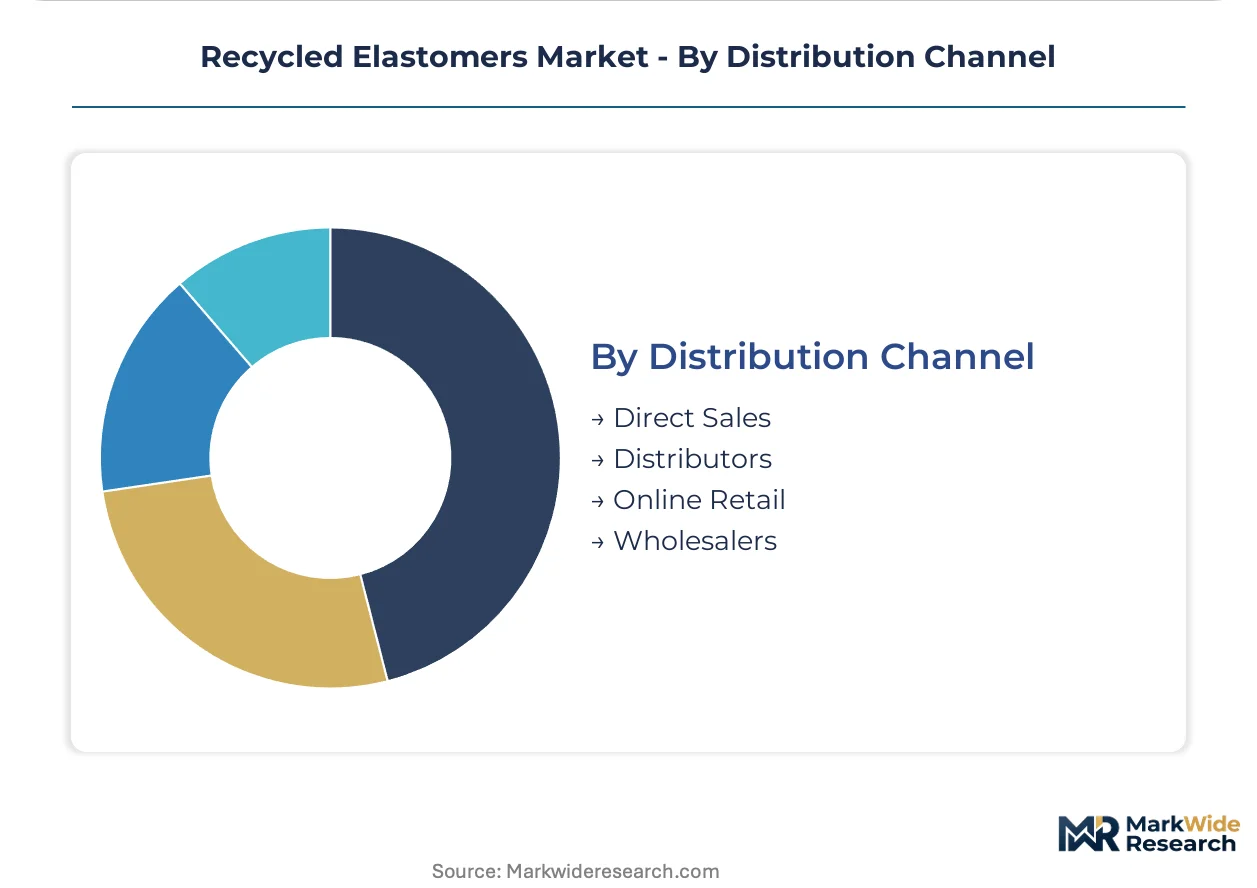
Channel selection reflects customer scale and specification complexity, with direct sales capturing qualified automotive volume while distributors aggregate fragmented construction demand.
- Direct Sales:Automotive OEMs and tier-1 compounders negotiate long-term offtake agreements with cryogenic grinding operators in Denmark and Germany. These arrangements lock in particle size distribution variance below 5% for asphalt modification and molded product specifications.
- Distributors:Regional aggregators serve mid-sized construction firms and industrial manufacturers without direct procurement infrastructure, bridging fragmented demand to Liberty Tire Recycling's North American collection network.
- Online Retail:Small-volume buyers source standardized crumb rubber grades for DIY and specialty applications.
- Wholesalers:Bulk material handlers move commodity-grade tire-derived crumb for non-specified fill applications.
Direct sales lead volumes today; distributor channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled elastomer processing scaled from post-war industrial scrap recovery in Germany's Ruhr Valley, spreading through European tire collection networks and North American waste management infrastructure over subsequent decades.
Germany
Rhine-Ruhr automotive compounders source devulcanized EPDM for BMW and Volkswagen procurement scorecards. The EU Green Deal's extended producer responsibility framework diverts scrap tire volumes toward qualified crumb rubber processors. Cryogenic grinding facilities in Denmark and Germany have cut particle size distribution variance below 5% for asphalt modification specifications.
United States
California and Texas mandate recycled content minimums for public works projects, pulling crumb rubber into highway surfacing specifications. The US EPA oversees scrap tire stockpile reduction programs while state-level regulations create demand anchors. Liberty Tire Recycling leverages its North American collection network to anchor supply security for asphalt modification and molded products.
India
National highway expansion programs in Maharashtra and Gujarat are adopting crumb rubber modified bitumen specifications, opening import demand for cryogenically processed material from European exporters. The country's national infrastructure regulator has incorporated recycled elastomer content into road construction standards. Mumbai-Pune expressway projects now specify imported European crumb rubber for durability testing.
France
Commercial roofing membrane specifiers respond to LEED v4.1 and BREEAM point systems for recycled content, pushing post-consumer EPDM compounds for membrane and flashing applications across Paris and Lyon building projects. The EU F-Gas Regulation indirectly shapes elastomer recycling economics by restricting certain virgin polymer chemistries. Lyon-based construction firms now require tier-1 suppliers to demonstrate cradle-to-gate carbon footprints.
Italy
Tire manufacturers in Italy and Spain are accelerating qualification of alternative recovered carbon black sources from industrial rubber scrap rather than end-of-life tires. REACH restriction proposals on polycyclic aromatic hydrocarbons in recovered carbon black are tightening impurity thresholds. Milan-Turin industrial corridor compounders now source devulcanized material from licensed tire collection schemes to meet automotive OEM requirements.
Recycled Elastomers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and vertical integration dimensions. The vendor base organizes around three strategic tiers: vertically integrated collectors with cryogenic grinding capabilities, specialized compounders serving automotive qualification windows, and regional distributors aggregating construction-grade crumb rubber. Consolidation pressures favor operators with direct feedstock partnerships and chain-of-custody documentation systems. Two dominant competitive moves are reshaping positioning: backward integration into licensed tire collection schemes, and technology licensing for continuous shear reactor devulcanization.
Within the vertically integrated tier, Genan Holding and Liberty Tire Recycling exemplify scale-driven positioning through automated processing infrastructure and collection network density. American Tire Recycling occupies a defensible niche position against commodity-oriented competitors. These three anchors represent distinct archetypes—European cryogenic grinding leadership, North American collection network dominance, and specialty sports surfacing focus—illustrating how geographic origin and company structure shape strategic options without guaranteeing segment capture.
| Leading Market Players |
|---|
| American Tire Recycling |
| Monmouth Rubber & Plastics Corp. |
| Liberty Tire Recycling |
| RubberForm Recycled Products LLC |
| J. Allcock & Sons Limited |
| GRP Ltd. |
| West Coast Rubber Recycling |
| Green Rubber Global |
| Genan Holding |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement scorecards mandating recycled content minimums for under-the-hood components are forcing compounders to secure certified post-consumer feedstock, compressing margins for processors lacking direct tire collection partnerships while elevating premiums for chain-of-custody documentation.
Pricing Analysis
Contract-based long-term offtake agreements dominate automotive procurement, with price differentiation driven by certification grade and volume scale. Three-tier pricing structure across premium, standard, and economy levels separates devulcanized EPDM with OEM qualification from unclassified crumb rubber. Cost compression in standard grades is intensifying because natural rubber price volatility inverts substitution economics periodically. Construction firms exhibit highest price sensitivity, while medical device manufacturers accept substantial premiums for cleanroom-recovered silicone grades.
Supply Chain Analysis
Scrap tire supply rests on collection network density concentrated in Germany, Denmark, and the United States. Raw material dependencies include end-of-life tires, industrial rubber offcuts, and pyrolysis-derived recovered carbon black. Single-source vulnerability runs through North American collection networks dominated by three national operators. Distribution runs through vertically integrated processors serving automotive OEMs directly and regional distributors aggregating construction-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in recycled elastomers hinges on devulcanization technology scale-up reducing unit processing costs and automotive OEMs accepting premium-tier pricing for certified post-consumer grades with full lifecycle traceability.
For Market Incumbents: To counter feedstock security risks from concentrated scrap tire collection networks, secure long-term offtake agreements with licensed tire collection schemes in Germany and Denmark while investing in continuous shear reactor devulcanization capacity to meet OEM qualification timelines. For New Entrants and Emerging Players: Begin with India's infrastructure build-out in Maharashtra and Gujarat, where crumb rubber modified bitumen specifications have opened import demand for cryogenically processed material. Target construction sector green building certifications as the most penetrable entry point, leveraging LEED v4.1 and BREEAM point systems to displace virgin EPDM in commercial roofing membranes. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compounders possessing devulcanization expertise and direct automotive OEM relationships. Long-term viability favors operators with backward integration into tire collection and cryogenic grinding infrastructure. Watch for ECHA decisions on REACH SVHC thresholds for recovered carbon black as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tire Collection | Direct feedstock partnerships with licensed collection schemes in Germany secure supply security for automotive qualification. |
| Continuous Shear Reactor Devulcanization Scale-Up | Mechanochemical processing preserves molecular weight distribution for BMW and Volkswagen fatigue resistance specifications. |
| Crumb Rubber Modified Bitumen Export Capacity | Cryogenic grinding lines meeting India's highway specifications capture infrastructure-driven demand in Maharashtra and Gujarat. |
| Recovered Carbon Black Vapor-Phase Treatment Investment | Secondary treatment systems address REACH PAH restrictions for tire sidewall applications in Italy and Spain. |
| Automotive OEM Direct Partnership Programs | Tier-1 supplier development programs at Mercedes-Benz require cradle-to-gate carbon footprint certification. |
Methodological Framework
Bottom-up automotive and construction demand modeling reconciled against top-down tire collection and processing capacity tracking forms the analytical core. Primary interviews with tire collection network operators, compounder procurement leads, automotive Tier-1 supplier development managers, and cryogenic grinding facility engineers combined with secondary validation from customs trade data, EU Green Deal implementation reports, EPA scrap tire stockpile databases, and ECHA substance evaluation timelines. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of devulcanization technology adoption rates and crumb rubber modified bitumen specification spreads informed projection parameters across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with regional production hub clustering as an additional industry-specific dimension. CAGRs derived from elasticity-adjusted demand curves incorporating OEM qualification timeline compression and infrastructure program rollout schedules.
Several conditions sit outside the modeled scope, including natural rubber futures price volatility beyond historical bands, unilateral REACH restriction accelerations on polycyclic aromatic hydrocarbons, and breakthrough devulcanization chemistry displacing mechanical methods. Forecasts reflect assumptions about regulatory stability and technology cost curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Plated Hose Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Snap on Rubber Stopper Market
Rubber
Liquid Silicone Rubber Market
Rubber
Rubber Chemicals Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Rubber Roller Cleaner Market
Rubber
Rubber Molding Market
Rubber
Tire and Rubber Lubricants Market
Rubber
FKM Elastomers Market
Rubber
US Nitrile Gloves Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Europe Silicone Rubber Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Rubber Reinforcing Chemicals Market