
 Ethylene Bis Stearamide Market | 2026-2036
Ethylene Bis Stearamide Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Bis Stearamide Market Intelligence
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct procurement relationships between EBS manufacturers and large polymer compounders. Croda International plc leverages its oleochemical expertise to sustain backward integration into vegetable-derived feedstocks. BASF anchors its position through integrated production networks spanning Ludwigshafen and Asian manufacturing hubs. PMC Biogenix Inc. competes on specialized grades for FDA-regulated food packaging applications.
Ethylene bis stearamide is a synthetic wax formed from the amidation of ethylenediamine with stearic acid, exhibiting a melting point near 140-145°C and serving primarily as a lubricant, release agent, and dispersant in polymer processing. The plastics application segment dominates volume consumption as EBS functions as an internal and external lubricant in PVC, polyolefin, and engineering resin compounding. Powder form leads current shipments due to ease of dry blending in extrusion operations, while granule and pellet formats gain traction in automated feeding systems at large compounding facilities.
REACH registration requirements in Europe and FDA food-contact substance notifications in the United States impose purity and migration testing burdens that favor suppliers with certified analytical capabilities. China's GB standards for food-contact additives and SAMR oversight of chemical imports create additional compliance layers for market participants. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with evolving substance restrictions and notification pathways.
Market Dynamics
REACH registration requirements and FDA food-contact substance notifications are compressing supplier margins while fragmenting the vendor base into certified analytical laboratories versus commodity traders.
Growth Catalysts
- Automotive lightweighting mandates:Polymer compounding for interior and under-hood components consumes EBS as an internal lubricant in glass-filled nylon and polypropylene formulations. OEM specifications in Germany and Japan now require processing aids that reduce melt viscosity without thermal degradation.
- REACH compliance deadlines:European chemical registrants face substance evaluation triggers that favor EBS grades with full analytical dossiers over unregistered alternatives. This regulatory filter consolidates procurement toward REACH-registered suppliers.
- PVC extrusion automation:Automated feeding systems at large compounding facilities in China and the United States are driving specification shifts toward pelletized EBS formats that minimize dust exposure and dosing variance.
Market Restraints
- Stearic acid feedstock volatility:Vegetable oil price swings—particularly palm and tallow derivatives—transmit directly into EBS manufacturing economics. Oleochemical supply concentration in Southeast Asia amplifies this exposure.
- Substitution by metallic stearates:Calcium and zinc stearate alternatives compete on price in non-food-contact PVC applications where thermal stability requirements are less stringent.
- REACH authorization thresholds:The European Chemicals Agency's substance of very high concern candidate list creates notification burdens for EBS derivatives containing residual ethylenediamine impurities above 0.1% w/w.
Strategic Opportunities
- India polymer processing expansion:The country's PLI scheme for specialty chemicals and domestic compounding capacity build-out creates first-mover positioning for EBS suppliers establishing local technical service presence.
- Bio-based feedstock certification:ISCC PLUS and RSB certification pathways enable premium positioning for EBS manufactured from renewable stearic acid streams, accessing brand-owner sustainability procurement criteria.
- Medical device polymer compounding:USP Class VI and ISO 10993 biocompatibility testing protocols for implant-grade polymers represent a white-space application segment with limited incumbent supply.
Industry Challenges
- Analytical chemistry talent scarcity:Migration testing for food-contact compliance requires gas chromatography-mass spectrometry and liquid chromatography expertise that competes with pharmaceutical and environmental laboratory hiring pools.
- Multi-jurisdiction dossier maintenance:Simultaneous REACH, FDA FCN, and China GB standard alignment demands dedicated regulatory affairs capacity that mid-scale producers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Bis Stearamide Market |
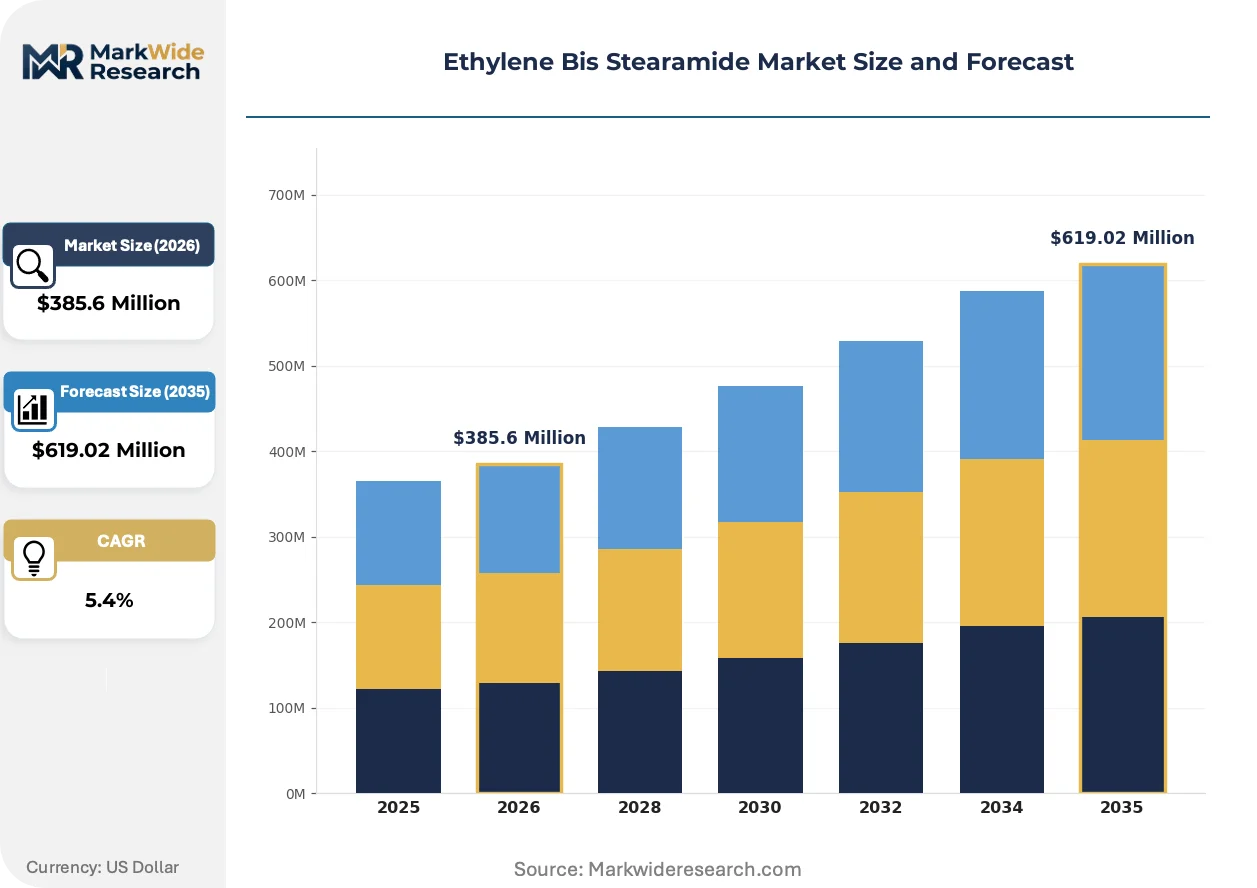
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Plastics, Lubricants, Additives End Use Industry: Food Packaging, Pharmaceuticals, Cosmetics, Automotive Application: Release Agents, Processing Aids, Surface Modifiers, Anti-Fogging Agents Form: Powder, Granules, Paste, Pellets |
| Companies Covered | Croda International plc, BASF, PMC Biogenix Inc., DEUREX AG, KLK OLEO, Kao Corporation, Sinwon Chemical Co., Ltd., BassTech International, Tarak Chemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Bis Stearamide Market Strategic Shifts & Innovations
Formulation science and regulatory analytics are converging to redefine how EBS grades are specified, tested, and procured across polymer processing value chains.
Micro-pelletization technology with controlled particle size distribution below 500 microns is rendering obsolete traditional powder grades in automated compounding operations. Tier-one automotive suppliers in Germany and Japan have completed specification conversions for interior trim compounds. The technology compresses dosing equipment maintenance cycles while eliminating dust containment capital expenditure.
China's GB 4806.7-2016 food-contact plastics standard and SAMR import inspection protocols are tightening purity specifications for amide additives. Domestic compounders serving dairy and beverage packaging now require Certificate of Analysis documentation for every lot. This regulatory layer favors suppliers with in-house migration testing capability over traders reliant on third-party laboratories.
Direct procurement relationships between EBS manufacturers and large polymer compounders are displacing traditional specialty chemical distribution in North America and Western Europe. Regional distributors lose volume share as BASF, Croda, and PMC Biogenix establish account-specific technical service teams. The channel compression is most visible in automotive and medical device verticals where formulation confidentiality requirements override distributor inventory convenience.
Ethylene Bis Stearamide Market Segmentation
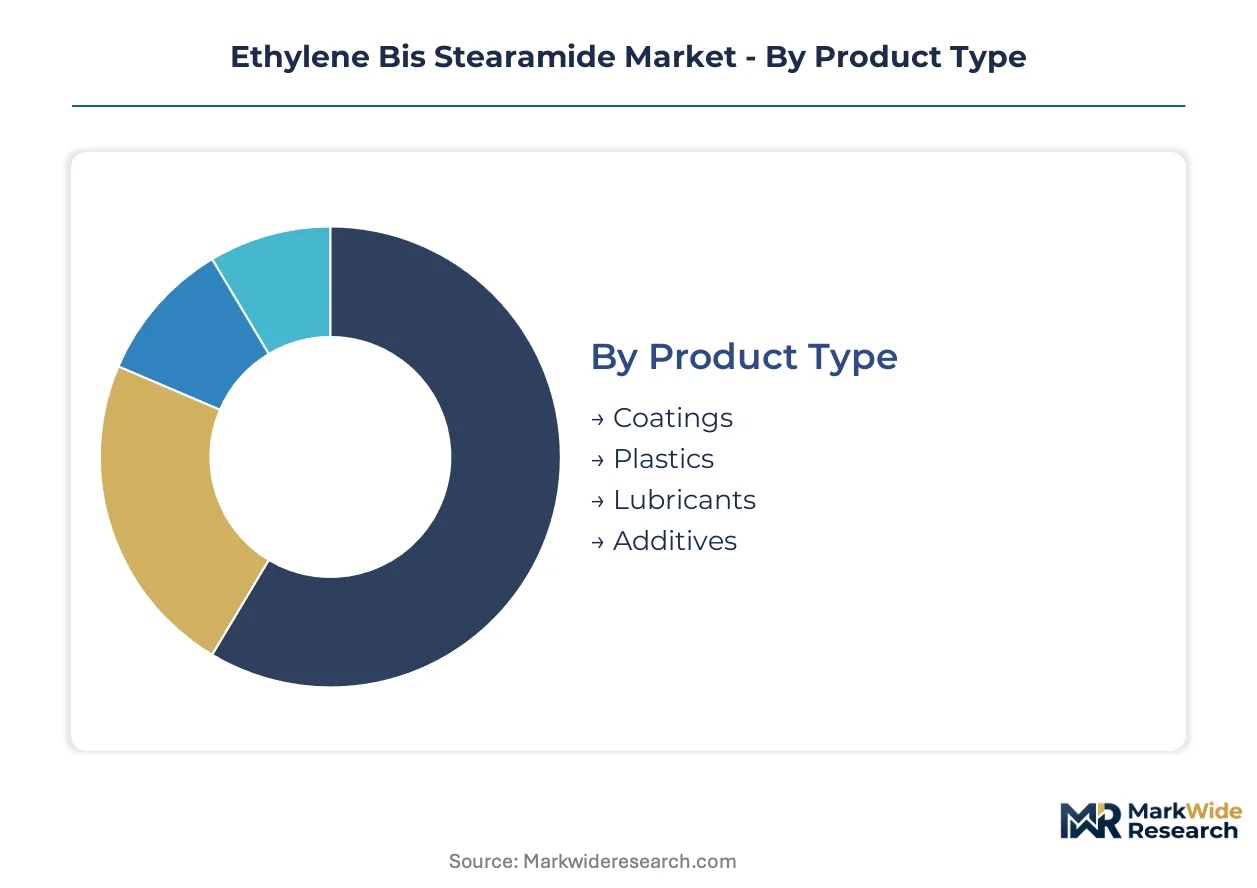
EBS grade specification varies sharply across polymer processing workflows, food-contact compliance tiers, and automated feeding infrastructure. Procurement teams segment supply by regulatory certification depth rather than commodity chemistry alone.
Product Type:
Mature industrial lubricant applications anchor volume, while emerging additive specializations command formulation premiums.
- Plastics:EBS functions as an internal and external lubricant in PVC, polyolefin, and engineering resin compounding. Automotive lightweighting programs in Germany and Japan specify these grades for glass-filled nylon and polypropylene formulations that reduce melt viscosity without thermal degradation.
- Additives:Specialized grades incorporate dispersion aids and compatibility boosters for masterbatch production. China's domestic polymer processing clusters are scaling consumption fastest as regional compounding capacity expands to serve packaging and automotive OEMs.
- Coatings:Surface finishing applications leverage EBS for scratch resistance and gloss control in industrial paints.
- Lubricants:Metalworking and textile processing utilize standard-grade EBS for friction reduction in high-temperature operations.
Plastics retains volume leadership; Additives holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity packaging from premium medical and cosmetic applications demanding certified purity dossiers.
- Automotive:Under-hood and interior trim components require EBS grades that maintain processing stability across recycled content blends. OEM specifications from German and Japanese manufacturers now mandate REACH-registered processing aids with full analytical documentation.
- Food Packaging:FDA food-contact substance notifications and China GB 4806.7-2016 compliance impose migration testing burdens that favor suppliers with in-house gas chromatography-mass spectrometry capability. Dairy and beverage packaging compounders require Certificate of Analysis documentation for every lot.
- Pharmaceuticals:Tablet coating and capsule lubrication applications demand USP-grade purity with residual ethylenediamine controls below 0.1% w/w.
- Cosmetics:Emulsion stabilizers and texture modifiers in personal care formulations utilize vegetable-derived EBS with ISCC PLUS certification for brand-owner sustainability procurement criteria.
Automotive commands the largest volume position; Food Packaging is expanding most quickly as Asia-Pacific regulatory alignment accelerates.
Application:
Customer type bifurcation distinguishes commodity processors seeking cost efficiency from specialty compounders requiring technical service integration.
- Processing Aids:Melt flow modifiers and viscosity reducers dominate extrusion and injection molding operations. Large compounding facilities in China and the United States are driving specification shifts toward pelletized formats that minimize dust exposure in automated feeding systems.
- Release Agents:Mold release formulations for rubber and plastics processing require consistent particle size distribution to prevent surface defects. Tier-one automotive suppliers in Germany have completed specification conversions to micro-pelletized grades below 500 microns.
- Surface Modifiers:Gloss control and scratch resistance applications in industrial coatings utilize standard powder grades.
- Anti-Fogging Agents:Agricultural film and food packaging applications leverage EBS amphiphilic properties to prevent moisture condensation.
Processing Aids maintains the broadest installed base; Release Agents is gaining share fastest through automotive specification upgrades.
Form:
Supply concentration in automated compounding corridors is reconfiguring physical format demand toward dust-free, precision-dosed alternatives.
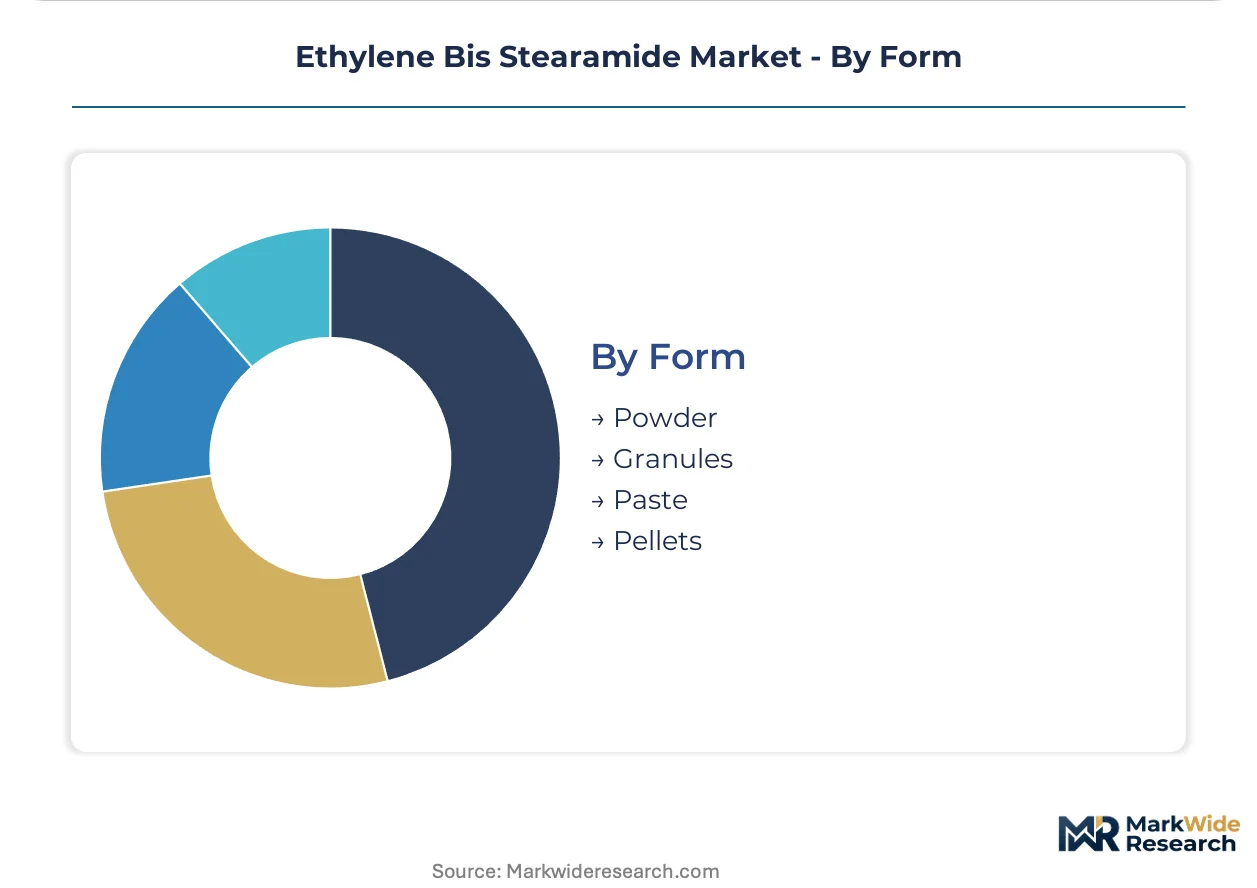
- Powder:Traditional dry-blending operations in extrusion compounding still consume significant volume, though dust containment capital expenditure and dosing variance drive conversion toward alternative formats.
- Pellets:Automated feeding systems at large compounding facilities require uniform particle geometry for consistent metering. Micro-pelletization technology below 500 microns eliminates dust containment requirements while compressing equipment maintenance cycles.
- Granules:Intermediate particle size formats serve regional compounders with semi-automated processing lines.
- Paste:Pre-dispersed liquid concentrates target specialized coating and cosmetic formulations requiring immediate incorporation.
Powder retains the largest installed base; Pellets is climbing the fastest as automation penetrates automotive and packaging verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive compounders while Chinese processors extract cost efficiencies from scaled domestic additive production. This asymmetry reshapes procurement negotiations across polymer value chains. Regulatory divergence between REACH-registered European suppliers and GB-standard Chinese producers widens specification premiums.
China
Domestic EBS production scales rapidly to serve Yangtze River Delta polymer processing clusters. SAMR oversight of chemical imports and GB 4806.7-2016 food-contact standards tighten purity documentation requirements. Regional compounders in Jiangsu and Zhejiang provinces now demand Certificate of Analysis for every lot serving dairy packaging applications.
Germany
Automotive OEM specifications from BMW and Volkswagen mandate REACH-registered processing aids with full analytical dossiers. ECHA substance evaluation triggers favor EBS grades with complete registration data over unregistered alternatives. Ludwigshafen and surrounding chemical parks anchor integrated production networks serving tier-one interior trim suppliers.
United States
FDA food-contact substance notifications impose migration testing burdens that consolidate procurement toward certified analytical laboratories. Midwest compounding facilities in Ohio and Michigan drive specification shifts toward pelletized EBS formats for automated feeding systems. PMC Biogenix anchors specialized supply for regulated food packaging verticals.
India
The PLI scheme for specialty chemicals and domestic compounding capacity build-out creates positioning opportunities for technical service presence. Maharashtra and Gujarat polymer processing clusters scale fastest as regional automotive and packaging demand expands. First-mover suppliers establish local analytical capability to serve BIS-aligned certification requirements.
Japan
METI industrial standards and automotive OEM specifications from Toyota and Honda require processing stability across recycled content blends. Kansai and Chubu regional compounders specify EBS grades that reduce melt viscosity without thermal degradation in glass-filled nylon formulations. Domestic suppliers leverage JIS standard alignment to defend premium positioning.
Ethylene Bis Stearamide Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in feedstock and certified-grade niches. The vendor base stratifies between integrated oleochemical producers and specialized additive formulators. Three archetypes dominate: backward-integrated feedstock controllers, regulatory-certified grade specialists, and regional scale fabricators. Capacity expansion and direct procurement relationships constitute the dominant competitive moves displacing traditional distribution channels.
Among European-anchored multinationals, Croda International plc exemplifies backward integration into vegetable-derived feedstocks, while BASF occupies a position defined by integrated production networks spanning Ludwigshafen and Asian manufacturing hubs. PMC Biogenix Inc. represents the regulatory-specialist archetype, sitting within the certified-grade tier for FDA-regulated food packaging applications.
| Leading Market Players |
|---|
| Croda International plc |
| BASF |
| PMC Biogenix Inc. |
| DEUREX AG |
| KLK OLEO |
| Kao Corporation |
| Sinwon Chemical Co., Ltd. |
| BassTech International |
| Tarak Chemicals Limited |
| Others |
Cost & Logistics Intelligence
Southeast Asian oleochemical concentration—particularly Malaysian and Indonesian palm oil derivatives—positions feedstock controllers to capture margin pools downstream in REACH-certified grade supply. This upstream geography directly shapes where pricing power concentrates versus where cost compression runs deepest.
Pricing Analysis
The customization-premium spread between FDA food-contact certified grades and standard industrial lubricant tiers runs wide. Pricing stratifies across REACH-registered analytical dossiers, FDA FCN migration-tested lots, and commodity unregistered alternatives. Cost compression in standard industrial grades is intensifying because metallic stearate substitution in non-food PVC erodes volume leverage. Commodity PVC compounders exhibit highest price sensitivity; medical device and food packaging buyers absorb premiums for certified purity documentation.
Supply Chain Analysis
Upstream stearic acid feedstock draws from Malaysian palm oil complexes, Indonesian oleochemical refineries, and tallow rendering operations in North America. Vegetable oil price volatility, ethylenediamine purity specifications, and automated compounding equipment compatibility requirements anchor raw material dependencies. Single-source vulnerability concentrates in Southeast Asian oleochemical supply where climate and trade policy disruptions transmit rapidly. Distribution runs through direct manufacturer-compounder relationships displacing regional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense defines strategic priority as metallic stearate alternatives encroach standard-grade PVC applications. Incumbents must navigate this displacement threat while extracting premium positioning from regulatory-certified segments.
For Market Incumbents: Entrench analytical certification capabilities as a moat against metallic stearate substitution in food-contact and medical segments. Deepen backward integration into vegetable-derived feedstocks to buffer oleochemical price volatility from Southeast Asian supply swings. Anchor direct procurement relationships with tier-one automotive compounders to lock out distributor-mediated competition. For New Entrants and Emerging Players: Establish a beachhead in India's polymer processing expansion where PLI-scaled compounding capacity outruns certified additive supply. Target medical device polymer compounding requiring USP Class VI and ISO 10993 biocompatibility protocols as the most penetrable white-space segment. Lead with local technical service presence rather than price-driven commodity positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors losing share to direct manufacturer relationships. Five-to-ten year viability hinges on regulatory dossier depth rather than volume scale alone. Watch for ECHA substance evaluation triggers that disqualify unregistered suppliers as an inflection signal for consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captures margin from Malaysian and Indonesian oleochemical volatility while securing ISCC PLUS certification pathways. |
| REACH Registration Dossier Expansion | Consolidates procurement toward analytical-capable suppliers as ECHA substance evaluations disqualify unregistered alternatives. |
| Micro-Pelletization Capacity Buildout | Aligns with German and Japanese automotive specification conversions toward sub-500-micron automated feeding formats. |
| Direct Technical Service Deployment | Displaces regional distributors by embedding formulation support teams with tier-one compounders in automotive and medical verticals. |
| India Manufacturing Footprint Establishment | Positions first-mover supply for PLI-scaled polymer processing clusters in Maharashtra and Gujarat. |
Research Approach
Two parallel data streams informed the analysis: primary engagement with polymer processing stakeholders and secondary validation across trade and regulatory sources. Plant managers at compounding facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at additive suppliers contributed operational perspective. Customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR import inspection records supplied external benchmarks. Bottom-up volume modeling triangulated against top-down market sizing.
Forecast inputs encompassed grade tier stratification, end-use industry demand patterns, physical format transitions, and regional production hub evolution across the projection horizon. Segment-level CAGRs derived from installed base conversion rates, regulatory deadline impacts, and automation penetration curves in compounding operations. Stearic acid feedstock price elasticity and REACH registration cost amortization informed margin trajectory assumptions.
Stress conditions across vegetable oil price bands, ECHA evaluation timelines, and FDA FCN approval velocities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory alignment and substitution elasticity. Cross-checking against Cefic polymer additive demand surveys and SAMR chemical import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Global White Oil Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Butyl Stearate Market