
 Recycled PET Market | 2026-2036
Recycled PET Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled PET Market Outlook
Modular bottle-to-bottle recycling configurations is rebalancing procurement decisions across European and North American packaging buyers. Indorama Ventures Public Company Limited leverages its integrated PET resin and recycling footprint to secure long-term supply agreements with multinational beverage brands. Plastipak Holdings Inc. anchors its position through captive flake-to-preform operations in the United States and Brazil. Unifi specializes in fiber-grade rPET for performance apparel, competing on traceability certifications rather than volume scale.
Recycled polyethylene terephthalate consists of post-consumer PET flakes or pellets reprocessed through mechanical or chemical means to achieve specified intrinsic viscosity and contaminant thresholds suitable for food-contact or textile applications. The material serves primarily as a substitute for virgin PET in closed-loop packaging and synthetic fiber production. Bottle-grade rPET commands premium positioning due to FDA and EFSA food-contact compliance requirements, while fiber applications in textiles sustain volume leadership through lower purity thresholds. Chemical recycling methods attract capital despite higher unit costs because they enable infinite-loop regeneration of degraded feedstock, a structural advantage over mechanical routes where thermal history limits reprocessing cycles.
The EU Green Deal mandates minimum recycled content thresholds for plastic packaging, enforced through EFSA food-contact approvals and harmonized EN standards. The EPA and FDA in the United States operate parallel but non-identical frameworks for post-consumer resin clearance, creating compliance complexity for exporters. China's GB standards and SAMR labeling rules shape import specifications for Asian converters. Stakeholders must monitor divergence between chemical recycling eligibility under EU packaging regulations versus mechanical-only preferences emerging in certain US state-level extended producer responsibility proposals.
Market Dynamics
The EU Green Deal packaging rules are compressing supply timelines for food-grade recycled content, forcing beverage brand owners to renegotiate long-term flake and pellet contracts before EFSA compliance deadlines harden in 2030.
Growth Catalysts
- Deposit-return systems:Germany's DRS infrastructure generates the continent's highest collection purity rates, feeding dedicated bottle-to-bottle reprocessing lines with contaminant loads below mechanical recycling thresholds.
- EU Green Deal mandates:Minimum recycled content thresholds for plastic packaging create binding offtake obligations that outpace current food-grade rPET supply capacity.
- Chemical recycling:Depolymerization methods enable infinite-loop regeneration of degraded PET feedstock, bypassing intrinsic viscosity degradation limits that constrain mechanical routes.
Market Restraints
- Feedstock cost volatility:Baled post-consumer PET prices fluctuate with crude oil parity and virgin resin arbitrage, compressing recycler margins when virgin PET dips below rPET parity.
- Collection infrastructure gaps:Southern and Eastern European markets lack harmonized sorting capacity, concentrating quality flake supply in German, Dutch, and Nordic collection zones.
- Mechanical recycling limits:Thermal reprocessing history degrades PET molecular chains, capping food-grade reprocessing cycles at 5-7 iterations before viscosity thresholds fail EFSA clearance.
Strategic Opportunities
- Underpenetrated geographies:Spain and Italy present collection infrastructure buildout opportunities as EU Green Deal enforcement extends beyond early-adopter Nordic and German markets.
- Chemical recycling scale-up:Enzymatic depolymerization and glycolysis investments unlock access to colored, multi-layer, and degraded feedstock currently rejected by mechanical sorters.
- Textile-to-textile circularity:Performance apparel brands are establishing take-back programs that bypass bottle-collection competition entirely, creating dedicated fiber-grade rPET supply chains.
Industry Challenges
- EFSA food-contact certification timelines:Novel recycling process approvals require 18-24 month safety dossier reviews, delaying commercial deployment of upgraded mechanical and chemical technologies.
- Contaminant detection integration:Legacy sorting lines require capital-intensive retrofits to detect and eject non-PET barriers, adhesives, and chemical contaminants at flake purification stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled PET Market |
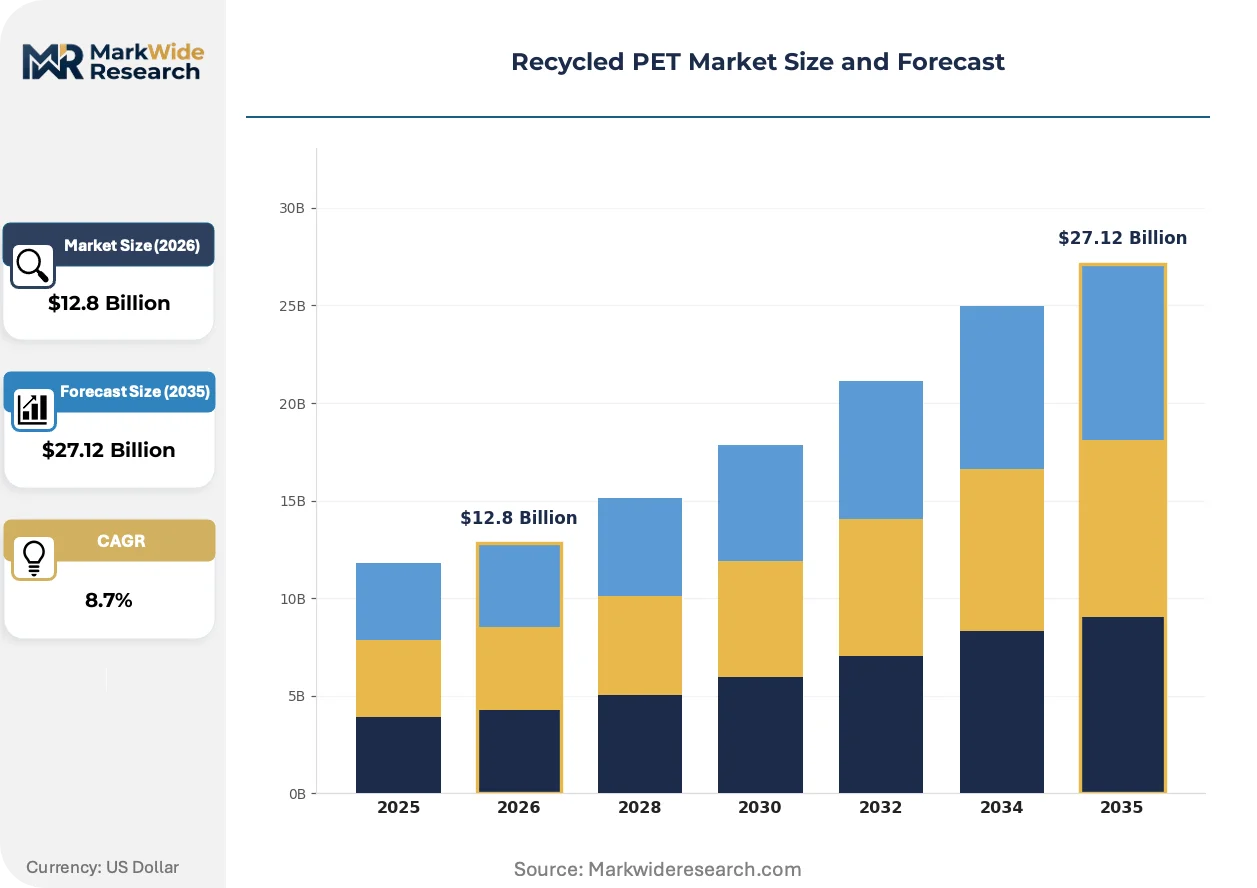
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Sheet, Bottle, Pellets End Use Industry: Textiles, Packaging, Automotive, Construction Recycling Method: Mechanical, Chemical, Thermal, Biological Form: Granules, Flakes, Sheets, Powder |
| Companies Covered | Plastipak Holdings Inc., Evergreen Recycling, Indorama Ventures Public Company Limited, PetStar, Phoenix Technologies International, Far Eastern New Century Corporation, Alpla Group, Unifi, Alpek S.A.B. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled PET Market Strategic Shifts
Technology convergence between chemical recycling and advanced mechanical purification is redrawing competitive boundaries between volume-scale and premium-grade rPET suppliers.
Enzymatic depolymerization is electrifying the technical feasibility of processing heavily contaminated and colored PET streams previously relegated to downcycling. Beverage brand owners with 2030 recycled content commitments are piloting offtake agreements with enzymatic recyclers despite unit cost premiums. This technology is compressing the volume-quality tradeoff that has historically separated food-grade and fiber-grade rPET markets.
EFSA is tightening food-contact safety dossier requirements for novel recycling processes, extending approval timelines for chemical recycling entrants. The industrial consequence is a certification bottleneck that favors incumbent mechanical recyclers with grandfathered clearances. Bottle-grade rPET suppliers with existing EFSA approvals are locking in multiyear supply agreements before new competitors clear regulatory gates.
Brand-owner procurement teams are consolidating supplier relationships around integrated resin-to-recycling partners capable of guaranteeing traceable chain-of-custody documentation. Long-term flake and pellet contracts with fixed-volume escalators are displacing spot-market purchasing for food-grade applications. This pattern concentrates most visibly in Germany, where deposit-return purity standards enable the highest-confidence supply agreements.
Recycled PET Market Segmentation
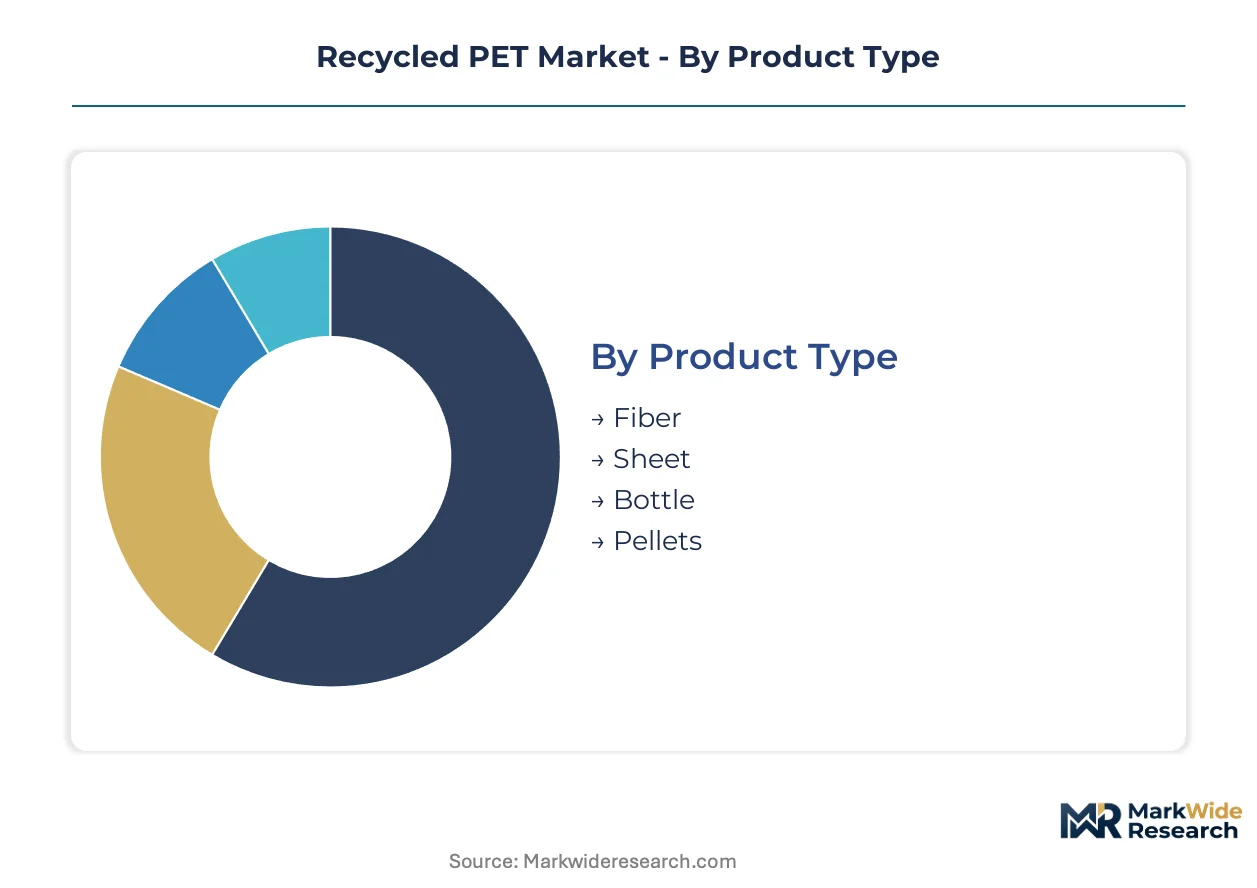
rPET market segmentation reveals a fundamental fracture between high-purity food-contact grades commanding supply premiums and volume-dominant fiber applications absorbing lower-grade feedstock. Procurement strategies diverge sharply across these tiers, with beverage brands paying scarcity premiums for bottle-grade material while textile converters optimize for cost-efficient flake supply.
Product Type:
Bottle-grade material captures the premium tier through EFSA and FDA food-contact compliance burdens, while fiber applications sustain volume leadership through lower purity thresholds and broader feedstock acceptance.
- Bottle:Food-contact grade rPET requires intrinsic viscosity above 0.72 dL/g and contaminant thresholds meeting EFSA safety dossier standards. German deposit-return systems supply the highest-purity feedstock for this segment, with beverage brand procurement teams locking in multiyear offtake agreements ahead of EU Green Deal enforcement.
- Fiber:Textile-grade rPET tolerates lower intrinsic viscosity and broader color variation, enabling mechanical recyclers to process mixed post-consumer bales without chemical purification. Demand concentrates in performance apparel supply chains where Unifi and competing spinners compete on traceability certifications rather than purity metrics.
- Sheet:Thermoformed packaging applications require intermediate purity grades suitable for non-food contact trays and blister packs, positioning this segment between bottle and fiber economics.
- Pellets:Extruded pellet form factors serve compounders and converters seeking standardized feedstock for injection molding operations across automotive and consumer goods applications.
Today's leader: Fiber. Tomorrow's challenger: Bottle.
End Use Industry:
Packaging procurement is accelerating fastest under regulatory mandate pressure, while textile demand maintains structural volume dominance through established mechanical recycling infrastructure.
- Packaging:Beverage bottles, food trays, and cosmetic containers drive food-grade rPET consumption. EU Green Deal minimum recycled content thresholds are compressing supply timelines, forcing brand owners to renegotiate flake and pellet contracts before EFSA compliance deadlines harden.
- Textiles:Synthetic fiber production for apparel, home furnishings, and industrial applications absorbs the largest volume of rPET globally. Lower purity requirements enable broader feedstock sourcing from mixed post-consumer collection streams outside deposit-return systems.
- Automotive:Interior trim, under-hood components, and acoustic insulation utilize rPET for weight reduction and sustainability credentials. OEMs specify flame-retardant and UV-stable grades distinct from packaging applications.
- Construction:Geotextiles, insulation materials, and concrete reinforcement fibers employ rPET for durability and chemical resistance in infrastructure applications.
Packaging is climbing the fastest as regulatory mandates reshape procurement priorities.
Recycling Method:
Mechanical routes dominate current capacity but face intrinsic viscosity degradation limits, while chemical methods attract capital for infinite-loop regeneration despite unit cost premiums.
- Mechanical:Conventional sorting, washing, and reprocessing of post-consumer PET flakes. Thermal history limits food-grade reprocessing cycles to 5-7 iterations before molecular chain degradation fails EFSA clearance thresholds.
- Chemical:Depolymerization through glycolysis or enzymatic processes breaks PET into monomers for virgin-quality repolymerization. Enzymatic recyclers are piloting offtake agreements with beverage brands despite higher costs, enabling processing of colored and degraded feedstock rejected by mechanical sorters.
- Thermal:Pyrolysis and solvolysis methods process contaminated or multi-layer feedstock unsuitable for mechanical routes, yielding intermediate products for downstream purification.
- Biological:Emerging enzymatic and microbial degradation approaches remain pre-commercial, with pilot-scale operations targeting heavily contaminated post-consumer streams.
Mechanical maintains capacity leadership. Chemical represents the technology bet for feedstock flexibility.
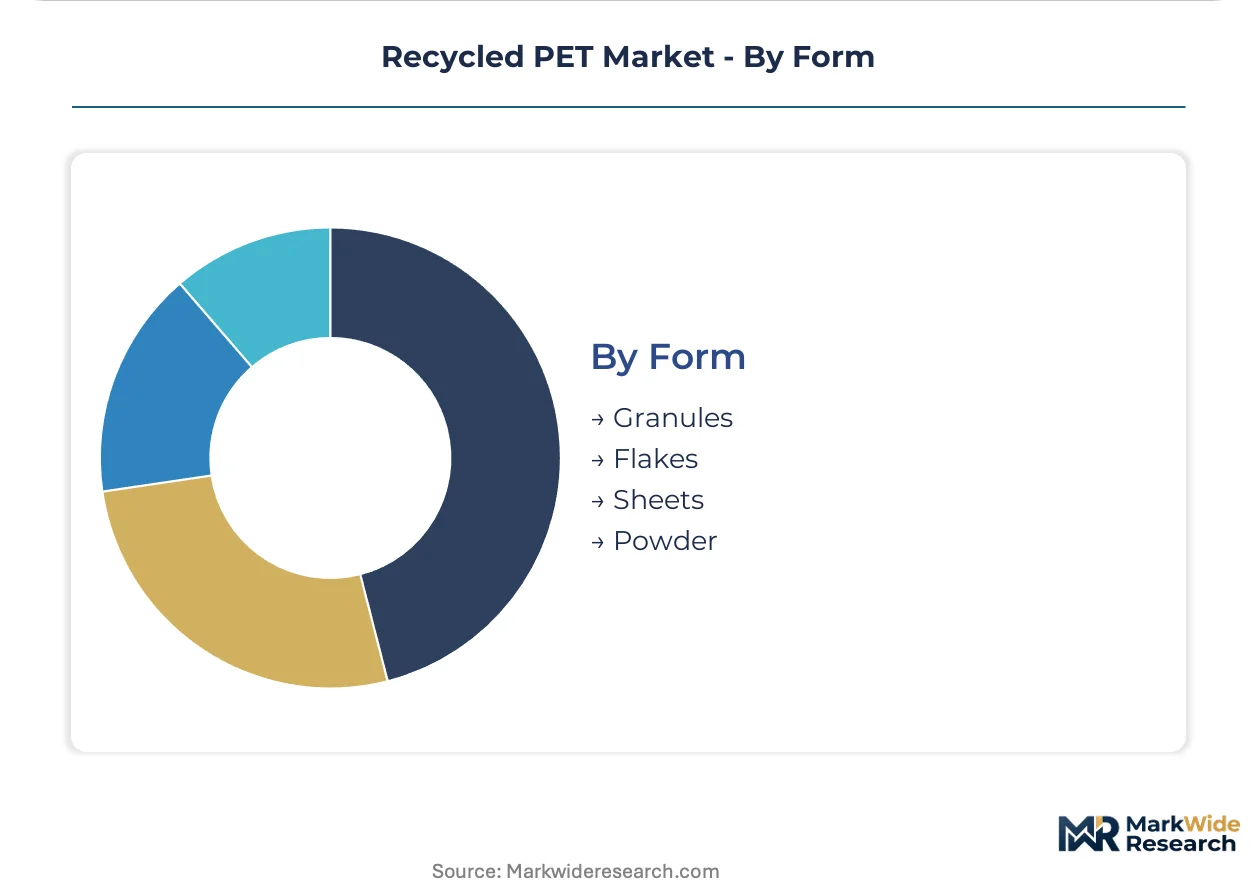
Form:
Flake-to-pellet conversion economics favor integrated recyclers with captive washing and extrusion lines, while powder applications serve niche compounding markets.
- Flakes:Washed and sorted post-consumer PET fragments serve as the primary feedstock for fiber extrusion and sheet production. Collection infrastructure gaps in Southern and Eastern Europe concentrate quality flake supply in German, Dutch, and Nordic zones.
- Granules:Extruded and crystallized pellet form enables standardized handling for injection molders and blow molders requiring consistent melt flow indices. Integrated resin producers leverage captive flake-to-granule operations to secure long-term supply agreements.
- Sheets:Calendered or extruded sheet products serve thermoformers producing trays, clamshells, and blister packaging for non-food applications with intermediate purity requirements.
- Powder:Micronized rPET serves rotational molders and powder coating applications requiring specific particle size distributions for surface finish control.
Flake commands upstream margins. Granules capture downstream value addition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The recycled PET industry traces its industrial-scale origins to Germany's 2003 packaging ordinance, which established the world's first mandatory deposit-return system for polyethylene terephthalate beverage containers. This regulatory innovation created the template for closed-loop bottle-to-bottle recycling that now spreads across industrialized economies.
Germany
Deposit-return infrastructure generates Europe's highest collection purity rates, feeding dedicated reprocessing lines with contaminant loads below mechanical recycling thresholds. EFSA food-contact approvals for German recyclers have hardened into competitive moats as novel process certification timelines extend to 24 months. The Rhineland corridor between Cologne and Düsseldorf concentrates bottle-grade flake production capacity serving multinational beverage procurement teams.
United States
California's recycled content mandates for plastic beverage containers drive procurement urgency among West Coast brand owners. FDA post-consumer resin clearance operates parallel to EPA state authorization frameworks, creating compliance complexity for cross-border suppliers. The Southeast industrial belt from South Carolina to Georgia hosts expanding flake-to-pellet operations targeting Coca-Cola and PepsiCo supply agreements.
China
Dual carbon policy targets accelerate investment in chemical recycling demonstration plants despite mechanical route dominance in current capacity. GB standards and SAMR labeling rules impose stricter contaminant thresholds on imported post-consumer bales than domestic collection streams. The Yangtze River Delta around Shanghai anchors textile-grade rPET production for performance apparel export supply chains.
Japan
METI circular economy roadmaps mandate 50% recycled plastic content in beverage containers by 2030, compressing procurement timelines for domestic converters. JIS standards for food-contact recycled materials diverge from EFSA testing protocols, fragmenting certification requirements for multinational suppliers. The Kansai industrial corridor between Osaka and Kobe hosts integrated resin-to-recycling operations serving Suntory and Kirin procurement specifications.
Brazil
ANVISA pharmaceutical-grade packaging standards create adjacent demand for high-purity rPET in cosmetic and healthcare applications beyond beverage markets. Extended producer responsibility proposals in São Paulo and Rio de Janeiro states remain pre-regulatory, leaving collection infrastructure dependent on voluntary brand-owner programs. The ABC industrial region outside São Paulo concentrates mechanical recycling capacity serving Mercosur packaging converters.
Recycled PET Market Competitive Environment
Premium-margin players sit above commodity-margin players across EFSA certification status, with grandfathered food-contact approvals commanding multiyear supply premiums over novel process entrants. The vendor base stratifies between integrated resin producers with captive flake supply, independent mechanical recyclers with regional collection contracts, and chemical recycling ventures pursuing feedstock flexibility. Three archetypes dominate: deposit-return system operators leveraging purity advantages, textile-grade specialists competing on traceability certification, and petrochemical incumbents backward integrating into recycling capacity. Competitive moves concentrate on long-term offtake locking and regulatory certification racing ahead of EU Green Deal enforcement deadlines.
Within the integrated petrochemical tier, Indorama Ventures Public Company Limited and Alpek S.A.B. de C.V. represent archetypes of upstream resin producers securing downstream recycling capacity through organic expansion and strategic positioning. Among independent mechanical specialists, Unifi occupies a position exemplifying fiber-grade competitors competing on chain-of-custody documentation rather than food-contact purity metrics. Plastipak Holdings Inc. anchors the packaging-integrated archetype through captive flake-to-preform operations serving beverage brand direct procurement channels.
| Leading Market Players |
|---|
| Plastipak Holdings Inc. |
| Evergreen Recycling |
| Indorama Ventures Public Company Limited |
| PetStar |
| Phoenix Technologies International |
| Far Eastern New Century Corporation |
| Alpla Group |
| Unifi |
| Alpek S.A.B. de C.V. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging mandates gate both qualified supply and premium-tier pricing access, compressing procurement timelines as beverage brands race to lock EFSA-certified flake contracts before enforcement deadlines harden. Food-contact grade rPET commands scarcity premiums while fiber-grade material absorbs cost pressure from virgin PET parity swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified bottle-grade from industrial sheet and fiber applications. Price differentiation hinges on contaminant thresholds and chain-of-custody documentation depth. Pricing pressure stems from virgin PET arbitrage compressing recycler margins when crude-linked resin undercuts recycled parity. Small converters in Southern Europe exhibit highest price sensitivity; German beverage multinationals absorb premiums for supply security.
Supply Chain Analysis
Post-consumer bale supply rests on Germany, the Netherlands, and Nordic collection zones where deposit-return infrastructure generates highest purity feedstock. Raw material dependencies include sorted PET bales, caustic soda for washing, and food-grade additives for viscosity restoration. Single-source vulnerability concentrates in German flake purification capacity serving pan-European converters. Distribution runs through integrated resin producers with captive flake-to-pellet operations securing direct brand-owner offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recycled PET market functions as a stable compounder where regulatory mandates create irreversible demand floors regardless of virgin resin price cycles.
For Market Incumbents: Deepen EFSA certification moats by accelerating novel process safety dossiers before approval timelines extend further. Lock multiyear supply agreements with integrated resin partners to defend against chemical recycling entrants. Prioritize backward integration into collection infrastructure in Spain and Italy where EU Green Deal enforcement will outpace local supply buildout. For New Entrants and Emerging Players: Enter via enzymatic depolymerization pilots targeting colored and multi-layer feedstock streams rejected by mechanical sorters. Spain and Italy present the most penetrable geographies given collection infrastructure gaps and impending mandate pressure. Pursue offtake partnerships with performance apparel brands establishing textile-to-textile take-back programs outside bottle-collection competition. For Investors and Strategic Acquirers: Roll-up economics work for regional mechanical recyclers with grandfathered food-contact approvals because EFSA certification bottlenecks prevent rapid competitive entry. The 5-10 year viability window favors targets with established brand-owner relationships and deposit-return system access. Watch enzymatic recycling pilot scale-up rates as the inflection signal for feedstock flexibility disruption.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Certification Investment | Grandfathered approvals command multiyear supply premiums over novel process entrants awaiting 24-month dossier reviews. |
| Collection Infrastructure Buildout | Southern European expansion captures EU Green Deal enforcement extending beyond German and Nordic early-adopter markets. |
| Chemical Recycling Scale-Up | Enzymatic depolymerization unlocks colored and degraded feedstock streams currently relegated to downcycling. |
| Long-Term Offtake Agreements | Fixed-volume escalators displace spot purchasing as beverage brands secure supply ahead of compliance deadlines. |
| Textile-to-Textile Circularity | Performance apparel take-back programs bypass bottle-collection competition entirely for dedicated fiber-grade supply chains. |
Study Parameters
Coverage spans Germany, the United States, China, and Japan, with primary inputs from each market cluster combining interviews with recycling plant managers, beverage procurement leads, EFSA regulatory affairs specialists, and textile spinning technical directors. Secondary validation drew from EU Green Deal implementation documents, FDA post-consumer resin guidance, customs trade data on PET bale flows, and SEC filings of integrated resin producers. Bottom-up capacity modeling triangulated against top-down demand projections from packaging and textile end-use analysis.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product grade tier, recycling method, end-use industry, and regional regulatory cluster. CAGRs derived from installed capacity buildout schedules, mandate enforcement calendars, and substitution elasticity estimates between virgin and recycled resin. Industry-specific forecast inputs included EFSA approval pipeline tracking and deposit-return system expansion announcements.
The model holds under steady EU Green Deal enforcement timelines and stable crude oil parity ranges; deviation in chemical recycling cost curves or virgin PET supply disruptions would shift trajectory assumptions. A small set of triggers—enzymatic scale-up rates, Southern European collection buildout pace, and EFSA process approval delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
India Plastic Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Global Recycled Base Oil Market