
 North America Plastic Recycling Market | 2026-2036
North America Plastic Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Recycling Market Intelligence
Food-grade rPET specification tiers is collapsing the price premium between virgin and recycled polyethylene terephthalate across beverage bottling supply chains. KW Plastics anchors North American HDPE recycling through its Troy, Alabama reprocessing complex. Avangard Innovative leverages film recovery networks across Texas and Mexico to sustain bale supply for downstream pelletizers. Ultra-Poly Corporation specializes in industrial scrap conversion, occupying a defensible niche in automotive bumper reclaim.
North America plastic recycling encompasses the collection, sorting, cleaning, and reprocessing of post-industrial and post-consumer thermoplastic waste into resin suitable for re-extrusion or molding, with melt-flow indices and contamination thresholds varying by end-use application. The practice diverts polymer waste from landfill and energy recovery while reducing virgin petrochemical feedstock demand across durable and nondurable goods manufacturing. Mechanical recycling dominates current throughput volumes, though chemical recycling is capturing margin pools from difficult-to-process multi-layer films and degraded polyolefins. PET retains the largest share of curbside-derived tonnage due to established beverage container deposit frameworks, while HDPE grows fastest in non-bottle applications including pipe and decking. Packaging end-use absorbs the majority of recycled resin offtake, though automotive specifications are tightening for interior trim content minimums.
The EPA administers recycled-content procurement standards under the Resource Conservation and Recovery Act, while state-level extended producer responsibility frameworks in California, Oregon, and Colorado reshape collection infrastructure economics. The FDA issues letters of no objection for food-contact recycled plastics, conditioning market access for rPET into beverage and food packaging. Stakeholders must monitor chemical recycling facility permitting under the Clean Air Act as capacity announcements outpace operational commissioning timelines.
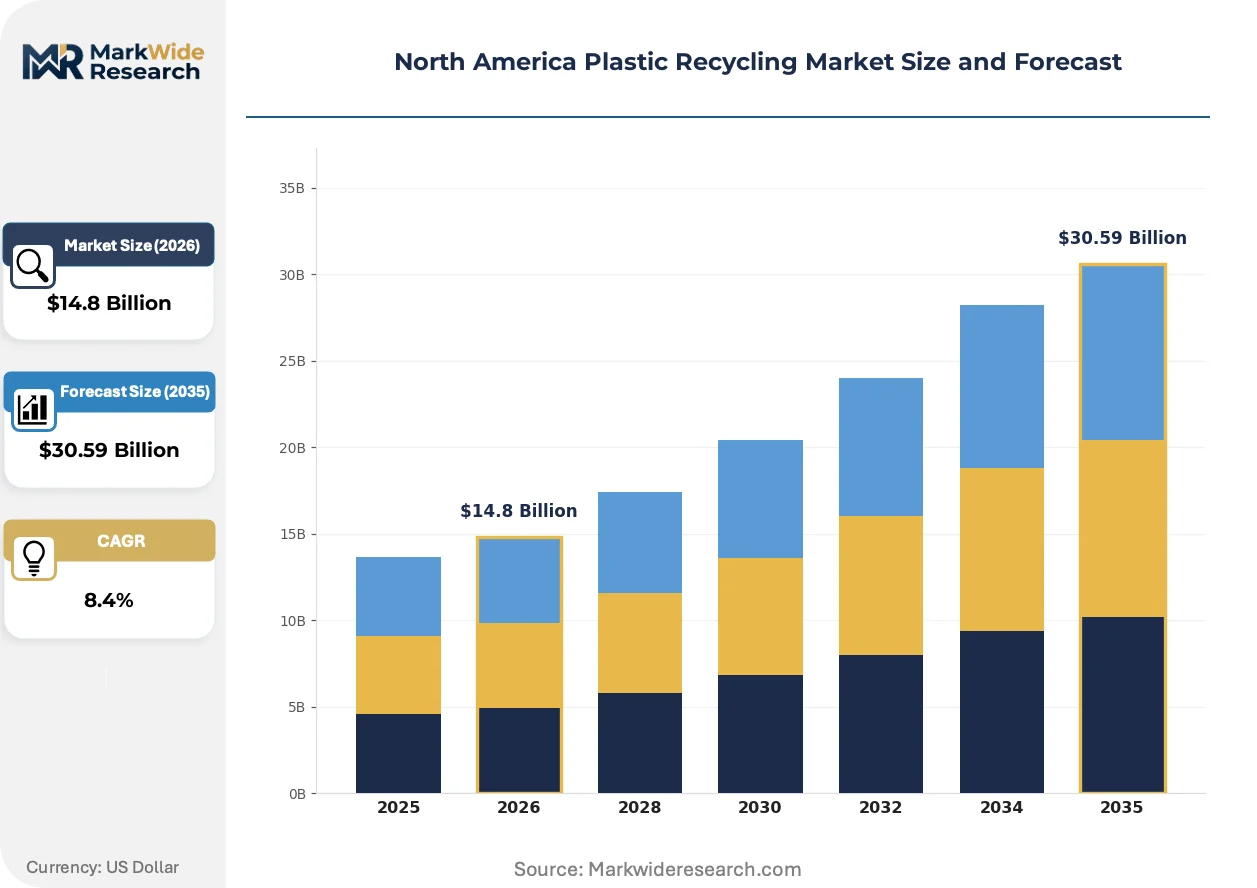
Market Dynamics
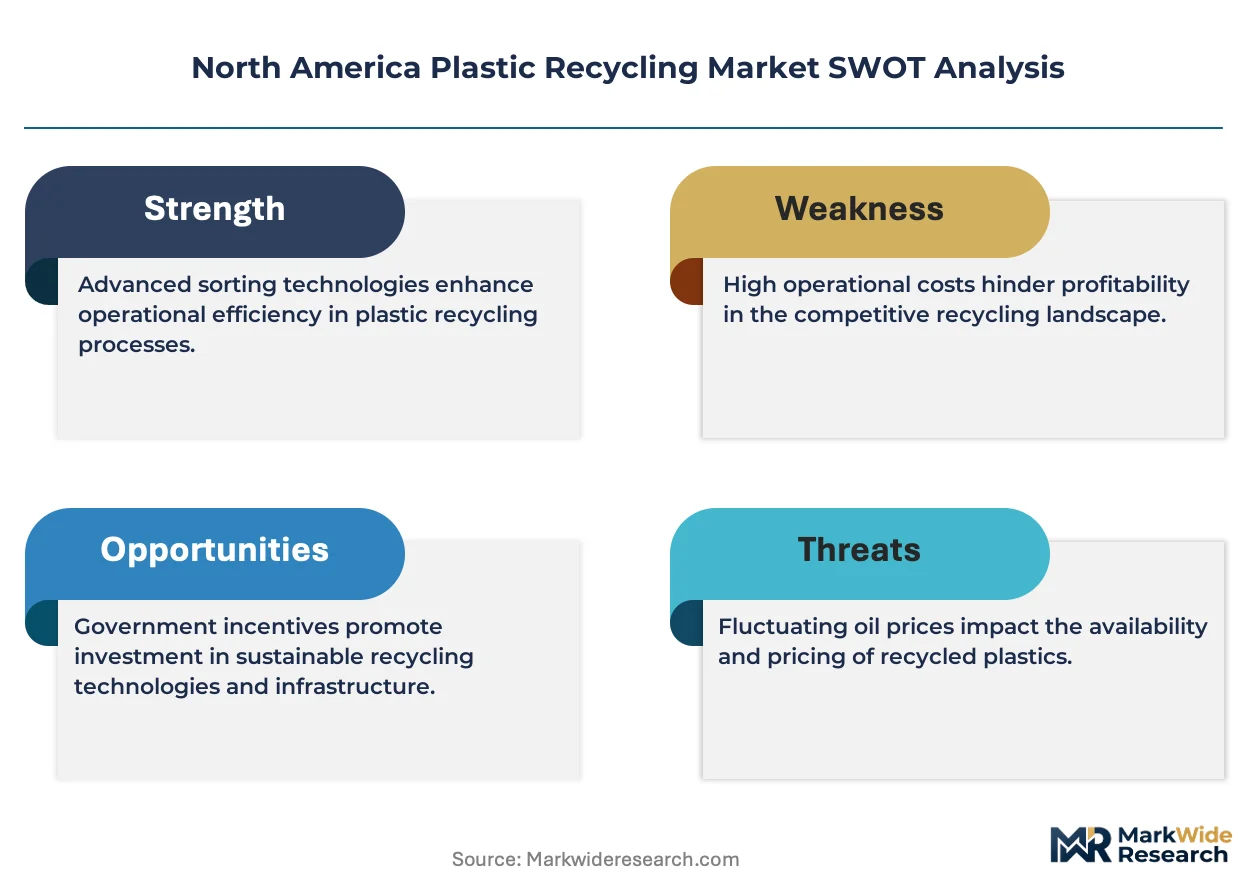
Chemical recycling capacity announcements along the US Gulf Coast corridor are outpacing operational commissioning timelines, creating a supply-demand mismatch that mechanical recyclers are exploiting to defend resin price premiums.
Growth Catalysts
- Extended Producer Responsibility frameworks:California, Oregon, and Colorado EPR laws are restructuring collection infrastructure economics by shifting municipal cost burdens upstream to packaging producers.
- Food-contact rPET certification:FDA letters of no objection for post-consumer resin are unlocking beverage bottling procurement specifications previously restricted to virgin PET.
- Houston-Corpus Christi corridor clustering:Chemical recycling infrastructure concentration near Texas petrochemical feedstock hubs is reducing pyrolysis oil logistics costs for difficult-to-process polyolefins.
Market Restraints
- Contamination rate volatility:Curbside bale quality swings between 2-8% non-target residue, forcing reprocessors to maintain dual-input sourcing strategies that erode margin predictability.
- Natural gas price exposure:Chemical recycling energy intensity ties facility economics to Henry Hub spot volatility, compressing project IRRs during winter demand spikes.
- Mechanical degradation limits:PET thermal reprocessing caps at 5-7 cycles before intrinsic viscosity drops below bottle-grade thresholds, constraining closed-loop supply chain claims.
Strategic Opportunities
- Automotive interior trim mandates:OEM specifications for minimum recycled content in dashboard and door panel substrates are opening specification engineering contracts for compounded PP and ABS recyclers.
- Mexico bale arbitrage:Film recovery networks spanning Texas border zones can access lower-collection-cost feedstock from northern Mexican industrial corridors for US pelletization.
- Clean Air Act permitting tailwinds:EPA fast-track designation for chemical recycling under waste-to-fuel pathways is compressing facility approval timelines versus traditional solid waste incineration classifications.
Industry Challenges
- Polymer identification workforce gaps:Near-infrared spectroscopy operation and melt-flow index calibration require technician training pipelines that community colleges have not yet scaled to match facility buildout rates.
- Multi-layer film delamination capex:Solvent-based separation systems for metallized flexible packaging demand $40-60 million per line, stranding mid-cap processors without offtake agreements from CPG majors.
- Food-grade certification timelines:FDA no-objection letter processes for novel recycling technologies extend 18-24 months, delaying revenue recognition for pilot-scale chemical recycling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Recycling Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, PVC, LDPE End User: Packaging, Automotive, Construction, Textiles Collection Method: Curbside Collection, Drop-off Centers, Industrial Recycling, Deposit Return Recycling Technology: Mechanical Recycling, Chemical Recycling, Energy Recovery, Biodegradation |
| Companies Covered | B&B Plastics, Ultra-Poly Corporation, KW Plastics, Green Line Polymers, WM Recycle America LLC, Avangard Innovative, Parc Corporation, Phoenix Technologies, Envision Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Recycling Market Strategic Shifts & Innovations
Pyrolysis and depolymerization technologies are migrating from pilot demonstration to commercial scale-up, while regulatory pressure on virgin plastic production intensifies specification engineering for recycled-content alternatives across durable goods manufacturing.
PureCycle Technologies' solvent-based polypropylene purification is decomposing odor and color contaminants from post-industrial carpet and packaging scrap at molecular level. Automotive tier-one suppliers are qualifying this output for bumper and interior applications previously reserved for virgin resin. The process is decomposing the technical barriers that historically restricted recycled PP to lower-value injection molding grades.
The EPA's recycled-content procurement guidelines under the Save Our Seas 2.0 Act are mandating federal agency purchasing preferences for post-consumer resin in shipping pallets, traffic cones, and park benches. Federal procurement volume concentration is creating anchor demand contracts that de-risk reprocessor capacity expansion financing. Military logistics and postal operations represent the earliest compliance verticals given specification flexibility in non-food-contact durable goods.
Beverage bottlers are consolidating resin purchasing through direct tolling arrangements with mechanical recyclers, bypassing traditional distributor intermediaries. CPG majors including Coca-Cola and PepsiCo are executing multi-year offtake contracts that specify melt-flow index ranges and contamination thresholds rather than buying commoditized rPET pellets on spot markets. California and Oregon deposit-return systems exhibit the most advanced procurement model evolution due to bale traceability infrastructure mandated by state redemption center regulations.
North America Plastic Recycling Market Segmentation
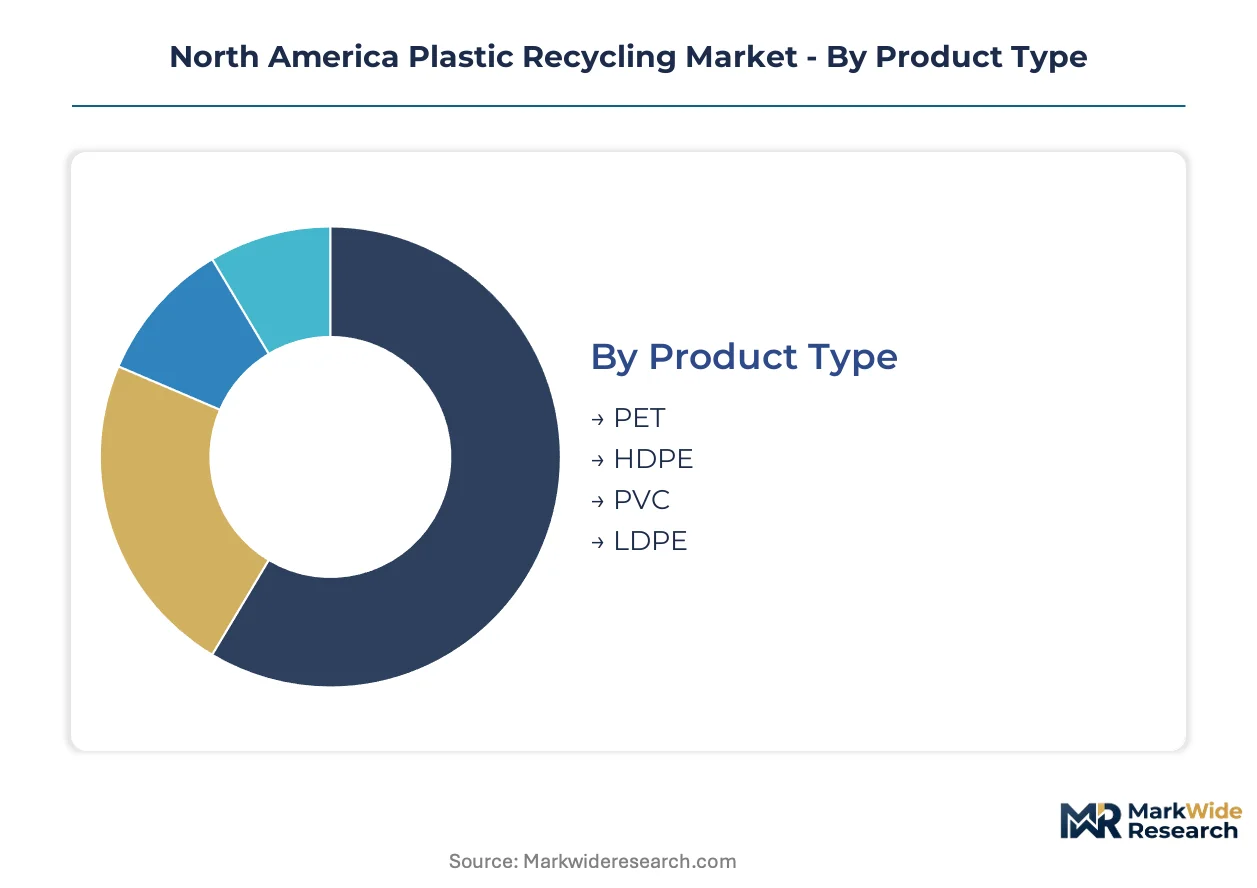
Segmentation in North American plastic recycling reveals where capital is concentrating and which specification tiers command sustainable premiums. Understanding these divisions exposes arbitrage opportunities between collection infrastructure gaps and end-use procurement mandates.
Product Type:
Margins cluster around resin grades with established food-contact certification pathways and closed-loop supply chain integration.
- PET:Polyethylene terephthalate dominates curbside-derived tonnage through beverage container deposit frameworks in California, Oregon, and Maine. Bottling procurement specifications are collapsing the virgin-rPET price premium as FDA letters of no objection unlock food-contact applications.
- HDPE:High-density polyethylene is rotating up the share rankings in non-bottle applications including pipe, decking, and automotive fuel tanks. KW Plastics anchors North American capacity through its Troy, Alabama reprocessing complex serving these durable goods verticals.
- PVC:Polyvinyl chloride recycling concentrates in construction scrap recovery from demolition and window fabrication waste streams, constrained by additive separation complexity.
- LDPE:Low-density polyethylene film recovery depends on Avangard Innovative's Texas-Mexico bale networks to sustain pelletizer feedstock supply.
PET holds installed capacity. HDPE is rotating up the share rankings.
End User:
Application-driven demand splits between specification-tight packaging mandates and durability-focused industrial offtake.
- Packaging:Beverage bottlers are consolidating resin purchasing through direct tolling arrangements that bypass distributor intermediaries. Coca-Cola and PepsiCo execute multi-year offtake contracts specifying melt-flow indices rather than buying commoditized rPET pellets on spot markets.
- Automotive:OEM specifications for minimum recycled content in dashboard and door panel substrates are opening engineering contracts for compounded PP and ABS recyclers. Ultra-Poly Corporation specializes in bumper reclaim for this vertical.
- Construction:HDPE pipe and decking applications absorb post-industrial scrap from fabrication offcuts, with federal procurement guidelines under the Save Our Seas 2.0 Act mandating post-consumer resin in traffic cones and park benches.
- Textiles:Carpet reclamation feeds PureCycle Technologies' solvent-based polypropylene purification for automotive tier-one supplier qualification.
Packaging commands procurement volume concentration. Automotive is climbing the fastest on specification engineering contracts.
Collection Method:
Infrastructure economics vary dramatically by who bears collection cost burdens and contamination risk.
- Curbside Collection:Municipal programs generate 2-8% non-target residue volatility, forcing reprocessors to maintain dual-input sourcing strategies that erode margin predictability. California and Oregon deposit-return systems exhibit the most advanced procurement model evolution due to bale traceability infrastructure.
- Deposit Return:Container redemption centers in bottle-bill states deliver higher-quality PET bales with lower contamination rates, supporting food-grade rPET certification timelines.
- Industrial Recycling:Post-industrial scrap from automotive and packaging fabrication offers consistent composition and lower sorting costs.
- Drop-off Centers:Supplementary collection points for bulky rigid plastics and film serve regions without comprehensive curbside coverage.
Deposit return holds quality premiums. Curbside collection is gaining share fastest on volume scale.
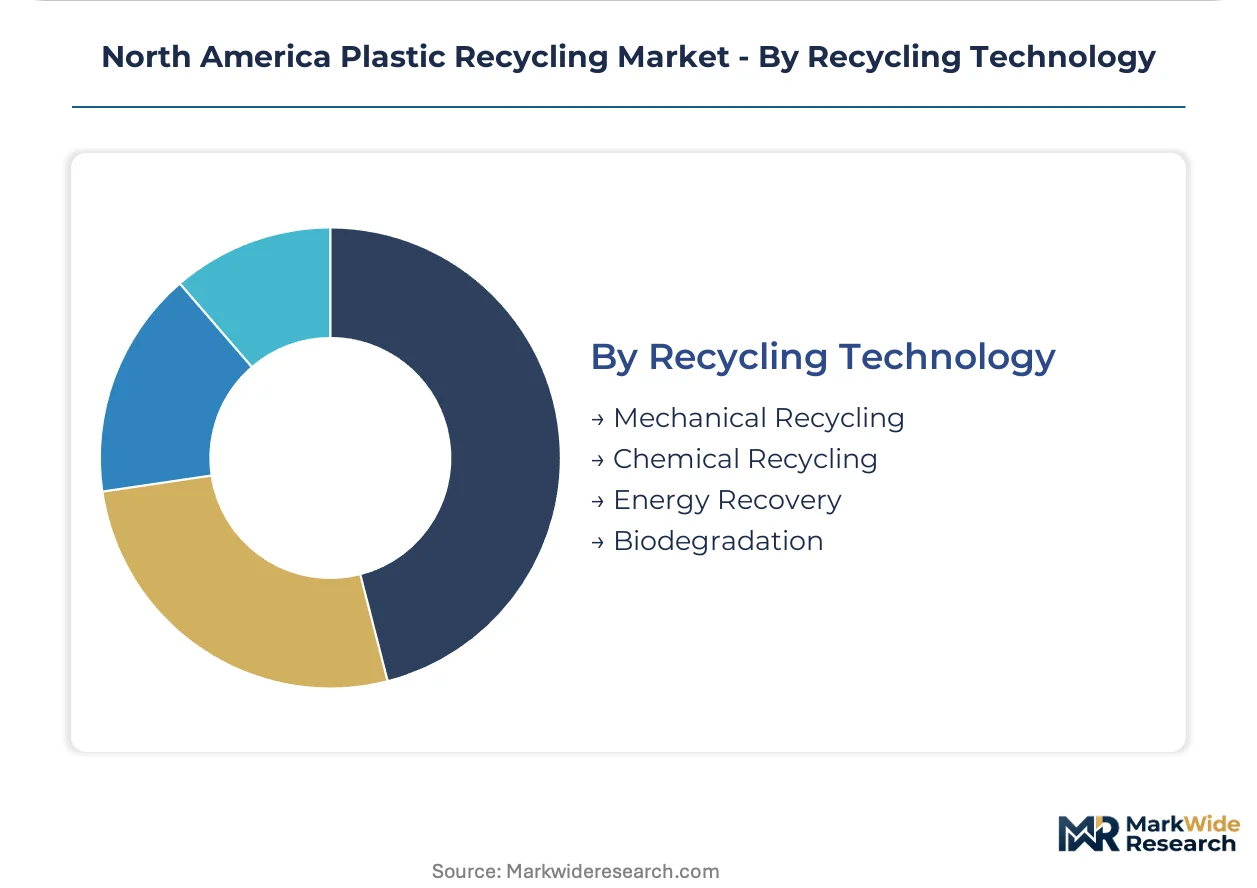
Recycling Technology:
Technology selection determines addressable feedstock scope and regulatory classification under the Clean Air Act.
- Mechanical Recycling:Dominates current throughput volumes with melt-reprocessing constraints—PET thermal cycles cap at 5-7 iterations before intrinsic viscosity drops below bottle-grade thresholds. Mechanical recyclers exploit chemical recycling commissioning delays to defend resin price premiums.
- Chemical Recycling:Pyrolysis and depolymerization capacity announcements along the Houston-Corpus Christi corridor outpace operational timelines, creating supply-demand mismatches. EPA fast-track designation under waste-to-fuel pathways compresses facility approval timelines.
- Energy Recovery:Waste-to-fuel applications for degraded polyolefins face permitting scrutiny versus traditional incineration classifications.
- Biodegradation:Limited commercial scale in North America due to infrastructure incompatibility with existing sorting and reprocessing systems.
Mechanical recycling holds installed capacity. Chemical recycling is rotating up the share rankings on pyrolysis oil logistics cost advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States exports recovered rPET pellets to Canadian beverage bottlers while Mexican film bales flow northward to Texas reprocessors, establishing a triangular trade pattern that concentrates value-add processing in the US Gulf Coast corridor.
United States
California and Oregon deposit-return systems generate the highest-quality PET bales for food-grade certification, while Texas and Louisiana host chemical recycling buildouts near Houston and Corpus Christi petrochemical hubs. EPA procurement guidelines under the Save Our Seas 2.0 Act mandate federal agency purchasing of post-consumer resin in durable goods. The US Gulf Coast corridor clusters pyrolysis and depolymerization capacity to exploit feedstock proximity and logistics cost advantages.
Canada
Ontario and Quebec curbside programs supply HDPE and PP feedstock to reprocessors serving automotive and construction verticals, though contamination volatility forces dual-input sourcing strategies. Health Canada regulates food-contact recycled plastics through pre-market notification requirements that parallel FDA frameworks. The Toronto-Windsor corridor concentrates mechanical recycling capacity to serve Great Lakes manufacturing demand.
Mexico
Northern industrial states generate post-industrial film and rigid scrap that crosses into Texas for pelletization, exploiting collection cost arbitrage across the border zone. The national environmental regulator SEMARNAT advances extended producer responsibility consultations that may restructure municipal collection economics. Monterrey and Tijuana anchor cross-border bale supply networks feeding Avangard Innovative's recovery infrastructure.
California
State-level extended producer responsibility legislation shifts packaging cost burdens upstream to producers while mandating recycled content minimums that outpace federal requirements. CalRecycle administers grant programs for sorting infrastructure that reduce curbside contamination rates below national averages. The Central Valley and Los Angeles Basin concentrate reprocessing capacity to serve West Coast beverage bottling demand.
Texas
Industrial scrap from Houston petrochemical complexes and Corpus Christi resin production generates captive feedstock for mechanical and chemical recycling operations. The Texas Commission on Environmental Quality coordinates permitting for pyrolysis facilities under waste-to-fuel regulatory pathways. The Houston Ship Channel corridor hosts the densest concentration of announced chemical recycling capacity in North America.
North America Plastic Recycling Market Key Industry Players
Listed leaders compete with private specialists across technology licensing and feedstock access dimensions, producing a tiered structure where scale-driven consolidators hold pricing power in commoditized resin grades while mid-cap specialists defend margins in specification-tight automotive and food-contact applications. Three archetypes dominate: integrated waste managers with collection-to-pellet vertical control, pure-play mechanical recyclers with regional bale monopolies, and chemical recycling ventures with pyrolysis oil offtake agreements. Competitive moves concentrate on multi-year tolling contracts with CPG majors and strategic partnerships to secure film bale supply from Mexico.
Among private specialists, KW Plastics anchors North American HDPE recycling through its Troy, Alabama reprocessing complex, exemplifying the regional-bale-monopoly archetype. Ultra-Poly Corporation occupies a defensible niche in automotive bumper reclaim, representing specification-tight segment specialization. Avangard Innovative leverages film recovery networks across Texas and Mexico, illustrating cross-border feedstock arbitrage strategies that sustain downstream pelletizer supply.
| Leading Market Players |
|---|
| B&B Plastics |
| Ultra-Poly Corporation |
| KW Plastics |
| Green Line Polymers |
| WM Recycle America LLC |
| Avangard Innovative |
| Parc Corporation |
| Phoenix Technologies |
| Envision Plastics |
| Others |
Cost & Logistics Intelligence
Long-term tolling contracts between beverage bottlers and mechanical recyclers lock in both bale supply access and resin price visibility across the North American market. These direct arrangements bypass distributor intermediaries and stabilize margins against chemical recycling commissioning delays.
Pricing Analysis
Mechanical recycling holds a cost-generation pricing gap against chemical recycling alternatives. Three-tier pricing structure across food-grade, industrial-grade, and non-spec resin levels tracks FDA certification status and melt-flow index consistency. Price differentiation hinges on contamination thresholds and bale traceability infrastructure. Cost compression in industrial-grade tiers is intensifying because curbside contamination volatility forces dual-input sourcing. Small compounders serving automotive specifications exhibit lowest price sensitivity due to OEM mandate compliance requirements.
Supply Chain Analysis
Inventory cycles for post-consumer bales stretch 30-45 days from collection to pelletization, creating working capital intensity for reprocessors. Feedstock supply concentrates in the United States, Canada, and Mexico with cross-border arbitrage flows. Raw material dependencies rest on curbside collection systems, deposit-return infrastructure, and industrial scrap generation networks. Single-source vulnerability runs through the Houston-Corpus Christi chemical recycling corridor where permitting delays strand announced capacity. Distribution feeds from reprocessing complexes to tolling customers through dedicated rail and truck arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American plastic recycling represents a high-growth disruption as EPA procurement guidelines under the Save Our Seas 2.0 Act create anchor demand contracts that de-risk capacity expansion financing.
For Market Incumbents: Secure multi-year offtake agreements with CPG majors that specify melt-flow indices and contamination thresholds rather than commoditized spot purchases. Defend margin position by investing in near-infrared spectroscopy and automated sorting to reduce contamination-driven yield loss. Chemical recycling commissioning delays present a window to lock in mechanical recycling price premiums before pyrolysis oil supply ramps.
For New Entrants and Emerging Players: Lead with automotive interior trim specifications where OEM recycled content mandates create procurement urgency with limited qualified supplier bases. Target northern Mexican industrial corridors for film bale supply arbitrage into Texas pelletization capacity. Pursue tolling arrangements with beverage bottlers rather than competing for commoditized rPET spot markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mechanical recyclers with deposit-return system bale access and food-grade certification pathways. Long-term viability favors facilities with backward integration into collection infrastructure or captive industrial scrap supply. Monitor FDA no-objection letter timelines for chemical recycling technologies as the signal indicating revenue recognition acceleration for pilot-scale investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Builds pyrolysis and depolymerization infrastructure along the Houston-Corpus Christi corridor to exploit feedstock proximity. |
| Backward Integration | Acquires film recovery networks across Texas and Mexico to secure bale supply for downstream pelletization operations. |
| Long-term Supply Agreement | Executes direct tolling contracts with Coca-Cola and PepsiCo that specify melt-flow indices rather than spot market purchases. |
| Joint Venture | Partners with automotive tier-one suppliers to qualify solvent-based polypropylene purification for bumper and interior applications. |
| Green Certification Program | Pursues FDA letters of no objection for food-contact recycled plastics to unlock beverage bottling procurement specifications. |
Research Approach
Initial hypotheses were tested against primary input from reprocessing plant managers, municipal collection coordinators, CPG procurement leads, and chemical recycling project developers and refined through secondary validation. Plant managers at Troy, Alabama and Houston corridor facilities provided operational data on yield rates and contamination handling. Secondary sources drew from EPA procurement guideline documents, FDA no-objection letter databases, state-level EPR legislation texts, and American Chemistry Council industry statistics. Bottom-up capacity buildouts were triangulated against top-down resin demand projections.
Variance in output estimates decomposes across technology mix assumptions, feedstock quality scenarios, and regulatory timeline sensitivities. The analytical framework segments by resin type, end-use application, collection method, and recycling technology across the projection horizon. CAGRs were derived from installed capacity trajectories and offtake contract visibility. Forecast inputs incorporated chemical recycling permitting velocity under Clean Air Act waste-to-fuel pathways and mechanical recycling thermal cycle degradation limits.
The analysis sits within stated boundaries; outcomes outside sustained EPR legislative momentum or accelerated FDA certification timelines would require recalibration. Forecasts reflect documented assumptions regarding bale quality improvement rates and pyrolysis oil logistics cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Global Post-Consumer Recycled Plastics Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market