
 Vietnam Recycled Plastics Market | 2026-2036
Vietnam Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Recycled Plastics Market Intelligence
Decree 08/2022/ND-CP on extended producer responsibility is decoupling informal collection from formal market access. VietCycle leverages its nationwide collection network to supply certified feedstock directly to brand compliance programs. Formosa Plastics Group anchors industrial-scale mechanical recycling with integrated resin-to-film operations near its Ha Tinh complex. Duy Tan Plastic Recycling Co., Ltd. differentiates through food-grade rPET pellet production serving multinational beverage bottlers.
Vietnam recycled plastics comprise reprocessed thermoplastic polymers derived from post-industrial and post-consumer waste streams, typically requiring washing, sorting, extrusion, and pelletization to achieve melt flow indices between 2-20 g/10min for injection or blow molding applications. These materials substitute virgin resin in packaging, automotive, and construction applications where technical specifications permit partial or full replacement. PET dominates packaging applications due to established bottle-to-bottle recycling pathways and brand sustainability commitments. Mechanical Recycling occupies the majority of installed capacity, though Chemical Recycling is attracting capital for mixed-film streams that mechanical processes cannot valorize. Feedstock Recycling remains nascent but holds structural importance for multilayer and contaminated plastics that would otherwise route to energy recovery or landfill.
Vietnam's Ministry of Natural Resources and Environment administers the National Action Plan on Marine Plastic Debris, while the General Department of Customs enforces import restrictions under Circular 12/2022/TT-BCT limiting scrap plastic categories. The country's national standard regulator sets quality benchmarks for recycled resin under TCVN standards that determine eligibility for green product certification and public procurement preference. Stakeholders must monitor enforcement consistency across provincial environmental departments and the pace of domestic collection infrastructure buildout relative to import substitution targets.
Market Dynamics
Decree 08/2022/ND-CP is decoupling informal waste collection from formal market access, forcing packaging manufacturers to rebuild feedstock procurement around certified domestic networks rather than imported scrap.
Growth Catalysts
- Extended Producer Responsibility Mandate:Vietnam's Circular Economy Decree requires brand owners to finance collection infrastructure, redirecting capital toward mechanical recycling capacity in Ho Chi Minh City and Hanoi industrial zones.
- EU Import Compliance:Export-oriented manufacturers supplying European Union markets must demonstrate recycled-content traceability, pulling certified rPET and rHDPE through audited supply chains.
- Chemical Recycling Pilot Scale:Pyrolysis and depolymerization units for mixed multilayer films are attracting project finance, addressing feedstock categories mechanical processes cannot valorize.
Market Restraints
- Feedstock Cost Volatility:Domestic post-consumer collection infrastructure remains underdeveloped relative to import substitution targets, creating price pressure on baled PET and PE fractions.
- Import Restriction Friction:Circular 12/2022/TT-BCT limits scrap plastic categories eligible for customs clearance, constraining raw material access for processors without backward integration into collection.
- Technical Specification Gaps:TCVN quality benchmarks for recycled resin lag brand technical requirements for food-contact applications, restricting premium pricing capture.
Strategic Opportunities
- Central Highlands Collection Buildout:Da Nang and surrounding provinces lack formal recovery infrastructure, creating first-mover advantages for vertically integrated operators securing municipal concessions.
- Beverage Brand Compliance Programs:Multinational bottlers face 2025-2030 recycled-content commitments, generating offtake agreements for food-grade rPET pellet producers meeting FDA and EFSA standards.
- Construction Sector Substitution:Infrastructure projects in the Red River Delta specify recycled-content drainage and piping, opening volume outlets for mixed-polymer reprocessors.
Industry Challenges
- Sorting Technology Deployment:Near-infrared and robotics-based purification systems require capital outlays that mid-scale mechanical recyclers struggle to finance without project debt.
- Certification Timeline Compression:EU Green Claims Directive and US FTC Green Guides demand third-party chain-of-custody verification, extending sales cycles for non-integrated traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Recycled Plastics Market |
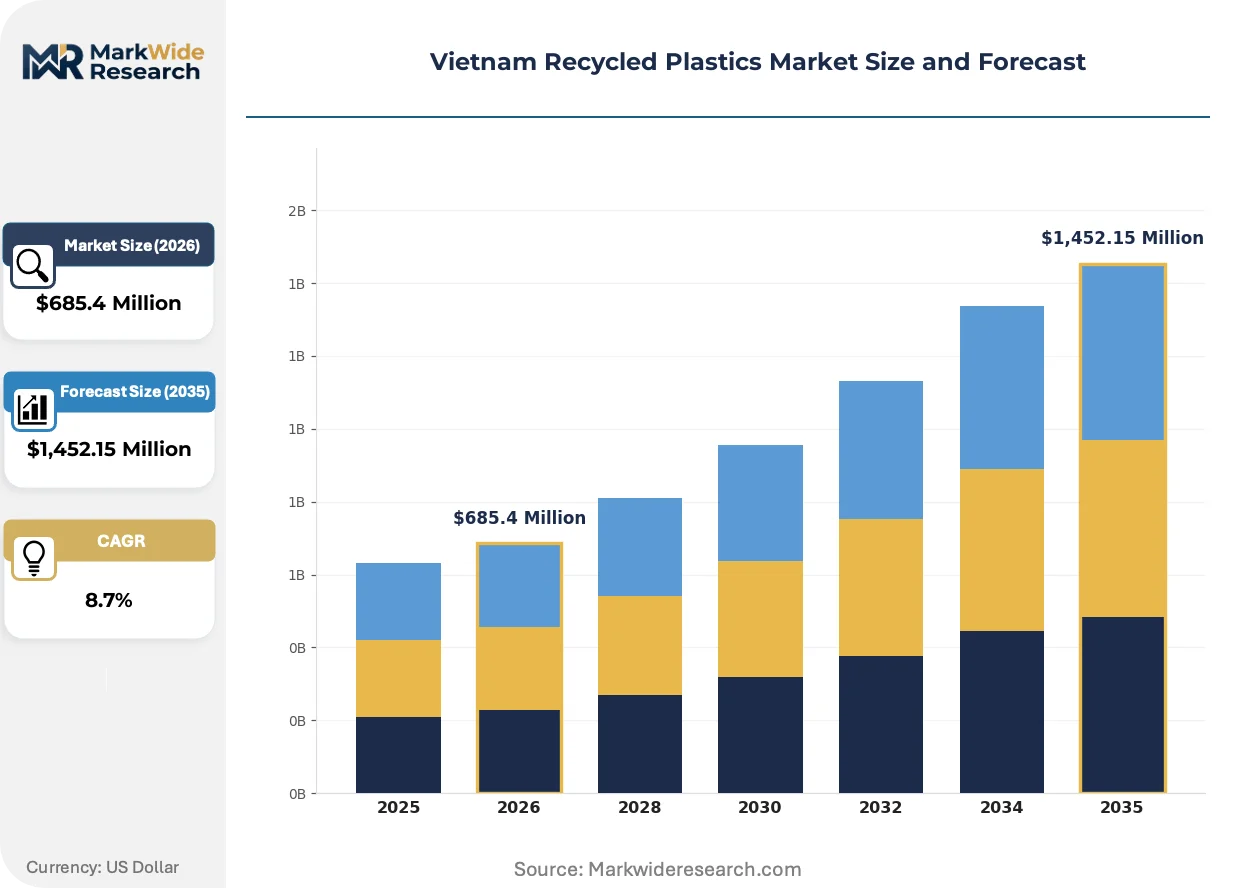
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC Application: Packaging, Automotive Components, Construction Materials, Textiles End User: Manufacturers, Retailers, Waste Processors, Exporters Recycling Technology: Mechanical Recycling, Chemical Recycling, Energy Recovery, Feedstock Recycling |
| Companies Covered | VietCycle, Formosa Plastics Group, Duy Tan Plastic Recycling Co., Ltd., IAV Global Limited Co., Tin Thanh Plastic Manufacturing-Trading Co., Ltd., Circular Plastics Company, Blue Sky Recycling Co., Ltd., Indorama Ventures Public Company Limited, ALBA Group Asia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Recycled Plastics Market Strategic Shifts & Innovations
Mechanical and chemical recycling pathways are diverging in capital allocation, with project finance flowing toward pyrolysis for contaminated streams while brand compliance pulls food-grade mechanical output.
Advanced sorting systems integrating near-infrared spectroscopy with robotic pickers are converging with cloud-based feedstock traceability platforms. Beverage bottlers and personal care brands are deploying these technologies at contract reprocessors to meet EU Digital Product Passport requirements. This convergence is compressing the role of informal aggregators who lack digitized chain-of-custody documentation.
The Ministry of Natural Resources and Environment is tightening enforcement of National Action Plan on Marine Plastic Debris targets through provincial environmental departments. Industrial parks in Ha Tinh and Binh Duong now face mandatory waste audits, redirecting post-industrial scrap from landfill toward qualified recyclers. Packaging exporters are responding by pre-qualifying suppliers against TCVN and ISO 14021 standards to secure green product certification.
Brand technical teams are embedding recycled-content specifications directly into packaging design briefs, displacing procurement's traditional arm's-length spot purchasing. This specification shift compresses the supplier base toward integrated resin-to-film operators capable of lot-level traceability. The pivot is most visible among cosmetics and food exporters supplying US and EU retail chains with EPR-linked sustainability scorecards.
Vietnam Recycled Plastics Market Segmentation
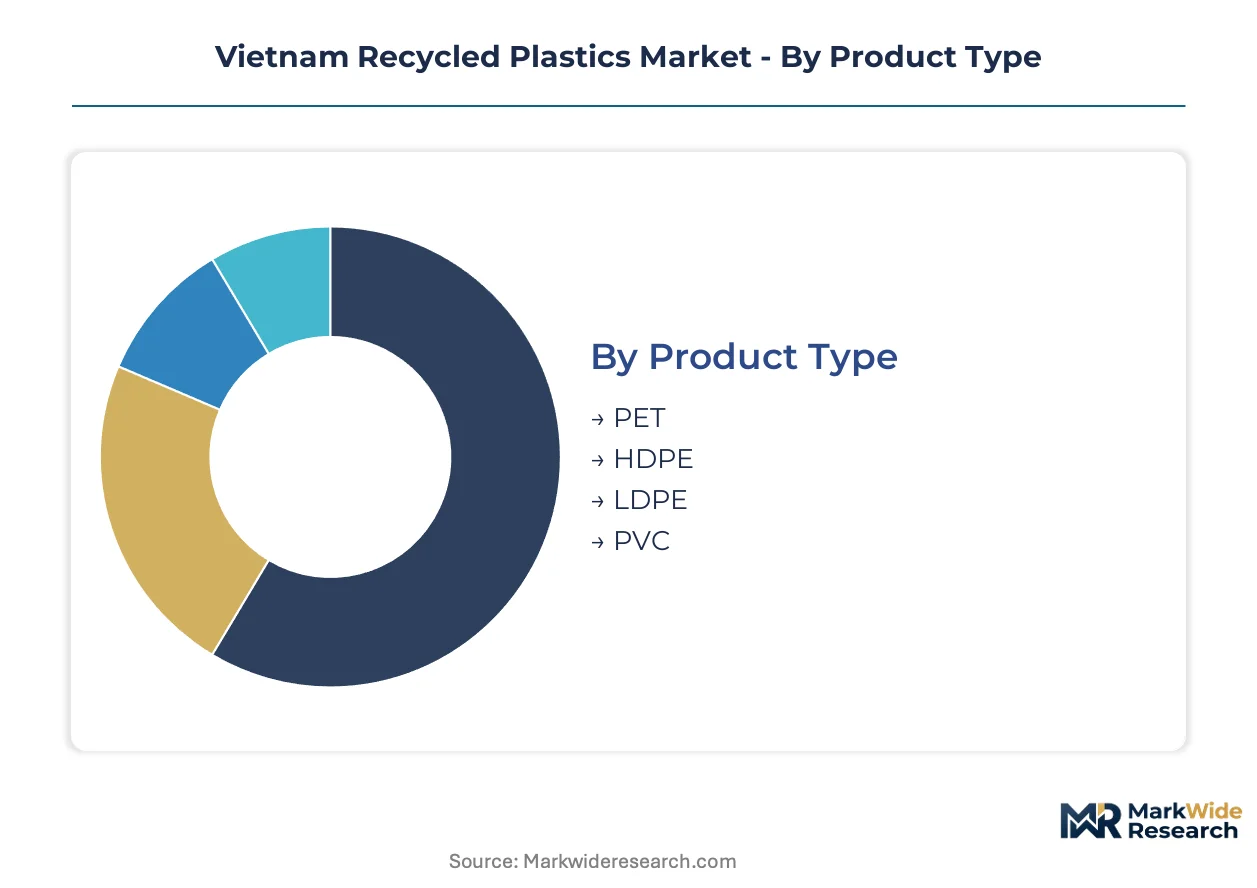
Vietnam's recycled plastics market segments along four intersecting dimensions that determine procurement patterns and margin structures. Technical specifications, regulatory compliance requirements, and export certification needs vary sharply across these categories, forcing processors to specialize rather than compete as generalists.
Product Type:
Buyers differentiate primarily by melt flow index requirements and contamination tolerance thresholds for their molding equipment.
- PET:Reprocessed polyethylene terephthalate achieves intrinsic viscosity levels between 0.70-0.84 dL/g suitable for bottle-to-bottle applications. Demand concentrates among beverage exporters in Binh Duong province seeking FDA-compliant rPET for EU and US retail chain supply. Brand sustainability mandates are pulling certified food-grade pellet through audited supply chains at premium spreads over industrial-grade resin.
- HDPE:High-density polyethylene regrind delivers melt flow indices of 4-15 g/10min for blow-molded containers and injection-molded caps. Procurement is accelerating among personal care manufacturers in Ho Chi Minh City industrial zones replacing virgin resin in shampoo and detergent packaging. TCVN quality benchmarks for post-consumer HDPE lag brand technical specifications, constraining premium capture.
- LDPE:Low-density polyethylene film scrap requires extensive washing and densification to achieve 0.3-2.0 g/10min flow rates for agricultural film and carrier bag production.
- PVC:Polyvinyl chloride reprocessing demands specialized stabilizer packages to manage thermal degradation during extrusion, limiting viable processor pools.
Volume sits with PET; growth tilts toward HDPE as personal care brands accelerate recycled-content commitments.
Application:
End-use specifications determine contamination thresholds, certification requirements, and pricing power across downstream markets.
- Packaging:Flexible and rigid packaging applications consume the majority of reprocessed resin volumes, spanning food-contact bottles, personal care containers, and industrial films. Formosa Plastics Group's integrated resin-to-film operations near Ha Tinh supply export-oriented converters with lot-level traceability documentation required by EU Digital Product Passport mandates.
- Construction Materials:Drainage piping, decking profiles, and waterproofing membranes utilize mixed-polymer regrinds with lower purity requirements. Infrastructure projects in the Red River Delta increasingly specify recycled-content thresholds, opening volume outlets for processors lacking food-grade certification capabilities.
- Automotive Components:Underhood and interior trim applications demand heat-stabilized polypropylene and engineering-grade nylon with consistent lot properties.
- Textiles:rPET fiber production for apparel and industrial yarn requires chip purity levels approaching virgin resin specifications.
Packaging commands the largest volume share; construction materials are climbing the fastest as public procurement rules tighten.
End User:
Procurement sophistication and backward integration depth separate buyer tiers in feedstock sourcing.
- Manufacturers:Brand-owning converters with direct retail relationships finance collection infrastructure to secure certified feedstock streams. These operators pre-qualify suppliers against ISO 14021 and TCVN standards, compressing sales cycles for integrated resin-to-film processors capable of lot-level documentation.
- Exporters:Contract packagers supplying EU and US retail chains face EPR-linked sustainability scorecards demanding third-party chain-of-custody verification. Procurement teams are embedding recycled-content specifications directly into packaging design briefs, displacing traditional spot purchasing.
- Retailers:Private-label brand owners are consolidating supplier bases toward vertically integrated operators with captive collection networks.
- Waste Processors:Mid-scale mechanical recyclers without brand direct relationships struggle to finance near-infrared and robotics-based purification systems required for export compliance.
Manufacturers anchor current volume; exporters are gaining share fastest as EU Green Claims Directive enforcement tightens.
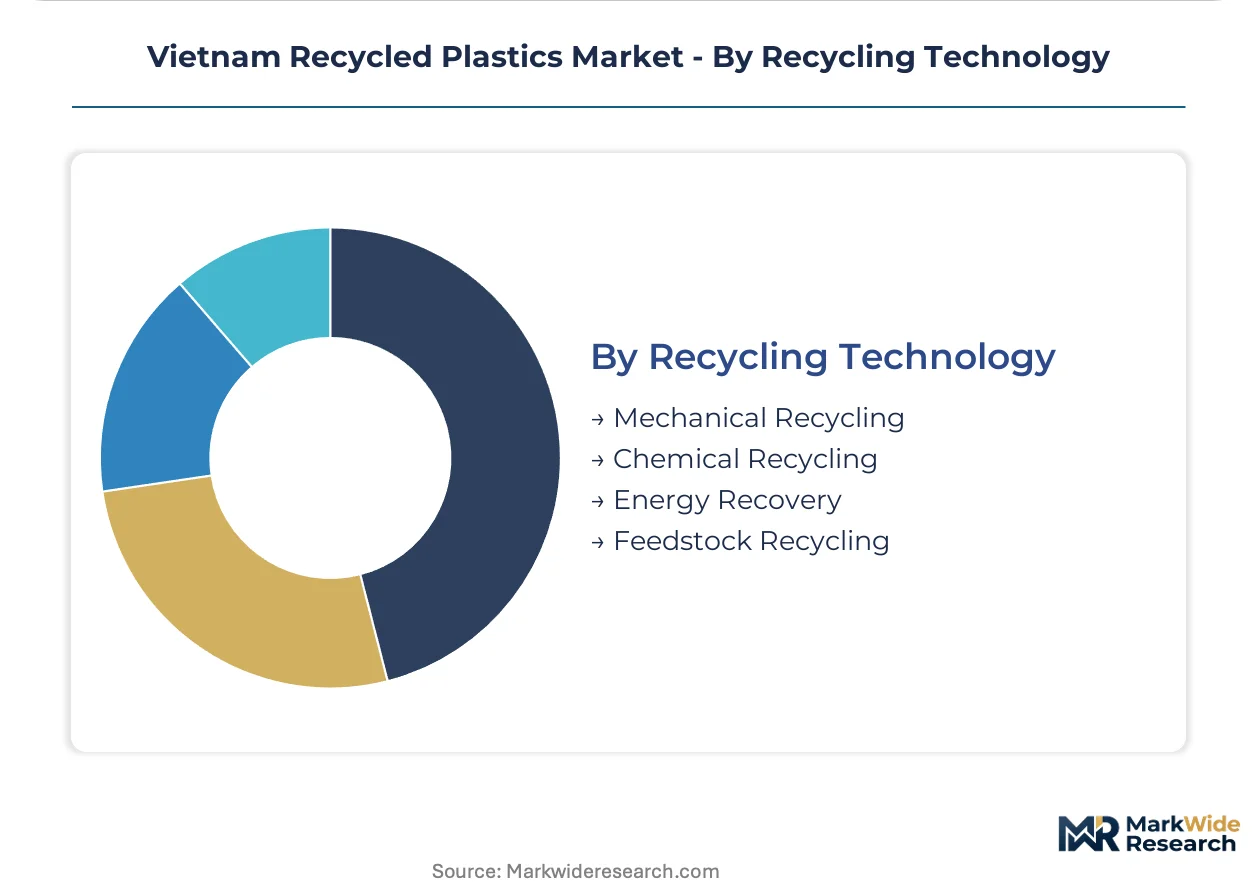
Recycling Technology:
Capital intensity and feedstock flexibility determine technology selection for different waste stream categories.
- Mechanical Recycling:Washing, sorting, extrusion, and pelletization operations dominate installed capacity, producing regrind and pellet for injection and blow molding. Duy Tan Plastic Recycling Co., Ltd. differentiates through food-grade rPET pellet production serving multinational beverage bottlers with FDA and EFSA compliance documentation.
- Chemical Recycling:Pyrolysis and depolymerization units for mixed multilayer films are attracting project finance, addressing feedstock categories mechanical processes cannot valorize. Pilot-scale operations near Ho Chi Minh City target contaminated agricultural film and laminated packaging for monomer recovery.
- Feedstock Recycling:Gasification and cracking pathways for heavily contaminated or multilayer plastics remain nascent but hold structural importance for materials otherwise routing to energy recovery.
- Energy Recovery:Waste-to-incineration with energy capture serves as residual outlet for fractions below mechanical or chemical recycling quality thresholds.
Mechanical recycling holds dominant volume; chemical recycling is expanding most quickly as project finance flows toward pyrosis deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thanh Long Industrial Park in Ha Tinh province anchors Vietnam's recycled plastics concentration through integrated resin-to-film operations and preferential tax treatment for circular economy investments.
Ho Chi Minh City Metropolitan Area
Beverage exporters and personal care manufacturers drive rPET and rHDPE procurement in Binh Duong and Dong Nai provinces. Decree 08/2022/ND-CP enforcement through the Department of Natural Resources and Environment redirects post-industrial scrap from landfill toward qualified mechanical recyclers. District 12 and Hoc Mon industrial zones host mid-scale pelletizers upgrading washing and extrusion lines to meet EU Digital Product Passport traceability requirements.
Hanoi and Red River Delta
Construction materials specification shifts create volume outlets for mixed-polymer reprocessors serving infrastructure projects across Vinh Phuc and Bac Ninh provinces. The Ministry of Construction's recycled-content mandates for drainage and piping accelerate substitution away from virgin resin. Dong Anh and Gia Lam districts concentrate film washing operations supplying agricultural sector demand.
Da Nang and Central Coast
Underdeveloped formal collection infrastructure in Quang Nam and Thua Thien Hue provinces creates first-mover opportunities for vertically integrated operators securing municipal concessions. The National Action Plan on Marine Plastic Debris targets redirect provincial environmental department enforcement toward beachfront and riverine recovery programs. Hoi An and Hue urban centers pilot smart collection bin networks linked to cloud-based feedstock traceability platforms.
Can Tho and Mekong Delta
Agricultural film recovery dominates feedstock flows across An Giang and Dong Thap provinces, with contamination levels challenging mechanical recycling economics. Circular 12/2022/TT-BCT import restrictions force processors to develop backward integration into rural collection networks. Tra Noc Industrial Park hosts emerging pyrolysis pilot units targeting multilayer laminated packaging from rice processing and aquaculture supply chains.
Vietnam Recycled Plastics Market Key Industry Players
Ha Tinh-anchored integrated producers command one tier through captive resin-to-film operations; Ho Chi Minh City specialists hold another through food-grade certification capabilities. Market structure tilts toward consolidation as brand compliance programs compress supplier bases toward operators with lot-level traceability documentation. Three archetypes define competitive positioning: nationwide collection network operators, integrated petrochemical-resin recyclers, and food-grade pellet specialists. Capacity expansion and certification timeline compression represent the dominant competitive moves as EU Green Claims Directive enforcement tightens.
Among collection-integrated operators, VietCycle exemplifies the network-architype model spanning municipal concession agreements. Formosa Plastics Group anchors the petrochemical-integrated tier through backward control over resin supply chains. Duy Tan Plastic Recycling Co., Ltd. occupies the food-grade specialist position, representing certification-capable mechanical recycling operations serving multinational beverage compliance programs.
| Leading Market Players |
|---|
| VietCycle |
| Formosa Plastics Group |
| Duy Tan Plastic Recycling Co., Ltd. |
| IAV Global Limited Co. |
| Tin Thanh Plastic Manufacturing-Trading Co., Ltd. |
| Circular Plastics Company |
| Blue Sky Recycling Co., Ltd. |
| Indorama Ventures Public Company Limited |
| ALBA Group Asia |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap recyclers anchored in Binh Duong and Dong Nai provinces exert asymmetric pricing power through captive control over municipal collection concessions, compressing margin capture for traders lacking backward integration into baled PET and PE feedstock streams.
Pricing Analysis
Short lead-time premiums for FDA-compliant rPET pellet separate contract offtake agreements from spot inventory discounts in the industrial-grade regrind tier. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade against TCVN benchmarks and volume scale commitments. Cost compression in the standard tier intensifies because import substitution targets outpace domestic collection infrastructure buildout. Exporters supplying EU retail chains demonstrate least price sensitivity; mid-scale mechanical recyclers without brand direct relationships face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from beverage bottlers and personal care manufacturers mandate multi-supplier qualification across VietCycle's nationwide network and Formosa Plastics Group's integrated Ha Tinh complex. Feedstock draws from post-consumer collection in Ho Chi Minh City municipal zones, post-industrial scrap from Binh Duong industrial parks, and agricultural film recovery across Mekong Delta provinces. Single-source vulnerability concentrates in food-grade rPET pellet supply where FDA and EFSA certification capabilities remain scarce. Distribution runs through qualified mechanical recyclers pre-approved against ISO 14021 and EU Digital Product Passport standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's recycled plastics market functions as a vertical-integration race where control over certified domestic collection networks determines access to brand compliance programs and premium pricing tiers.
For Market Incumbents: Cement market position by securing exclusive municipal concessions in Da Nang and Central Coast provinces ahead of Decree 08/2022/ND-CP enforcement expansion. Invest in near-infrared and robotics-based purification systems to defend against emerging chemical recycling entrants targeting mixed multilayer film streams. Prioritize TCVN standard upgrades to match FDA technical specifications for food-contact applications. For New Entrants and Emerging Players: Capture first-mover advantage in the Central Highlands collection buildout where formal recovery infrastructure remains underdeveloped relative to Ho Chi Minh City and Hanoi saturation. Target agricultural film recovery across An Giang and Dong Thap provinces as the most penetrable feedstock segment given contamination tolerance for non-food-grade applications. Pursue pyrolysis pilot deployment with rice processing and aquaculture supply chain partnerships as the go-to-market anchor. For Investors and Strategic Acquirers: Distressed-cycle entries favor food-grade pellet specialists in Ha Tinh province where integrated resin-to-film operations command lot-level traceability premiums. Long-term viability over the projection horizon hinges on EU Green Claims Directive enforcement pace and the compression of certification timelines for non-integrated traders. Monitor Circular 12/2022/TT-BCT import restriction tightening as the inflection signal for domestic collection infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Secures certified feedstock streams for EU Digital Product Passport compliance. |
| Food-Grade Certification Investment | Unlocks premium pricing from multinational beverage bottlers under EPR mandates. |
| Pyrolysis Capacity Deployment | Addresses mixed multilayer films that mechanical recycling cannot valorize. |
| Municipal Concession Securement | Captures exclusive access to post-consumer PET and HDPE in underserved provinces. |
| Cloud-Based Traceability Platform Integration | Compresses sales cycles by automating chain-of-custody documentation for exporters. |
Research Approach
Document review covered regulatory filings from Vietnam's Ministry of Natural Resources and Environment, General Department of Customs trade data, and TCVN standard documentation, complemented by interviews with plant managers at mechanical recycling facilities, procurement leads at beverage exporters, collection network operators, and technical R&D directors. Secondary validation drew from customs records, industrial park waste audit disclosures, and circular economy investment filings. Bottom-up capacity and feedstock flow estimates were cross-referenced against top-down demand projections from packaging export volumes.
Historical capacity utilization rates were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. The segmentation framework modeled product type, application, end user sophistication, and recycling technology pathways. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement pacing and import substitution progress. Key inputs included provincial environmental department audit frequencies and brand recycled-content commitment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Decree 08/2022/ND-CP enforcement consistency and the pace of domestic collection infrastructure buildout. Deviation in EU Green Claims Directive implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Global Recycled Base Oil Market