
 Recycled PET Flakes Market | 2026-2036
Recycled PET Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled PET Flakes Market Intelligence
The EU Green Deal is recalibrating procurement standards across European packaging and textile value chains. Indorama Ventures Public Company Limited leverages integrated flake-to-fiber operations across multiple continents. Alpla Group anchors its competitive stance through backward integration into bottle collection networks. Evergreen specializes in food-grade flake production for North American beverage customers.
Recycled PET flakes consist of post-consumer polyethylene terephthalate containers that undergo sorting, washing, grinding, and optical separation to achieve specified intrinsic viscosity and contaminant thresholds, serving primarily as feedstock for new packaging, fibers, and engineered components. Flake output dominates volume flows given its role as the universal intermediate for downstream pelletization and direct sheet extrusion. Food-grade classification commands premium positioning due to FDA and EFSA compliance burdens in bottle and container applications. Textile end-use absorbs substantial flake volumes, though packaging applications retain tighter margin structures through long-term supply agreements with multinational brands.
FDA clearance under its food-contact notification program and EFSA scientific opinions govern food-grade flake eligibility in the United States and European Union respectively, while China's SAMR enforces GB standards for recycled plastics in domestic packaging. The EPA's emerging frameworks on extended producer responsibility and the EU's CSRD disclosure requirements are tightening traceability demands across supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity investments as compliance thresholds harden.
Market Dynamics
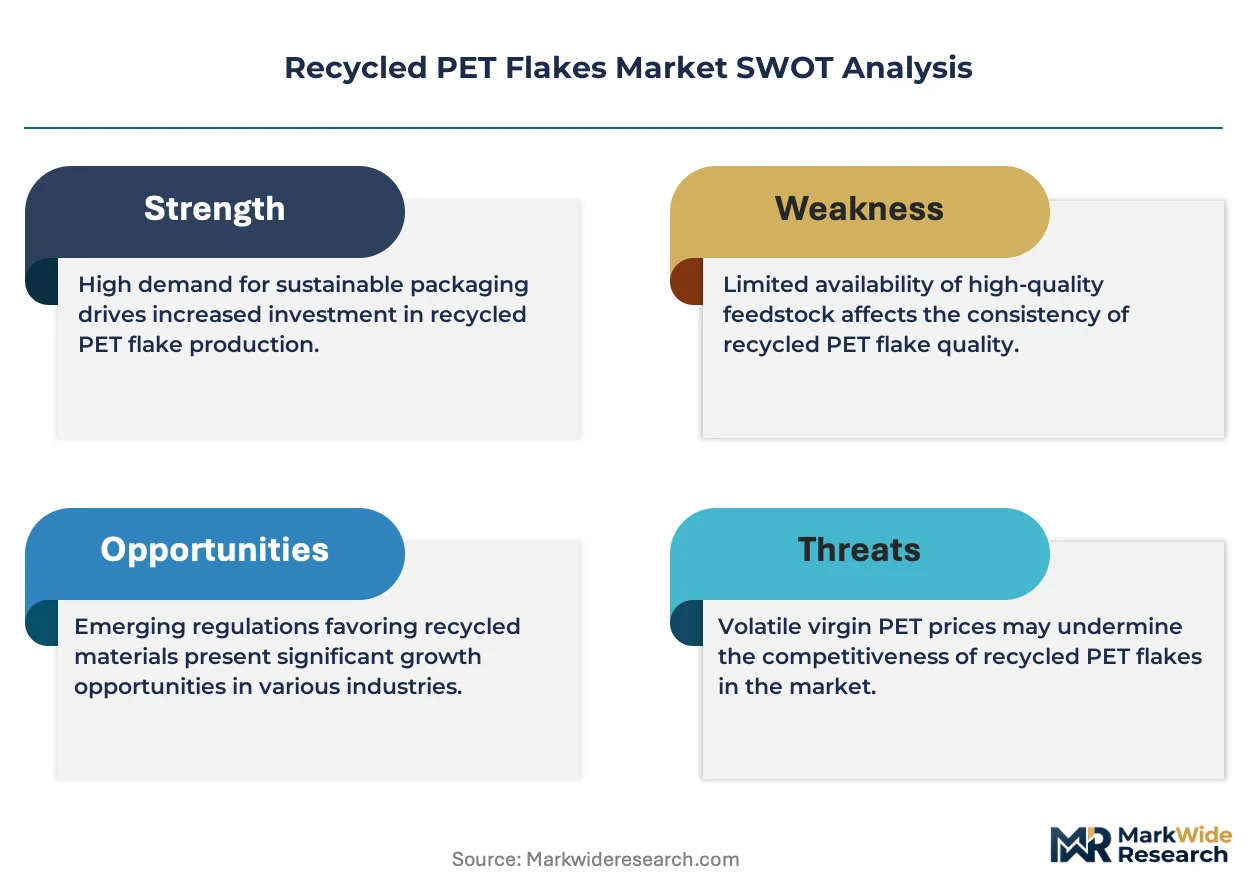
EU Green Deal recycled content mandates are compressing procurement timelines across European packaging and textile value chains, forcing flake suppliers to accelerate purification capacity deployment ahead of 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal packaging mandates:Binding recycled content thresholds for PET beverage bottles are pulling food-grade flake demand upward across Germany, France, and Italy as brand owners lock in long-term supply agreements.
- Textile sector circularity:Bottle-to-fiber recycling loops are tightening as European apparel brands integrate rPET feedstock into polyester fiber production to meet Science Based Targets.
- China's dual carbon goals:Domestic flake purification capacity is accelerating under national decarbonization commitments, reducing import dependency for high-IV material.
Market Restraints
- Post-consumer bale cost volatility:Collection infrastructure gaps in emerging economies create feedstock price swings that compress processor margins during seasonal demand spikes.
- Food-grade purification bottleneck:Super-cleaning technology deployment lags behind demand growth, constraining qualified supply for FDA and EFSA-compliant applications.
- Contamination threshold rigidity:EFSA scientific opinions and FDA food-contact notifications impose contaminant limits that exclude substantial post-consumer feedstock from premium-grade markets.
Strategic Opportunities
- India's emerging packaging standards:BIS recycled plastics regulations and brand-led sustainability pledges are opening demand nodes for imported food-grade flake in Mumbai and Delhi manufacturing clusters.
- Chemical recycling convergence:Pyrolysis and glycolysis technologies are converging with mechanical flake processing to handle degraded PET streams currently routed to fiber applications.
- Extended producer responsibility expansion:EPA frameworks and state-level bottle bill modernizations are creating collection infrastructure investments that expand bale supply for independent processors.
Industry Challenges
- Optical sorting technician scarcity:Near-infrared and X-ray fluorescence equipment operation requires specialized training that outpaces vocational program output in key processing regions.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and SAMR food-grade approvals demand 18-24 month validation cycles that delay revenue recognition for purification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled PET Flakes Market |
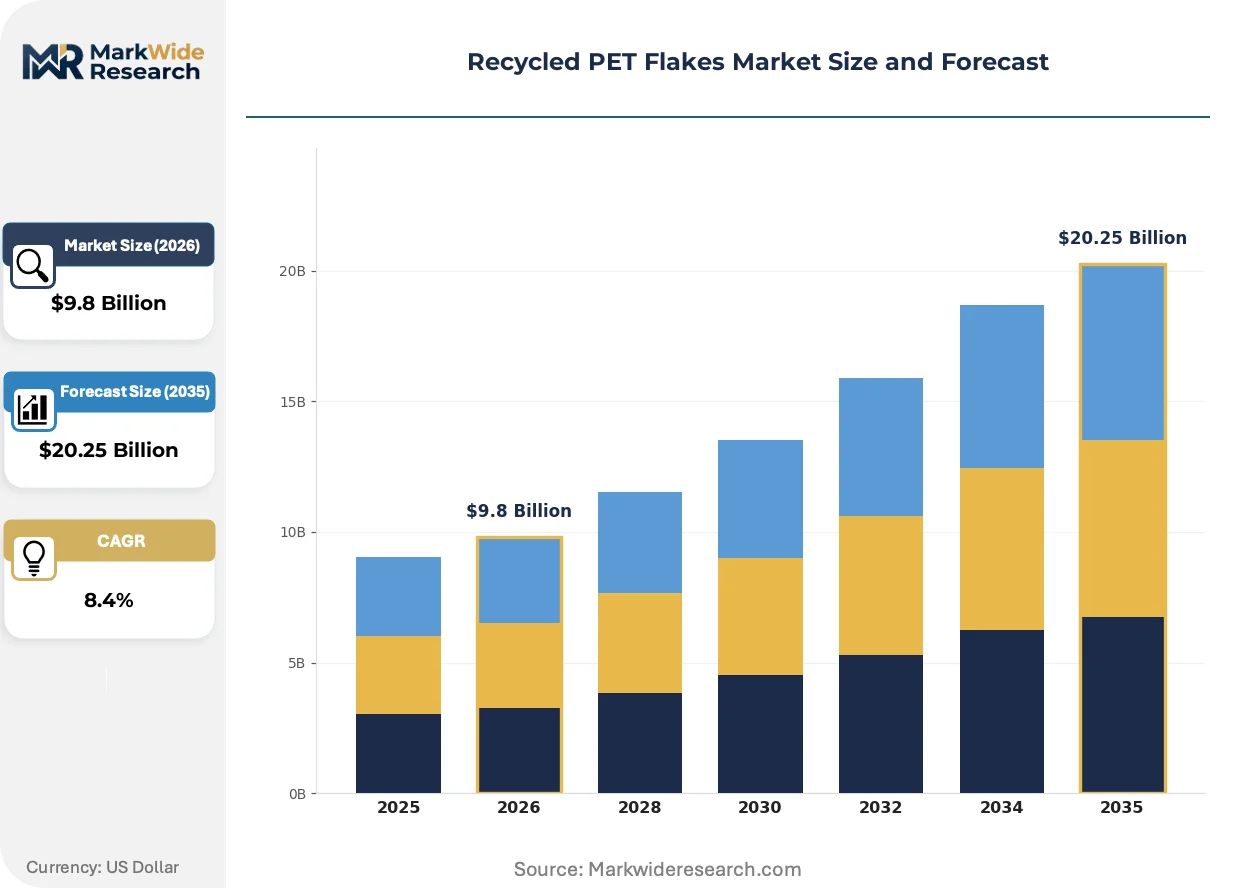
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Pellet, Resin, Sheet End Use: Textiles, Packaging, Automotive Parts, Consumer Goods Grade: Food Grade, Industrial Grade, High Quality, Standard Quality Application: Bottles, Containers, Fibers, Films |
| Companies Covered | Alpek S.A.B. de C.V., Evergreen, Indorama Ventures Public Company Limited, PFR Nord GmbH, Phoenix Technologies International LLC, Far Eastern New Century Corporation, Plastipak Holdings Inc., PetStar, Alpla Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled PET Flakes Market Strategic Shifts & Innovations
Digital traceability platforms and advanced sorting technologies are compressing quality assurance cycles while regulatory disclosure requirements harden documentation standards across supply chains.
Super-cleaning flake purification systems are consolidating technical standards for food-grade rPET production. European beverage bottlers are adopting these systems at accelerated pace to meet EU Green Deal thresholds. The technology is consolidating supplier bases by excluding smaller processors unable to finance super-cleaning capital expenditure.
CSRD disclosure requirements are mandating granular supply chain emissions reporting across European packaging value chains. Corporate sustainability reporting now extends to Scope 3 upstream impacts including flake procurement. Textile and beverage sectors are most affected, with brands restructuring supplier contracts to capture traceability data.
Brand-led packaging pledges are restructuring procurement relationships between multinational beverage companies and flake suppliers. Long-term offtake agreements with fixed pricing mechanisms are displacing spot-market transactions for food-grade material. This shift is most visible in Germany and Brazil where concentrated brand ownership creates buyer consortium leverage.
Recycled PET Flakes Market Segmentation
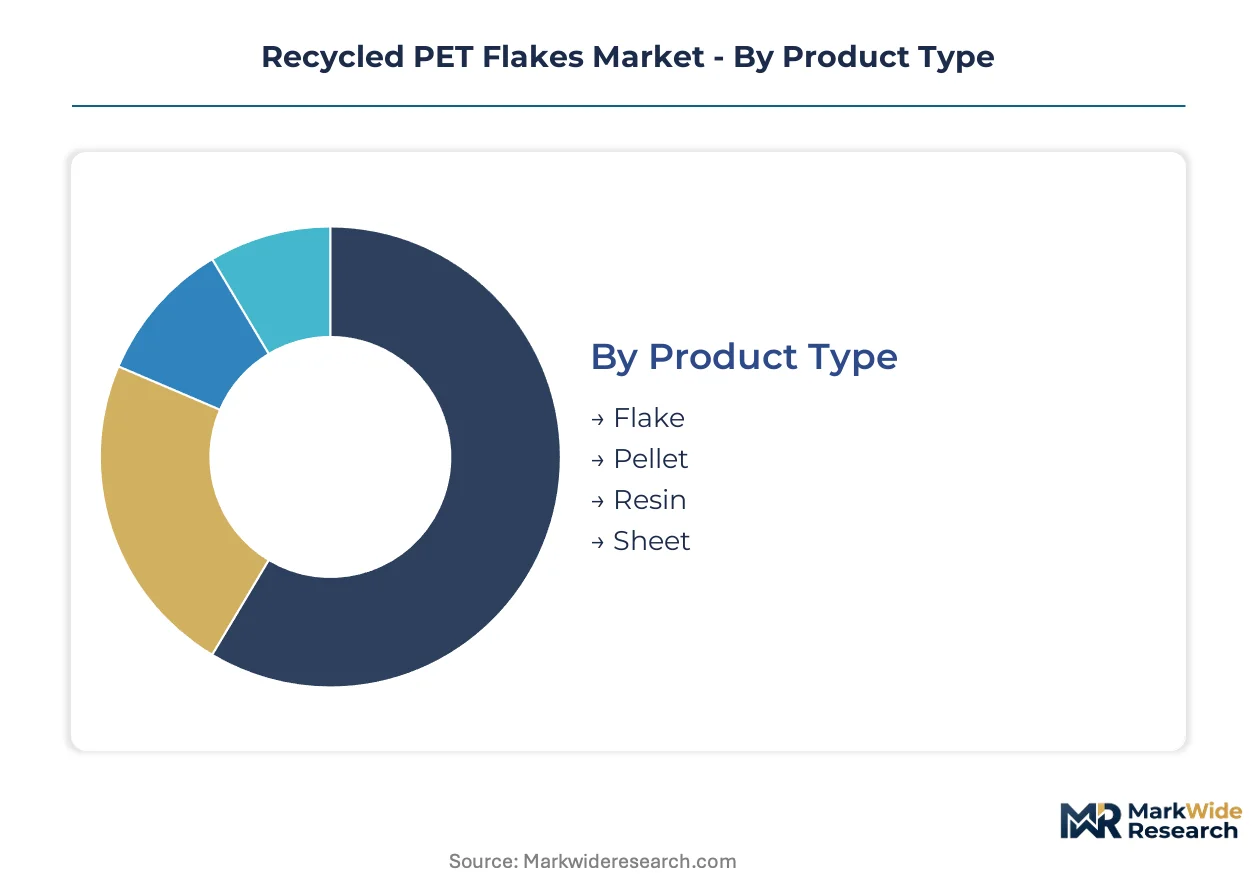
Segmentation in recycled PET flakes reveals how purification thresholds, end-use specifications, and regulatory classifications fragment procurement strategies across the value chain. Each dimension carries distinct margin structures and compliance burdens that reshape supplier-buyer relationships.
Product Type:
Standardization dominates at the commodity end while premium tiers demand customized purification protocols and viscosity controls.
- Flake:Post-consumer containers undergo washing, grinding, and optical sorting to achieve specified intrinsic viscosity thresholds. This intermediate format feeds directly into sheet extrusion and pelletization lines across German and Chinese manufacturing clusters, with EU Green Deal mandates compressing procurement timelines for qualified supply.
- Pellet:Extruded and crystallized flake processed to precise melt-flow indices for injection molding and blow molding applications. Brand-led packaging pledges in Brazil and India are restructuring offtake agreements toward long-term pellet contracts with fixed pricing mechanisms.
- Resin:Polymerized material meeting engineered specifications for high-performance applications.
- Sheet:Thermoformed feedstock for tray and clamshell production with specific gauge requirements.
Leading the category by volume: Flake. Expanding most quickly: Pellet.
End Use:
Margin concentration follows certification intensity, with food-contact applications commanding structural premiums over industrial feedstock.
- Textiles:Bottle-to-fiber recycling loops absorb substantial flake volumes for polyester fiber production. European apparel brands integrate rPET feedstock to meet Science Based Targets, with demand concentrating in Italian and Portuguese spinning clusters where EU Green Deal circularity requirements tighten procurement standards.
- Packaging:Beverage bottles, food containers, and cosmetic jars require FDA and EFSA food-grade compliance. Super-cleaning technology deployment lags behind demand growth, constraining qualified supply as brand owners in Germany and France lock in long-term agreements ahead of recycled content mandates.
- Automotive Parts:Interior trim, under-hood components, and acoustic insulation utilizing industrial-grade material.
- Consumer Goods:Household items, electronics housings, and durable goods with moderate purity requirements.
Highest margin capture: Packaging. Steepest volume trajectory: Textiles.
Grade:
Regulatory clearance tiers create rigid stratification between food-contact eligibility and industrial applications.
- Food Grade:Material achieving FDA food-contact notification or EFSA scientific opinion clearance with contaminant thresholds below specified limits. Multi-jurisdiction certification timelines demand 18-24 month validation cycles, delaying revenue recognition for purification investments while commanding premium positioning in North American and European beverage supply chains.
- Industrial Grade:Non-food applications with relaxed purity specifications for fiber and sheet production.
- High Quality:Elevated intrinsic viscosity and color consistency for demanding aesthetic applications.
- Standard Quality:Baseline material for undifferentiated commodity end-uses with cost-driven procurement.
Price differentiation widest between: Food Grade and Industrial Grade. Certification bottleneck tightest at: Food Grade.
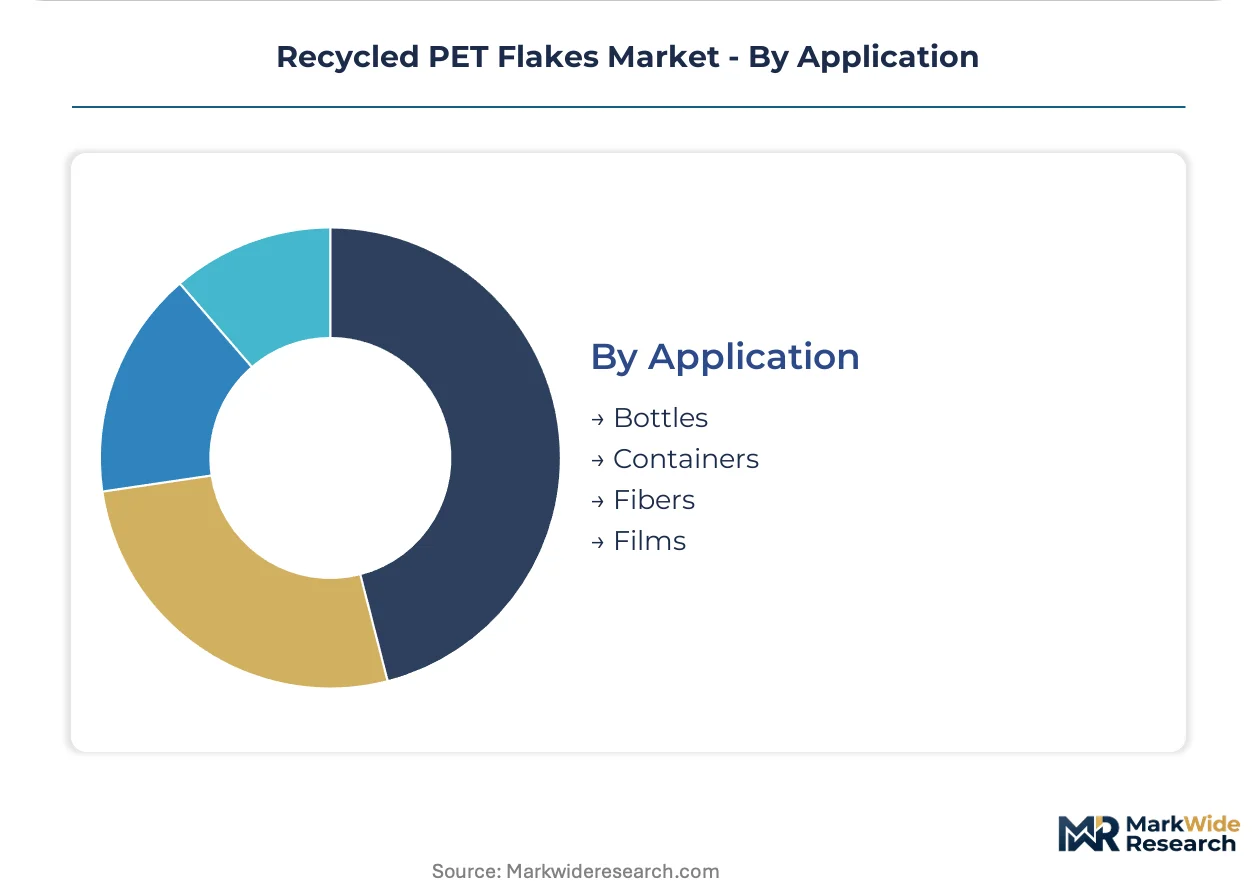
Application:
Container formats impose stricter compliance burdens than film and fiber outputs, fragmenting supplier capabilities.
- Bottles:Blow-molded beverage and personal care containers requiring super-cleaning purification and EFSA or FDA clearance. European bottlers accelerate adoption of these systems to meet binding recycled content thresholds, consolidating supplier bases by excluding smaller processors unable to finance requisite capital expenditure.
- Containers:Jars, tubs, and trays for food and non-food applications with thermoforming specifications.
- Fibers:Staple and filament outputs for textile manufacturing with intrinsic viscosity requirements distinct from packaging grades.
- Films:Sheet and oriented film products for flexible packaging and industrial uses.
Compliance burden heaviest: Bottles. Fastest process innovation: Fibers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of global flake purification capacity while Germany and the United States absorb premium food-grade volumes. This production-consumption divide creates arbitrage flows across Atlantic and Pacific trade lanes. National regulations now determine where capital deploys fastest.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia lock in long-term offtake agreements ahead of EU Green Deal mandates. The country's national packaging regulator enforces binding recycled content thresholds for PET bottles. Düsseldorf and Munich manufacturing clusters concentrate super-cleaning technology investments as smaller processors face exclusion from qualified supply chains.
China
Domestic textile mills in Zhejiang and Jiangsu provinces drive substantial flake demand for polyester fiber production. SAMR enforces GB standards for recycled plastics in domestic packaging applications. The Yangtze River Delta hosts expanding purification capacity as state-owned enterprises accelerate investments under dual carbon goals.
United States
North Carolina and California beverage brands restructure procurement toward fixed-price pellet contracts. FDA food-contact notification requirements govern food-grade flake eligibility for bottle applications. The Southeast manufacturing corridor attracts mechanical recycling investments as EPA frameworks on extended producer responsibility expand bale collection infrastructure.
India
Mumbai and Delhi packaging converters seek imported food-grade flake as BIS recycled plastics regulations tighten domestic standards. The central pollution control board implements evolving national standards for post-consumer material utilization. Maharashtra and Gujarat manufacturing clusters integrate rPET feedstock as multinational brands enforce sustainability pledges across supplier networks.
Brazil
São Paulo and Rio de Janeiro bottlers negotiate buyer consortium arrangements to secure qualified flake supply. ANVISA oversees food-contact safety assessments for recycled plastics in domestic packaging. The Southeast industrial belt concentrates mechanical recycling capacity as brand-led packaging commitments restructure procurement relationships toward long-term agreements.
Recycled PET Flakes Market Key Industry Players
The competitive structure tilts toward integrated petrochemical conglomerates with captive bottle collection networks. Three tiers have emerged: multinational resin producers with backward integration into collection infrastructure, mid-cap specialists focused on food-grade purification, and regional processors serving textile fiber markets. Dominant competitive moves include capacity expansion in high-IV flake production and strategic partnerships between bottlers and purification technology providers.
Within the integrated conglomerate tier, Indorama Ventures Public Company Limited and Alpek S.A.B. de C.V. exemplify scale-driven positioning through multinational flake-to-fiber operations. Evergreen occupies a specialist position in North American food-grade production. Among European purification specialists, PFR Nord GmbH anchors the premium-tier segment. Far Eastern New Century Corporation represents Asia-Pacific capacity expansion. These archetypes reflect how capital requirements and regulatory compliance timelines consolidate supplier bases.
| Leading Market Players |
|---|
| Alpek S.A.B. de C.V. |
| Evergreen |
| Indorama Ventures Public Company Limited |
| PFR Nord GmbH |
| Phoenix Technologies International LLC |
| Far Eastern New Century Corporation |
| Plastipak Holdings Inc. |
| PetStar |
| Alpla Group |
| Others |
Cost & Logistics Intelligence
Multinational beverage brand procurement consortiums in Germany and Brazil anchor pricing power through long-term offtake agreements with fixed-price mechanisms, displacing spot-market volatility for food-grade flake supply. This buyer concentration compresses processor margins while rewarding purification investments that secure multi-jurisdiction certification.
Pricing Analysis
Margin tightening in food-grade flake reflects super-cleaning technology deployment lags and 18-24 month FDA-EFSA-SAMR validation cycles. Contract-based long-term offtake dominates, with price differentiation widest between food-grade and industrial-grade tiers driven by certification burden and intrinsic viscosity thresholds. Cost-down pressure on standard-grade material accelerates because China's domestic purification capacity expansion reduces import dependency. Emerging economy packaging converters exhibit highest price sensitivity, while European beverage bottlers under EU Green Deal mandates show least.
Supply Chain Analysis
Dual-sourcing requirements from multinational brands mandate multi-supplier qualification across China, Germany, and the United States purification networks. Raw material flows draw from post-consumer bale collection in North America and Europe, optical sorting equipment from German and Japanese manufacturers, and super-cleaning technology licenses from European specialists. Single-source vulnerability concentrates in food-grade flake purification capacity as EFSA contaminant thresholds exclude smaller processors. Distribution runs through captive bottle collection networks integrated by resin producers and independent processors serving textile fiber markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU Green Deal recycled content thresholds create a barrier-to-entry moat for processors with validated super-cleaning infrastructure and multi-jurisdiction food-grade clearance.
For Market Incumbents: Acquire optical sorting and super-cleaning technology assets to consolidate supplier bases as EU Green Deal deadlines compress procurement timelines. Defensive positioning requires backward integration into bottle collection networks in Germany and Brazil, locking in bale supply against feedstock price volatility from emerging economy collection infrastructure gaps.
For New Entrants and Emerging Players: Launch via toll-processing arrangements with existing purification facilities to bypass 18-24 month certification timelines. India's emerging BIS packaging standards and brand-led sustainability pledges offer the most penetrable demand node, with Mumbai and Delhi manufacturing clusters seeking imported food-grade flake as domestic standards tighten.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with validated FDA-EFSA food-grade clearance and captive collection infrastructure in high-IV flake production. Long-term viability centers on processors positioned ahead of 2030 compliance deadlines. Watch EPA extended producer responsibility framework implementation as the inflection signal for North American collection infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Alpla Group's captive bottle sourcing secures feedstock supply against bale cost volatility in Brazil and Germany. |
| Super-Cleaning Technology Deployment | Evergreen's food-grade purification investments capture premium positioning with North American beverage customers under FDA notification requirements. |
| Long-Term Offtake Agreement Restructuring | Indorama Ventures' fixed-price contracts with European bottlers lock in volume ahead of EU Green Deal recycled content mandates. |
| Multi-Jurisdiction Certification Investment | PFR Nord GmbH's EFSA-validated capacity commands structural premiums as SAMR and FDA timelines exclude smaller competitors. |
| Chemical Recycling Convergence | Pyrolysis and glycolysis technology partnerships handle degraded PET streams currently routed to lower-margin fiber applications. |
Research Approach
Multi-period observation of flake purification capacity deployment, post-consumer bale supply flows, and brand procurement contract structures anchored the trend analysis, supplemented by interviews with plant managers at mechanical recycling facilities, procurement leads at beverage bottlers, regulatory affairs specialists navigating FDA-EFSA-SAMR frameworks, and distribution channel partners in textile fiber markets. Secondary validation drew from EPA extended producer responsibility filings, EU CSRD disclosure databases, SAMR GB standard updates, customs and trade data on PET waste imports, and SEC 10-K filings from integrated resin producers. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-weighting across product type, end-use, grade, and application dimensions structured the analytical framework, with intrinsic viscosity thresholds and contaminant compliance tiers as industry-specific forecast inputs. CAGRs were derived from capacity deployment timelines against EU Green Deal mandate deadlines and China's dual carbon goal investments. The projection horizon reflects mechanical recycling capacity expansion, chemical recycling technology maturation, and evolving national packaging standards across the analysis window.
Regulatory divergence between FDA, EFSA, and SAMR food-grade timelines, post-consumer collection infrastructure investment shortfalls, and super-cleaning technology deployment bottlenecks are the dominant revision risks to modeled forecasts. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or EPA extended producer responsibility implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Germany Plastics Market