
 Mobile Power Plant Market | 2026-2036
Mobile Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Power Plant Market Analysis
Trailer-mounted gas turbine production in the United States is shifting toward modular, rapid-deploy configurations. General Electric leverages its aeroderivative turbine heritage to dominate high-output mobile units above 30 MW. Siemens AG anchors European supply through its industrial gas turbine division, competing on combined-cycle efficiency in temporary power contracts. Caterpillar sustains channel control across mining and construction segments through its dealer network density in resource-rich geographies.
A mobile power plant is a self-contained, transportable electricity generation system—typically housed in standard shipping containers or on skid-mounted trailers—designed for rapid deployment and grid-independent operation with outputs ranging from 1 MW to over 100 MW depending on turbine or reciprocating engine configuration. Its primary purpose is to deliver reliable baseload or peaking capacity to locations lacking permanent infrastructure or requiring supplemental power during outages, maintenance, or demand surges. Diesel Generators retain the largest installed base across emergency power and construction applications due to capital accessibility and fuel logistics maturity, though Hybrid Systems are gaining fastest in renewable integration deployments where solar-battery-gas turbine combinations reduce fuel consumption and emissions compliance costs. Gas Turbines command premium pricing in utility-scale temporary power contracts where rapid ramp rates and grid-forming capabilities justify higher lease rates.
The EPA enforces Tier 4 Final emissions standards for non-road diesel engines, compelling manufacturers to integrate selective catalytic reduction and diesel particulate filters into mobile generator sets or face market exclusion. The EU F-Gas Regulation constrains fluorinated greenhouse gas use in cooling systems, affecting mobile power plant thermal management designs across European deployments. ISO 8528 governs transient performance and load acceptance criteria, shaping product certification requirements for international tender participation. Stakeholders must monitor evolving carbon border adjustment mechanisms and their interaction with temporary power procurement rules in major mining jurisdictions.
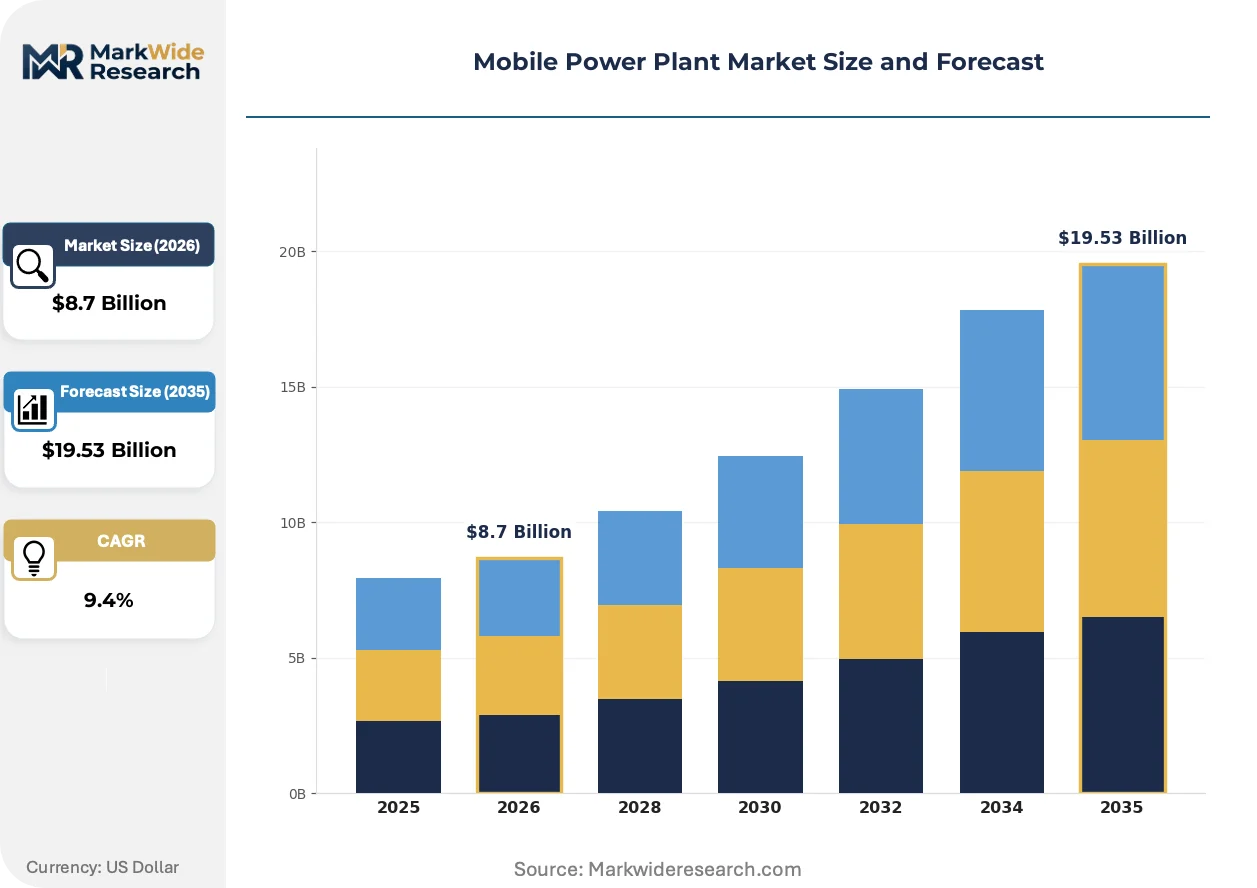
Market Dynamics
Hybrid gas turbine-battery architectures are displacing pure diesel configurations as mining operators face Tier 4 Final compliance deadlines and fuel logistics constraints across remote extraction sites.
Growth Catalysts
- EPA Tier 4 Final mandates:Non-road engine emissions standards force fleet upgrades toward SCR-equipped mobile units, accelerating replacement cycles in North American construction and mining.
- Grid extension economics:Remote resource corridors in Western Australia and Chilean Atacama remain beyond viable transmission reach, sustaining demand for trailer-mounted baseload capacity.
- Lithium-ion cost curves:Battery energy density improvements enable meaningful solar-hybrid integration, reducing fuel transport burdens for islanded operations.
Market Restraints
- Steel and rare earth input volatility:Turbine castings and permanent magnet supply chains concentrate in Chinese and Russian metallurgical facilities, exposing OEMs to price swings and export licensing friction.
- Specialized technician scarcity:Aeroderivative turbine maintenance requires FAA-certified airframe mechanics, a labor pool that does not overlap with conventional power plant operations.
- EU F-Gas cooling constraints:Fluorinated gas phase-down limits thermal management options for high-output mobile units in European temporary power contracts.
Strategic Opportunities
- Indonesian nickel processing expansion:Sulawesi and Halmahera smelter projects lack grid infrastructure, creating demand for 50+ MW mobile baseload during construction phases.
- Carbon border adjustment alignment:EU CBAM implementation incentivizes low-carbon temporary power procurement, favoring hybrid configurations in African and South American mining supply chains feeding European offtake.
- Digital twin integration:Predictive maintenance platforms converge with remote monitoring to unbundle service contracts from equipment leases, opening SaaS revenue streams.
Industry Challenges
- ISO 8528 certification timelines:Transient load acceptance testing for grid-forming mobile units requires specialized test benches, creating bottlenecks for new market entrants.
- Legacy SCADA interoperability:Mining operators demand seamless integration with existing mine-wide control systems, forcing customization that erodes modular cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Power Plant Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Emergency Power, Construction Sites, Renewable Integration, Disaster Relief Technology: Gas Turbines, Diesel Generators, Solar Modules, Hybrid Systems End User: Utilities, Military, Mining, Event Management Deployment: Onshore, Offshore, Remote Locations, Urban Areas |
| Companies Covered | General Electric, Siemens AG, Caterpillar, Cummins, Aggreko, Kawasaki Heavy Industries, APR Energy, PW Power Systems, Mapna Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Power Plant Market Emerging Trajectories
Containerized power electronics and modular turbine packaging are compressing deployment timelines from weeks to days, reshaping competitive differentiation around logistics velocity rather than unit cost alone.
High-frequency power conversion hardware is decentralizing control architectures within mobile power plants. Mining fleet operators in Western Australia adopt these systems to enable seamless island-to-grid synchronization without external switchgear. The technology is decentralizing traditional engineering-procurement-construction contract structures by allowing end-users to self-integrate modular components.
The EU F-Gas Regulation constrains refrigerant selection for turbine inlet cooling systems, forcing thermal design revisions across European deployments. Manufacturers respond with air-cooled alternatives that sacrifice peak output for compliance certainty. Utility-scale temporary power tenders in Germany and Poland now specify F-Gas-free cooling as a mandatory technical qualification.
Power purchase agreements for mobile capacity are fragmenting from multi-year leases toward seasonal or event-based contracting. African mining operators now procure trailer-mounted units through brokered spot markets rather than direct OEM relationships. This pattern concentrates in copper and cobalt extraction corridors where production schedules track commodity price volatility rather than fixed mine plans.
Mobile Power Plant Market Segmentation
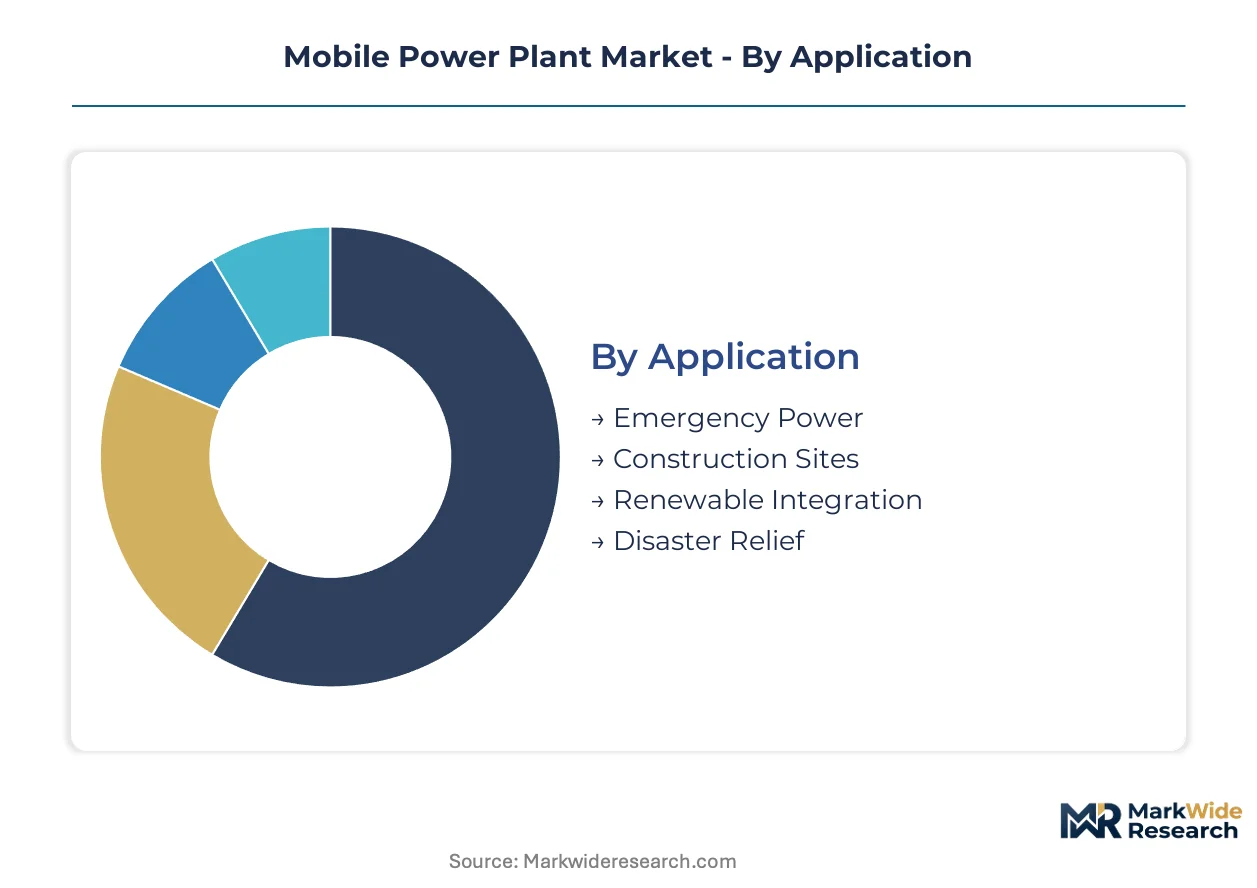
Mobile power plant procurement hinges on fuel logistics, emissions compliance, and deployment velocity. Buyers segment requirements across four dimensions that determine lease rates, technology selection, and contract duration.
Application:
Site-specific power reliability requirements dictate technology choice and rental terms.
- Emergency Power:Hospitals, data centers, and telecommunications facilities deploy trailer-mounted units within four-hour response windows. Grid instability in Texas and California sustains demand for 10-50 MW standby contracts with automatic transfer switches.
- Construction Sites:Civil infrastructure projects across Indonesia and Vietnam rent 1-5 MW diesel sets for 18-36 month build cycles. Tier 4 Final compliance premiums now exceed 15% over Tier 3 legacy fleets.
- Renewable Integration:Solar-wind hybrid buffering for microgrids.
- Disaster Relief:Rapid-deploy containerized units for hurricane and earthquake response.
Volume sits with Construction Sites; growth tilts toward Renewable Integration.
Technology:
Capital intensity and fuel availability shape technology adoption curves.
- Gas Turbines:Aeroderivative units deliver 30-100 MW with sub-10 minute ramp rates. Australian iron ore operators favor these for baseload replacement during transmission outages.
- Diesel Generators:Reciprocating engines dominate sub-10 MW deployments. Brazilian construction rental fleets maintain 70% diesel share due to fuel distribution maturity.
- Solar Modules:Containerized PV with rapid-mount racking.
- Hybrid Systems:Battery-gas turbine combinations reduce fuel transport to remote Chilean copper mines by 40%.
Revenue concentrates in Diesel Generators; Hybrid Systems are climbing the fastest.
End User:
Procurement sophistication varies sharply across buyer categories.
- Utilities:Grid operators in Germany and Poland tender 50-200 MW temporary capacity during peak demand or maintenance outages. Contract terms specify ISO 8528 transient compliance.
- Military:Forward operating bases require silent-running, EMP-hardened units. US Department of Defense specifications drive ruggedized packaging standards.
- Mining:Extraction operators in Western Australia and Chilean Atacama lease 20-60 MW baseload for 5-10 year mine life cycles.
- Event Management:Music festivals and sporting events demand 1-10 MW silent sets with rapid cable deployment.
Contract value peaks with Utilities; Mining delivers the steadiest renewal rates.
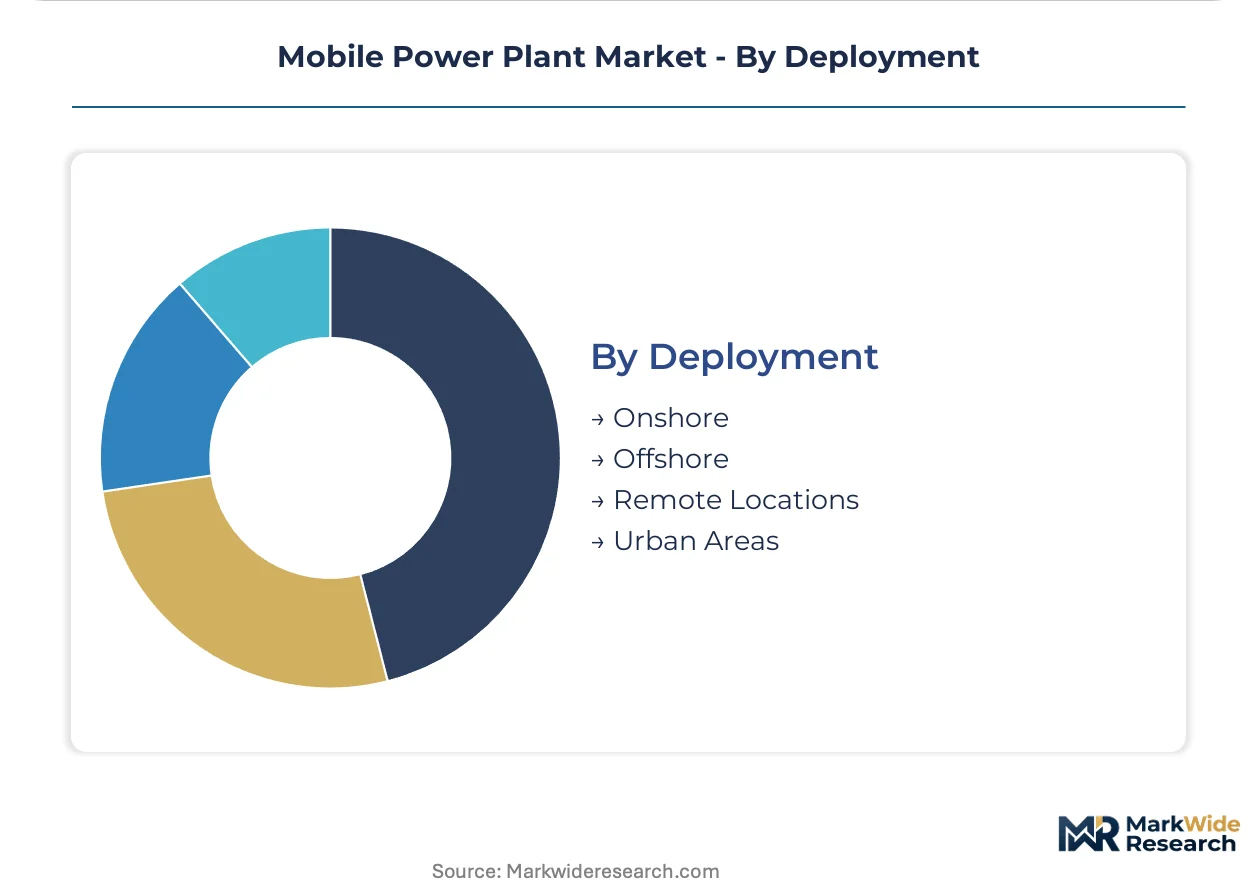
Deployment:
Logistics constraints determine modular packaging and transport mode.
- Onshore:Standard highway-legal trailers serve industrial corridors with road access. Permitting timelines in Germany average 14 days for 50 MW installations.
- Offshore:Platform-mounted gas turbines supply oil and gas production facilities. North Sea operators specify marine-grade corrosion protection.
- Remote Locations:Helicopter-liftable sub-5 MW units access mining exploration camps in Papua New Guinea.
- Urban Areas:Noise-enforced districts require 65 dB enclosures and emissions aftertreatment.
Installation count favors Onshore; margin expansion tracks Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia's Pilbara region anchor mobile power demand across remote extraction corridors. Copper-rich northern Chile sustains trailer-mounted turbine deployments where grid extension remains economically prohibitive. Lithium carbonate processing in Argentina's Salta Province drives hybrid system adoption for islanded smelter operations.
United States
Texas data centers and California utilities sustain 10-50 MW standby contracts during grid instability events. EPA Tier 4 Final mandates force construction fleet upgrades toward SCR-equipped diesel units. Permian Basin oilfield operations deploy rapid-deploy gas turbines for drilling power where pipeline infrastructure lags.
Australia
Western Australia mining operators lease 20-60 MW aeroderivative baseload for 5-10 year iron ore mine life cycles. The country's national environmental regulator enforces strict emissions thresholds for non-road engines in protected areas. Queensland coal seam gas projects use trailer-mounted units during upstream development phases.
Chile
Atacama Desert copper mines reduce fuel transport burdens by 40% through battery-gas turbine hybrid configurations. The Ministry of Energy promotes renewable integration mandates for off-grid mining concessions. Antofagasta and Calama industrial clusters concentrate temporary power procurement for lithium processing expansion.
Indonesia
Sulawesi and Halmahera nickel smelter projects create demand for 50+ MW mobile baseload during construction phases. The country's energy regulator streamlines permitting for captive power in special economic zones. Morowali Industrial Park hosts the densest concentration of trailer-mounted turbine deployments in Southeast Asia.
Germany
Grid operators tender 50-200 MW temporary capacity during peak demand or nuclear maintenance outages. EU F-Gas Regulation constrains refrigerant selection for turbine inlet cooling systems. Industrial clusters in North Rhine-Westphalia specify F-Gas-free cooling as mandatory technical qualification in utility-scale tenders.
Mobile Power Plant Market Vendor Landscape
Global majors compete with regional champions across technology tiers and geographic coverage. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with aeroderivative heritage, specialized rental fleet operators with logistics velocity, and emerging regional fabricators with cost-advantaged manufacturing. Dominant competitive moves include portfolio diversification into hybrid architectures and strategic partnerships for remote service coverage.
Among diversified industrial conglomerates, General Electric and Siemens AG exemplify the premium-tier position anchored by aeroderivative turbine heritage. Caterpillar occupies a position within the rental fleet archetype through dealer network density in resource-rich geographies. These three companies represent the competitive spectrum from high-output utility-scale contracts to construction and mining segment coverage.
| Leading Market Players |
|---|
| General Electric |
| Siemens AG |
| Caterpillar |
| Cummins |
| Aggreko |
| Kawasaki Heavy Industries |
| APR Energy |
| PW Power Systems |
| Mapna Group |
| Others |
Supply Flow & Price Mechanics
Turbine casting alloys and permanent magnet feedstock originate in Chinese and Russian metallurgical facilities before flowing through tiered pricing structures that separate premium OEM supply contracts from spot-market procurement by rental fleet operators. Steel price volatility and rare earth export licensing friction compress margins across mid-tier manufacturers while reinforcing pricing power for vertically integrated conglomerates with captive foundry capacity.
Pricing Analysis
Warranty bundling separates premium-tier OEM offerings from unbundled equipment-only transactions common in brokered spot markets. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 8528 certification grade and after-sales service intensity. Cost compression in economy-tier diesel generator rentals is intensifying because Brazilian and Indonesian construction fleets prioritize capital accessibility over emissions compliance. Mining operators in Western Australia and Chilean Atacama exhibit lowest price sensitivity due to fuel logistics constraints that dominate total cost of ownership.
Supply Chain Analysis
Indonesian domestic-content mandates for nickel processing infrastructure are reshaping sourcing patterns for Sulawesi and Halmahera smelter power projects. Turbine castings and power electronics concentrate in China, Germany, and Japan. Permanent magnets for high-efficiency generators draw from Chinese rare earth processing and Vietnamese assembly. Single-source vulnerability in aeroderivative turbine blade supply creates exposure to export licensing friction. Distribution runs through OEM direct sales for utility-scale contracts and specialized rental fleet operators for construction and mining segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around hybrid technology capabilities as EPA Tier 4 Final and EU F-Gas Regulation compliance costs force pure-play diesel specialists toward exit or acquisition.
For Market Incumbents:Acquire battery integration and power electronics engineering teams to fortify against pure-diesel fleet obsolescence. Secure FAA-certified airframe mechanic training pipelines to resolve aeroderivative maintenance scarcity. Backward integration into permanent magnet supply hedges Chinese export licensing risk.
For New Entrants and Emerging Players:EU F-Gas Regulation in Germany and Poland opens a window for air-cooled turbine inlet cooling specialists to capture utility-scale temporary power tenders. Target Indonesian nickel smelter construction phases where 50+ MW mobile baseload demand outpaces established OEM deployment capacity. Partner with regional EPC contractors to bypass entrenched dealer networks.
For Investors and Strategic Acquirers:Fragmentation from multi-year leases toward seasonal spot contracting in African copper and cobalt corridors is the leading indicator that asset-light SaaS-enabled remote monitoring platforms will outperform pure equipment lessors. Target mid-cap rental fleet operators with dense Western Australia or Chilean Atacama coverage. Watch for mobile power procurement migrating to brokered spot markets as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Battery-gas turbine combinations reduce fuel transport burdens for Chilean copper mines. |
| Backward Integration into Magnets | Captive rare earth supply hedges Chinese export licensing exposure for turbine OEMs. |
| Digital Twin Platform Launch | Predictive maintenance SaaS unbundles service contracts from equipment leases. |
| F-Gas-Free Cooling Certification | Air-cooled turbine designs qualify for mandatory German and Polish utility tenders. |
| Remote Service Partnership | FAA-certified mechanic networks resolve aeroderivative maintenance scarcity in Australia. |
Methodological Framework
Document review covered EIA power generation statistics, EPA enforcement actions, EU F-Gas Regulation implementation guidance, and mining sector procurement databases, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Secondary validation drew from FERC interconnection queues, IEA renewable integration reports, and customs trade data for turbine component flows. Bottom-up unit deployment tracking and top-down market sizing were triangulated against OEM revenue disclosures.
Historical deployment patterns across the analysis window were cross-referenced against expert panel input from grid operators and mining procurement directors. The forecast framework modeled fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs included lithium-ion cost curve trajectories and EPA enforcement intensity projections.
Caveats apply where battery chemistry cost breakthroughs or carbon border adjustment mechanism expansion could materially shift the outlook toward accelerated hybrid adoption or stranded diesel assets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Power Generation Technologies Market
Power Generation
Oman Power Market
Power Generation
India Gensets Market
Power Generation
Canada Power EPC Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
United Kingdom Power Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Captive Power Plant Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Wind Power EPC Market
Power Generation
Solar Generator Market
Power Generation
LAMEA Microturbine Market
Power Generation
Malaysia Power Market
Power Generation
Global Gensets Market