
 Power Generation Technologies Market | 2026-2036
Power Generation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Power Generation Technologies Market Analysis
The capital-intensity gap between integrated turbine manufacturers and modular solar suppliers is collapsing as project finance models shift toward smaller, distributed assets. General Electric Company leverages its deep vertical integration in gas turbine servicing to sustain aftermarket revenue streams even as new-build orders soften. Siemens AG anchors its competitiveness through digital twin platforms that optimize fleet performance across utility customers. Mitsubishi Heavy Industries differentiates via hydrogen-ready gas turbine development, positioning its technology for fuel-switching scenarios.
Power generation technologies encompass the engineered systems, prime movers, and balance-of-plant equipment that convert primary energy sources into grid-deliverable electricity, with thermal efficiencies ranging from sub-30% for simple-cycle gas turbines to above 60% for combined-cycle configurations and capacity factors varying dramatically by resource availability. These technologies serve industrial facilities, municipal utilities, and independent power producers seeking dispatchable or renewable output. Solar and wind equipment now dominates capacity additions, with turbine and panel supply chains experiencing margin compression from manufacturing scale races. Utility-scale application segments command the largest project values, though residential solar-plus-storage systems are expanding addressable market boundaries through third-party ownership structures.
The EPA enforces emissions standards under the Clean Air Act that constrain new fossil-fired plant permitting, while FERC Order 2222 enables distributed energy resource aggregation in wholesale markets, reshaping how small-scale generators access revenue streams. ISO 50001 energy management standards and IEC renewable equipment certification protocols further condition product acceptance and bankability. Stakeholders must track how interconnection queue reforms and transmission planning rules determine which power capacity classes can achieve commercial operation timelines.
Market Dynamics
The power generation technologies market is experiencing a fundamental restructuring as data center operators deploy on-site generation assets to secure baseload power against grid instability and interconnection delays.
Growth Catalysts
- EU Green Deal carbon border adjustments:These mechanisms tighten emissions benchmarks for imported electricity equipment, accelerating demand for low-carbon generation technologies across European procurement chains.
- India's state-level renewable purchase obligations:State mandates are accelerating utility-scale solar and wind procurement, creating concentrated demand pull for turbine and panel manufacturers.
- Hydrogen-ready gas turbine development:Fuel-switching capabilities in new turbine designs are extending asset lifespans and protecting capital investments against future fuel price volatility.
Market Restraints
- Polysilicon supply concentration:Solar panel manufacturing depends on polysilicon refining capacity concentrated in specific geographies, exposing project developers to input cost volatility and trade policy disruptions.
- FERC interconnection queue backlogs:Transmission access delays in US wholesale markets extend project development timelines and increase carrying costs for capital-intensive generation assets.
- Combined-cycle thermal efficiency ceilings:Gas turbine technology approaches theoretical efficiency limits above 60%, constraining further performance differentiation among competing OEMs.
Strategic Opportunities
- Third-party ownership structures for residential solar-plus-storage:Financial innovation in customer acquisition models is expanding addressable market boundaries beyond traditional utility-scale segments.
- Digital twin platform deployment:Fleet optimization software creates recurring revenue streams and deepens vendor lock-in across utility customer bases.
- India's utility-scale procurement acceleration:State-level tendering activity is concentrating demand for turnkey EPC services and long-term O&M contracts.
Industry Challenges
- Grid code compliance certification timelines:Evolving IEEE 1547 and IEC 61400 standards require extensive testing protocols that delay commercial operation dates for inverter and turbine suppliers.
- Aftermarket technical workforce scarcity:Specialized turbine servicing expertise concentrates among aging technician cohorts, constraining OEM capacity to sustain service revenue growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Generation Technologies Market |
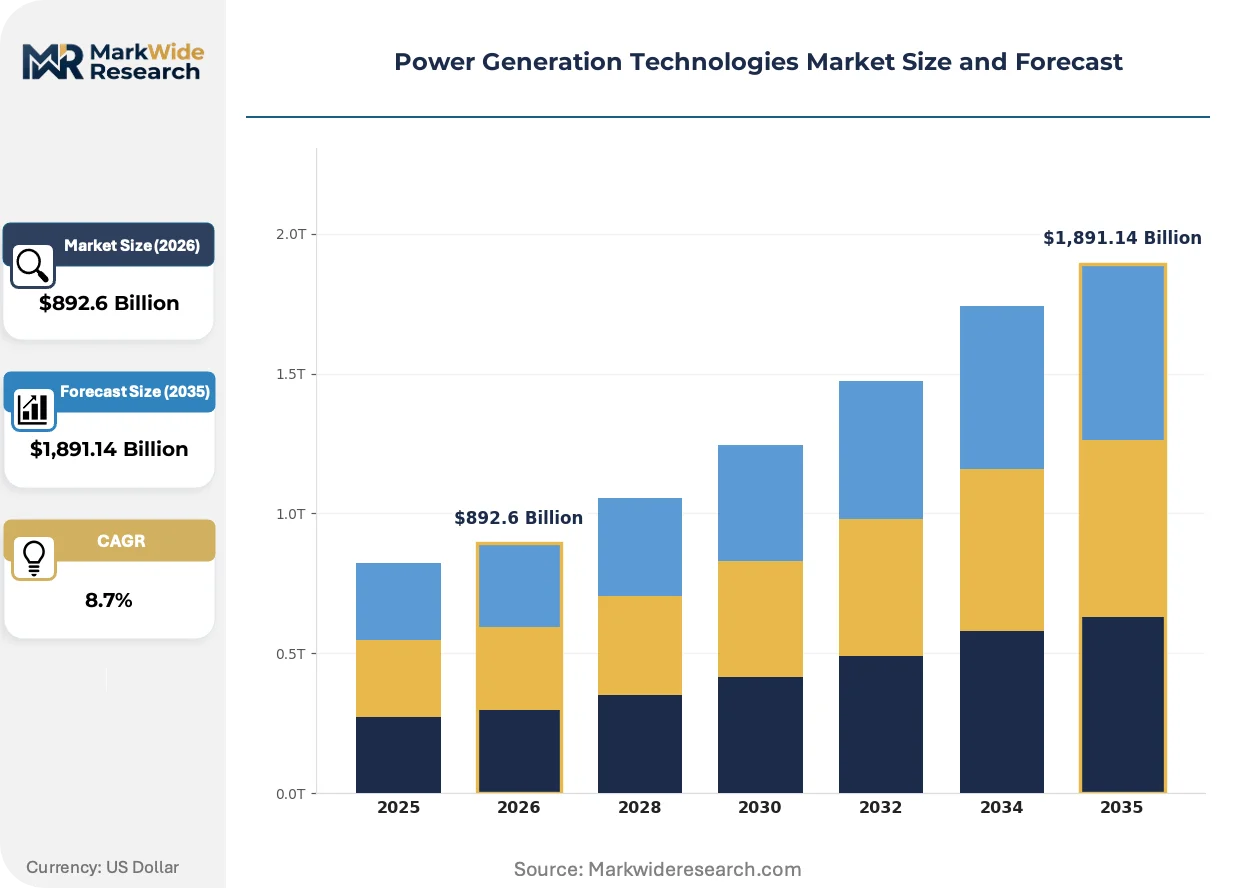
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,891.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Hydro, Biomass Application: Commercial, Residential, Industrial, Utility Equipment Type: Turbines, Panels, Generators, Inverters Power Capacity: Small-Scale, Medium-Scale, Large-Scale, Gigawatt |
| Companies Covered | General Electric Company, Siemens AG, Mitsubishi Heavy Industries, Vestas Wind Systems, Andritz AG, Caterpillar, Cummins, Alstom, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Generation Technologies Market Emerging Trajectories
Solid-state power electronics and modular system architectures are compressing equipment footprints while enabling faster deployment cycles for distributed generation projects.
Silicon carbide power semiconductors are replacing traditional silicon IGBTs in solar inverters and wind turbine converters, enabling higher switching frequencies and reduced thermal losses. Data center operators in Virginia and Texas are specifying SiC-based equipment for new on-site generation installations. The technology is miniaturizing inverter enclosures and reducing balance-of-plant footprint requirements by 30-40% compared to conventional designs.
The EPA's Clean Air Act emissions standards constrain new fossil-fired plant permitting timelines, particularly for simple-cycle gas turbines in non-attainment zones. Developers face extended environmental review processes that compress project finance windows and increase development risk premiums. Combined-cycle configurations in Texas and Louisiana are responding by front-loading emissions control engineering to secure construction permits before regulatory thresholds tighten.
Power purchase agreement structures are unbundling energy and capacity attributes, allowing commercial and industrial buyers to optimize procurement against specific load profiles. Virtual power purchase agreements are displacing traditional physical PPAs for corporate renewable energy buyers seeking geographic flexibility. This contract innovation is most visible in technology sector procurement concentrated in Northern Virginia and Silicon Valley data center clusters.
Power Generation Technologies Market Segmentation
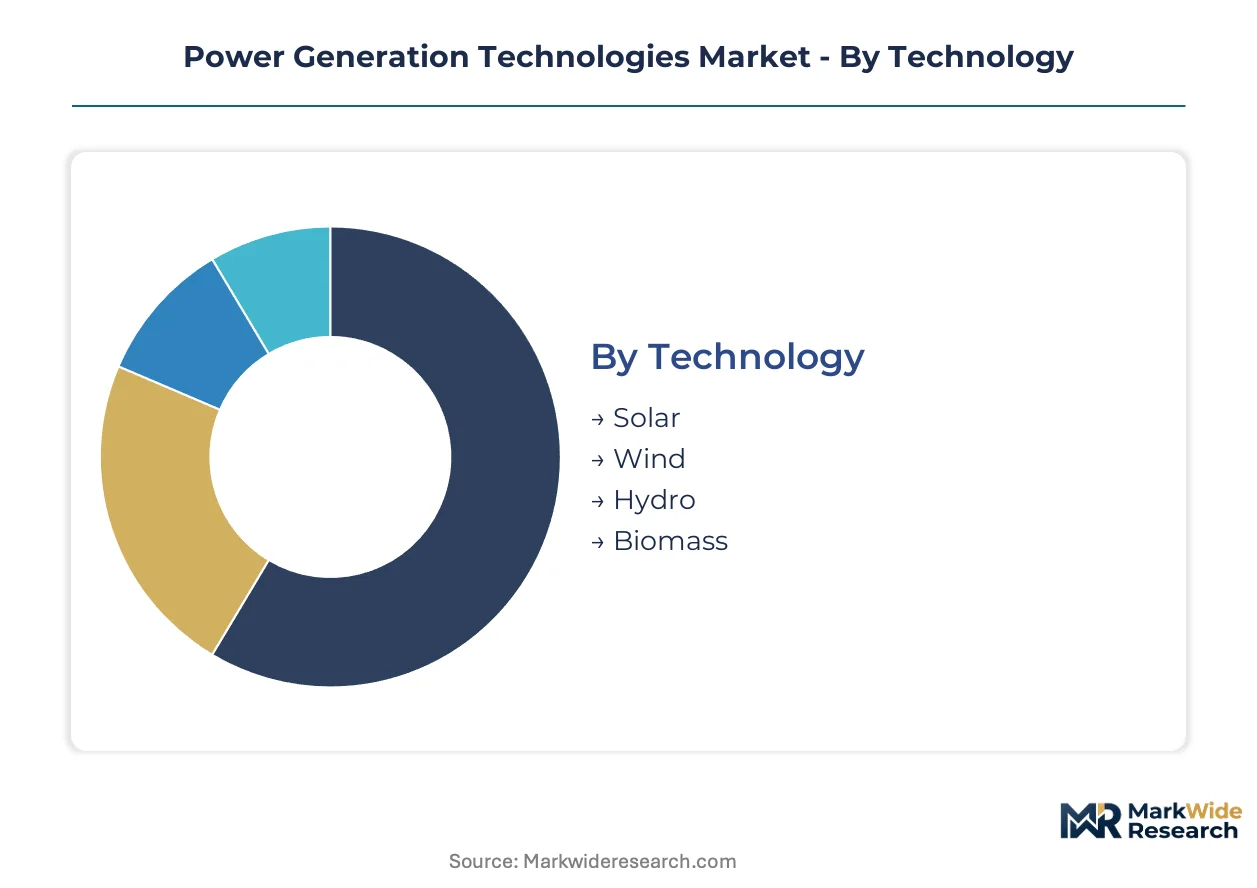
Technology and application boundaries in power generation are blurring as distributed assets penetrate customer premises and utility-scale procurement concentrates in specific geographies. Channel strategy now determines which segments capture margin versus volume.
Technology:
Solar and wind equipment flows through EPC contractors and direct OEM sales to utility buyers, while hydro and biomass technologies rely more heavily on specialized engineering firms and regional development banks.
- Solar:Photovoltaic panels and concentrated solar thermal systems convert irradiance into direct current electricity with silicon or thin-film semiconductor architectures. Utility-scale procurement in India and distributed rooftop installations in Germany and Australia are pulling crystalline silicon module demand through diverging channel structures.
- Wind:Horizontal-axis turbines with doubly-fed induction generators or direct-drive permanent magnet systems harvest kinetic energy at 80-120 meter hub heights. Onshore repowering in the United States and new offshore auctions in the United Kingdom are concentrating nacelle and blade orders among turnkey suppliers capable of marine logistics.
- Hydro:Run-of-river and pumped-storage configurations leverage gravitational potential through Francis, Kaplan, or Pelton turbine designs. Run-of-river projects in Norway and Switzerland continue adding capacity through alpine watercourse development.
- Biomass:Combustion, gasification, and anaerobic digestion systems process organic feedstocks into dispatchable thermal or electrical output. Agricultural residue plants in Brazil and municipal waste facilities in Sweden anchor equipment demand for grate-fired boilers and organic Rankine cycle generators.
Solar dominates installed base. Wind is where expansion concentrates.
Application:
Customer type shapes procurement authority and contract structure, with utilities aggregating volume and commercial buyers driving contract innovation.
- Commercial:Office buildings, retail centers, and logistics facilities deploy rooftop solar, fuel cells, and combined heat and power systems under power purchase agreements or direct ownership. Data center operators in Northern Virginia and Texas are scaling on-site generation to bypass interconnection delays.
- Residential:Single-family and multi-family dwellings adopt solar-plus-storage through third-party ownership or cash purchase. Third-party lease and loan products in California and Arizona are expanding addressable market boundaries beyond creditworthy homeowners.
- Industrial:Manufacturing plants and processing facilities require dispatchable baseload with high capacity factors. Petrochemical complexes in Texas and aluminum smelters in Iceland prioritize combined-cycle gas turbines and geothermal hookups for process heat and electricity.
- Utility:Centralized power plants and grid-scale renewable farms sell into wholesale markets under regulated cost-of-service or competitive merchant structures. State-level renewable purchase obligations in India are accelerating tendering activity for turnkey EPC services.
Utility applications command project value concentration. Commercial segments are climbing the fastest.
Equipment Type:
Manufacturing scale and supply concentration vary dramatically across component categories, compressing margins in commoditized segments while preserving pricing power in precision-engineered systems.
- Turbines:Gas, steam, and wind turbine assemblies convert fluid energy into rotational mechanical power with blade or bucket geometries optimized for specific thermodynamic conditions. Hydrogen-ready gas turbine development by Mitsubishi Heavy Industries and Siemens AG is extending asset lifespans against future fuel-switching scenarios.
- Panels:Crystalline silicon and thin-film photovoltaic modules encapsulate semiconductor junctions between glass and polymer backsheet layers. Polysilicon supply concentration in specific geographies exposes project developers to input cost volatility and trade policy disruptions.
- Generators:Synchronous and asynchronous machines convert mechanical torque into grid-frequency alternating current through electromagnetic induction. Large-frame generators for combined-cycle plants maintain procurement cycles tied to utility capital expenditure timelines.
- Inverters:Power electronic converters transform direct current output from solar arrays and batteries into grid-synchronous alternating current. Silicon carbide semiconductors are replacing traditional silicon IGBTs, enabling higher switching frequencies and reducing thermal losses by 30-40%.
Panels dominate manufacturing volume. Inverters are gaining share fastest.
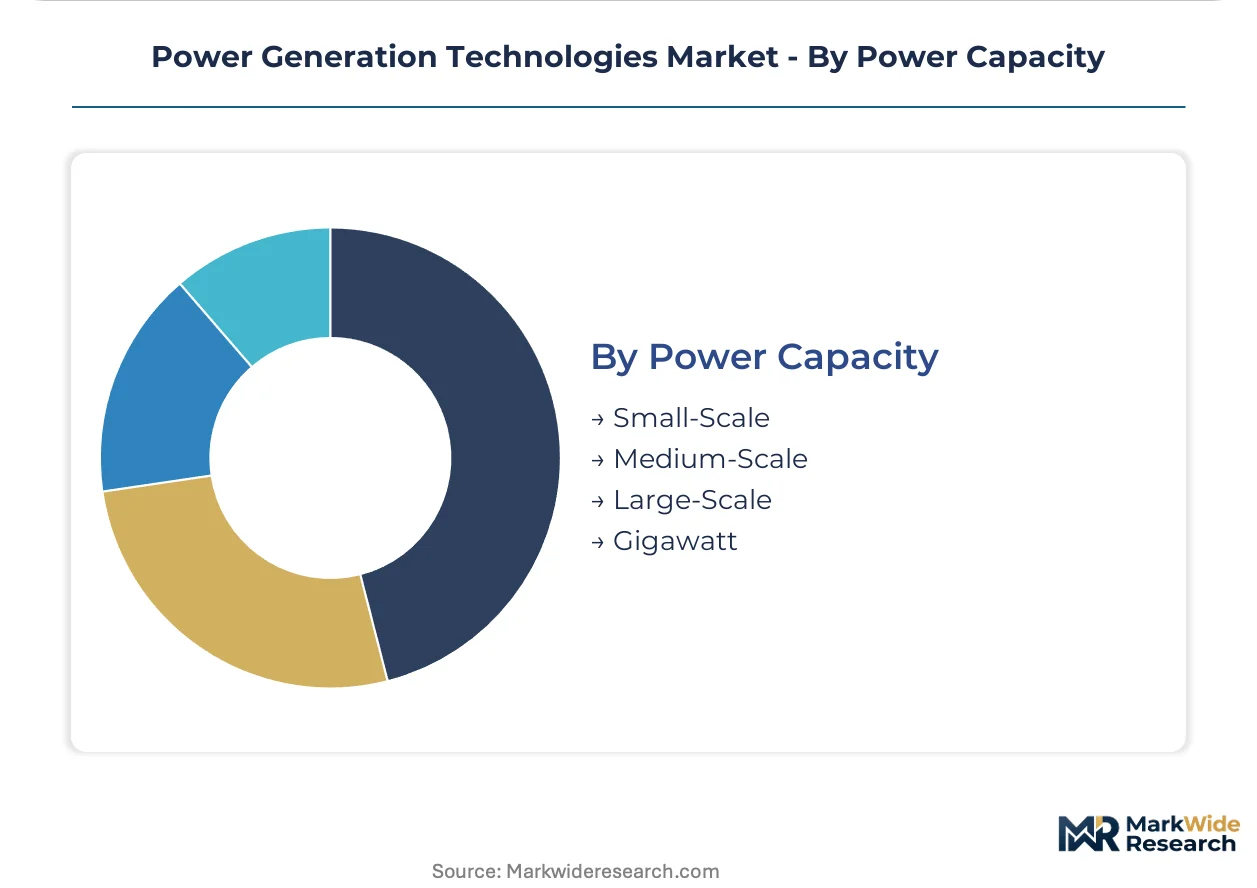
Power Capacity:
Project finance structures and development risk profiles stratify sharply by capacity class, with smaller assets accessing distributed energy resource aggregation and larger plants facing extended permitting timelines.
- Small-Scale:Sub-megawatt installations serve individual buildings or isolated microgrids with simplified interconnection standards. Residential solar-plus-storage in Germany and Australia leverages streamlined permitting for rooftop systems under 10 kilowatts.
- Medium-Scale:One to fifty megawatt projects serve commercial campuses, industrial parks, and community solar subscribers. Commercial and industrial buyers in the United States are unbundling energy and capacity attributes through virtual power purchase agreements.
- Large-Scale:Fifty to five hundred megawatt facilities compete in wholesale markets with dedicated transmission access. FERC Order 2222 enables distributed energy resource aggregation, reshaping how mid-sized generators access revenue streams.
- Gigawatt:Multi-gigawatt complexes require decade-long development timelines and coordinated transmission expansion. Interconnection queue backlogs in US wholesale markets extend project development timelines and increase carrying costs for these capital-intensive assets.
Large-Scale commands development expenditure. Small-Scale is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India exhibit the highest price elasticity as state tenders drive module costs toward marginal production levels, while data center operators in Northern Virginia and Texas absorb substantial premiums to bypass interconnection delays.
United States
Data center clusters in Northern Virginia and Texas are scaling on-site generation to secure baseload power against grid instability and FERC interconnection queue backlogs. The EPA enforces Clean Air Act emissions standards that constrain new fossil-fired plant permitting timelines, particularly for simple-cycle gas turbines in non-attainment zones. Developers in Texas and Louisiana front-load emissions control engineering to secure construction permits before regulatory thresholds tighten.
India
State-level renewable purchase obligations are accelerating utility-scale solar and wind procurement, creating concentrated demand pull for turbine and panel manufacturers. The Central Electricity Authority coordinates interstate transmission planning to integrate variable renewable capacity from Rajasthan and Gujarat into national load centers. Manufacturing clusters in Tamil Nadu and Karnataka are expanding crystalline silicon module assembly capacity to serve domestic content requirements under the PLI scheme.
Germany
Industrial facilities in the Rhine-Ruhr and Bavaria regions prioritize dispatchable generation to maintain process continuity amid grid volatility. The EU Green Deal carbon border adjustments tighten emissions benchmarks for imported electricity equipment, accelerating demand for low-carbon generation technologies across European procurement chains. Siemens AG anchors its competitiveness through digital twin platforms that optimize fleet performance across utility customers in the German market.
China
Polysilicon refining capacity concentrated in Xinjiang and Inner Mongolia exposes project developers to input cost volatility and trade policy disruptions. The Ministry of Ecology and Environment enforces dual carbon goals that constrain new coal-fired plant approvals while accelerating renewable manufacturing scale. Yangtze River Delta industrial parks are integrating silicon carbide power semiconductor production for inverter and converter applications.
Brazil
Agricultural residue plants in São Paulo and Minas Gerais anchor equipment demand for grate-fired boilers and organic Rankine cycle generators. ANVISA regulates biomass feedstock quality standards for municipal waste facilities, conditioning project bankability for anaerobic digestion systems. Run-of-river hydro development continues in the Amazon basin and southern highlands through alpine watercourse configurations.
Power Generation Technologies Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap between integrated turbine manufacturers and modular solar suppliers collapsing as project finance models shift toward smaller, distributed assets. The market stratifies across three archetypes: vertically integrated OEMs with deep aftermarket service networks, pure-play renewable equipment specialists, and diversified industrial conglomerates with captive power generation divisions. Competitive moves concentrate on digital twin platform deployment for fleet optimization and hydrogen-ready turbine development to extend asset lifespans against fuel-switching scenarios.
Among European-based integrated OEMs, General Electric Company and Siemens AG exemplify the vertically integrated archetype with established utility customer relationships, while Mitsubishi Heavy Industries occupies a position within the diversified industrial tier. These entities represent contrasting strategic postures: GE leverages deep servicing integration to sustain aftermarket revenue streams, Siemens anchors competitiveness through software-driven fleet optimization, and Mitsubishi Heavy Industries differentiates via fuel-flexible turbine architectures positioning for hydrogen transition scenarios.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| Mitsubishi Heavy Industries |
| Vestas Wind Systems |
| Andritz AG |
| Caterpillar |
| Cummins |
| Alstom |
| ABB |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with utility buyers lock in polysilicon supply access and price visibility for solar module manufacturers, insulating project developers from spot market volatility in Xinjiang-sourced raw materials while compressing margins for non-integrated assemblers competing on procurement flexibility.
Pricing Analysis
Aftermarket service contracts and spare parts provisioning drive lifetime value for gas turbine OEMs, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and geographic proximity to servicing hubs. Cost compression in crystalline silicon modules is intensifying because manufacturing scale races in India and Southeast Asia expand effective supply. Utility-scale buyers in India exhibit the highest price elasticity as state tenders push module costs toward marginal production levels, while data center operators in Northern Virginia and Texas absorb substantial premiums to secure baseload power against interconnection delays.
Supply Chain Analysis
Inventory cycles for silicon carbide wafers and power semiconductor substrates extend lead times for inverter manufacturers, with polysilicon refining concentrated in Xinjiang and Inner Mongolia and precision turbine blade casting anchored in Japan and Germany. Component sourcing draws from rare earth magnet suppliers in China for direct-drive wind generators and high-grade steel mills in South Korea for combined-cycle pressure vessels. Single-source vulnerability in polysilicon purification exposes solar supply chains to trade policy disruptions. Distribution runs through EPC contractors for utility-scale projects and direct OEM channels for commercial and industrial on-site generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power generation technologies market rewards specialized technical capabilities that concentrate among aging technician cohorts and precision manufacturing assets, creating durable scarcity premiums for firms controlling hydrogen-ready turbine architectures or silicon carbide semiconductor fabrication.
For Market Incumbents: Secure aftermarket technical workforce pipelines through apprenticeship partnerships with regional technical institutes, protecting service revenue streams against technician retirement waves. Deepen backward integration into polysilicon refining or precision casting to defend margin position against supply cost volatility and emerging low-cost assemblers. For New Entrants and Emerging Players: Remote monitoring and predictive maintenance software layers represent under-served service gaps where incumbents lack digital-native capabilities, creating entry points for fleet optimization platforms targeting mid-scale commercial and industrial generators. Target India's utility-scale EPC services market through turnkey O&M contracts, leveraging domestic content requirements under the PLI scheme to establish local presence before module manufacturing saturates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital twin platform providers and long-term service contractors, offering superior cash flow predictability against cyclical equipment sales. Long-term viability favors acquisition targets with hydrogen-ready turbine development pipelines or silicon carbide inverter manufacturing capabilities. Watch FERC interconnection queue reform progress as the critical inflection signal for distributed generation asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Siemens AG leverages fleet optimization software to deepen vendor lock-in across German utility customers. |
| Hydrogen-Ready Turbine Development | Mitsubishi Heavy Industries extends asset lifespans against fuel-switching scenarios in EU Green Deal compliance markets. |
| Silicon Carbide Semiconductor Scale-Up | Yangtze River Delta production integration reduces thermal losses for data center on-site generation specifications. |
| Third-Party Ownership Structure Expansion | Residential solar-plus-storage in California and Arizona broadens addressable market beyond creditworthy homeowner segments. |
| Domestic Module Assembly Capacity Buildout | Tamil Nadu and Karnataka manufacturing clusters serve Indian PLI scheme content requirements for state tender participation. |
Methodological Framework
The analysis maps gas turbine servicing networks, solar module supply chains, and inverter manufacturing clusters, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews combined with EIA data, IEA reports, FERC filings, and project development databases for secondary triangulation. Bottom-up capacity installation tracking and top-down macroeconomic scenario modeling ensure cross-verification.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon, with segmentation modeling covering fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from historical deployment trajectories, policy incentive durability assessments, and technology cost curve extrapolations, incorporating interconnection queue reform timelines and carbon border adjustment implementation schedules as industry-specific forecast inputs.
Underlying assumptions cover policy incentive continuity, supply chain trade policy stability, and technology cost reduction trajectories, with deviation risk concentrated in FERC regulatory reform timing and EU carbon border adjustment enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Distributed Generation Market
Power Generation
South America Thermal Power Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Gas Gensets Market
Power Generation
South East Asia Power Market
Power Generation
Distributed Power Generation Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Iraq Power EPC Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Microturbine Market
Power Generation
Europe Thermal Power Market
Power Generation
India Thermal Power Plant Market