
 South Korea Combined Heat and Power Market | 2026-2036
South Korea Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Combined Heat and Power Market Analytics
The gap between premium efficiency gas turbine installations and standard reciprocating engine packages is expanding as energy-intensive buyers prioritize total cost of ownership over upfront capital. KEPCO Engineering & Construction Co. Inc. leverages its utility parent relationships to dominate turnkey power plant contracts. GS E&R Corp. anchors its position through captive natural gas supply and downstream heat offtake agreements. Siemens Energy AG differentiates via advanced aeroderivative turbine technology optimized for hydrogen cofiring ratios.
Combined heat and power denotes integrated systems that simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving overall efficiencies of 75-85% through waste heat recovery boilers or absorption chillers. Gas turbine technology leads installed capacity due to superior power-to-heat ratios in large industrial applications, while reciprocating engine segments gain traction in commercial microgrid configurations where modularity and fast ramp rates matter. District heating installations command stable margin pools from long-term municipal concessions, whereas on-site industrial cogeneration faces shorter replacement cycles and fuel price volatility.
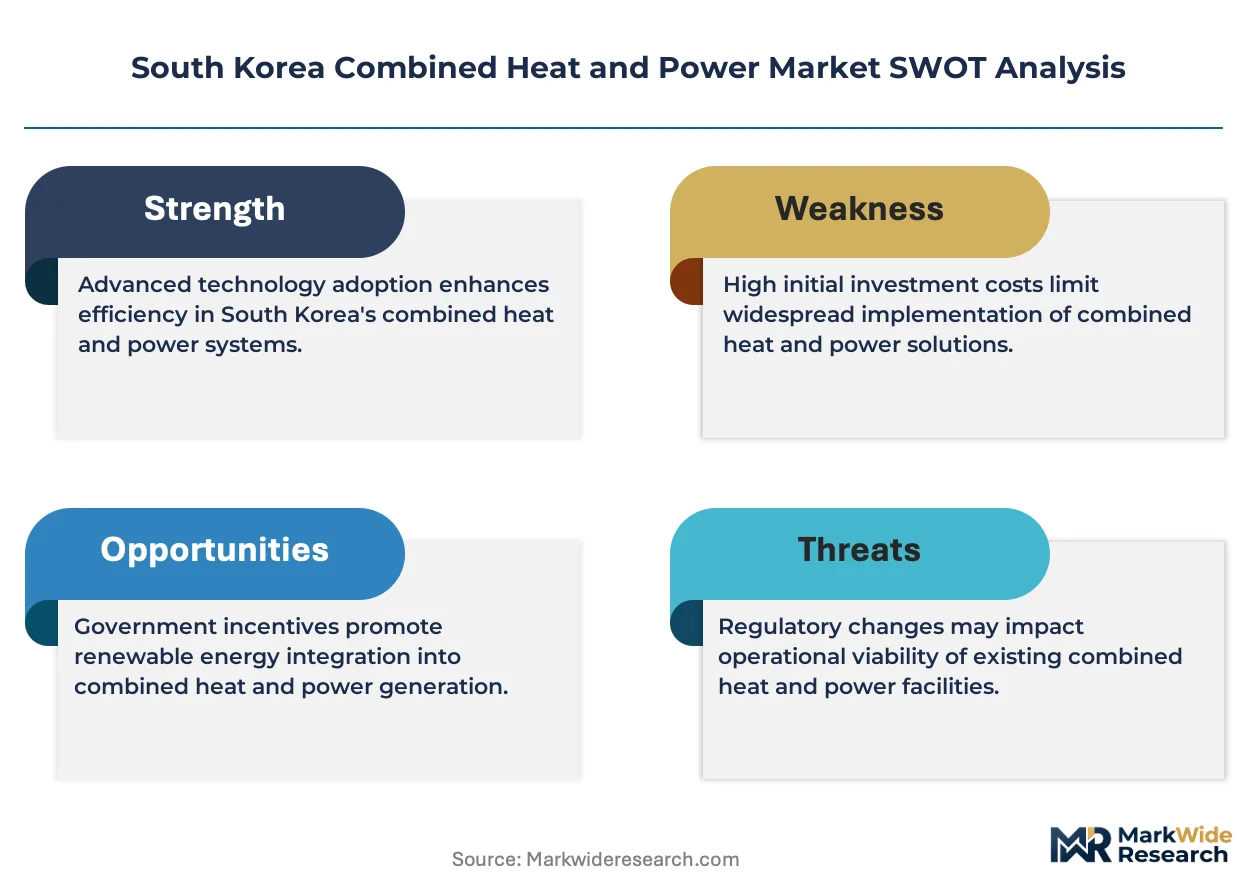
MFDS equipment safety standards, KEEA grid interconnection codes, and MOTIE renewable energy certificates collectively shape technology selection and project economics for new CHP deployments. South Korea's national hydrogen roadmap and building energy codes are tightening emission thresholds, pushing existing operators toward fuel switching or carbon capture retrofits. Stakeholders must weigh hydrogen infrastructure readiness against the operational flexibility of dual-fuel turbine investments as the policy framework tightens.
Market Dynamics
MFDS equipment safety standards and MOTIE renewable energy certificates are compressing technology selection windows, forcing operators to commit to hydrogen-ready turbine configurations before pipeline infrastructure matures.
Growth Catalysts
- Industrial Cluster Thermal Demand:Petrochemical complexes in Ulsan and Yeosu anchor baseload heat offtake, creating captive demand for large-scale gas turbine installations with guaranteed utilization rates.
- Hydrogen Blending Mandates:South Korea's national hydrogen roadmap requires progressive cofiring ratios in new generation assets, positioning dual-fuel turbines as compliant long-term investments.
- District Heating Network Expansion:Seoul metropolitan area and Gyeonggi province municipal concessions offer stable 20-year revenue streams for combined cycle heat and power operators.
Market Restraints
- Liquefied Natural Gas Price Volatility:Import dependency through three primary terminals exposes operators to JKM-linked fuel cost swings that erode project IRR calculations.
- KEPCO Grid Interconnection Queues:KEEA certification timelines and utility dispatch prioritization create 18-24 month connection delays for non-utility generators.
- Battery Energy Storage Substitution:Lithium-ion systems paired with renewable PPAs capture peak shaving revenue streams previously reserved for fast-ramp reciprocating engine CHP.
Strategic Opportunities
- Data Center Heat Offtake Partnerships:Hyperscale cloud facilities in Pangyo and Busan seek reliable thermal sinks for cooling loads, enabling trigeneration configurations with absorption chillers.
- Green Hydrogen Electrolyzer Integration:Surplus renewable generation curtailment creates arbitrage potential for electrolyzer-fed hydrogen storage feeding turbine cofiring systems.
- Building Energy Code Tightening:Ministry of Land, Infrastructure and Transport efficiency mandates for commercial structures above 10,000 square meters expand on-site generation compliance pathways.
Industry Challenges
- Hydrogen Turbine Retrofit Engineering:Existing Frame 6B and 7E installations require combustor redesign and fuel system upgrades to achieve 30% cofiring targets without derating.
- MFDS Pressure Equipment Certification:Waste heat recovery boiler inspections and safety valve recertification cycles impose 45-60 day planned outages that disrupt continuous industrial process heat contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Combined Heat and Power Market |
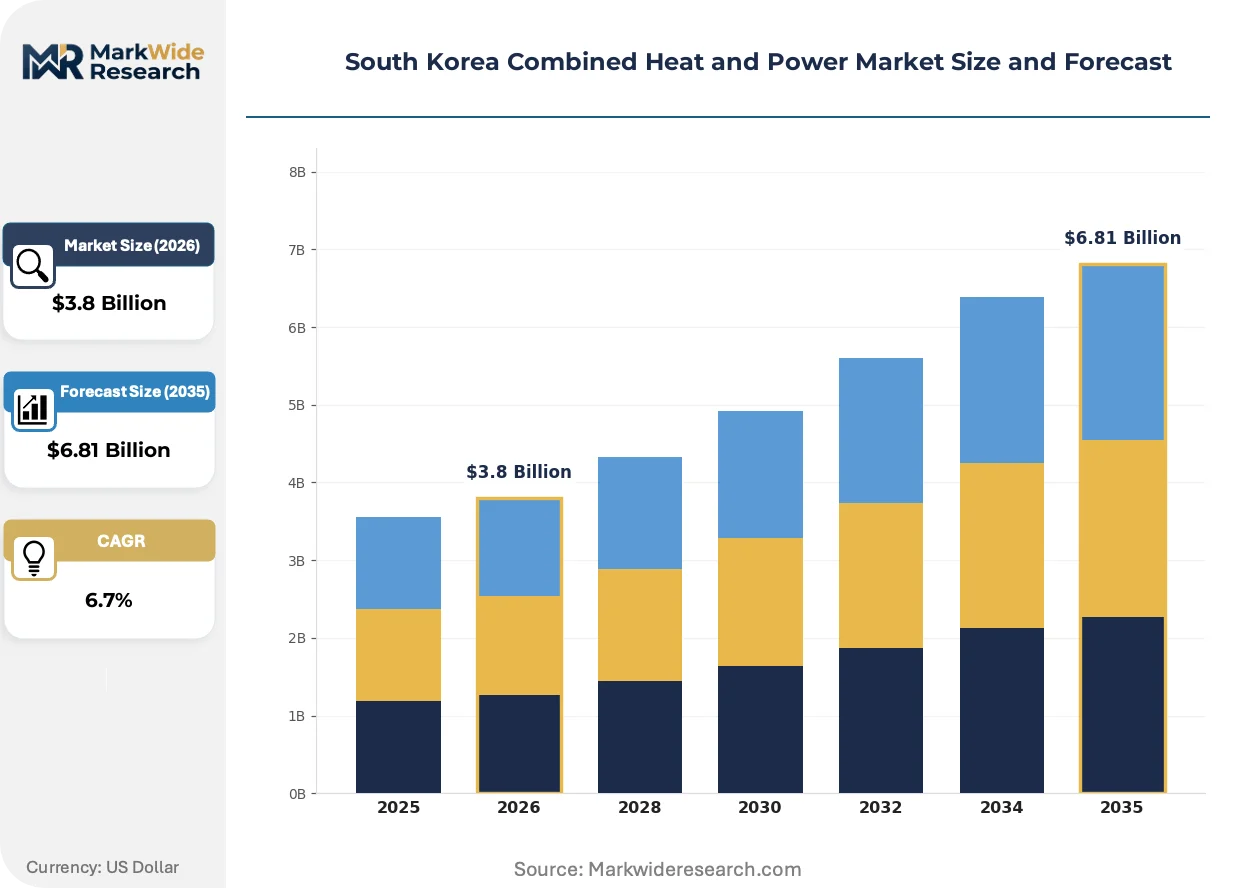
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Reciprocating Engine, Micro Turbine End User: Industrial, Commercial, Residential, Institutional Installation Type: On-site, District Heating, Cogeneration Plant, Microgrid Fuel Type: Natural Gas, Biogas, Diesel, Biomass |
| Companies Covered | KEPCO Engineering & Construction Co. Inc., GS E&R Corp., Korea District Heating Engineering Co. Ltd, Hanwha Engineering & Construction Corp., Mitsubishi Heavy Industries Ltd, Siemens Energy AG, General Electric Company, Kawasaki Heavy Industries Ltd, Wärtsilä Oyj Abp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Combined Heat and Power Market Evolving Landscape
Aeroderivative turbine architectures and solid oxide fuel cell hybrids are compressing the efficiency frontier for distributed generation assets serving South Korea's industrial belt.
Small-scale proton exchange membrane fuel cell systems are expanding into commercial building microgrids, offering 40% electrical efficiency at sub-1MW scale. Department store operators in Seoul and Busan deploy these for basement-level generation avoiding rooftop turbine noise restrictions. The technology is expanding into district heating substations as buffer units smoothing thermal load profiles.
MOTIE's renewable portfolio standard enforcement tightens annually, requiring utilities to source specified percentages from certified clean generation. Industrial self-generators now stack REC values atop avoided grid purchase savings, improving project economics for gas-fired CHP with green hydrogen blending claims. Petrochemical majors in Yeosu respond by securing long-term biomethane supply contracts to preserve certificate eligibility.
Energy service company contracting models displace direct equipment ownership for mid-sized manufacturing facilities. GS E&R and regional utilities offer heat-and-power-as-a-service arrangements with guaranteed thermal output tariffs and fixed electricity rates. Automotive suppliers in Gwangju and Ulsan adopt these structures to transfer fuel price risk while preserving balance sheet capacity for core manufacturing investments.
South Korea Combined Heat and Power Market Segmentation
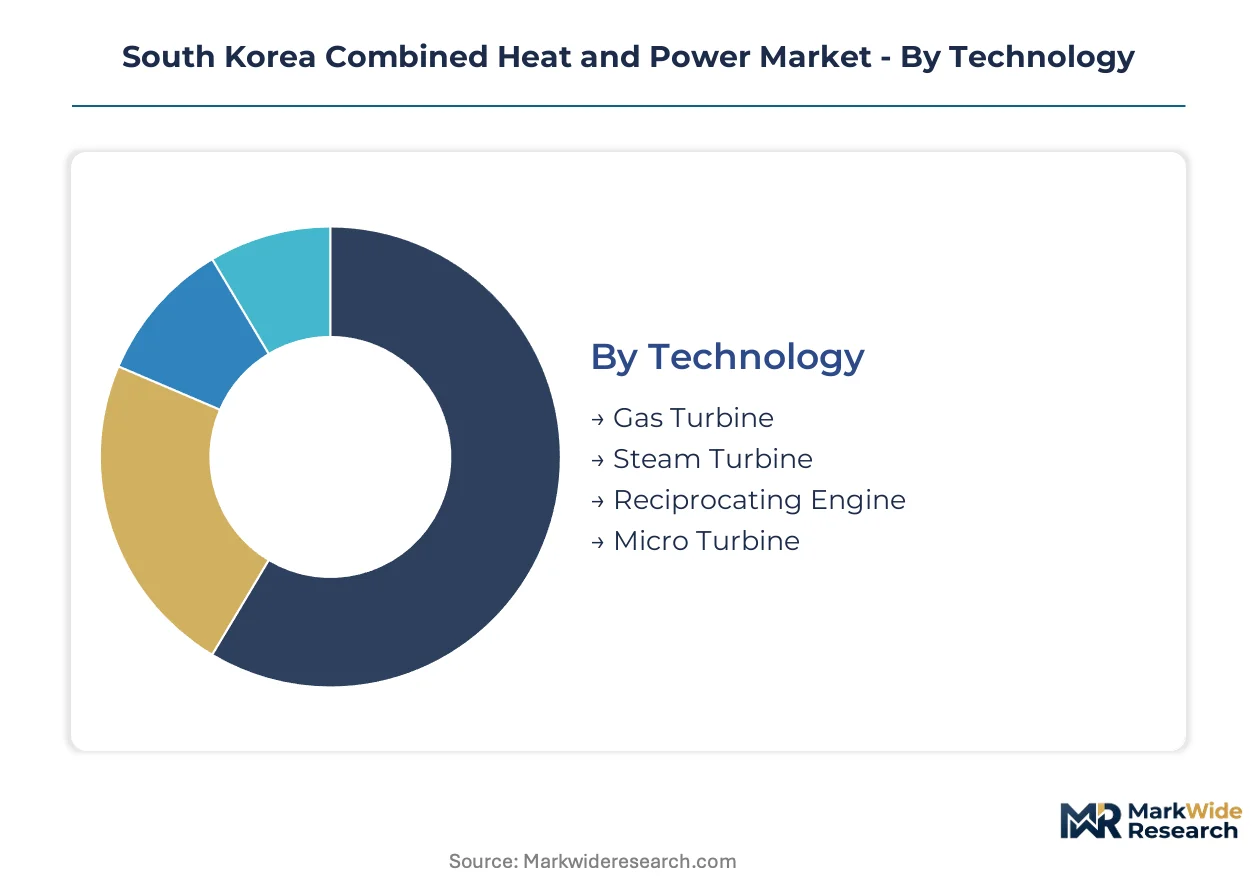
Technology selection in South Korean CHP deployments hinges on power-to-heat ratios, fuel flexibility for hydrogen blending, and grid interconnection scale. End-use thermal profiles and installation ownership structures further stratify equipment specifications across industrial clusters and municipal networks.
Technology:
Gas turbine architectures dominate large-scale baseload configurations through superior thermal efficiency and hydrogen cofiring readiness.
- Gas Turbine:Aeroderivative and heavy-duty frame designs achieve 60% electrical efficiency in combined cycle arrangements. Petrochemical complexes in Ulsan and Yeosu specify these for 50MW+ installations with guaranteed steam offtake contracts.
- Reciprocating Engine:Modular piston-engine packages offer sub-10MW scale with sub-5-minute ramp rates. Commercial microgrids in Pangyo and Busan data center corridors favor these for demand response participation.
- Steam Turbine:Back-pressure and extraction configurations serve process steam-intensive manufacturing with lower capital intensity than gas turbines.
- Micro Turbine:Capstone-style radial designs address sub-1MW building-scale generation with minimal maintenance intervals.
Mature deployment sits with Gas Turbine. Newer deployment is concentrated in Reciprocating Engine.
End User:
Customer scale determines thermal load profile predictability and fuel procurement sophistication.
- Industrial:Petrochemical, steel, and automotive manufacturers anchor baseload heat demand with 24/7 operations. Yeosu and Ulsan industrial parks specify 100MW-class installations with 20-year heat supply agreements.
- Commercial:Department stores, hospitals, and hotels in Seoul metropolitan area deploy mid-scale systems for electricity cost hedging and MFDS building code compliance.
- Residential:Apartment complex district heating substations aggregate thermal demand across multiple buildings.
- Institutional:University campuses and government facilities adopt CHP for energy independence targets.
Industrial captures the dominant revenue share. Commercial is expanding most quickly.
Installation Type:
Ownership and dispatch control arrangements segment project finance structures and regulatory pathways.
- District Heating:Municipal concessions in Seoul and Gyeonggi province guarantee 20-year thermal offtake with KEPCO grid backup. These projects secure lowest-cost project finance through public-private partnerships.
- On-site:Captive industrial generation transfers fuel price risk to operators but preserves thermal reliability for continuous process industries.
- Cogeneration Plant:Centralized multi-customer facilities serve industrial parks with shared infrastructure.
- Microgrid:Island-capable configurations with battery integration target resilience-critical facilities.
District Heating commands the deepest project finance pools. Microgrid is gaining share fastest.
Fuel Type:
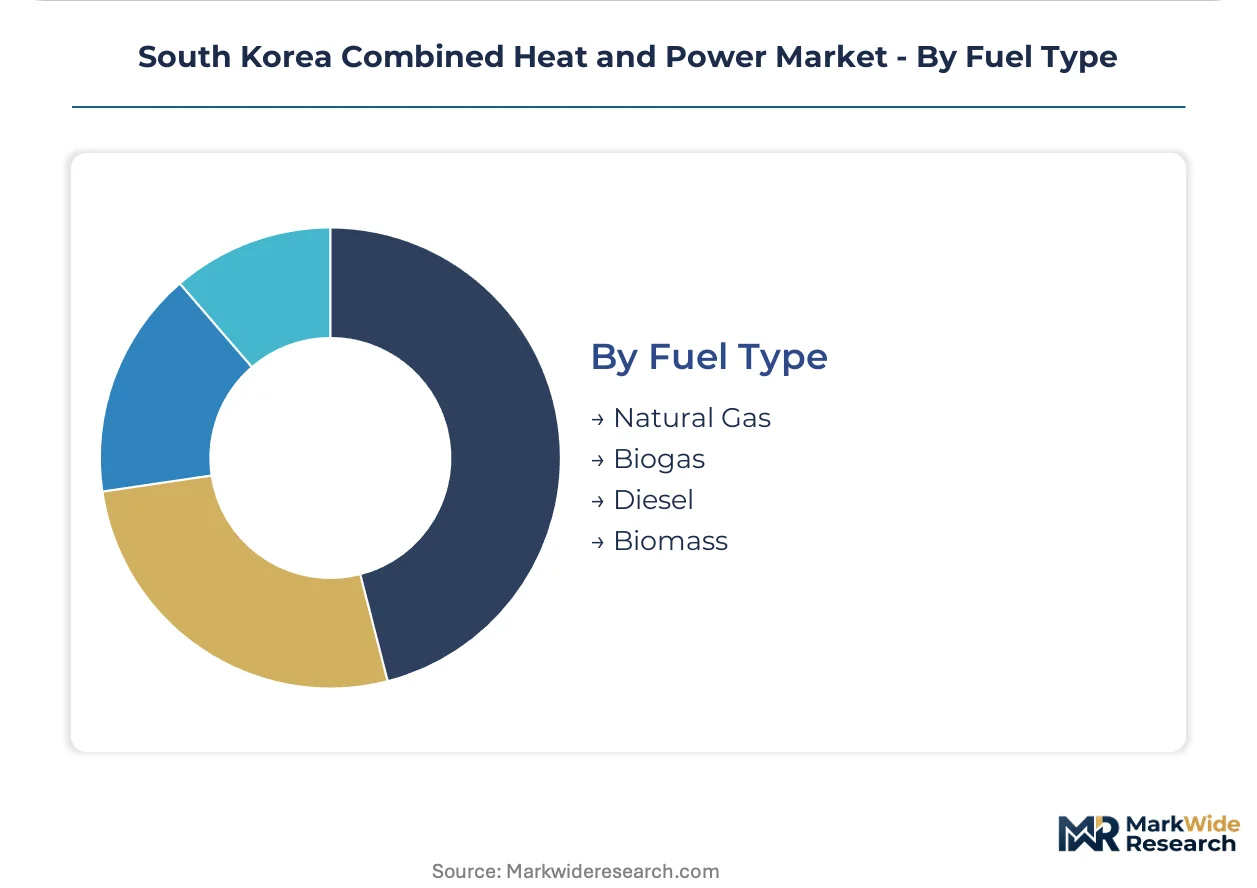
Hydrogen blending mandates and carbon accounting rules reshape fuel procurement strategies.
- Natural Gas:KOGAS pipeline supply and LNG terminal access anchor 90% of installed capacity. JKM-linked pricing exposes operators to import volatility through three primary receiving terminals.
- Biogas:Landfill and agricultural digester gas qualifies for MOTIE renewable energy certificates. Food waste processing facilities in metropolitan areas supply localized feedstock.
- Diesel:Emergency backup and remote installations retain niche demand where pipeline infrastructure is absent.
- Biomass:Wood pellet and agricultural residue combustion serves smaller-scale district heating with higher capital intensity than gas-fired alternatives.
Natural Gas dominates current capacity. Biogas shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates over half of national CHP thermal demand through dense district heating networks and commercial building stock. Industrial parks in Busan-Ulsan and Yeosu anchor large-scale gas turbine installations with guaranteed process heat offtake. Regional deployment patterns track manufacturing density, hydrogen infrastructure readiness, and municipal concession availability across five distinct economic zones.
Seoul Capital Area
Gyeonggi province municipal heating concessions and Seoul metropolitan commercial building codes drive mid-scale reciprocating engine deployments. MOTIE renewable portfolio standard enforcement tightens annually, requiring utilities to source specified clean generation percentages. Pangyo technology corridor data centers seek trigeneration partnerships with absorption chiller integration.
Busan-Ulsan
Petrochemical complexes in Ulsan industrial park anchor 100MW-class gas turbine baseload with 20-year steam supply guarantees. MFDS pressure equipment certification cycles impose planned outage windows that disrupt continuous process heat contracts. Hyundai Heavy Industries and adjacent shipyards maintain captive CHP for welding and surface treatment thermal loads.
Daegu-Gyeongbuk
Automotive component suppliers in Gwangju adopt energy service company contracting to transfer fuel price risk. KEEA grid interconnection queues create 18-24 month dispatch prioritization delays for non-utility generators. Textile and electronics manufacturing clusters specify modular reciprocating engines for demand response participation.
Daejeon-Sejong
Government complex energy independence targets and research institute thermal loads support institutional CHP adoption. National hydrogen roadmap pilot programs test electrolyzer-turbine integration for surplus renewable curtailment arbitrage. Sejong administrative city building efficiency mandates expand on-site generation compliance pathways above 10,000 square meters.
Gwangju-Honam
Agricultural processing and food waste biogas facilities supply localized feedstock for MOTIE renewable energy certificate eligibility. Smaller-scale biomass combustion serves district heating substations with higher capital intensity than gas-fired alternatives. Honam petrochemical belt operators secure long-term biomethane contracts to preserve certificate eligibility under tightening carbon accounting rules.
South Korea Combined Heat and Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and hydrogen cofiring readiness. The vendor base stratifies between utility-affiliated turnkey contractors, independent power producers with captive fuel supply, and foreign turbine technology licensors. Three archetypes dominate: state-linked engineering groups leveraging parent utility relationships, integrated energy merchants controlling downstream heat offtake, and equipment specialists licensing aeroderivative or heavy-frame turbine designs. Consolidation pressure favors M&A between fuel suppliers and project developers, while technology licensing agreements accelerate hydrogen-ready turbine deployment ahead of pipeline infrastructure maturity.
Within the utility-affiliated tier, KEPCO Engineering & Construction Co. Inc. and Korea District Heating Engineering Co. Ltd. exemplify state-linked engineering groups positioned for municipal concession capture. GS E&R Corp. anchors the integrated energy merchant archetype through natural gas supply chain control and long-term thermal tariff structures. Among foreign technology licensors, Siemens Energy AG occupies a position representing advanced aeroderivative configurations optimized for hydrogen cofiring ratios, while Mitsubishi Heavy Industries Ltd. and General Electric Company exemplify heavy-duty frame turbine specialists serving large industrial baseload requirements.
| Leading Market Players |
|---|
| KEPCO Engineering & Construction Co. Inc. |
| GS E&R Corp. |
| Korea District Heating Engineering Co. Ltd |
| Hanwha Engineering & Construction Corp. |
| Mitsubishi Heavy Industries Ltd |
| Siemens Energy AG |
| General Electric Company |
| Kawasaki Heavy Industries Ltd |
| Wärtsilä Oyj Abp |
| Others |
Value Network & Pricing Analysis
Dual-fuel turbine retrofits for hydrogen cofiring ratios are compressing capital expenditure timelines while concentrating procurement leverage among KEPCO-affiliated engineering groups with captive equipment sourcing agreements. This technology transition simultaneously elevates upfront project costs and narrows the vendor base capable of delivering certified hydrogen-ready configurations under MFDS pressure equipment standards.
Pricing Analysis
Guaranteed thermal output tariffs anchor value-based pricing for district heating concessions in Seoul and Gyeonggi province, with operators bidding on levelized cost of heat rather than equipment capital recovery. Price differentiation separates premium aeroderivative turbine packages with 50% hydrogen cofiring capability from standard heavy-frame configurations limited to 30% blending. Pricing pressure stems from JKM-linked LNG import volatility eroding project IRR calculations for independent power producers. Industrial self-generators in Ulsan and Yeosu exhibit lowest price sensitivity due to captive process heat demand, while commercial microgrid operators in Pangyo data center corridors prioritize fast-ramp reciprocating engines despite higher per-kW capital intensity.
Supply Chain Analysis
Specialized turbine blade casting and precision machining workforce availability concentrates in Germany, Japan, and the United States, creating bottlenecks for hydrogen-combustor retrofit programs. South Korean CHP supply chains draw from nickel-based superalloy forgings sourced from Japanese foundries, aeroderivative turbine packages licensed from Siemens Energy AG in Germany, and waste heat recovery boilers fabricated by domestic MFDS-certified pressure equipment manufacturers. Single-source vulnerability sits with heavy-frame gas turbine core engine imports from Mitsubishi Heavy Industries and General Electric. Distribution runs through KEPCO Engineering & Construction Co. Inc. turnkey contracting for utility-scale projects and GS E&R Corp. integrated fuel-and-power service arrangements for industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea CHP market is becoming a vertical-integration race as operators secure captive hydrogen supply through electrolyzer partnerships and long-term biomethane offtake contracts to preserve MOTIE renewable energy certificate eligibility.
For Market Incumbents: Acquire electrolyzer manufacturing capability or green hydrogen production assets to lock in fuel supply for dual-fuel turbine deployments ahead of pipeline infrastructure maturity. KEPCO-affiliated engineering groups should consolidate district heating concession portfolios in Seoul Capital Area to defend against energy service company contracting models displacing direct equipment ownership. Battery energy storage substitution for peak shaving revenue streams represents the priority threat requiring fast-ramp reciprocating engine capability integration. For New Entrants and Emerging Players: Capture data center trigeneration partnerships in Pangyo and Busan where hyperscale cloud facilities seek reliable thermal sinks for absorption chiller integration. The commercial building microgrid segment offers lowest entry barriers through sub-10MW modular reciprocating engine deployments with sub-5-minute ramp rates. Position through energy-as-a-service arrangements transferring fuel price risk while preserving balance sheet capacity for tenant core operations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated energy merchants seeking captive natural gas supply and downstream heat offtake control. Long-term viability favors operators with secured hydrogen infrastructure access and MFDS certification maintenance capabilities across the analysis window. Watch MOTIE renewable portfolio standard enforcement tightening as the inflection signal for certificate-eligible asset valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Deployment | Dual-fuel configurations secure MOTIE compliance ahead of cofiring mandate deadlines in Seoul metropolitan concessions. |
| District Heating Concession Consolidation | Municipal 20-year thermal offtake agreements in Gyeonggi province anchor lowest-cost project finance structures. |
| Data Center Trigeneration Partnership | Absorption chiller integration with Pangyo hyperscale facilities captures premium cooling-load revenue streams. |
| Biomethane Supply Contracting | Long-term offtake agreements preserve MOTIE renewable energy certificate eligibility under tightening carbon accounting. |
| Energy-as-a-Service Model Expansion | GS E&R and regional utilities transfer fuel price risk for automotive suppliers in Gwangju and Ulsan. |
Research Methodology
Multi-period observation of MOTIE renewable portfolio standard enforcement trajectories, hydrogen blending mandate implementation schedules, and KEEA grid interconnection queue durations anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Secondary validation drew from MOTIE policy bulletins, KEEA certification databases, KOGAS infrastructure development disclosures, and MFDS pressure equipment safety filings. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic demand modeling for industrial thermal load growth.
Segment-weighting across technology, end user, installation type, and fuel type dimensions informed the analytical framework, with gas turbine and reciprocating engine capacity additions modeled separately for hydrogen cofiring readiness tiers. CAGRs were derived from unit economics projections incorporating JKM-linked LNG price scenarios and renewable energy certificate value stacking. Industry-specific forecast inputs included district heating network expansion timelines in Seoul Capital Area and petrochemical complex thermal demand baselines in Ulsan and Yeosu.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen pipeline infrastructure buildout delays and MOTIE renewable energy certificate pricing volatility. Forecasts reflect documented assumptions regarding KEEA grid interconnection prioritization rules and MFDS equipment certification cycle durations. Material deviation in JKM spot pricing or hydrogen blending mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Microturbine Market
Power Generation
Europe Thermal Power Market
Power Generation
Global Gensets Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
South East Asia Power Market
Power Generation
Marine Power Plant Market
Power Generation
Gas Gensets Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Peaking Power Plant Market
Power Generation
Global Power Grid System Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Algeria Power Market
Power Generation
Global Black Start Generator Market