
 Captive Power Plant Market | 2026-2036
Captive Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Captive Power Plant Market Analysis
Natural gas is broadening its role as the preferred fuel input across new captive installations, displacing heavier residual oils in baseload configurations. General Electric Company leverages its aeroderivative turbine portfolio to anchor utility-scale efficiency benchmarks within industrial parks. Siemens AG sustains technology leadership through integrated digital controls that optimize fuel flexibility across varying load profiles. Reliance Industries dominates India's captive landscape with refineries and petrochemical complexes that operate among the largest private generation assets in the country.
A captive power plant denotes an electricity generation facility owned and operated by an industrial or commercial entity primarily to serve its own energy requirements, typically employing gas turbines, reciprocating engines, or steam cycles with outputs ranging from single-digit megawatts to several hundred megawatts. These installations serve the core purpose of insulating energy-intensive operations from grid instability, tariff volatility, and supply interruptions that disrupt continuous process industries. Natural gas-based generation leads among power source categories due to cleaner combustion profiles and faster ramp rates suited to fluctuating factory demand, while renewable energy hybridization represents the fastest-expanding segment as solar-wind-battery configurations reduce diesel dependence in remote mining and telecommunications applications. Fuel cell technology occupies an emerging niche where hydrogen feedstock availability aligns with decarbonization mandates in European manufacturing clusters.
The EPA enforces emissions thresholds under the Clean Air Act that constrain diesel generator deployments across US industrial facilities, while India's CEA mandates technical standards for grid interconnection that shape captive plant design and operational protocols. The EU Green Deal's carbon border adjustment mechanism forces energy-intensive exporters to document embedded emissions, directly incentivizing lower-carbon captive configurations in steel and cement operations. Stakeholders must monitor evolving hydrogen blending regulations and carbon accounting rules that will determine which technology investments retain competitive validity across jurisdictions.
Market Dynamics
Natural gas supply concentration and hydrogen blending mandates are restructuring investment priorities across industrial self-generation, forcing asset owners to weigh fuel flexibility against stranded asset risk in multi-decade plant lifecycles.
Growth Catalysts
- India's PLI scheme:Manufacturing incentives accelerate capital deployment into captive gas turbine capacity among chemical and textile clusters seeking tariff insulation.
- Steel sector electrification:Arc furnace expansion in energy-intensive metals processing drives baseload power demand that grid reliability cannot satisfy.
- Aeroderivative turbine efficiency:Advanced thermodynamic cycles cut heat rates below 9,500 Btu/kWh, shrinking fuel cost exposure for continuous process industries.
Market Restraints
- LNG price volatility:Asian spot market swings above $15/MMBtu erode operating margins for gas-dependent installations lacking long-term offtake contracts.
- Steam turbine supply concentration:Heavy industrial equipment fabrication clusters in Northeast Asia create 18-24 month delivery bottlenecks for large-scale units.
- EPA Clean Air Act constraints:Stationary source emissions thresholds block diesel generator expansion across US process manufacturing facilities.
Strategic Opportunities
- EU Green Deal carbon border adjustments:Embedded emissions documentation requirements create competitive advantage for low-carbon captive configurations in cement and steel exports.
- Solar-wind-battery hybridization:Renewable-plus-storage architectures displace diesel dependence in remote mining and telecommunications tower applications.
- Fuel cell hydrogen integration:European industrial clusters with pipeline hydrogen access pilot solid oxide systems for combined heat and power baseload.
Industry Challenges
- Grid synchronization protocols:India's CEA interconnection standards demand specialized protection systems that extend commissioning timelines and inflate engineering costs.
- Carbon accounting complexity:Divergent Scope 1-3 measurement methodologies across jurisdictions complicate asset valuation and financing for cross-border industrial operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Captive Power Plant Market |
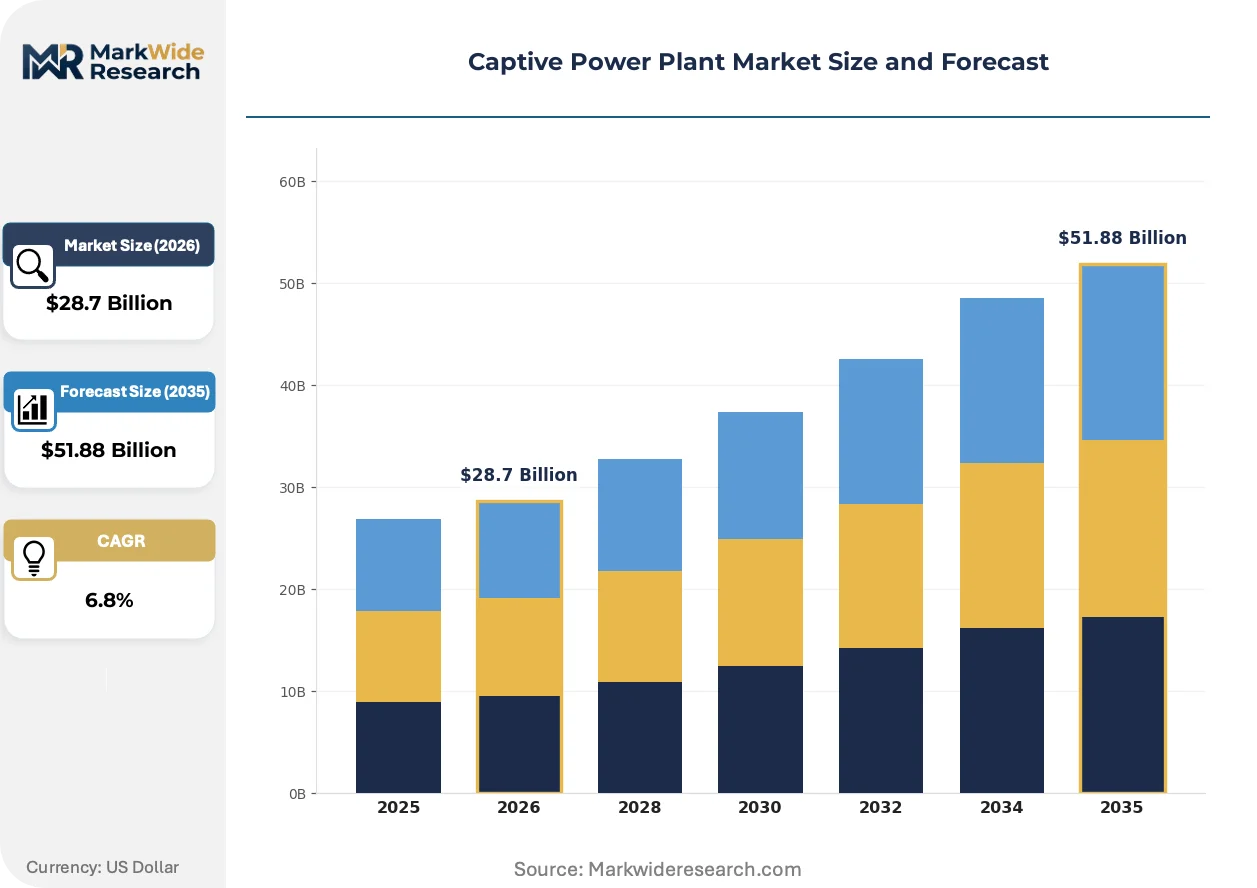
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Diesel, Natural Gas, Renewable Energy, Biomass Application: Industrial Facilities, Commercial Buildings, Manufacturing Plants, Remote Areas Technology: Gas Turbines, Steam Turbines, Diesel Generators, Fuel Cells End User: Manufacturing, Mining, Telecommunications, Hospitality |
| Companies Covered | Thermax, Mitsubishi Heavy Industries Ltd., General Electric Company, Reliance Industries, Clarke Energy, Wärtsilä Oyj Abp, Caterpillar Inc., Jindal Steel & Power Ltd., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Captive Power Plant Market Emerging Trajectories
Digital control architectures and fuel-flexible combustion systems are compressing the economic viability window for single-fuel legacy installations while opening new operational regimes for hybrid power trains.
Aeroderivative gas turbines with dry low-NOx combustors are unifying baseload efficiency and peaking responsiveness in a single asset class. Chemical complexes in Gujarat's industrial corridor deploy these units for combined-cycle operation that ramps 50 MW per minute. The technology is unifying what previously required separate baseload steam turbines and emergency diesel sets, collapsing capital intensity for mid-scale industrial parks.
The EU F-Gas Regulation mandates phasedown of fluorinated greenhouse gases used in turbine inlet cooling and fire suppression systems. Industrial operators must retrofit existing installations with alternative chemistries or absorb escalating carbon-equivalent penalties. Steel and cement exporters to European markets face the steepest compliance timelines as the carbon border adjustment mechanism tightens documentation requirements.
Power purchase agreements for surplus captive generation are displacing traditional utility offtake structures in deregulated industrial zones. Third-party aggregators in India's open access states now contract directly with cement and aluminum producers for scheduling flexibility services. This contractual innovation concentrates most visibly in Maharashtra and Tamil Nadu, where state regulatory frameworks permit bilateral trading outside distribution utility monopolies.
Captive Power Plant Market Segmentation
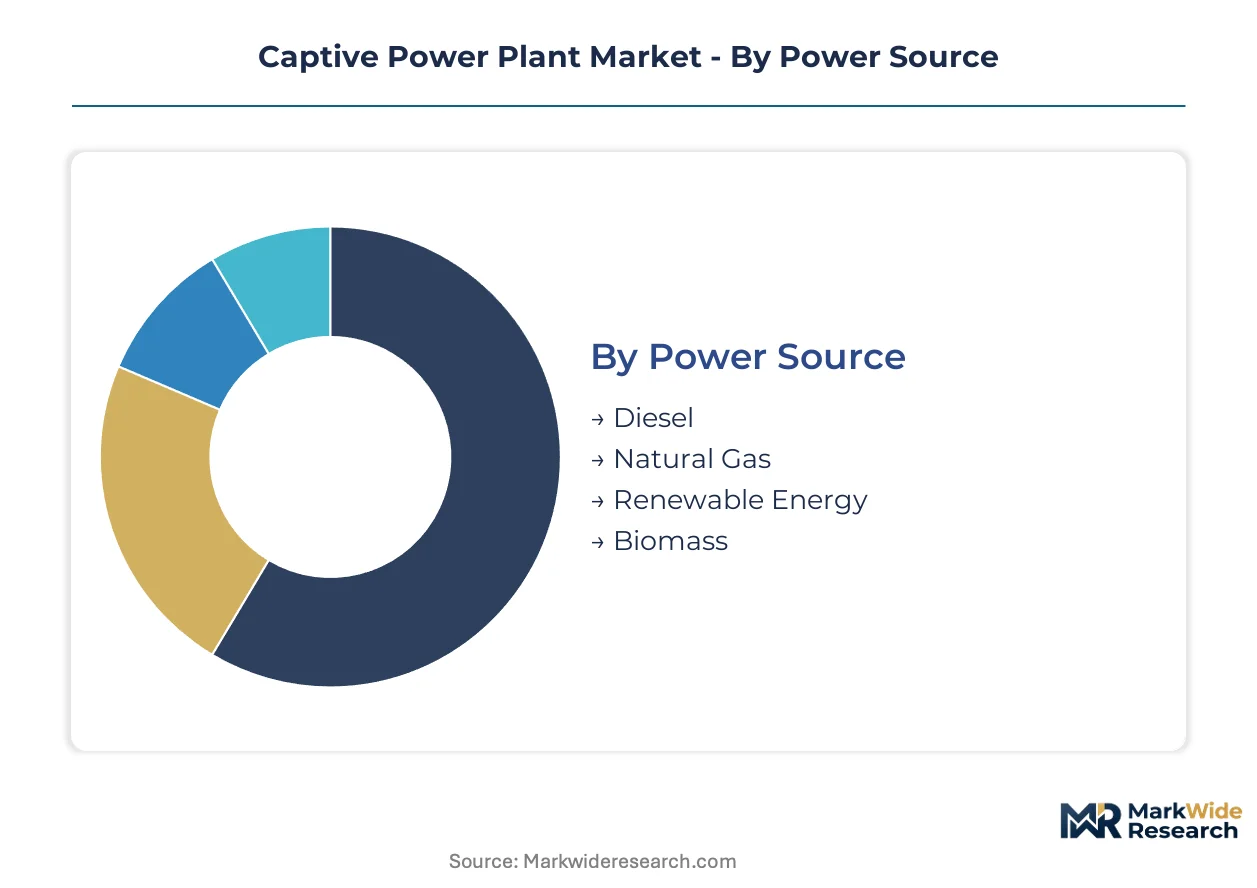
Segmentation in captive power plants reveals how capital allocation, fuel access, and process continuity requirements shape technology choices across industrial verticals. Understanding these divisions exposes where infrastructure investments concentrate and which configurations face obsolescence pressure.
Power Source:
Capital intensity varies sharply across fuel inputs, with natural gas requiring pipeline interconnection investments that dwarf diesel generator deployments while offering superior thermodynamic efficiency.
- Natural Gas:Combined-cycle configurations achieve heat rates below 9,500 Btu/kWh through aeroderivative turbines with dry low-NOx combustors. Chemical complexes in Gujarat's industrial corridor favor these installations for baseload operation with 50 MW-per-minute ramp capability.
- Renewable Energy:Solar-wind-battery hybrid architectures displace diesel dependence in remote mining and telecommunications applications where grid extension proves economically unviable.
- Diesel:Reciprocating engine sets dominate emergency backup roles despite EPA Clean Air Act constraints on stationary source emissions thresholds.
- Biomass:Agricultural residue combustion serves sugar mills and paper manufacturers with captive feedstock access.
Natural gas absorbs the bulk of installed capacity; renewable energy is expanding most quickly.
Application:
Process continuity requirements determine backup redundancy levels, with continuous manufacturing demanding triple-redundant configurations that intermittent commercial loads cannot justify.
- Industrial Facilities:Steel arc furnaces and cement kilns require baseload power exceeding 100 MW that grid reliability cannot guarantee, driving investment in dedicated generation assets with islanding capability.
- Manufacturing Plants:Textile and chemical clusters in India's PLI scheme zones deploy captive gas turbines to insulate operations from tariff volatility and supply interruptions.
- Remote Areas:Mining concessions and telecommunications tower networks rely on hybrid renewable-diesel configurations where transmission infrastructure remains absent.
- Commercial Buildings:Data centers and hospitals prioritize uninterrupted power supply through smaller-scale natural gas or diesel installations with automatic transfer switching.
Industrial facilities command the largest share of megawatt deployment; remote area applications are climbing the fastest.
Technology:
Thermodynamic cycle selection hinges on load profile predictability, with baseload operations favoring steam turbine efficiency and variable demand requiring gas turbine responsiveness.
- Gas Turbines:Aeroderivative units unify baseload efficiency and peaking responsiveness, collapsing capital intensity for mid-scale industrial parks that previously required separate steam and emergency diesel assets.
- Steam Turbines:Heavy industrial equipment fabrication concentration in Northeast Asia creates 18-24 month delivery bottlenecks for large-scale units exceeding 200 MW output.
- Diesel Generators:Reciprocating engines face regulatory pressure under EPA emissions thresholds while retaining niche roles in emergency backup and remote deployment.
- Fuel Cells:Solid oxide systems pilot in European industrial clusters with pipeline hydrogen access, offering combined heat and power baseload for decarbonization-aligned manufacturing.
Gas turbines dominate current installed base; fuel cells are gaining share fastest.
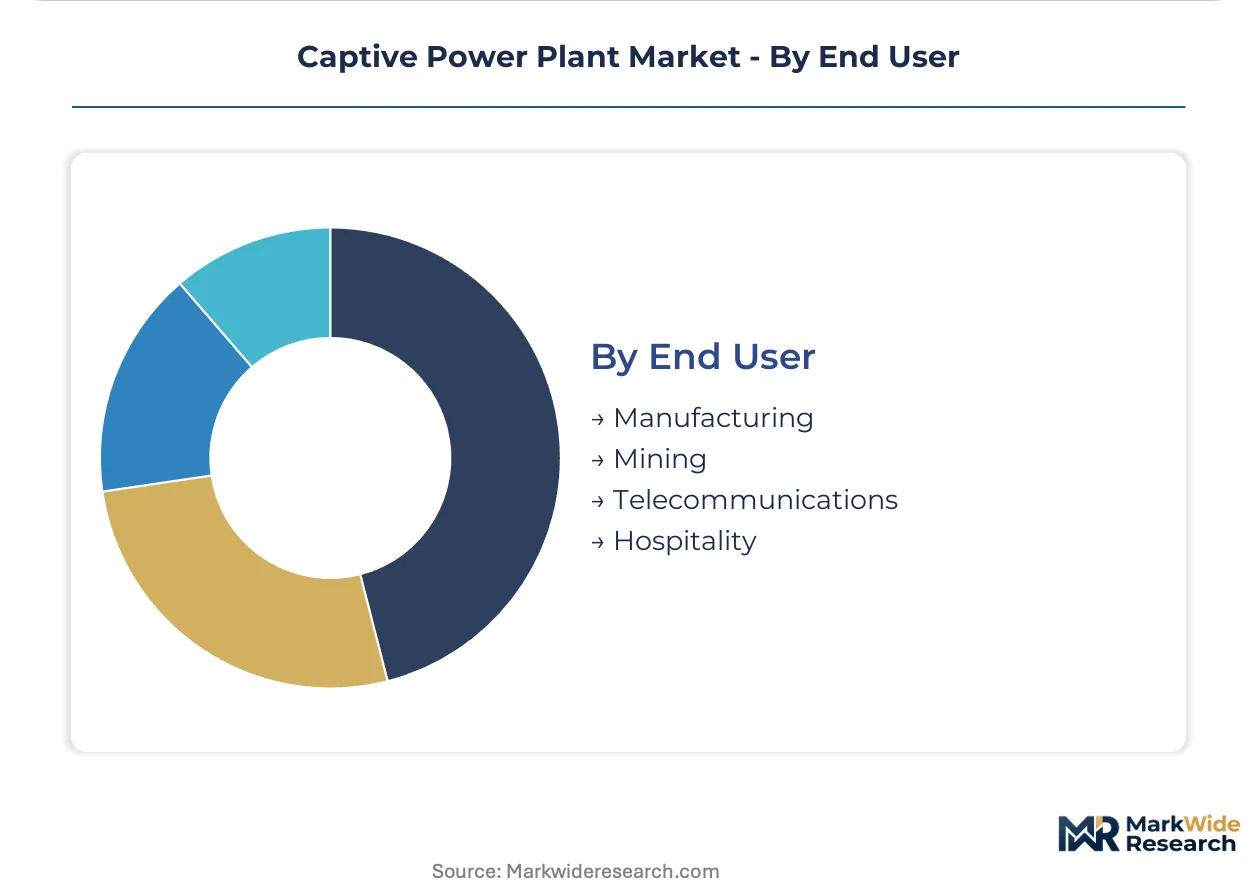
End User:
Energy intensity and outage cost exposure stratify end-user investment capacity, with metals processing accepting decade-long payback periods that hospitality operators reject.
- Manufacturing:Steel, cement, and aluminum producers face EU Green Deal carbon border adjustment documentation requirements that incentivize lower-carbon captive configurations for export competitiveness.
- Mining:Extractive operations in geographically isolated concessions deploy renewable-plus-storage architectures to reduce diesel logistics burden and fuel price volatility exposure.
- Telecommunications:Tower operators aggregate distributed generation assets through third-party power purchase agreements for scheduling flexibility services in deregulated Indian states.
- Hospitality:Hotels and resorts prioritize guest experience continuity through smaller-scale natural gas or diesel installations with sub-10 MW output.
Manufacturing anchors the majority of capacity additions; mining is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme concentrates captive power investment in designated manufacturing zones, where tariff volatility and grid reliability concerns override pure economic calculus for energy-intensive operators.
India
Steel arc furnaces and cement kilns in Gujarat's industrial corridor anchor the largest captive gas turbine deployments, as chemical and textile clusters seek insulation from distribution utility tariffs. The CEA mandates technical standards for grid interconnection that shape plant design and protection system specifications. Dahej and Hazira petrochemical complexes operate combined-cycle installations exceeding 500 MW output.
United States
Data centers in Northern Virginia and Texas deploy natural gas reciprocating engines for baseload reliability that grid operators cannot guarantee during extreme weather events. The EPA enforces Clean Air Act emissions thresholds that constrain diesel generator expansion across process manufacturing facilities. Gulf Coast petrochemical complexes leverage pipeline gas access for combined heat and power configurations.
Germany
Steel and cement exporters face EU Green Deal carbon border adjustment documentation requirements that incentivize lower-carbon captive configurations for export competitiveness. The F-Gas Regulation mandates phasedown of fluorinated greenhouse gases in turbine inlet cooling systems. Ruhr industrial clusters pilot solid oxide fuel cells with pipeline hydrogen access for combined heat and power baseload.
China
Dual carbon goals and provincial emissions intensity targets accelerate renewable-plus-storage hybridization in remote mining concessions where grid extension proves economically unviable. The MIIT sets equipment efficiency standards that shape gas turbine procurement decisions. Inner Mongolia and Xinjiang coal-chemical complexes integrate captive wind and solar to meet decarbonization mandates.
Saudi Arabia
Desalination and petrochemical complexes in the Eastern Province anchor heavy industrial power demand that favors combined-cycle gas turbine baseload configurations. The national regulator enforces grid code compliance for captive plant synchronization and islanding capability. Jubail Industrial City hosts among the largest concentrations of private generation assets in the Middle East.
Captive Power Plant Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy conglomerates controlling the largest installed capacity while equipment fabricators compete on thermodynamic efficiency and fuel flexibility. The vendor base concentrates around three strategic archetypes: diversified industrial groups with captive assets, pure-play turbine OEMs, and EPC contractors with regional installation expertise. Competitive positioning hinges on M&A activity consolidating service capabilities and strategic partnerships securing long-term fuel supply contracts.
Within the diversified industrial group tier, Reliance Industries and Jindal Steel & Power Ltd. exemplify asset-heavy operators that anchor captive capacity within their core manufacturing footprints. Among turbine OEMs, General Electric Company and Siemens AG occupy positions defined by aeroderivative portfolios and integrated digital control architectures. Mitsubishi Heavy Industries Ltd. represents the heavy industrial equipment fabricator archetype with concentrated fabrication capacity in Northeast Asia.
| Leading Market Players |
|---|
| Thermax |
| Mitsubishi Heavy Industries Ltd. |
| General Electric Company |
| Reliance Industries |
| Clarke Energy |
| Wärtsilä Oyj Abp |
| Caterpillar Inc. |
| Jindal Steel & Power Ltd. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap EPC contractors anchor procurement discipline across India's captive power sector, translating fabrication bottlenecks into extended payment terms and selective order acceptance that insulates margins from raw material volatility.
Pricing Analysis
Premium pricing for sub-12-month delivery slots distinguishes urgent project schedules from standard 18-24 month lead time quotations. Three-tier pricing structure across aeroderivative turbine packages, standard industrial gas turbine configurations, and economy-class reciprocating engine sets stratifies by efficiency certification and fuel flexibility rating. Cost compression in the standard tier is intensifying because Northeast Asian fabricators are absorbing steel alloy price swings to maintain backlog fill. Mining operators in remote concessions exhibit highest price sensitivity, while Gulf Coast petrochemical complexes demonstrate lowest elasticity due to integrated fuel cost pass-through mechanisms.
Supply Chain Analysis
Dual-sourcing mandates from Indian CEA interconnection standards force project developers to qualify both Japanese and European protection system suppliers, fragmenting procurement leverage. Heavy industrial equipment fabrication concentrates in Japan, South Korea, and Germany, drawing from specialty steel forgings, precision turbine blades, and advanced control system electronics. Single-source vulnerability runs through aeroderivative turbine hot section component supply. Distribution runs through EPC contractors with regional installation expertise who bundle long-term service agreements with initial equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam turbine supply concentration in Northeast Asia props pricing discipline, as 18-24 month delivery backlogs prevent competitive discounting even during demand softening.
For Market Incumbents: Anticipate hydrogen blending mandate acceleration by securing fuel-flexible combustion system certifications ahead of regulatory deadlines. Siemens AG and General Electric Company should anchor service contract renewals through predictive maintenance digital platforms that lock in aftermarket revenue streams. Reliance Industries and Jindal Steel & Power Ltd. must defend captive asset valuations by documenting carbon intensity metrics for EU Green Deal export compliance. For New Entrants and Emerging Players: Begin with fuel cell system integration for European steel and cement clusters where pipeline hydrogen access creates first-mover positioning. Solar-wind-battery hybrid configurations for remote Indian mining concessions offer the most penetrable white-space, given grid extension economics and diesel logistics burdens. Target third-party power purchase agreement aggregation in Maharashtra and Tamil Nadu open access states as the primary go-to-market channel. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale gas turbine EPC specialists with Indian regulatory relationships and stranded fabrication capacity in Northeast Asia. Long-term viability across the next decade hinges on fuel flexibility retrofit capabilities and hydrogen-ready technology positioning. Watch F-Gas Regulation compliance cost escalation as the inflection signal for stranded asset risk in European-installed turbine cooling systems.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Flexibility Retrofit Program | Extends asset life across India's PLI scheme manufacturing zones facing hydrogen blending mandates. |
| Long-term Service Agreement Expansion | Locks recurring revenue from Gujarat chemical complexes operating combined-cycle baseload installations. |
| Carbon Border Adjustment Documentation System | Preserves EU export eligibility for steel producers under Green Deal embedded emissions tracking. |
| Renewable-Plus-Storage Hybrid Deployment | Displaces diesel dependence in Inner Mongolia mining concessions under China's dual carbon goals. |
| Pipeline Hydrogen Integration Partnership | Positions solid oxide fuel cell pilots in Ruhr industrial clusters for combined heat and power baseload. |
Methodological Framework
Regulatory filings from the EPA, India's CEA, and the EU F-Gas Regulation database formed the secondary backbone, supplemented by EIA generation statistics, IEA industrial energy reports, and FERC interconnection dockets. Primary interviews with IPP project developers, EPC contractors, utility planning officers, and fuel supply specialists grounded demand assumptions. Plant engineers at steel and cement facilities, alongside grid operators in Maharashtra and Tamil Nadu, validated operational constraints. Bottom-up project pipeline aggregation and top-down industrial energy consumption triangulation reconciled capacity deployment estimates.
Historical trendline analysis of installed captive capacity, fuel source migration patterns, and technology substitution rates informed the projection framework across the analysis window. Segmentation modeling incorporated power source categories, generation capacity tiers, application types, and regional regulatory frameworks. CAGRs derived from capacity addition trajectories, equipment replacement cycles, and manufacturing incentive program uptake curves. Forecast inputs included India's PLI scheme disbursement schedules, LNG contract renewal patterns, and EU carbon border adjustment implementation phases.
LNG price volatility, hydrogen infrastructure deployment delays, and carbon accounting methodology divergence are the dominant revision risks to capacity deployment timelines. Deviation in India's CEA interconnection standard enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Iraq Power EPC Market
Power Generation
Indonesia Power Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Australia Thermal Power Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Residential Solar Generator Market
Power Generation
Global Gensets Market
Power Generation
Power Plant EPC Market
Power Generation
Europe Thermal Power Market
Power Generation
Global Power to Gas Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
North America Distributed Power Generation Market
Power Generation
India Gas Generator Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Coal Fired Power Generation Market