
 Oilfield Rotary Table Market | 2026-2036
Oilfield Rotary Table Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Rotary Table Market Analysis
Drilling contractors are rotating away from speculative fleet builds toward precision replacement cycles for high-duty rotary tables. National Oilwell Varco Inc. leverages its integrated manufacturing footprint across Houston and Norway to control lead times for API-certified tables. Schlumberger Ltd. competes through its digital drilling portfolio that embeds rotary table telemetry within broader rig automation architectures. RM Holding BV anchors European aftermarket demand with specialized refurbishment capabilities for aging North Sea infrastructure.
An oilfield rotary table is a mechanical device mounted on the rig floor that transmits rotational power from the drive system to the drill string, typically rated between 1,000 and 3,000 horsepower with table openings ranging from 17.5 to 49.5 inches to accommodate various casing programs. Its primary function is to rotate the drill bit during drilling operations and to suspend the casing during completion phases. Hydraulic rotary tables dominate deepwater and extended-reach applications where precise torque modulation reduces fatigue on drill pipe connections. Conventional technology still occupies the majority of onshore rental fleets, though automated rotary tables with integrated top-drive interfaces represent the fastest-expanding margin pool as operators push for reduced crew exposure on rig floors.
API 7K standards govern load ratings and material traceability for rotary tables in the United States, while the EU Machinery Directive and ATEX certification constrain market access for equipment deployed on European offshore platforms. China's GB/T 23505 national standard and NMPA-equivalent pressure equipment regulations create parallel compliance pathways for suppliers targeting domestic shale development in Sichuan and Xinjiang. Stakeholders must monitor how divergent regional certification timelines affect inventory pooling strategies and whether modular rotary table architectures can compress recertification costs across multiple regulatory jurisdictions.
Market Dynamics
API 7K certification timelines and ISO 14691 material traceability mandates are compressing supplier qualification windows, forcing drilling contractors to consolidate procurement relationships around vertically integrated manufacturers with captive metallurgical testing capabilities.
Growth Catalysts
- Shale basin deepening:Permian Basin operators are demanding higher-load rotary tables rated above 2,000 horsepower to accommodate extended-reach laterals exceeding 15,000 feet measured depth.
- API 7K enforcement:United States federal regulators are disqualifying non-certified equipment from federally leased acreage, redirecting rental fleet investment toward compliant suppliers.
- Hydraulic torque modulation:Deepwater contractors are specifying closed-loop hydraulic tables for fatigue-sensitive drill pipe connections in high-pressure, high-temperature formations.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input costs swing 15-40 percent quarterly, eroding fixed-price contract margins for forged table manufacturers.
- Supplier concentration:Houston-Galveston corridor dominates large-diameter casting capacity, creating hurricane exposure and single-point failure risk for North American delivery schedules.
- Top-drive substitution:Integrated top-drive systems eliminate rotary table dependency on newbuild offshore rigs, capping replacement demand in floating production segments.
Strategic Opportunities
- Sichuan shale development:China's domestic operators are localizing rotary table supply chains under GB/T 23505 standards, creating captive demand for certified joint-venture manufacturers.
- Refurbishment specialization:North Sea infrastructure aging is generating aftermarket demand for remanufactured tables with updated API certification packages.
- Telemetry integration:Rotary tables with embedded torque and vibration sensors are converging with rig automation architectures, opening premium pricing tiers.
Industry Challenges
- Metallurgical engineering talent:Forged alloy expertise is concentrating among retiring specialists, constraining quality assurance throughput at certification laboratories.
- Multi-jurisdiction recertification:Modular table designs face divergent API 7K, EU Machinery Directive, and GB/T 23505 testing timelines, complicating inventory pooling strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Rotary Table Market |
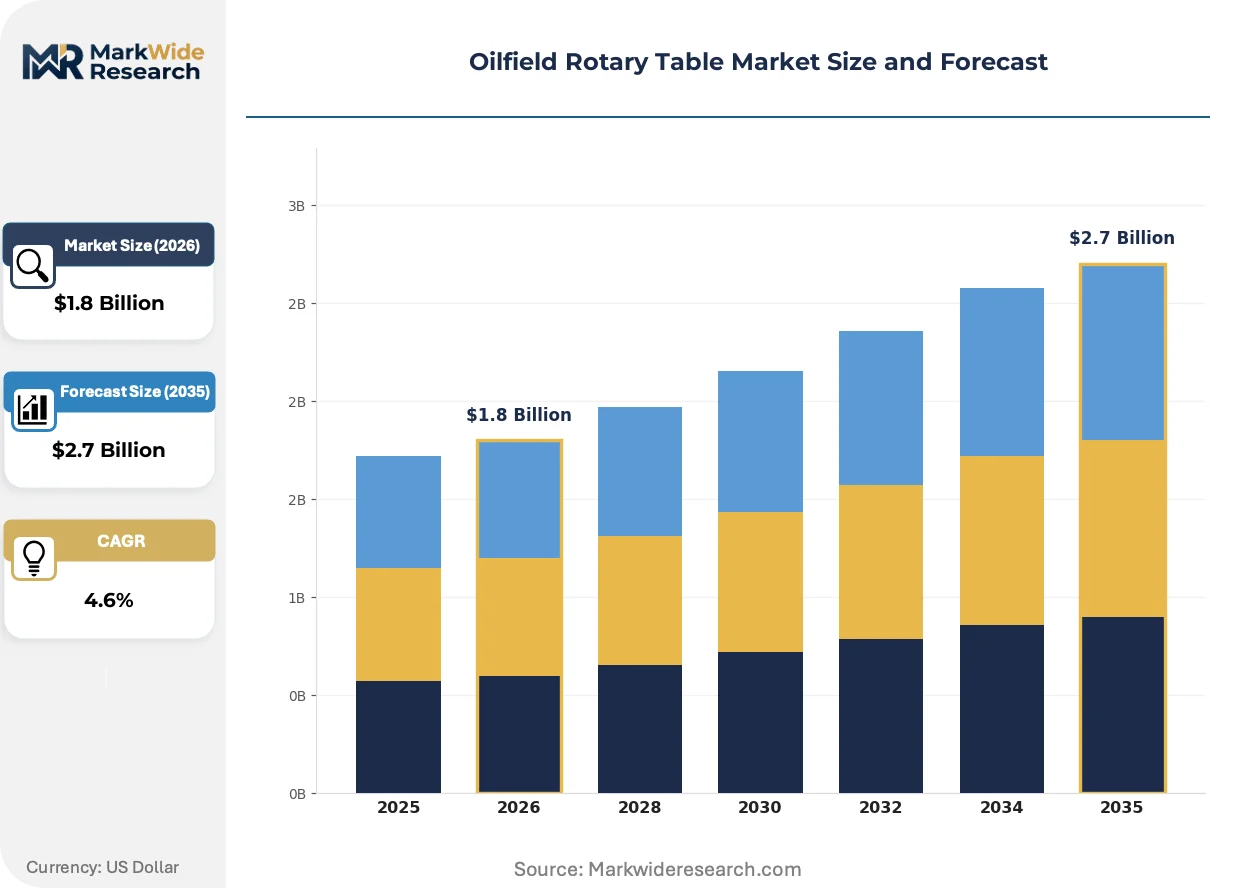
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rotary Tables, Table Assemblies, Hydraulic Rotary Tables, Electric Rotary Tables Service Type: Rental Services, Maintenance Services, Installation Services, Repair Services End User: Oil & Gas Operators, Drilling Contractors, Service Companies, Independent Producers Technology: Conventional, Computerized, Modular, Automated |
| Companies Covered | National Oilwell Varco Inc., Schlumberger Ltd., RM Holding BV, CMIC Ocean En-Tech Holding Co. Ltd., MHWirth AS, Pickett Oilfield, Chengdu Zhonghang Machinery Co. Ltd., Shaanxi FYPE Rigid Machinery Co., Ltd., YZS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Rotary Table Market Emerging Trajectories
Digital instrumentation and predictive maintenance architectures are embedding themselves into mechanical power transmission equipment, transforming rotary tables from passive hardware into data-generating nodes within integrated drilling systems.
Automated rotary tables with integrated top-drive interfaces are displacing conventional mechanically-driven units in onshore contractor fleets. Precision drilling contractors in the Permian Basin are specifying these systems to reduce crew exposure on rig floors during connection-making operations. This displacement is compressing rental rates for legacy equipment while expanding margin pools for suppliers with software-integrated product lines.
EU Machinery Directive compliance deadlines are forcing European offshore operators to retire pre-certified equipment ahead of mechanical end-of-life. North Sea drilling contractors are accelerating replacement cycles to meet ATEX certification requirements for explosive atmosphere operations. Suppliers with established EU notified body relationships are capturing this regulatory-driven replacement volume.
Drilling contractors are unbundling after-sales service contracts from equipment procurement, creating standalone refurbishment and certification revenue streams. Independent service providers in the US Gulf Coast are building dedicated facilities for API 7K recertification, challenging OEM service monopolies. This unbundling is most visible among mid-size onshore contractors seeking to extend asset life without full replacement capital expenditure.
Oilfield Rotary Table Market Segmentation
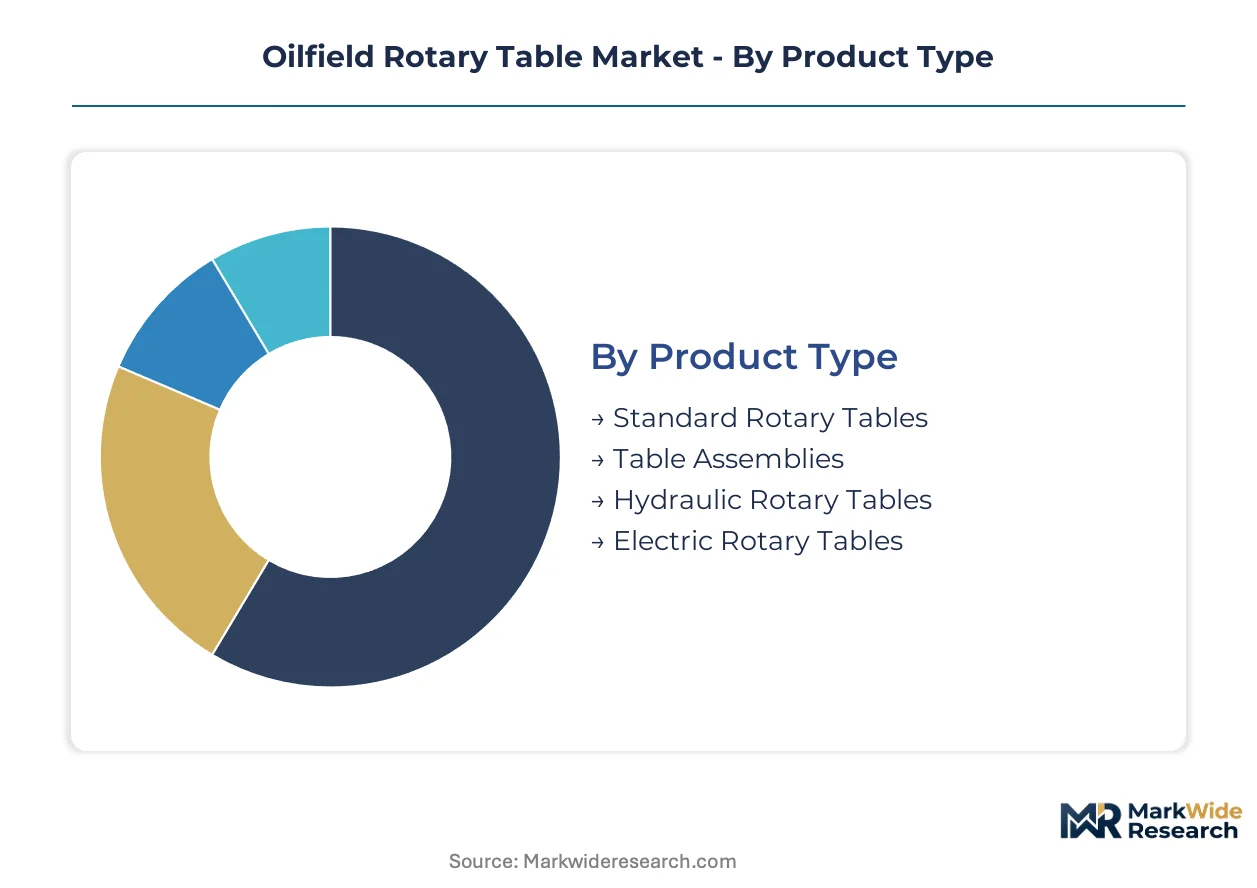
Rotary table procurement patterns diverge sharply between domestic shale basins and export-oriented manufacturing hubs. Understanding these segment boundaries clarifies where certification requirements, rental fleet strategies, and technology refresh cycles concentrate investment.
Product Type:
Hydraulic and electric rotary tables flow predominantly toward deepwater export markets, while standard mechanical units serve captive onshore demand in Texas and New Mexico.
- Standard Rotary Tables:Conventional gear-driven designs rated 1,000–2,000 horsepower dominate Permian Basin rental fleets. Drilling contractors in West Texas favor these units for their field-proven durability and rapid parts availability from Houston-Galveston distribution corridors.
- Hydraulic Rotary Tables:Closed-loop hydraulic systems enable precise torque modulation critical for extended-reach laterals exceeding 15,000 feet. Gulf of Mexico deepwater contractors specify these for high-pressure formations where drill pipe fatigue management determines operational economics.
- Table Assemblies:Integrated master bushing and kelly drive combinations reduce rig-up time for pad drilling programs.
- Electric Rotary Tables:Variable frequency drive systems align with rig electrification trends targeting emissions reduction on European offshore platforms.
Standard rotary tables command the established base. The steepest expansion runs through hydraulic rotary tables.
Service Type:
Service revenue splits reflect capital discipline cycles—rental spikes during drilling booms, while refurbishment accelerates in price-depressed intervals.
- Rental Services:Asset-light drilling contractors in the Permian Basin rely on short-term rotary table leases to match rig count volatility. Rental fleets concentrate around Midland-Odessa logistics hubs serving 24-hour mobilization requirements.
- Maintenance Services:Predictive maintenance contracts embedding torque sensor telemetry are displacing time-based overhaul schedules. North Sea operators favor these arrangements to extend asset life within ATEX compliance windows.
- Installation Services:Rig-up supervision ensures API 7K alignment between rotary table interfaces and existing mast structures.
- Repair Services:Emergency weld repair and bearing replacement sustain aging mechanical tables beyond original design life.
Rental services capture volume during drilling upswings. Maintenance services are climbing the fastest as regulatory recertification intervals compress.
End User:
Customer scale determines procurement sophistication—majors negotiate integrated service packages while independents transact spot rental.
- Drilling Contractors:Specialist drilling firms operating 20+ rig fleets standardize on API 7K-certified rotary tables with unified maintenance protocols. These contractors drive specification convergence across the Permian, Bakken, and Eagle Ford shale plays.
- Oil & Gas Operators:Integrated majors with captive drilling divisions specify automated rotary tables with embedded telemetry. ExxonMobil and Chevron deployments in the Permian Basin favor closed-loop hydraulic systems integrated with rig automation architectures.
- Service Companies:Directional drilling and logging contractors require rotary table compatibility with downhole tool deployment systems.
- Independent Producers:Small-scale operators with single-rig programs prioritize rental flexibility over capital ownership.
Drilling contractors anchor procurement volume. Oil & gas operators are gaining share fastest through integrated drilling technology mandates.
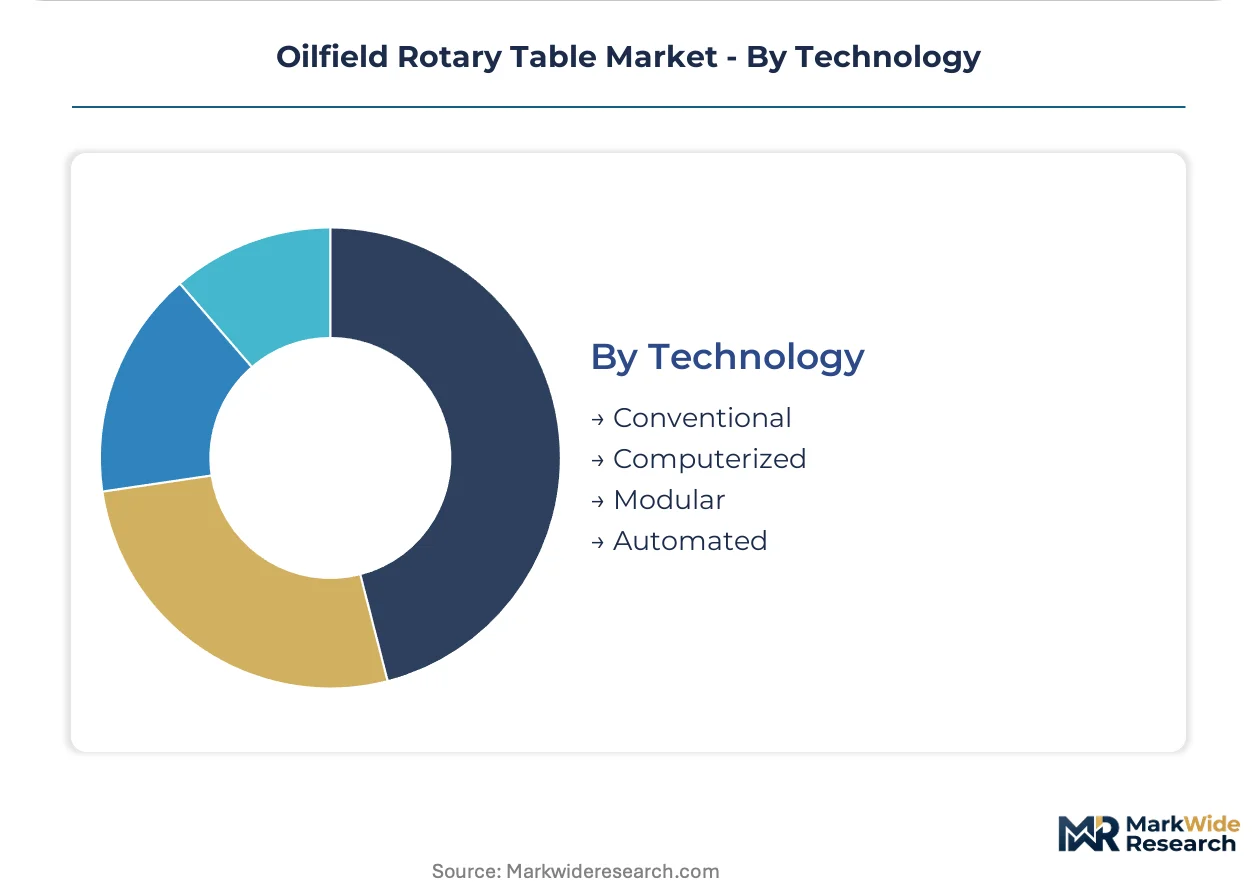
Technology:
Technology tiers stratify by crew exposure reduction priorities and capital availability for automation retrofits.
- Automated:Robotic pipe handling and connection-making systems eliminate manual rotary table intervention. Permian Basin contractors deploy these to reduce insurance exposure and accelerate drilling curves on multi-well pads.
- Computerized:Digital torque monitoring and automated parameter optimization improve rate of penetration in heterogeneous formations. These systems bridge conventional mechanical tables and full automation for mid-size contractors.
- Modular:Swappable sub-assemblies enable rapid reconfiguration between drilling and completion modes.
- Conventional:Mechanical clutch and brake systems persist in legacy rental fleets serving price-sensitive markets.
Conventional technology retains the installed base. Automated systems are expanding most quickly as crew safety regulations tighten across US federal lease operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston-Galveston exporters supply rotary table assemblies to North Sea contractors facing EU Machinery Directive compliance deadlines. Chinese fabricators ship GB/T 23505-certified units to Sichuan shale operators under localized procurement mandates.
United States
Permian Basin drilling contractors drive demand for 2,000+ horsepower hydraulic tables rated for extended-reach laterals. OSHA and EPA enforcement on federally leased acreage disqualifies non-API 7K equipment, redirecting procurement toward certified Houston-Galveston manufacturers. Midland-Odessa logistics hubs support 24-hour mobilization for rental fleet operators.
Norway
North Sea infrastructure aging generates aftermarket demand for remanufactured tables with updated ATEX certification. Petroleum Safety Authority Norway mandates equipment traceability for explosive atmosphere operations. Stavanger-based service providers specialize in refurbishment cycles that compress recertification timelines for offshore contractors.
China
Sichuan and Xinjiang shale development localizes supply chains under GB/T 23505 national standards. NMPA-equivalent pressure equipment regulations create parallel compliance pathways for domestic manufacturers. Chengdu fabricators capture captive demand from joint-venture operators seeking import substitution.
Germany
Ruhr Valley industrial clusters supply forged alloy components to EU offshore markets facing Machinery Directive deadlines. REACH and RoHS constraints on material composition affect bearing and seal procurement for tables deployed on North Sea platforms. Dortmund metallurgical laboratories anchor certification throughput for regional manufacturers.
Brazil
Pre-salt deepwater development specifies closed-loop hydraulic tables for high-pressure formation drilling. ANP regulatory frameworks align with API standards for equipment qualification on federally administered blocks. Macaé service bases coordinate installation and maintenance for foreign OEMs operating under local content requirements.
Oilfield Rotary Table Market Vendor Landscape
Player mix skews toward integrated rig equipment manufacturers with captive metallurgical testing and forging capabilities. The vendor base stratifies across three tiers: multinational OEMs with full drilling system portfolios, regional specialists in refurbishment and recertification, and emerging Asian fabricators serving localized shale markets. Competitive positioning depends on API 7K certification velocity, backward integration into alloy forging, and telemetry integration with rig automation architectures. Capacity expansion and strategic partnerships dominate competitive moves as suppliers compress lead times for compliant equipment.
Within the integrated OEM tier, National Oilwell Varco Inc. and Schlumberger Ltd. anchor premium positioning through control of Houston and Norway manufacturing footprints. RM Holding BV occupies the European aftermarket specialist position, leveraging North Sea refurbishment demand under ATEX compliance windows. Among Chinese fabricators, Chengdu Zhonghang Machinery Co. Ltd. and Shaanxi FYPE Rigid Machinery Co., Ltd. represent the localized supply chain archetype serving GB/T 23505-certified domestic shale development.
| Leading Market Players |
|---|
| National Oilwell Varco Inc. |
| Schlumberger Ltd. |
| RM Holding BV |
| CMIC Ocean En-Tech Holding Co. Ltd. |
| MHWirth AS |
| Pickett Oilfield |
| Chengdu Zhonghang Machinery Co. Ltd. |
| Shaanxi FYPE Rigid Machinery Co., Ltd. |
| YZS |
| Others |
Supply Flow & Price Mechanics
Twenty-four-week lead times for API 7K-certified forged housings concentrate pricing power among Houston-Galveston manufacturers with captive metallurgical laboratories, compressing margins for rental fleet operators unable to secure fixed-price alloy contracts.
Pricing Analysis
The technology-generation pricing gap separates automated hydraulic tables with embedded telemetry from conventional mechanical units and next-generation electric drive systems. Three-tier pricing structure across premium, standard, and economy levels reflects API 7K certification status and torque rating tier. Price differentiation rests on metallurgical traceability documentation and aftermarket service bundling. Cost compression in standard mechanical tiers is intensifying because nickel-chromium alloy volatility erodes fixed-price contract viability. Independent Permian Basin drilling contractors exhibit highest price sensitivity, while integrated majors with captive fleets absorb premium tier pricing for automation integration.
Supply Chain Analysis
Inventory pooling across dual-certification stockpiles stretches working capital cycles for suppliers serving both API 7K and EU Machinery Directive markets simultaneously. Forged alloy supply concentrates in the United States, Germany, and China, with Ruhr Valley specialists supplying bearing housings to North Sea contractors. Raw material dependencies center on nickel-chromium-molybdenum alloy bar stock, high-load tapered roller bearings, and flame-hardened steel master bushings. Single-source vulnerability runs through the Houston-Galveston casting corridor exposed to Gulf Coast hurricane disruption. Distribution runs through Midland-Odessa logistics hubs for Permian Basin rental fleets and Stavanger service bases for North Sea refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forged alloy metallurgy expertise is retiring faster than certification laboratories can replenish technical talent, constraining quality assurance throughput and compressing supplier qualification windows for drilling contractors.
For Market Incumbents: Compound API 7K certification velocity through backward integration into captive forging capacity and metallurgical testing laboratories. National Oilwell Varco and Schlumberger should expand Stavanger refurbishment facilities to capture EU Machinery Directive-driven replacement cycles before ATEX compliance deadlines accelerate. Control of alloy supply chains defends margin position against nickel price volatility eroding fixed-price contract economics. For New Entrants and Emerging Players: Differentiate on telemetry integration and predictive maintenance architectures rather than competing on forged housing manufacturing scale. White-space targets include Sichuan shale localization under GB/T 23505 standards and independent API 7K recertification services for Gulf Coast rental fleets. The most penetrable segment sits among mid-size onshore contractors unbundling after-sales service from equipment procurement. Go-to-market angle: software-integrated rotary tables with subscription-based maintenance contracts displacing time-based overhaul schedules. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because certification mandates are accelerating replacement cycles independently of drilling activity levels. Acquisition target archetype: European aftermarket specialists with ATEX notified body relationships and North Sea contractor service contracts. Signal to watch: divergence between API 7K and EU Machinery Directive recertification timelines forcing inventory duplication strategies among multinational suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive alloy supply insulates margins from nickel-chromium volatility eroding contract economics. |
| Telemetry Integration Partnership | Embedded torque sensors align rotary tables with Schlumberger and NOV rig automation architectures. |
| EU Notified Body Certification Investment | ATEX compliance capability captures North Sea replacement volume ahead of Machinery Directive deadlines. |
| Sichuan Joint Venture Localization | GB/T 23505 certification access secures captive demand from PetroChina and Sinopec shale operators. |
| Refurbishment Facility Expansion | Stavanger and Houston service bases compress recertification timelines for aging offshore infrastructure. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings on certification timeline compression. Drilling contractors, rig equipment procurement managers, API certification laboratory directors, and aftermarket service heads provided operational perspective on replacement cycle dynamics. Secondary sources include API 7K standard documentation, EU Machinery Directive technical files, SEC 10-K equipment segment disclosures, and Norwegian Petroleum Safety Authority equipment traceability records. Bottom-up rig count modeling and top-down shale capital expenditure triangulation validate volume assumptions.
Sensitivity analysis across alloy price scenarios and regulatory enforcement intensity brackets tests forecast robustness throughout the projection horizon. Segmentation dimensions span product type (hydraulic, electric, mechanical), service model (rental, maintenance, refurbishment), end-user scale (integrated major, drilling contractor, independent producer), and technology tier (automated, computerized, conventional). CAGRs derive from rig activity trajectories and replacement cycle elasticity to certification mandates. Industry-specific inputs include Permian Basin lateral length extension curves and North Sea infrastructure age distribution.
The analysis sits within stated boundaries; outcomes outside sustained shale basin deepening or accelerated EU decarbonization timelines would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement consistency and alloy supply continuity. Extreme weather disruption to Houston-Galvestan forging capacity or abrupt API 7K standard revision could compress or extend replacement cycles materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Planned LNG Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Smart Well Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Gold Mining Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
India Oil and Gas Midstream Market