
 LAMEA Microturbine Market | 2026-2036
LAMEA Microturbine Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Microturbine Market Insights
A capital-intensity divergence between integrated manufacturers and assembly-focused suppliers is unwinding competitive hierarchies across the LAMEA microturbine landscape. Capstone Green Energy Corporation leverages its vertically integrated recuperator manufacturing to sustain margin structures in Brazil's offshore power segment. FlexEnergy Solutions anchors its position through fuel-flexible architectures that navigate Latin America's variable gas quality. Ansaldo Energia S.p.A. competes via heavy-duty turbine heritage translated into compact unit reliability for Middle Eastern industrial clients.
Microturbines are compact gas turbines typically rated below 500 kW, employing single-shaft or split-shaft designs with air bearings and recuperators achieving electrical efficiencies of 25–35 percent; their primary purpose is decentralized power generation with minimal footprint and rapid start capability. Combined Heat and Power Systems command the dominant value share due to superior total fuel utilization rates in industrial process settings across the Gulf states. Natural Gas configurations lead fuel-type demand where pipeline infrastructure exists, while Biogas variants represent the fastest-expanding segment driven by landfill and agricultural waste projects in Brazil and South Africa.
Brazil's ANP distributed generation regulations, South Africa's NERSA licensing frameworks, and Gulf standardization bodies including SASO and GSO collectively shape product certification requirements and grid interconnection protocols for microturbine deployments. The EU F-Gas Regulation's extraterritorial influence on equipment imports adds compliance layers for European-originated systems entering LAMEA markets. Stakeholders must monitor evolving carbon border mechanisms and local content rules that will determine supplier qualification thresholds across the region's fragmented regulatory terrain.
Market Dynamics
ANP's distributed generation framework in Brazil is accelerating grid interconnection approvals for sub-500 kW gas turbines, compressing project timelines from 18 months to under 9 months and redrawing competitive entry barriers for foreign suppliers.
Growth Catalysts
- Offshore power mandates:Brazil's pre-salt oilfield operators require continuous on-site generation. ANP regulations exempt remote platforms from grid connection, mandating self-sufficient power architecture.
- NERSA licensing reform:South Africa's simplified embedded generation permits allow industrial facilities to install sub-1 MW systems without full utility-grade certification.
- Recuperator material advances:Ceramic matrix composites in heat exchangers are pushing electrical efficiency toward 35 percent, expanding viable application temperature windows.
Market Restraints
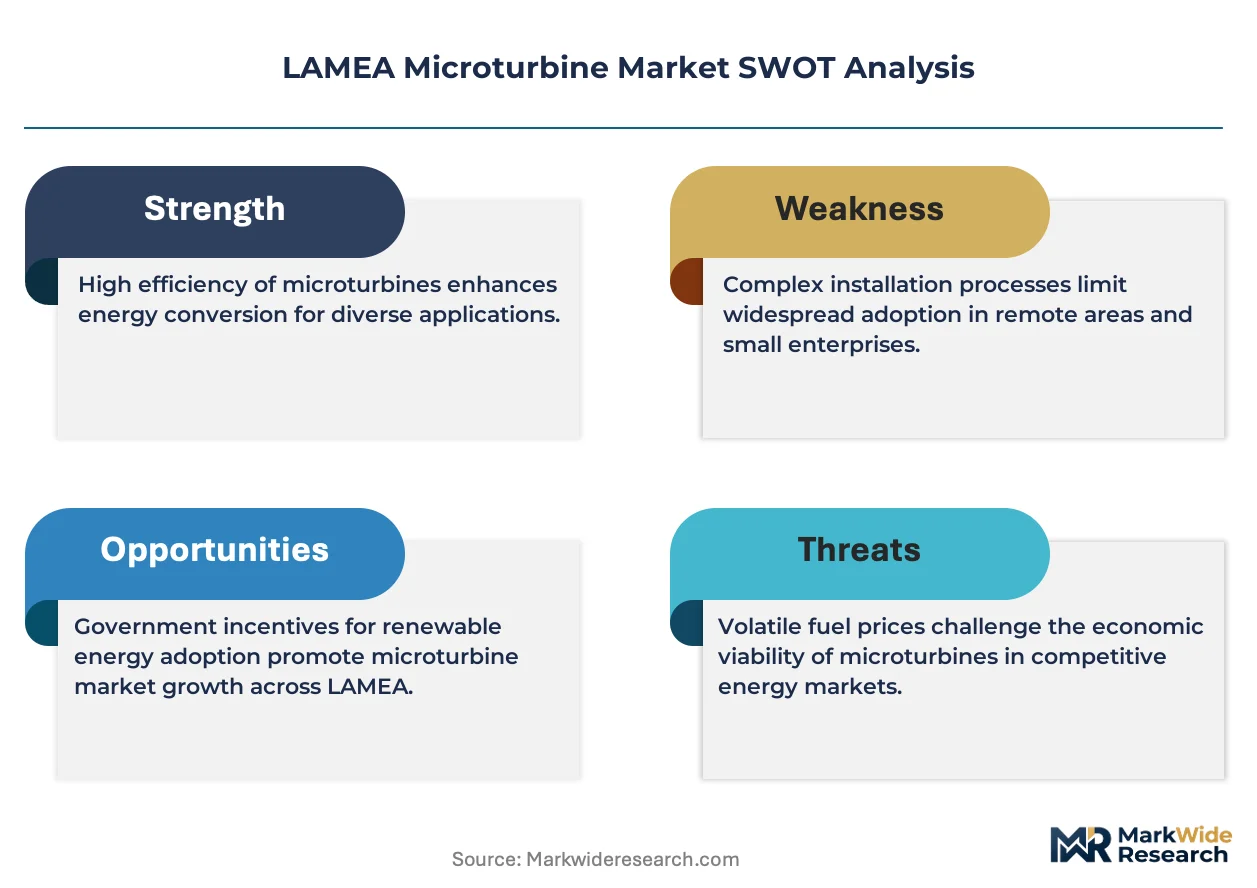
- Natural gas price volatility:Henry Hub-linked contracts in Latin America expose operators to 40-60 percent fuel cost swings, undermining operating expenditure predictability for long-dated power purchase agreements.
- Bearing supply concentration:Air bearing manufacturing concentrates among three specialized suppliers in Germany and Japan, creating 14-20 week lead time exposure for assembly-focused integrators.
- Biogas contaminant thresholds:Hydrogen sulfide levels above 200 ppm in Brazilian landfill gas degrade turbine hot section components, limiting fuel-flexible unit deployment without pre-treatment capital.
Strategic Opportunities
- UAE industrial zone clustering:SASO's streamlined equipment certification for Dubai South and KIZAD free zones offers 6-8 week approval pathways versus 4-6 month national timelines.
- Hybrid renewable pairing:Solar PV plus microturbine configurations address intermittency without battery storage costs, targeting South African mining operations with 24-hour process loads.
- Remote healthcare electrification:MOHAP's rural clinic power standards in northern Emirates create demand for sub-100 kW units with black-start capability and 30-second startup profiles.
Industry Challenges
- Recuperator welding specialization:Inconel superalloy joining requires ASME Section IX-certified technicians, with fewer than 200 qualified welders across the entire LAMEA region.
- EU F-Gas extraterritorial compliance:European-origin systems must document refrigerant containment protocols for import into Gulf states, adding 3-4 weeks to customs clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Microturbine Market |
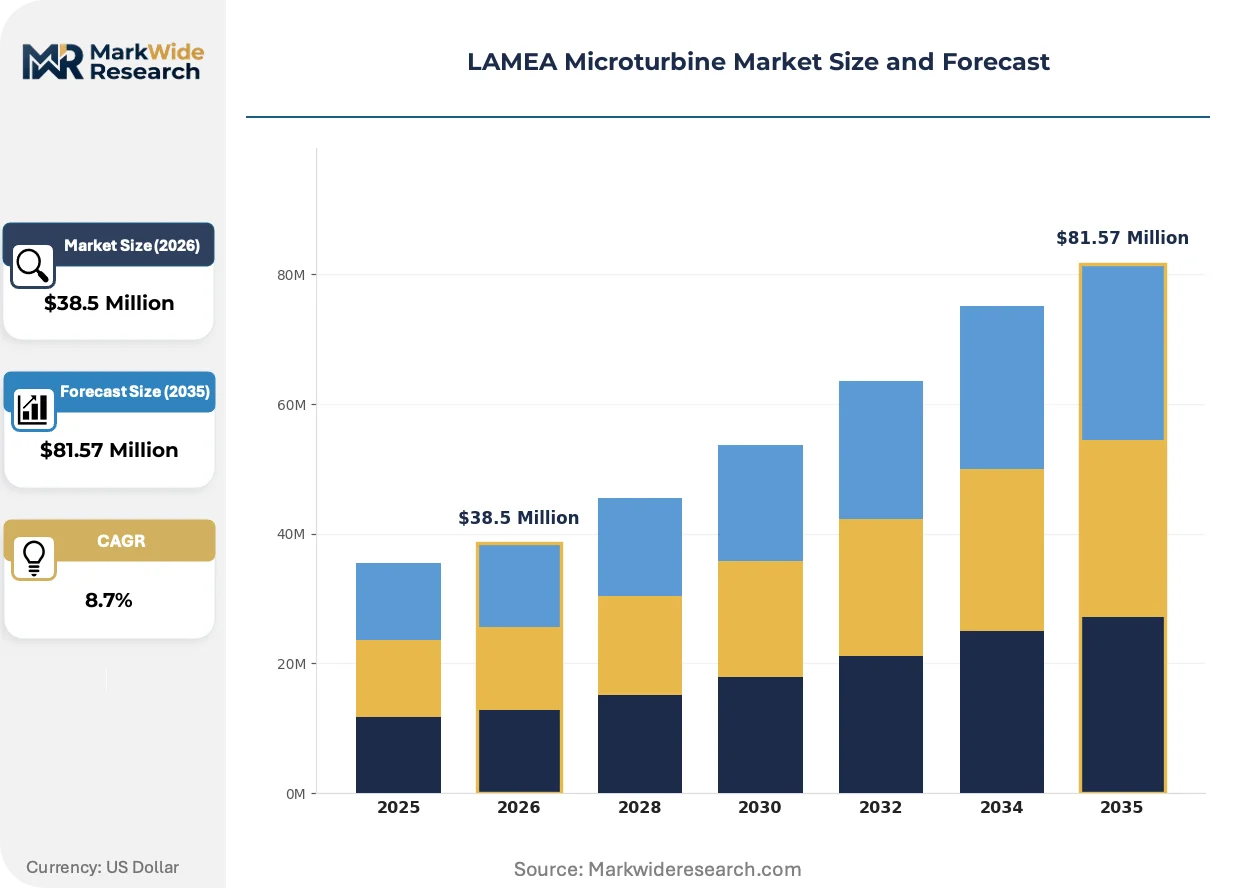
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $81.57 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Microturbines, Grid-Connected Microturbines, Combined Heat and Power Systems, Integrated Microturbines End User: Commercial Buildings, Industrial Facilities, Power Generation Plants, Residential Units Fuel Type: Natural Gas, Biogas, Propane, Diesel Application: Distributed Generation, Backup Power, Remote Power Supply, Combined Heat and Power |
| Companies Covered | Capstone Green Energy Corporation, FlexEnergy Solutions, Ansaldo Energia S.p.A., Bladon Microturbine, Calnetix Technologies LLC, Brayton Energy LLC, ICR Turbine Engine Corporation, Micro Turbine Technology B.V., Aurelia Turbines Oy, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Microturbine Market Trends and Innovations
Digital twin deployment is compressing commissioning cycles and enabling predictive maintenance contracts that shift revenue from equipment sales to performance guarantees across Latin American oilfield services.
Air bearing technology is miniaturizing. Foil bearing systems eliminate oil lubrication entirely, reducing maintenance intervals from 8,000 to 40,000 hours. Petrobras offshore platforms are specifying oil-free architectures for unmanned wellhead installations. This is miniaturizing the viable footprint for sub-200 kW installations, opening deck-space-constrained applications previously reserved for reciprocating engines.
F-Gas Regulation influence extends beyond European borders. Gulf standardization bodies SASO and GSO are adopting containment testing protocols mirroring EU requirements. Importing microturbines with onboard cooling systems now requires third-party leak-rate certification. Brazilian assemblers sourcing European recuperators face additional documentation layers that favor regional fabrication partnerships.
Power purchase agreement structures are fragmenting buyer risk profiles. Large mining houses in South Africa's Northern Cape are unbundling equipment ownership from energy delivery, contracting engineering firms for kilowatt-hour supply rather than asset transfer. This compresses supplier working capital cycles and demands balance sheet capacity for 10-15 year operational commitments.
LAMEA Microturbine Market Segmentation
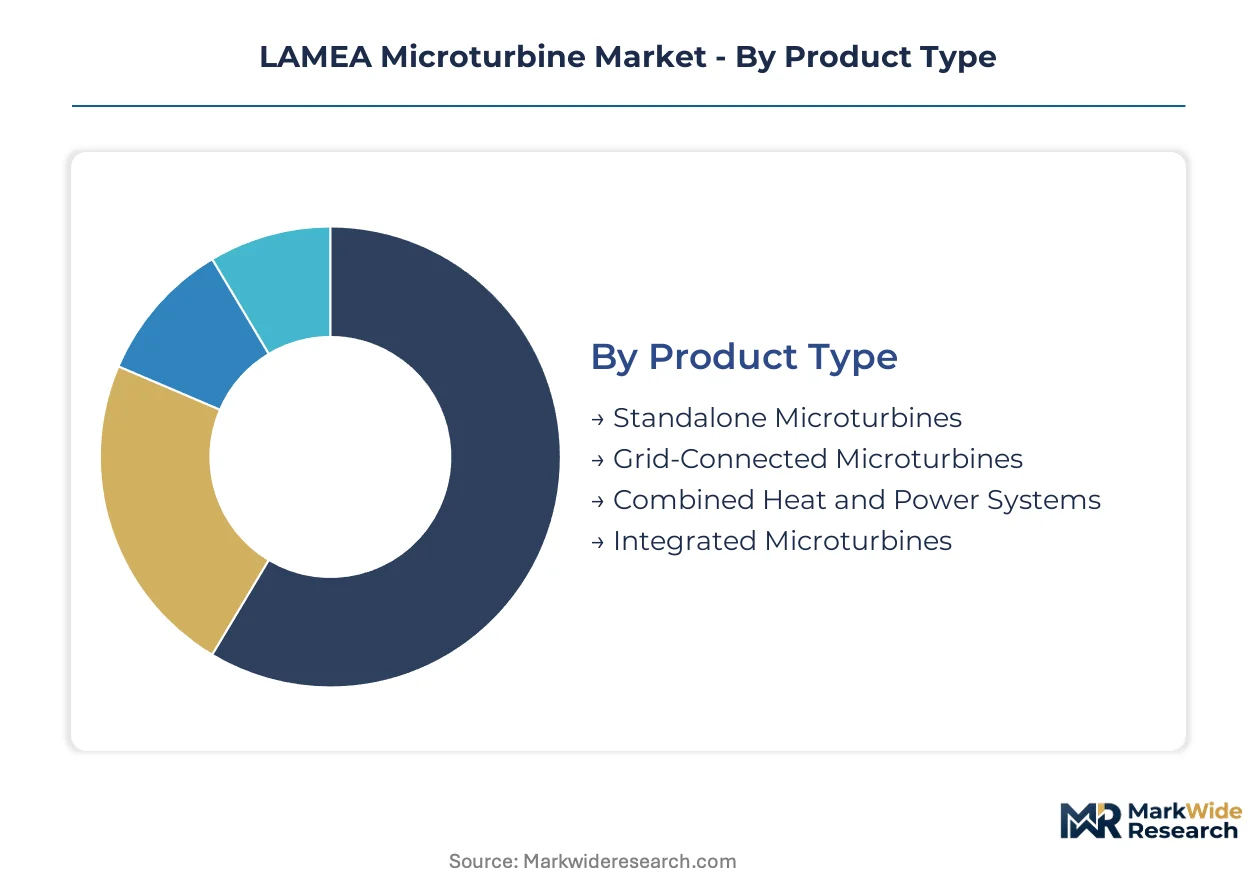
Segmentation in the LAMEA microturbine market reveals distinct procurement patterns between domestic infrastructure projects and export-oriented industrial installations. Understanding these divides helps suppliers align certification strategies with buyer risk profiles across Brazil's oilfields, South Africa's mining belts, and Gulf industrial zones.
Product Type:
Domestic installations in Brazil and South Africa favor simplified architectures, while Gulf industrial zones drive demand for integrated systems requiring SASO certification.
- Combined Heat and Power Systems:These configurations capture waste heat from turbine exhaust to drive absorption chillers or process heating loops. Demand concentrates in Saudi Arabia's petrochemical complexes and UAE aluminum smelters where total fuel utilization rates above 80 percent justify premium capital outlays. ANP's distributed generation incentives in Brazil are accelerating adoption in sugar-ethanol plants seeking thermal integration.
- Standalone Microturbines:Self-contained units without grid synchronization hardware dominate remote mining corridors in South Africa's Northern Cape and unmanned wellhead platforms offshore Brazil. NERSA's embedded generation exemptions allow sub-500 kW deployments without full utility interconnection studies.
- Grid-Connected Microturbines:Synchronization equipment for stable grid injection finds buyers in Dubai South and KIZAD free zones where SASO fast-track certification applies.
- Integrated Microturbines:Factory-integrated power conditioning and switchgear packages serve Gulf hospital complexes requiring black-start capability under MOHAP rural electrification standards.
Combined Heat and Power Systems hold the largest share; momentum sits with Standalone Microturbines.
End User:
Cost-tier stratification separates premium industrial specifications from standardized commercial deployments across the region.
- Industrial Facilities:Continuous-process manufacturers in Brazil's pre-salt oilfields and South Africa's platinum belt specify 24/7 reliability with 40,000-hour maintenance intervals. These buyers accept higher capital intensity for fuel-flexible architectures handling variable gas quality.
- Commercial Buildings:Hotels and office complexes in Dubai's hospitality corridor prioritize compact footprints and low noise signatures over peak efficiency. Procurement runs through engineering-procurement-construction contractors bundling microturbines into building mechanical packages.
- Power Generation Plants:Utility-scale distributed generation developers in Brazil's ANP framework aggregate sub-1 MW units for grid injection at distribution voltage levels.
- Residential Units:Luxury villa compounds in Abu Dhabi's Saadiyat Island represent niche demand for sub-100 kW backup systems displacing diesel generators.
Industrial Facilities dominate volume; Commercial Buildings are climbing the fastest.
Fuel Type:
Application maturity separates pipeline-dependent natural gas from emerging biogas projects requiring contaminant pre-treatment.
- Natural Gas:Pipeline-connected infrastructure in the Gulf states and southern Brazil enables straightforward deployments without fuel conditioning capital. Henry Hub-linked pricing contracts expose operators to volatility, compressing long-dated power purchase agreement tenors.
- Biogas:Landfill and agricultural waste digestion projects in São Paulo state and South Africa's KwaZulu-Natal province drive fastest expansion. Hydrogen sulfide levels above 200 ppm in Brazilian landfill gas degrade hot section components, mandating scrubber investments.
- Propane:Liquefied petroleum gas serves remote mining camps in Namibia and Botswana lacking pipeline infrastructure.
- Diesel:Liquid fuel backup configurations persist in Nigerian industrial estates where gas supply interruptions exceed 200 hours annually.
Natural Gas commands installed base; Biogas shows steepest expansion trajectory.
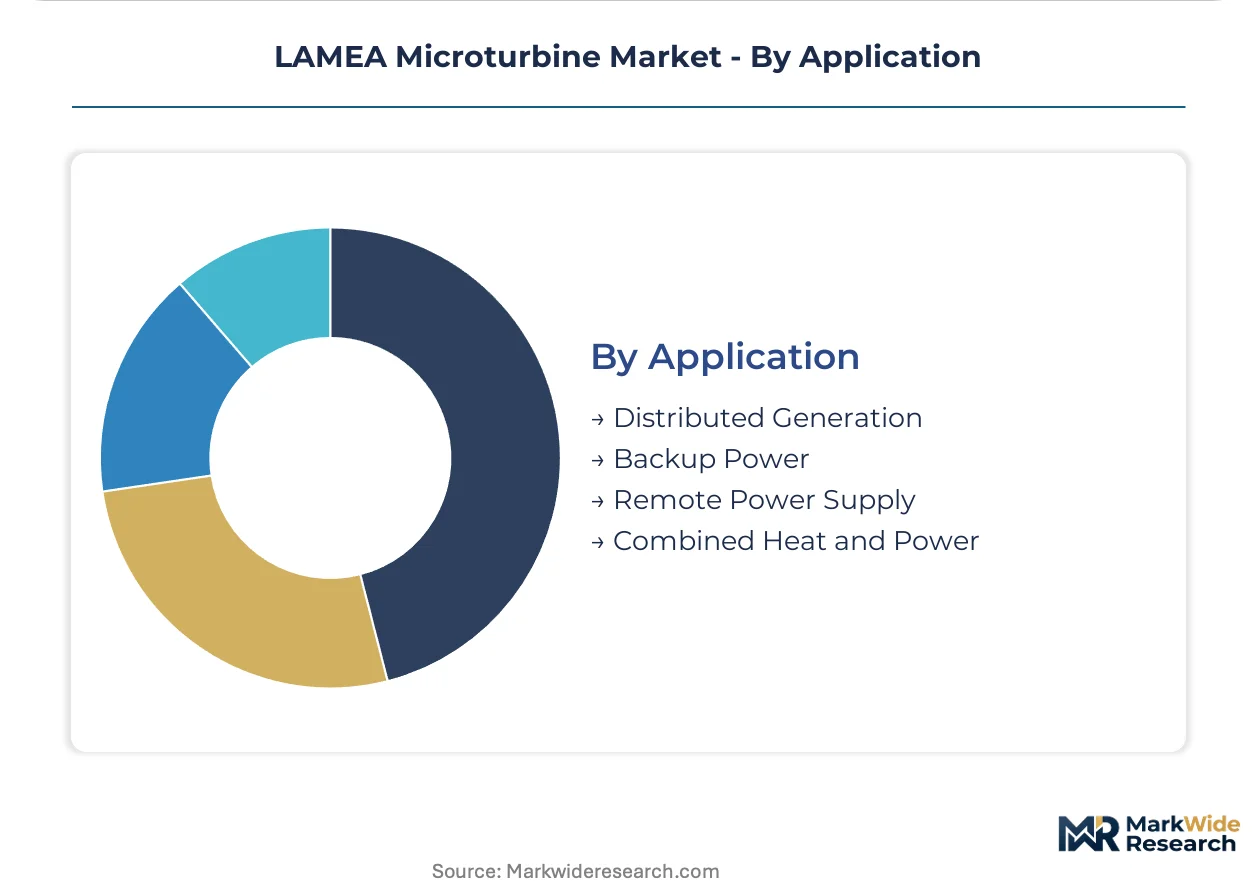
Application:
Customer-type differentiation separates utility-facing distributed generation from captive industrial power behind the meter.
- Distributed Generation:Grid-interconnected sub-1 MW systems under Brazil's ANP framework and South Africa's NERSA reforms enable commercial sale of surplus power. Project timelines compressed from 18 months to under 9 months are redrawing competitive entry barriers.
- Backup Power:Critical facility resilience drives demand in UAE healthcare and data center applications requiring 30-second startup profiles. MOHAP's rural clinic standards specify sub-100 kW units with automatic transfer switching.
- Remote Power Supply:Off-grid installations at Brazilian offshore platforms and Namibian mining operations operate without grid connection mandates. ANP regulations exempt pre-salt wellheads from interconnection requirements.
- Combined Heat and Power:Thermal integration applications in Gulf petrochemical facilities and Brazilian ethanol plants maximize total energy efficiency.
Distributed Generation holds the largest share; Remote Power Supply is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys microturbines primarily for offshore oilfield autonomy, while Gulf states prioritize thermal integration in petrochemical corridors. South Africa's mining belt favors standalone remote power. Each geography imposes distinct certification and fuel-quality requirements.
Brazil
Pre-salt oilfield operators mandate continuous on-site generation for unmanned wellhead platforms. ANP's distributed generation framework compresses grid interconnection timelines from 18 months to under 9 months for sub-500 kW systems. São Paulo state's sugar-ethanol plants are adopting thermal integration configurations to maximize total fuel utilization.
South Africa
Platinum and diamond mining operations in the Northern Cape require 24-hour remote power without grid connection. NERSA's simplified embedded generation permits allow industrial facilities to install sub-1 MW systems without full utility-grade certification. The KwaZulu-Natal province hosts emerging biogas projects processing agricultural waste for turbine fuel.
United Arab Emirates
Petrochemical complexes in Dubai South and KIZAD free zones demand combined heat and power systems with total fuel utilization above 80 percent. SASO's streamlined equipment certification offers 6-8 week approval pathways versus 4-6 month national timelines. MOHAP's rural clinic power standards in northern Emirates specify sub-100 kW units with black-start capability.
Saudi Arabia
Aluminum smelters and desalination plants along the Gulf coast anchor demand for high-reliability thermal integration. GSO's adoption of EU F-Gas containment testing protocols adds documentation layers for imported cooling systems. The Eastern Province industrial cities concentrate procurement through engineering-procurement-construction contractors.
Nigeria
Industrial estates in Lagos and Port Harcourt operate liquid fuel backup configurations due to gas supply interruptions exceeding 200 hours annually. The country's national petroleum regulator maintains fuel quality standards for captive power installations. Niger Delta gas processing facilities are evaluating fuel-flexible architectures to handle variable gas composition.
LAMEA Microturbine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage hinging on recuperator manufacturing control and fuel-flexible engineering. The market structure rewards backward integration into heat exchanger fabrication while penalizing pure assembly plays exposed to bearing supply bottlenecks. Two strategic archetypes dominate: vertically integrated manufacturers capturing margin through captive component supply, and fuel-flexibility specialists navigating variable gas quality environments. Capacity expansion and regional fabrication partnerships represent the dominant competitive moves as suppliers seek to compress lead times and satisfy local content requirements.
Among North American-originated developers, Capstone Green Energy Corporation and FlexEnergy Solutions occupy positions at opposite ends of the integration spectrum. Capstone exemplifies the vertically integrated archetype through captive recuperator manufacturing. FlexEnergy represents fuel-flexible specialization. Ansaldo Energia S.p.A. anchors the European heritage tier, translating heavy-duty turbine reliability into compact unit architectures. These three illustrate how geographic origin and structural positioning shape competitive posture across Brazil's offshore corridors and Gulf industrial zones.
| Leading Market Players |
|---|
| Capstone Green Energy Corporation |
| FlexEnergy Solutions |
| Ansaldo Energia S.p.A. |
| Bladon Microturbine |
| Calnetix Technologies LLC |
| Brayton Energy LLC |
| ICR Turbine Engine Corporation |
| Micro Turbine Technology B.V. |
| Aurelia Turbines Oy |
| Others |
Pricing and Supply Chain Analysis
Recuperator manufacturing scale economies in Germany and Japan anchor component cost floors for assembly-focused integrators across the LAMEA region. Capstone's captive heat-exchanger production in California compresses procurement cycles for Brazilian offshore operators while FlexEnergy's fuel-flexible architectures command premium positioning in variable-gas environments.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value capture more than initial equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates integrated manufacturers with captive recuperator supply from bearing-dependent assemblers exposed to 14-20 week lead times. Price differentiation hinges on ASME Section IX welding certification and fuel-flexibility engineering depth. Cost compression in the standard tier is intensifying because Henry Hub-linked natural gas contracts expose operators to volatile operating expenditure swings. Industrial facilities in Brazil's pre-salt corridors show lowest price sensitivity due to mandated platform autonomy, while South African mining procurement teams negotiate aggressively on upfront capital.
Supply Chain Analysis
Strategic stockpiling of Inconel superalloy sheet and ceramic matrix composite substrates dominates inventory strategy among integrated manufacturers serving Gulf petrochemical complexes. Component fabrication concentrates in Germany, Japan, and the United States for precision air bearings and recuperator assemblies. Raw material dependencies include nickel-based superalloys, high-temperature ceramics, and specialized foil-bearing alloys. Single-source vulnerability in air-bearing supply creates chokepoint exposure for assembly-focused integrators lacking backward integration into rotating machinery. Distribution runs through engineering-procurement-construction contractors in Saudi Arabia's Eastern Province and direct OEM relationships in Brazil's ANP-licensed distributed generation segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA microturbine market operates as a defensive-moat arena where ANP regulatory entrenchment and NERSA licensing frameworks create switching costs that protect incumbent positioning against pure-play assemblers.
For Market Incumbents: Shield installed-base relationships by deepening captive recuperator manufacturing partnerships in São Paulo state to satisfy emerging local content thresholds. Prioritize ASME Section IX-certified welding capacity expansion across the region, where fewer than 200 qualified technicians currently service Gulf and Latin American demand. Counter fuel-flexible entrant pressure by bundling predictive maintenance digital twins into long-dated power purchase agreements that embed operational switching costs.
For New Entrants and Emerging Players: Differentiate on biogas contaminant-handling engineering to capture São Paulo landfill projects and KwaZulu-Natal agricultural waste digestion installations where hydrogen sulfide pre-treatment mandates create technical barriers for pure natural-gas specialists. Target South Africa's Northern Cape mining belt through NERSA's simplified embedded generation exemptions, where sub-1 MW standalone configurations bypass full utility-grade certification requirements. Pursue engineering-procurement-construction contractor partnerships in Dubai South and KIZAD free zones where SASO fast-track certification compresses approval timelines versus national pathways.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with captive heat-exchanger supply and long-term service contract backlogs in Brazilian offshore oilfields. Five-to-ten year viability favors suppliers with demonstrated fuel-flexibility architectures and regional fabrication partnerships that satisfy evolving local content rules. Acquisition target archetype: mid-scale integrators with ANP project execution track records and underutilized ASME-certified welding capacity. Monitor ANP distributed generation tariff revisions as the critical inflection signal; material rate compression would restructure project finance viability across the sub-500 kW segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Fabrication Partnership | Brazilian ANP local content rules favor São Paulo-based recuperator assembly over imported European components. |
| Fuel-Flexibility Certification Investment | Biogas contaminant-handling validation unlocks São Paulo landfill and KwaZulu-Natal agricultural waste project pipelines. |
| Digital Twin Platform Deployment | Predictive maintenance contracts shift revenue from equipment sales to performance guarantees in Petrobras offshore services. |
| ASME Welding Capacity Expansion | Section IX-certified technician scarcity across LAMEA creates bottleneck for recuperator repair and remanufacturing services. |
| SASO Fast-Track Certification Pathway | Dubai South and KIZAD free zone approvals compress equipment authorization from months to weeks versus national timelines. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with microturbine deployment stakeholders and secondary validation across regulatory and project databases. Interview participants included EPC contractors in Saudi Arabia's Eastern Province, ANP-licensed distributed generation developers in São Paulo, maintenance directors at UAE petrochemical complexes, and procurement leads at South African platinum mining operations. Secondary sources encompassed ANP regulatory filings, NERSA embedded generation registers, SASO equipment certification records, and customs data tracking recuperator and bearing imports into Brazil and the Gulf states. Bottom-up unit deployment tallies triangulated against top-down fuel consumption projections and power purchase agreement disclosures.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, fuel source, application segment, and regulatory jurisdiction cluster. Segmentation dimensions included combined heat and power versus standalone configurations, natural gas versus biogas fuel types, and grid-connected versus remote power supply applications. CAGRs were derived from regression analysis of historical deployment rates against ANP interconnection timeline compression and NERSA licensing reform implementation curves. Industry-specific inputs incorporated Henry Hub price volatility scenarios and ceramic matrix composite efficiency advancement timelines.
Forecasts assume regulatory continuity in Brazil's ANP distributed generation framework and South Africa's NERSA embedded generation reforms; material policy shifts would require re-modeling interconnection timelines and local content thresholds. Revision becomes warranted when natural gas price volatility exceeds historical bands or when EU F-Gas extraterritorial compliance requirements expand to additional Gulf standardization bodies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
North America Distributed Power Generation Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Peaking Power Plant Market
Power Generation
Hydrogenerators Market
Power Generation
Global Power to Gas Market
Power Generation
Australia Thermal Power Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
East Africa Power Market
Power Generation
Retail Electricity Market