
 Wind Power EPC Market | 2026-2036
Wind Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power EPC Market Insights
Offshore project development pipelines is narrowing as turbine OEMs and construction firms consolidate around fewer viable sites with grid interconnection capacity. Vestas Wind Systems leverages its nacelle assembly scale to secure long-term service contracts across Northern European waters. Bechtel Corporation anchors its position through integrated civil-marine capabilities that reduce interface risk between foundation and turbine installation. Siemens Gamesa Renewable Energy competes on blade length technology leadership, pushing rotor diameters past commercial thresholds.
Wind power engineering, procurement, and construction encompasses the full-scope delivery of turbine arrays, substations, and transmission infrastructure from design through commissioning, typically involving steel monopile or jacket foundations rated for twenty-five-year design lives in saltwater environments. The primary purpose is converting wind kinetic energy into grid-synchronized electrical output at utility scale. Offshore project type commands premium contract values due to marine logistics complexity and specialized vessel requirements, while onshore segments sustain volume leadership across emerging markets. Fixed installation deployment strategy dominates current awarded capacity, though floating installation categories attract disproportionate engineering investment as water depths exceed fifty meters.
EPA offshore permitting timelines and FERC interconnection queue reforms shape US project economics, while EU F-Gas Regulation and MDR standards constrain equipment sourcing for European developments. China's MIIT and GB standards govern domestic turbine certification, creating divergent compliance pathways for multinational EPC firms. Stakeholders must weigh regulatory fragmentation against capital deployment speed when structuring cross-border consortium arrangements.
Market Dynamics
Offshore wind EPC contractors face a structural squeeze as turbine OEMs consolidate nacelle supply and marine installation vessels become the binding constraint on project timelines. The shift toward 15MW+ turbines is compressing foundation design cycles while stretching port infrastructure beyond original specifications.
Growth Catalysts
- EU Green Deal auction mechanisms:National renewable energy tenders in Germany, Denmark, and the Netherlands are accelerating project pipelines with contract-for-difference structures that de-risk developer capital commitment.
- China's marine development zones:Provincial governments in Jiangsu, Guangdong, and Fujian have designated exclusive offshore wind areas with streamlined seabed leasing procedures.
- Floating foundation engineering:Semi-submersible and tension-leg platform designs are unlocking water depths beyond 60 meters where fixed-bottom economics collapse.
Market Restraints
- Steel price volatility:Monopile and jacket foundation fabrication consumes heavy plate grades whose cost swings directly compress EPC margin buffers.
- Korean and Chinese shipyard concentration:Purpose-built turbine installation vessels are constructed at fewer than six yards globally, creating single-source risk for charter availability.
- Grid interconnection queue congestion:FERC reform timelines in the United States extend project revenue recognition by 18-36 months beyond construction completion.
Strategic Opportunities
- Floating wind in Portugal and Norway:Pre-commercial arrays at 80-120 meter depths offer first-mover EPC firms platform technology validation ahead of scale deployment.
- Integrated power-to-X bundling:Offshore wind paired with electrolyzer platforms creates bundled EPC scopes that capture hydrogen offtake premiums.
- US IRA production tax credit:The Inflation Reduction Act's enhanced credit for domestic content sourcing is reshaping supply chain localization strategies.
Industry Challenges
- Marine commissioning technician scarcity:Specialized crews for high-voltage offshore substation energization command 40% wage premiums over onshore equivalents.
- GB/T certification divergence:China's domestic turbine type-approval standards create parallel compliance tracks that fragment EPC quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power EPC Market |
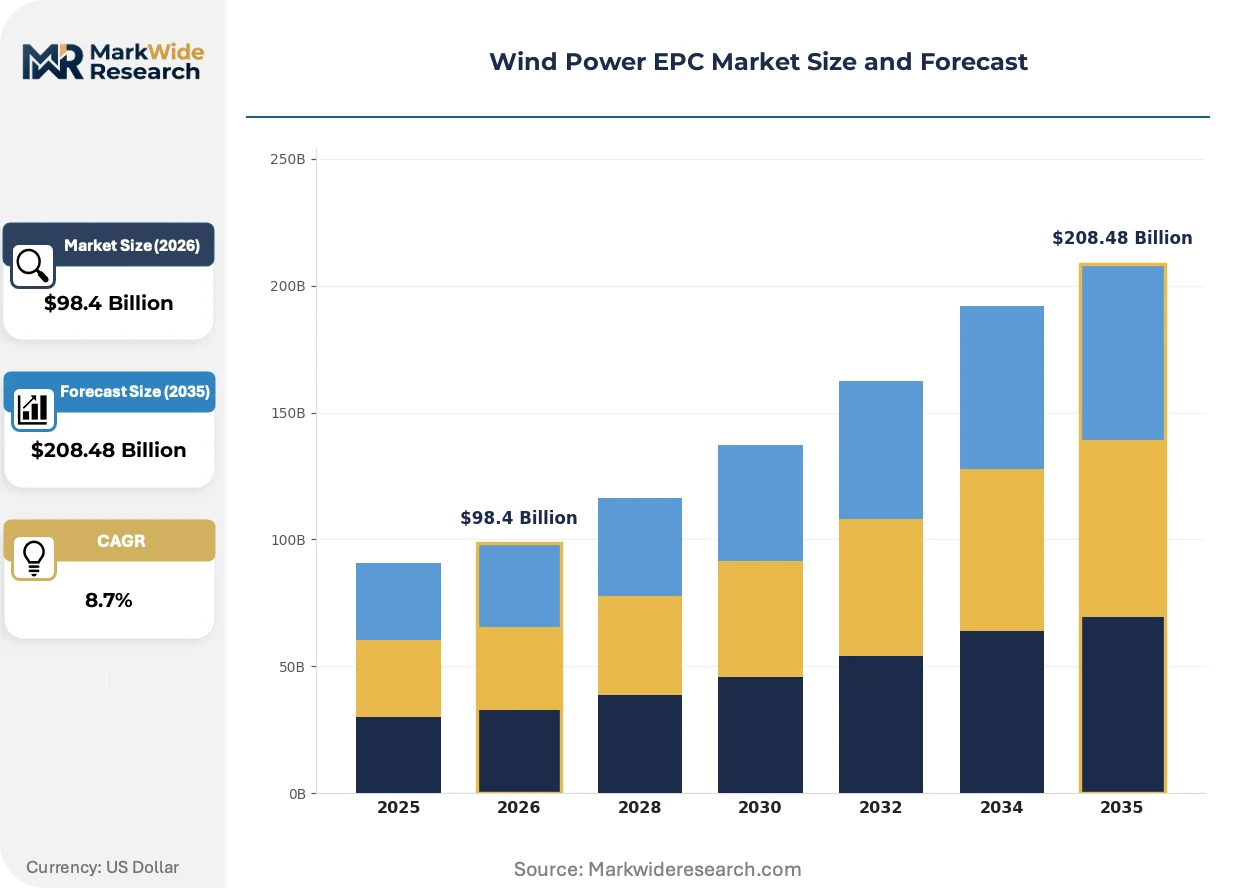
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Onshore, Offshore, Hybrid, Community Service Type: Engineering, Procurement, Construction, Commissioning Deployment Strategy: Fixed Installation, Floating Installation, Mobile Units, Modular End User: Utility Companies, Independent Power Producers, Government, Corporates |
| Companies Covered | Vestas Wind Systems, Bechtel Corporation, Fluor Corporation, Siemens Gamesa Renewable Energy, Larsen & Toubro, CJR Renewables, GE Vernova, Black & Veatch Holdings, Hyundai Engineering and Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power EPC Market Trends and Innovations
Turbine scaling and installation automation are compressing project delivery timelines while regulatory fragmentation forces modular engineering approaches. Three forces are actively restructuring competitive positioning.
Direct-drive generator technology is hybridizing with medium-speed geared architectures as OEMs seek torque density without rare-earth magnet exposure. Offshore developers in the North Sea are piloting these configurations at 12-14MW ratings. The technology convergence is compressing drivetrain supplier margins while expanding nacelle assembly outsourcing options.
EU F-Gas Regulation phase-down schedules are accelerating SF6-free switchgear adoption across offshore substation EPC scopes. The industrial consequence is a 15-20% capital cost premium for gas-insulated alternatives that must be recovered through operational reliability guarantees. German and Danish transmission system operators are now mandating fluoronitrile or vacuum interrupter technologies in new interconnection specifications.
Utility offtakers are unbundling long-term service agreements from initial EPC contracts to retain operational flexibility. Danish and UK offshore wind farms are separating 15-year turbine maintenance from construction procurement, displacing integrated OEM service lock-ins. This pattern is most visible in markets with mature O&M vessel infrastructure where third-party access is economically viable.
Wind Power EPC Market Segmentation
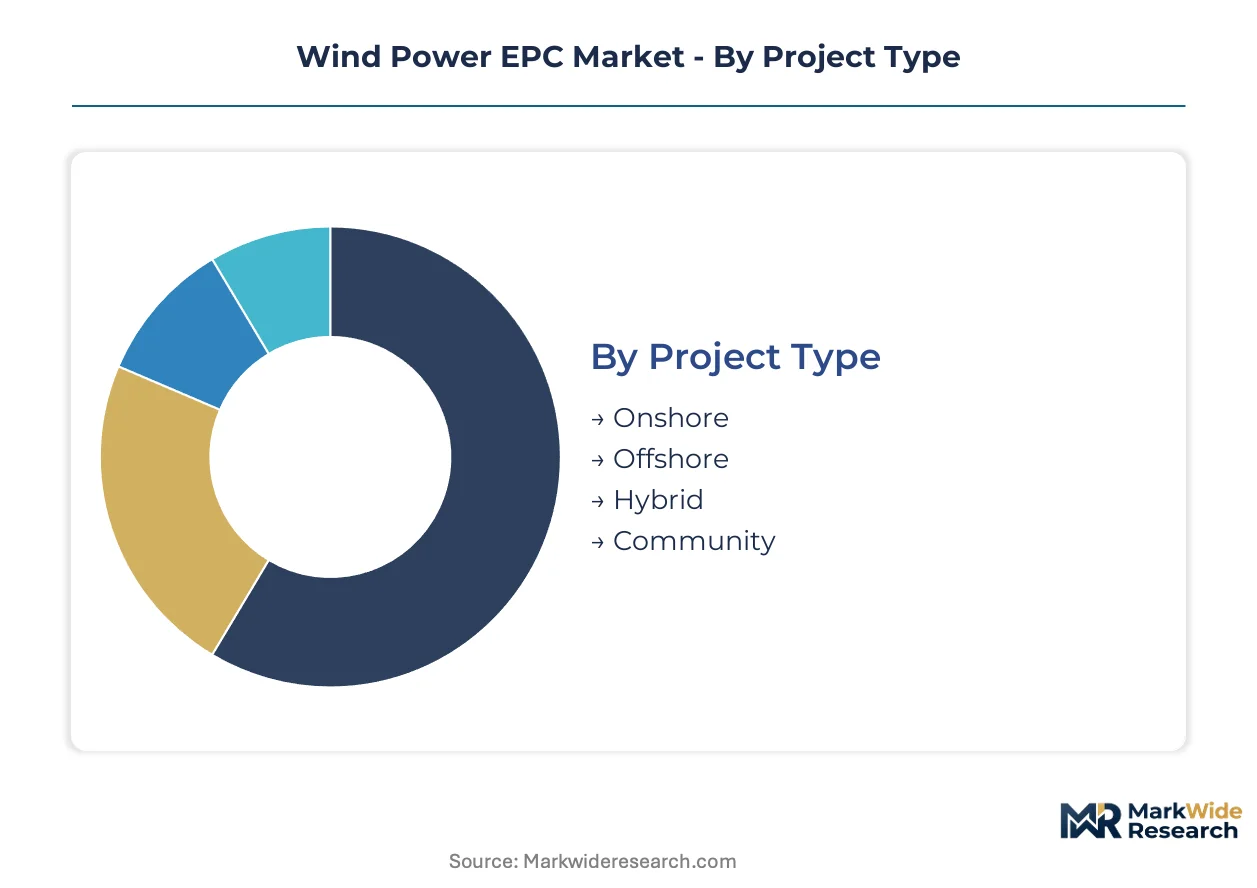
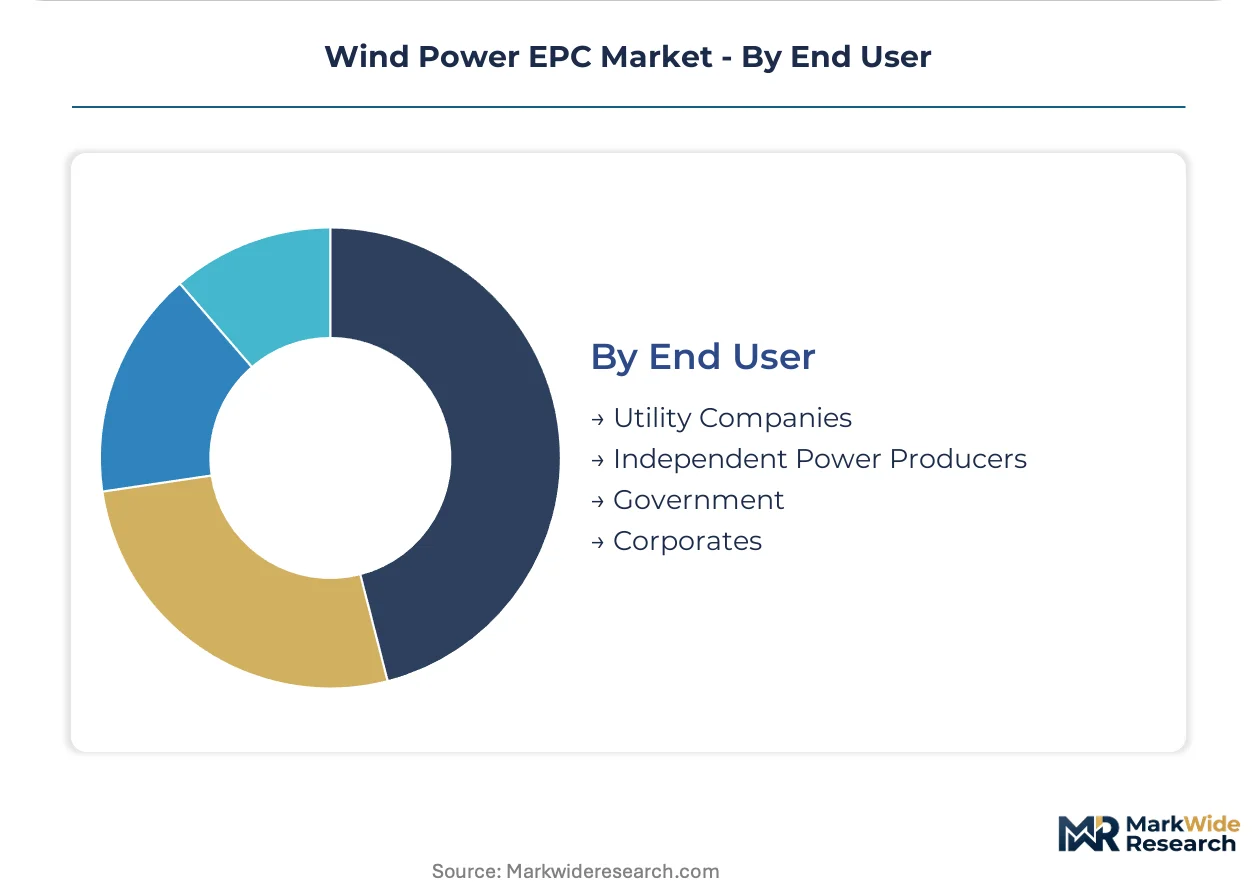
Wind power EPC segmentation reveals how contract scope, technical configuration, and buyer economics reshape vendor specialization. Each dimension carries distinct margin profiles and capability requirements that determine competitive positioning across development cycles.
Project Type:
Mature utility-scale formats coexist with emerging configurations that test new revenue models and risk allocation structures.
- Onshore:Ground-mounted turbine arrays on terrestrial sites dominate awarded capacity across emerging markets. Procurement concentrates with utility companies in India and Brazil where land availability and grid access costs determine project viability. Standardized foundation designs and established crane logistics compress EPC timelines relative to marine alternatives.
- Offshore:Fixed-bottom and floating turbine installations in saltwater environments command premium contract values due to specialized vessel requirements and marine logistics complexity. Demand clusters in China's Jiangsu and Guangdong provinces alongside North Sea developments where seabed leasing frameworks have matured.
- Hybrid:Co-located wind and solar generation with shared substation infrastructure reduces interconnection costs for developers. Configuration appeals to corporates seeking round-the-clock renewable supply contracts.
- Community:Smaller-scale developments with local ownership structures and distributed offtake arrangements. Germany's citizen energy cooperatives and US rural electric cooperatives represent primary demand centers.
Onshore retains volume leadership; offshore holds the steepest expansion curve.
Service Type:
Cost tier differentiation separates high-value integrated scopes from commoditized single-phase contracting.
- Engineering:Front-end design, geotechnical analysis, and turbine layout optimization establish project economics before construction commitment. Firms with IEC 61400 certification access premium pricing for complex offshore foundation design.
- Procurement:Equipment sourcing, long-lead material scheduling, and vendor qualification management. Steel monopile and jacket foundation purchasing consumes disproportionate working capital due to mill capacity constraints.
- Construction:Civil works, turbine installation, and electrical infrastructure build-out represent the largest revenue phase. Marine installation vessel availability has become the binding timeline constraint for offshore developments.
- Commissioning:Grid synchronization testing, performance verification, and operational handover. High-voltage offshore substation energization commands 40% wage premiums for specialized technician crews.
Construction captures the largest contract share; commissioning offers the highest margin expansion potential.
Deployment Strategy:
Application context determines whether fixed infrastructure or adaptable systems suit site-specific constraints.
- Fixed Installation:Permanent steel foundations rated for twenty-five-year design lives dominate current awarded capacity. Monopile configurations prevail in water depths below 40 meters across Northern European and Chinese coastal developments.
- Floating Installation:Semi-submersible and tension-leg platform designs unlock water depths beyond 60 meters where fixed-bottom economics collapse. Pre-commercial arrays in Portugal and Norway offer first-mover validation opportunities.
- Mobile Units:Transportable turbine systems for temporary power supply or disaster recovery applications. Mining operations in remote geographies represent intermittent demand.
- Modular:Standardized, factory-integrated turbine and foundation packages that reduce on-site assembly time. Appeals to developers facing compressed construction windows due to seasonal weather constraints.
Fixed installation maintains deployment dominance; floating configurations are climbing the fastest as water depth frontiers expand.
End User:
Customer type segmentation reflects divergent procurement sophistication, risk tolerance, and contract structuring preferences.
- Utility Companies:Vertically integrated grid operators with long-term integrated resource planning horizons. US utilities expanding offshore wind procurement under IRA production tax credit frameworks represent accelerating demand.
- Independent Power Producers:Merchant developers without regulated rate-base support who rely on power purchase agreements for project finance. Auction mechanisms in Germany, Denmark, and the Netherlands de-risk capital commitment through contract-for-difference structures.
- Government:State-owned enterprises and public authorities procuring renewable capacity for direct ownership or policy compliance. China's provincial governments in designated marine development zones streamline seabed leasing procedures.
- Corporates:Industrial and technology firms securing direct renewable supply through virtual or physical power purchase agreements. Bundled power-to-X scopes pairing offshore wind with electrolyzer platforms attract hydrogen offtake premiums.
Utility companies anchor procurement volume; corporates are gaining share fastest as direct PPA markets deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind EPC contract premiums in Germany and the Netherlands run 35-45% above Chinese coastal equivalents, reflecting divergent labor costs, vessel day-rates, and seabed leasing frameworks. This pricing-power asymmetry is narrowing as Chinese yards expand installation vessel output and European developers confront grid queue delays.
United States
Utility procurement of offshore capacity accelerates along the Atlantic seaboard from Massachusetts to Virginia. FERC interconnection queue reforms and EPA offshore permitting timelines compress project economics. Vineyard Wind and South Fork arrays demonstrate commercial-scale execution patterns for Gulf of Maine lease areas.
Germany
National renewable energy auctions with contract-for-difference structures de-risk developer capital commitment. EU F-Gas Regulation and MDR standards constrain switchgear sourcing for North Sea substations. Port clusters in Bremerhaven and Cuxhaven anchor foundation fabrication and turbine marshaling logistics.
China
Provincial governments in Jiangsu, Guangdong, and Fujian designate exclusive marine development zones with streamlined seabed leasing. MIIT and GB standards govern domestic turbine certification, creating parallel compliance tracks. Yancheng and Yangjiang anchor manufacturing and installation vessel deployment.
United Kingdom
Round 4 and Round 5 leasing frameworks expand capacity pipelines into Celtic Sea and Scottish waters. The Crown Estate seabed licensing process shapes project timeline risk allocation. Aberdeen and Hull anchor operations and maintenance infrastructure for Dogger Bank scale developments.
Norway
Pre-commercial floating arrays at 80-120 meter depths offer first-mover EPC firms platform technology validation. Equinor and Statkraft partnerships test tension-leg and semi-submersible configurations. Stavanger and Haugesund anchor subsea engineering and marine operations clusters.
Wind Power EPC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on foundation and electrical packages. The market structures around three to five dominant EPC consortia per basin, with turbine OEMs consolidating nacelle supply leverage. Two strategic archetypes predominate: integrated civil-marine contractors and pure-play installation specialists. Capacity expansion into purpose-built vessel fleets and backward integration into foundation fabrication represent the dominant competitive moves.
Among Danish-origin turbine OEMs with EPC-adjacent service arms, Vestas Wind Systems occupies a position emphasizing nacelle assembly scale and long-term service contract capture. US-based integrated engineering conglomerates exemplified by Bechtel Corporation and Fluor Corporation anchor the civil-marine tier through interface-risk reduction between foundation and turbine installation. Within the European electrical infrastructure tier, Siemens Gamesa Renewable Energy represents blade length technology leadership and rotor diameter commercialization.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| Bechtel Corporation |
| Fluor Corporation |
| Siemens Gamesa Renewable Energy |
| Larsen & Toubro |
| CJR Renewables |
| GE Vernova |
| Black & Veatch Holdings |
| Hyundai Engineering and Construction |
| Others |
Pricing and Supply Chain Analysis
Korean and Chinese shipyard concentration in turbine installation vessel construction concentrates pricing power with fewer than six yards globally, forcing EPC contractors to absorb charter rate volatility or lock in multi-year contracts at premium levels. This upstream bottleneck cascades into foundation fabrication where steel plate grades swing on mill capacity constraints, compressing margin buffers for integrated scopes.
Pricing Analysis
Configured-to-order pricing for floating foundation arrays commands spreads of 35-45% above standardized monopile equivalents, reflecting engineering customization for water depth and seabed geology. Project-based contract structures dominate, with price differentiation driven by certification grade (IEC 61400 offshore tier vs onshore baseline) and marine logistics complexity. Pricing pressure stems from steel cost volatility in heavy plate grades, with utility buyers in Germany and Denmark showing lowest price sensitivity due to contract-for-difference de-risking, while merchant IPPs in emerging markets negotiate hardest on EPC lump sums.
Supply Chain Analysis
Contract manufacturing for nacelle assembly concentrates at Vestas facilities in Denmark, Siemens Gamesa plants in Spain and Denmark, and GE Vernova operations in France and China. Geographic supply concentration spans China for tower and foundation steel, Germany for specialized switchgear and transformers, and South Korea for installation vessel construction. Raw material dependencies include rare-earth magnets for direct-drive generators, heavy steel plate for monopiles, and copper for array cabling. Single-source vulnerability in purpose-built vessel chartering creates supply chain risk. Distribution runs through port clusters—Bremerhaven, Yancheng, Hull—where foundation staging and turbine marshaling determine project timeline viability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wind Power EPC Market operates as a defensive-moat business where regulatory entrenchment in seabed leasing and grid interconnection protocols creates sticky incumbent positions. Switching costs between EPC consortia escalate once foundation designs are committed and vessel charters locked.
For Market Incumbents: Pre-empt emerging floating platform competition by securing exclusive vessel partnerships at yards in South Korea and China before charter rates escalate further. Anchor backward integration into steel foundation fabrication to capture margin pools currently leaking to specialized fabricators. The threat of 15MW+ turbine scaling compressing design cycles demands captive engineering capacity for geotechnical adaptation. For New Entrants and Emerging Players: Pursue white-space opportunity in floating wind pre-commercial arrays at 80-120 meter depths off Portugal and Norway, where first-mover EPC validation precedes scale deployment. Target the US Atlantic seaboard procurement wave where IRA domestic content requirements disadvantage established European consortia lacking localized supply chains. Angle entry through electrolyzer platform bundling for hydrogen offtake premiums. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across floating installation categories as semi-submersible platform engineering demands specialized marine fabrication assets. Long-term viability over the next decade favors EPC firms with integrated civil-marine capabilities that reduce interface risk between foundation and turbine installation. Watch vessel charter rate indices as the lead inflection indicator—spikes above historical bands signal supply-constrained pricing power migration to installation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Installation Vessel Fleet Expansion | Captures charter pricing power as Korean and Chinese yard output remains constrained. |
| Floating Foundation Technology Licensing | Unlocks water depths beyond 60 meters where Equinor and Statkraft test configurations. |
| Domestic Content Localization | Secures IRA production tax credit eligibility for US Atlantic seaboard developments. |
| Power-to-X Bundling Capability | Captures hydrogen offtake premiums through electrolyzer platform integration. |
| SF6-Free Switchgear Adoption | Meets EU F-Gas Regulation mandates from German and Danish transmission operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA offshore wind outlooks, FERC interconnection queue filings, and EU auction mechanism disclosures. Primary interviews engaged utility planning officers, IPP project developers, EPC contractors, grid operators, and marine vessel charter specialists. Bottom-up capacity and project pipeline tracking triangulates against top-down regulatory framework analysis across the United States, Germany, China, United Kingdom, and Norway.
Forecast inputs span project type segmentation (onshore, offshore fixed, offshore floating), service type tiering (engineering, procurement, construction, commissioning), deployment strategy (fixed vs floating installation), and end-user procurement sophistication (utility, IPP, government, corporate). CAGRs derive from project award velocity, vessel delivery schedules, and seabed leasing framework maturation. Industry-specific inputs include turbine OEM capacity expansion timelines and port infrastructure investment pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned EPC consortia into European waters would shift competitive outcomes. Regulatory acceleration or delay in EPA offshore permitting and FERC queue reform represents primary revision risk. Quarterly review of vessel charter rate indices, steel plate futures, and auction award volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
North America Distributed Power Generation Market
Power Generation
Power Plant EPC Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Commercial Gensets Market
Power Generation
Captive Power Plant Market
Power Generation
Captive Power Generation Market
Power Generation
Distributed Power Generation Market
Power Generation
Distributed Generation Market
Power Generation
South East Asia Power Market
Power Generation
India Thermal Power Plant Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
India Gensets Market
Power Generation
Global Distributed Energy Generation Market