
 Combined Cycle Power Plant Market | 2026-2036
Combined Cycle Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Combined Cycle Power Plant Market Intelligence
A scarcity of control systems engineers with expertise in integrating variable renewable energy sources is bifurcating the market between new-build projects and retrofits. Siemens Energy leverages its extensive service network for complex upgrade projects on existing infrastructure. GE Vernova competes on the efficiency of its H-class gas turbines for large-scale utility applications. Mitsubishi Heavy Industries differentiates through its advanced heat recovery steam generator (HRSG) technology for maximum energy capture.
A combined cycle power plant is a power generation facility employing both gas and steam turbines. It captures waste heat from the gas turbine's exhaust to produce steam for a second turbine, achieving thermal efficiencies often exceeding 60%. Base load power generation remains the dominant application, while the gas turbine component represents the core technology investment area for manufacturers.
The regulatory landscape is shaped by bodies like the US EPA, which sets emissions standards for pollutants such as nitrogen oxides. Frameworks such as the EU Green Deal and China's dual carbon goals incentivize the shift from coal to gas, favoring higher-efficiency combined cycle plants. Stakeholders must now decide on investment pathways for retrofitting existing assets for hydrogen co-firing versus developing new, fully hydrogen-ready facilities.
Market Dynamics
The central dynamic shaping the market is the strategic imperative to bridge near-term energy security with long-term decarbonization goals. This is manifesting in a bifurcation between new-build projects maximizing thermal efficiency and retrofit projects focused on hydrogen co-firing capabilities.
Growth Catalysts
- Policy-Driven Fuel Switching:China's dual carbon goals are accelerating the replacement of coal-fired power plants with higher-efficiency combined cycle gas turbine (CCGT) facilities to reduce particulate and carbon emissions while maintaining grid stability and meeting industrial power demand.
- Industrial On-Site Generation:Large industrial consumers, particularly in the chemicals and manufacturing sectors, are investing in on-site combined cycle plants to secure reliable power, control energy costs, and utilize waste heat for industrial processes, improving overall site efficiency.
- Technological Efficiency Gains:Continuous advancements in gas turbine technology, specifically the development of H-class and J-class turbines, offer unprecedented thermal efficiency levels, providing a strong economic incentive for utilities to upgrade aging fleets or invest in new baseload capacity.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for constructing a new combined cycle power plant, especially one featuring advanced H-class turbines and associated infrastructure, presents a major financial barrier for many project developers and utilities.
- Specialized Labor Scarcity:A shortage of control systems engineers and technicians with the specific expertise to integrate variable renewable energy sources and manage advanced digital control systems for modern CCGTs constrains project execution and long-term operational excellence.
- Renewable Energy Competition:The falling costs and policy support for utility-scale solar PV and wind power, increasingly paired with large-scale battery energy storage systems, present a viable alternative for new capacity additions, challenging the economic case for new gas-fired plants.
Strategic Opportunities
- Carbon Capture Integration:The convergence of CCGT technology with post-combustion carbon capture, utilization, and storage (CCUS) systems offers a pathway to decarbonize gas-fired power generation, creating new opportunities in markets with carbon pricing or emissions reduction mandates.
- Grid Stabilization Services:In markets with high renewable penetration like Germany and Australia, the fast-ramping capability of modern CCGTs creates an opportunity to provide essential grid ancillary services, such as frequency regulation and spinning reserve, generating new revenue streams.
- Hydrogen Retrofit Mandates:Incentives within frameworks like the EU Green Deal encourage the retrofitting of existing gas turbine fleets to enable hydrogen co-firing, opening a substantial service and upgrade market for original equipment manufacturers and engineering firms.
Industry Challenges
- Legacy System Integration:Retrofitting older power plants for hydrogen blending or efficiency upgrades presents significant engineering challenges in integrating new, advanced gas turbines with existing, and often decades-old, heat recovery steam generators and balance-of-plant equipment.
- Advanced Turbine Maintenance Skills:A widening skills gap exists for technicians qualified to service and maintain the latest generation of gas turbines, which incorporate complex materials, tight tolerances, and sophisticated digital monitoring systems, increasing operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combined Cycle Power Plant Market |
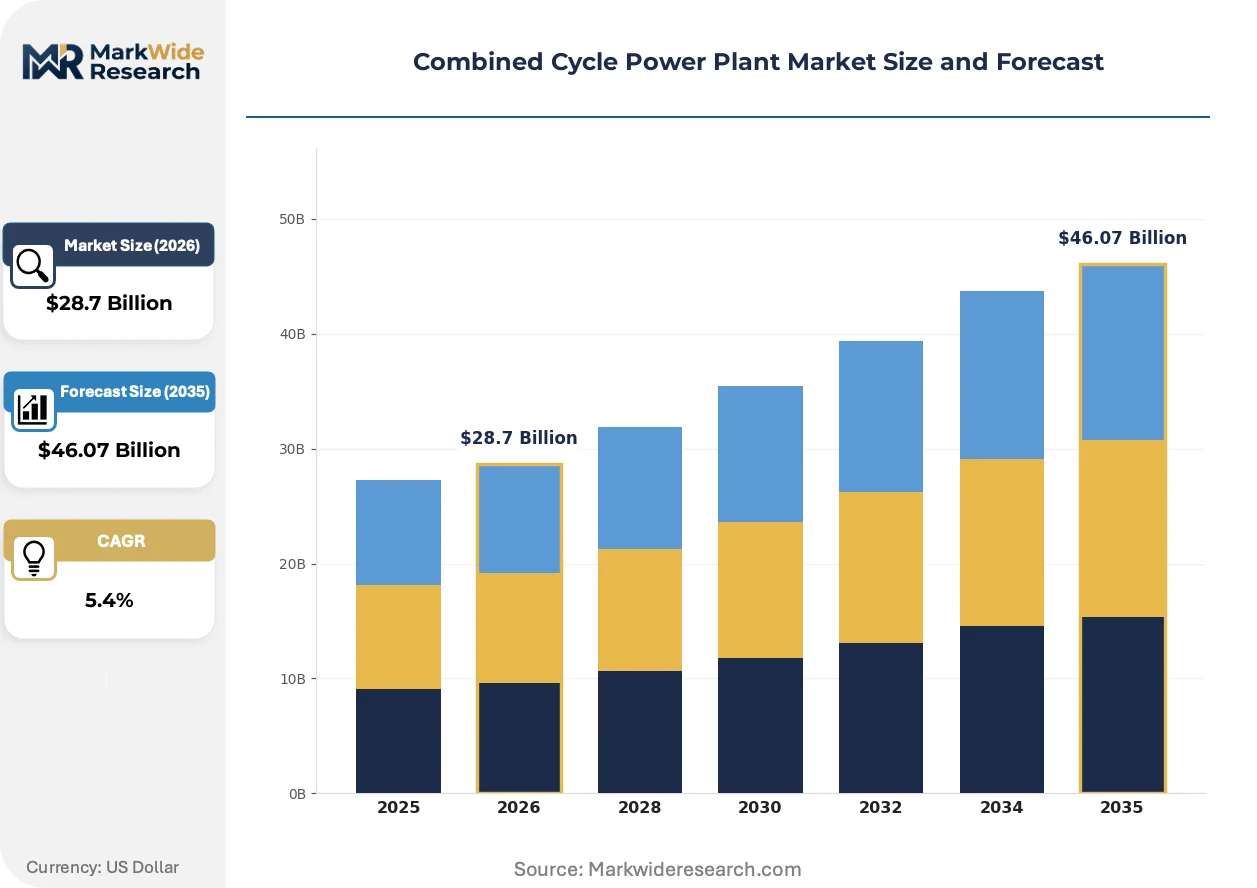
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Heat Recovery Steam Generator, Generators Application: Utility, Industrial, Co-generation, Base Load End User: Power Utilities, Independent Power Producers, Large Industries, Municipalities Installation: Onshore, Offshore, Brownfield, Greenfield |
| Companies Covered | Solar Turbines, Doosan Corp, GE Vernova, Shanghai Electric Group, Ansaldo Energia, Siemens Energy, Kawasaki Heavy Industries, ARANER Group, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combined Cycle Power Plant Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of peak operational performance and fuel source decarbonization. This drives innovation in turbine combustion technology for fuel flexibility while simultaneously pushing the boundaries of thermal efficiency for natural gas applications.
Advanced combustion technology designed for high-percentage hydrogen co-firing is a primary innovation. Power generation utilities and industrial operators are adopting these systems to future-proof their assets against evolving emissions regulations and potential carbon taxes. This fuel-flexible capability is supplanting the singular pursuit of natural gas efficiency, establishing hydrogen readiness as a critical criterion for new turbine selection and investment.
Regulatory frameworks such as the US EPA's stringent standards on nitrogen oxide (NOx) emissions are forcing operational changes. These rules compel plant operators to invest in costly selective catalytic reduction (SCR) exhaust after-treatment systems or adopt advanced dry low-NOx (DLN) combustor technology. This pressure is most acute for older, less efficient plants, often accelerating decisions to either perform major retrofits or retire the asset entirely.
A notable demand-side shift is occurring away from conventional baseload power purchase agreements toward contracts that value operational agility. This change disrupts the economic model for plants built solely for continuous operation, creating a premium for facilities capable of rapid start-up and load-following to balance intermittent renewables. This trend is most visible in energy markets with significant solar and wind capacity, such as California and Spain.
Combined Cycle Power Plant Market Segmentation
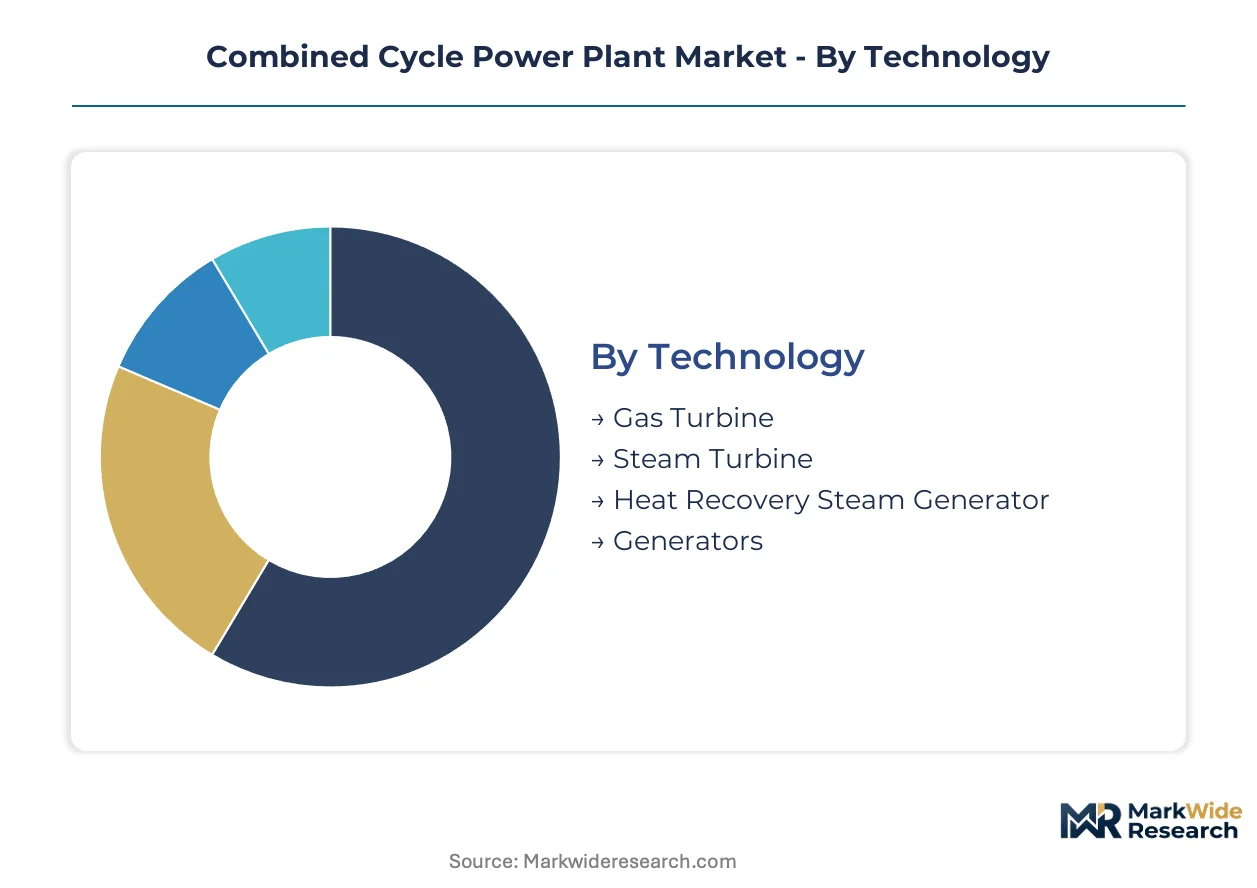
The Combined Cycle Power Plant market's segmentation highlights the diverse technological components, operational applications, and user types that drive investment and innovation. Understanding these segments is crucial for stakeholders to identify areas of concentrated value and emerging growth trajectories within the power generation landscape.
Technology:
Margin pools within the technology segment often centralize around proprietary gas turbine designs and advanced heat recovery systems.
- Gas Turbine:These components serve as the core technology investment area, converting natural gas into mechanical energy for electricity generation. Their efficiency, particularly H-class and J-class models, drives new baseload capacity investments in markets like China.
- Heat Recovery Steam Generator:HRSG technology captures waste heat from gas turbine exhaust to produce steam, significantly increasing overall plant efficiency. Mitsubishi Heavy Industries differentiates its offerings through advanced HRSG designs for maximum energy capture.
- Steam Turbine:This component utilizes steam generated by the HRSG to produce additional electricity, contributing to the plant's high overall thermal efficiency.
- Generators:These devices convert the mechanical energy from both gas and steam turbines into electrical power for transmission and distribution.
Generators hold installed capacity. Heat Recovery Steam Generators are rotating up the share rankings.
Application:
Investment in combined cycle power plants is primarily driven by the specific application requirements, influencing plant design and operational profiles.
- Base Load:This application represents the dominant use for combined cycle plants, providing continuous, reliable power to meet consistent electricity demand. Their high thermal efficiency makes them suitable for long-duration operation in stable grids.
- Industrial:Large industrial consumers, especially in chemicals and manufacturing, utilize on-site combined cycle plants for reliable power and waste heat utilization. This approach enhances energy cost control and overall site efficiency for these facilities.
- Utility:Utility-scale applications often involve large combined cycle plants integrated into national or regional grids to provide stable power.
- Co-generation:These applications simultaneously produce electricity and useful heat, often for industrial processes or district heating, maximizing energy utilization.
Co-generation facilities maintain a steady installed base. Industrial applications are gaining share most quickly.
End User:
The type of end-user dictates procurement strategies and operational priorities for combined cycle power plant projects.
- Power Utilities:These entities invest in large-scale combined cycle plants to provide grid-stabilizing baseload power and manage peak demand. Regulatory frameworks, such as the EU Green Deal, influence their shift from coal to gas.
- Large Industries:Manufacturing and chemical sectors deploy on-site combined cycle units to secure energy independence and optimize process heat utilization. Their investment decisions prioritize reliability and long-term operational cost control.
- Independent Power Producers:IPPs develop, own, and operate power generation facilities, selling electricity to utilities or directly to large consumers.
- Municipalities:Local government entities may invest in smaller combined cycle plants to provide power for municipal services or local grids.
Municipalities maintain a niche market presence. Independent Power Producers are expanding their portfolio.
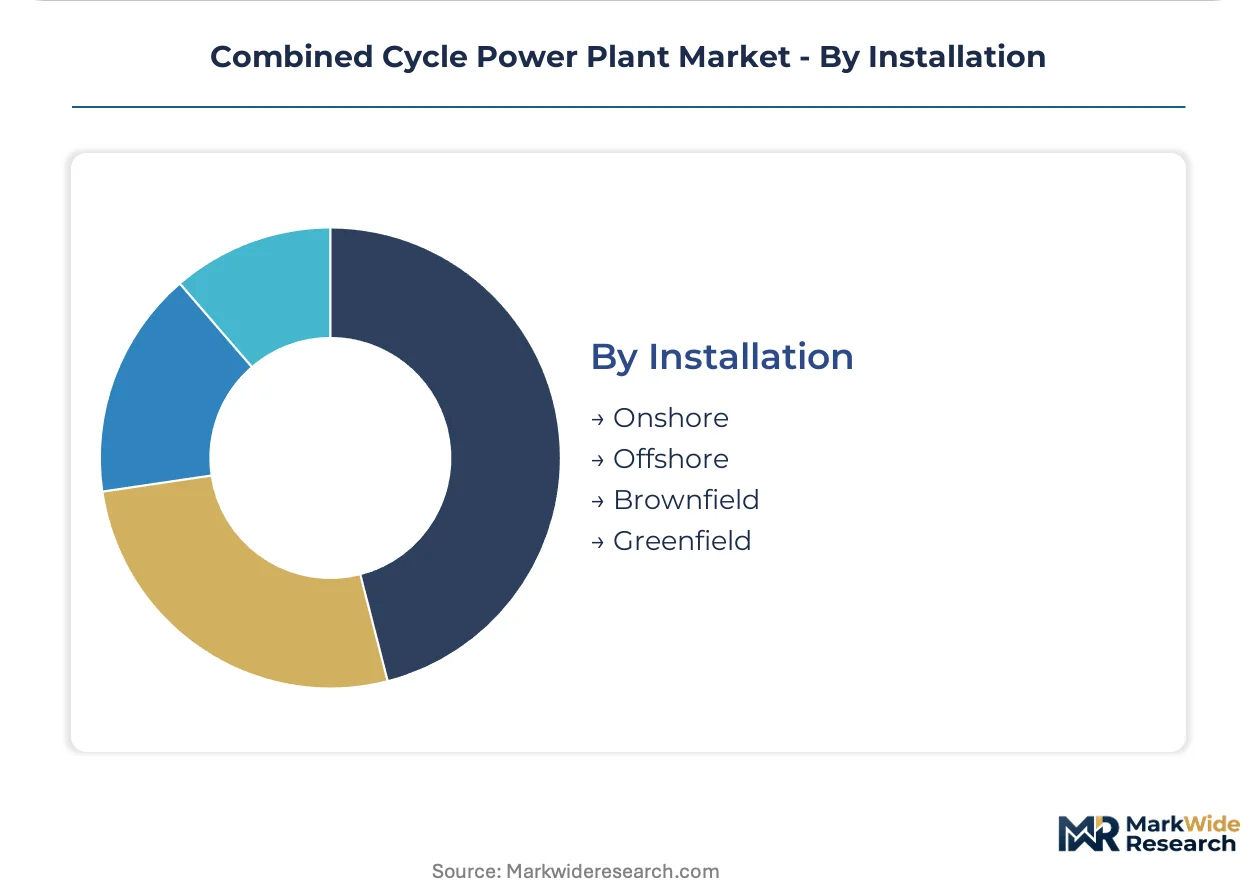
Installation:
Project maturity and site development significantly influence the complexity and cost profile of combined cycle power plant installations.
- Greenfield:These projects involve constructing entirely new power plants on undeveloped sites, allowing for optimal design and integration of the latest H-class turbine technologies. They represent significant capital expenditure but offer maximum efficiency potential.
- Brownfield:These installations involve upgrading or replacing existing power generation assets, often incorporating advanced gas turbines into older infrastructure. Retrofitting older plants for hydrogen blending presents significant engineering challenges.
- Onshore:The vast majority of combined cycle power plants are built on land, leveraging existing infrastructure and gas pipeline networks.
- Offshore:A specialized segment, offshore installations typically involve floating power plants or those on artificial islands, often for remote locations or specific industrial applications.
Offshore installations represent a specialized niche. Brownfield projects are seeing increased investment activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals significantly influence combined cycle power plant investments, driving the replacement of coal-fired assets. This strategic shift aims to enhance energy security while reducing emissions across major industrial regions. Policy frameworks prioritize high-efficiency gas turbine installations for stable power generation.
China
China's MEE standards drive the replacement of older coal plants with high-efficiency CCGTs to reduce particulate and carbon emissions. Industrial power demand in the Yangtze River Delta fuels on-site combined cycle plant development. These facilities support manufacturing while addressing national energy security objectives.
United States
The US EPA sets stringent emissions standards, influencing plant operators to adopt advanced low-NOx combustion technologies or SCR systems. Reliability concerns for industrial users in the Gulf Coast region increase demand for on-site power generation. New projects often feature H-class turbines for efficiency gains.
Germany
The EU Green Deal incentivizes the shift from coal to gas, favoring high-efficiency combined cycle plants for grid stability. Fast-ramping CCGTs in the Ruhr industrial area provide essential ancillary services to balance intermittent renewable energy. Hydrogen retrofit mandates create a service market for existing gas turbine fleets.
Japan
Japan's energy policy emphasizes high thermal efficiency and advanced heat recovery steam generator technology for maximum energy capture. Utilities in the Tokyo Bay area invest in advanced J-class turbines for baseload power generation. This focus supports a stable and efficient national grid infrastructure.
India
India's industrial expansion, particularly in states like Gujarat, drives demand for reliable, on-site power generation in manufacturing clusters. Policy initiatives promote cleaner energy sources to meet growing electricity needs. New combined cycle projects aim to bolster grid stability and reduce reliance on older, less efficient plants.
Combined Cycle Power Plant Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the combined cycle power plant market structure. This market features a highly concentrated core of original equipment manufacturers (OEMs) providing advanced gas and steam turbines, alongside specialized component suppliers. Strategic archetypes include technology innovators focused on efficiency and fuel flexibility, service providers specializing in complex retrofits, and regional players. Dominant competitive moves involve technology licensing, portfolio diversification, and strategic partnerships to expand market reach.
Within the technology innovator archetype, GE Vernova champions the efficiency of its H-class gas turbines for large-scale utility applications. Siemens Energy, a Germany-based industrial powerhouse, leverages its extensive service network, specializing in complex upgrade projects on existing infrastructure. Mitsubishi Heavy Industries, a Japan-based conglomerate, differentiates through its advanced heat recovery steam generator (HRSG) technology for maximum energy capture. These entities collectively drive innovation in turbine combustion, thermal efficiency, and hydrogen co-firing capabilities, shaping the future of gas-fired power generation across various global markets.
| Leading Market Players |
|---|
| Solar Turbines |
| Doosan Corp |
| GE Vernova |
| Shanghai Electric Group |
| Ansaldo Energia |
| Siemens Energy |
| Kawasaki Heavy Industries |
| ARANER Group |
| Mitsubishi Heavy Industries |
| Others |
Cost & Logistics Intelligence
Project-based contracts for new combined cycle power plants lock in long-term supply access for major components like gas turbines, providing price visibility for utilities and industrial operators. These agreements often span years, reflecting the significant capital investment.
Pricing Analysis
Long-term power purchase agreements often define pricing for combined cycle power plants, blending project-based costs with operational service contracts. Pricing stratifies across premium, standard, and economy tiers based on gas turbine efficiency, advanced HRSG integration, and comprehensive after-sales service bundles. Pricing pressure stems from intense competition among major OEMs and the falling costs of alternative renewable energy sources. Municipalities and Independent Power Producers exhibit higher price sensitivity, while large industrial users prioritize long-term reliability and operational cost control.
Supply Chain Analysis
Access to high-grade nickel-based superalloys underwrites the manufacturing of advanced gas turbine components, a critical dependency for the combined cycle power plant supply chain. Key manufacturing hubs for these complex systems are concentrated in Japan, Germany, and the United States. The supply chain relies on specialized steel for heat recovery steam generators and faces structural risk from geopolitical instability affecting natural gas availability. Distribution runs through direct sales channels from major OEMs to utilities and large industrial end-users, often facilitated by EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Combined Cycle Power Plant market represents a defensive moat, underpinned by significant regulatory entrenchment through stringent emissions standards and critical grid stability requirements. High switching costs for existing infrastructure further solidify this market's resilience.
For Market Incumbents: Shield core market share by accelerating R&D into advanced hydrogen co-firing capabilities and expanding service network capacity for complex brownfield retrofits. This counters the threat of falling renewable energy costs and addresses specialized labor scarcity. Deepen vertical integration into digital control systems for enhanced operational efficiency. Prioritize capacity additions in high-growth regions like China to leverage policy-driven fuel switching.
For New Entrants and Emerging Players: Lead with specialized, compact combined cycle solutions targeting industrial on-site generation and co-generation applications in regions like the US Gulf Coast. The most penetrable segment involves facilities seeking energy independence and waste heat utilization. Offer rapidly deployable CCGT units with advanced digital control systems for grid stabilization services in markets with high renewable penetration. Emphasize fuel flexibility, including hydrogen readiness, as a key differentiator.
For Investors and Strategic Acquirers: Capital is best deployed toward companies offering advanced component technologies or specialized engineering services critical for the combined cycle power plant market's long-term viability. This market remains essential for grid stability and industrial power generation over the next decade. Target acquisition profiles include manufacturers of advanced heat recovery steam generators or firms with deep expertise in hydrogen retrofit projects. An inflection indicator will be the acceleration of government mandates for hydrogen co-firing or carbon capture integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | OEMs expand manufacturing for H-class turbines to meet demand from China and the US. |
| Technology Licensing | Accelerates adoption of hydrogen co-firing combustors across diverse regional markets. |
| Vertical Integration into Digital Controls | Enhances operational efficiency and predictive maintenance for utilities. |
| Green Certification Program | Validates low-carbon power generation pathways, attracting environmentally conscious IPPs. |
| Long-term Service Agreements | Secures recurring revenue streams and operational support for complex turbine fleets. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary data validation. Primary research involved discussions with utility planning officers, EPC contractors, OEM product managers, and large industrial plant engineers. Secondary sources included IEA reports, EIA data, company annual reports, and regulatory filings from the US EPA and EU Green Deal. A rigorous bottom-up and top-down triangulation process ensured data accuracy.
The forecast across the analysis window utilized a robust quantitative modeling framework. Segmentation dimensions included technology, application, end-user, installation type, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected growth catalysts. Key industry-specific forecast inputs incorporated anticipated natural gas prices and evolving carbon pricing mechanisms.
The analysis sits within stated boundaries; outcomes outside significant macroeconomic shifts or unforeseen regulatory changes would require recalibration. Forecasts reflect assumptions regarding technological advancements and energy policy stability. Practitioners should keep alternative scenarios live as geopolitical events and renewable energy deployment rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Oilfield Power Generation Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Power Plant EPC Market
Power Generation
Stirling Engine Market
Power Generation
Canada Power EPC Market
Power Generation
Gas Gensets Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Residential Solar Generator Market
Power Generation
Distributed Power Generation Market
Power Generation
Power Generation Technologies Market
Power Generation
Global Gensets Market
Power Generation
United Kingdom Power Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Wind Power EPC Market
Power Generation
Vietnam Power Generation EPC Market
Power Generation
Temporary Power Generation & Power Rental Market