
 Containerized Solar Generators Market | 2026-2036
Containerized Solar Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Containerized Solar Generators Market Analysis
The EU Green Deal's embedded carbon border requirements is consolidating preference for deployable clean power at temporary industrial sites. Yangzhou CIMC New Energy Equipment Co., Ltd. leverages its container manufacturing heritage to control production costs across integrated shell-and-panel assemblies. HCI Energy LLC anchors North American demand through military and disaster-response contracting channels. Off Grid Energy Limited specializes in ruggedized mobile units purpose-built for mining logistics in harsh climates.
Containerized solar generators enclose photovoltaic arrays, battery storage, and power electronics within standard shipping containers, typically achieving 20-50 kW output with plug-and-play grid integration for off-grid or supplementary industrial power. Crystalline silicon technology dominates current deployments due to proven efficiency and supply chain maturity, while bifacial modules capture growing interest for albedo-enhanced output in desert mining environments. Hybrid systems command the strongest margin pools by combining diesel backup with solar-battery stacks, though pure off-grid configurations lead unit volume in humanitarian and remote construction applications.
EMA medical-device equivalency protocols and EU AI Act supply-chain disclosure rules shape certification burdens for European-deployable units, while EPA stationary source thresholds and OSHA temporary power standards govern US construction site acceptance. China's GB standards and MIIT equipment certification create parallel compliance tracks for Asia-sourced hardware. Stakeholders must weigh dual-certification investments against regional demand concentration when allocating product development budgets.
Market Dynamics
Hybrid diesel-solar configurations are displacing pure diesel gensets across remote industrial sites, with procurement officers prioritizing fuel displacement ratios over upfront capital metrics. This substitution dynamic concentrates purchasing power among mining conglomerates and defense contractors with multi-site deployment mandates.
Growth Catalysts
- EU Green Deal carbon border adjustments:Temporary industrial installations in Europe face embedded carbon reporting requirements that favor deployable renewable assets over fossil backup.
- Pilbara mining corridor electrification:Australian iron ore operators are consolidating mobile power procurement under fleet-wide sustainability targets.
- Bifacial module albedo capture:Dual-sided photovoltaic panels extract reflected irradiance from desert and high-altitude terrain, improving output density per container footprint.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production depends on cathode material refining concentrated in Chinese industrial zones, exposing non-Chinese assemblers to input volatility.
- Transport logistics for overweight containers:Fully equipped units exceed standard intermodal weight limits, requiring specialized flatbed haulage that fragments distribution economics.
- GB standards certification friction:China's domestic equipment certification creates parallel compliance tracks that delay export market entry for Asia-sourced hardware.
Strategic Opportunities
- South African platinum belt decarbonization:Underground mining operators face diesel particulate exposure regulations that mandate surface power substitution.
- Disaster-response agency pre-positioning:Federal emergency management authorities in North America are establishing regional equipment caches for grid-down scenarios.
- Container-to-container networking:Mesh-enabled units can synchronize output across distributed arrays, enabling virtual power plant aggregation for utility-scale offtake.
Industry Challenges
- Field technician scarcity for hybrid system commissioning:Diesel-solar integration requires cross-trained electricians comfortable with both combustion engine maintenance and DC power electronics.
- Multi-jurisdiction certification timelines:Units destined for defense contracting must satisfy EPA stationary source thresholds, OSHA temporary power standards, and military environmental stress protocols sequentially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Containerized Solar Generators Market |
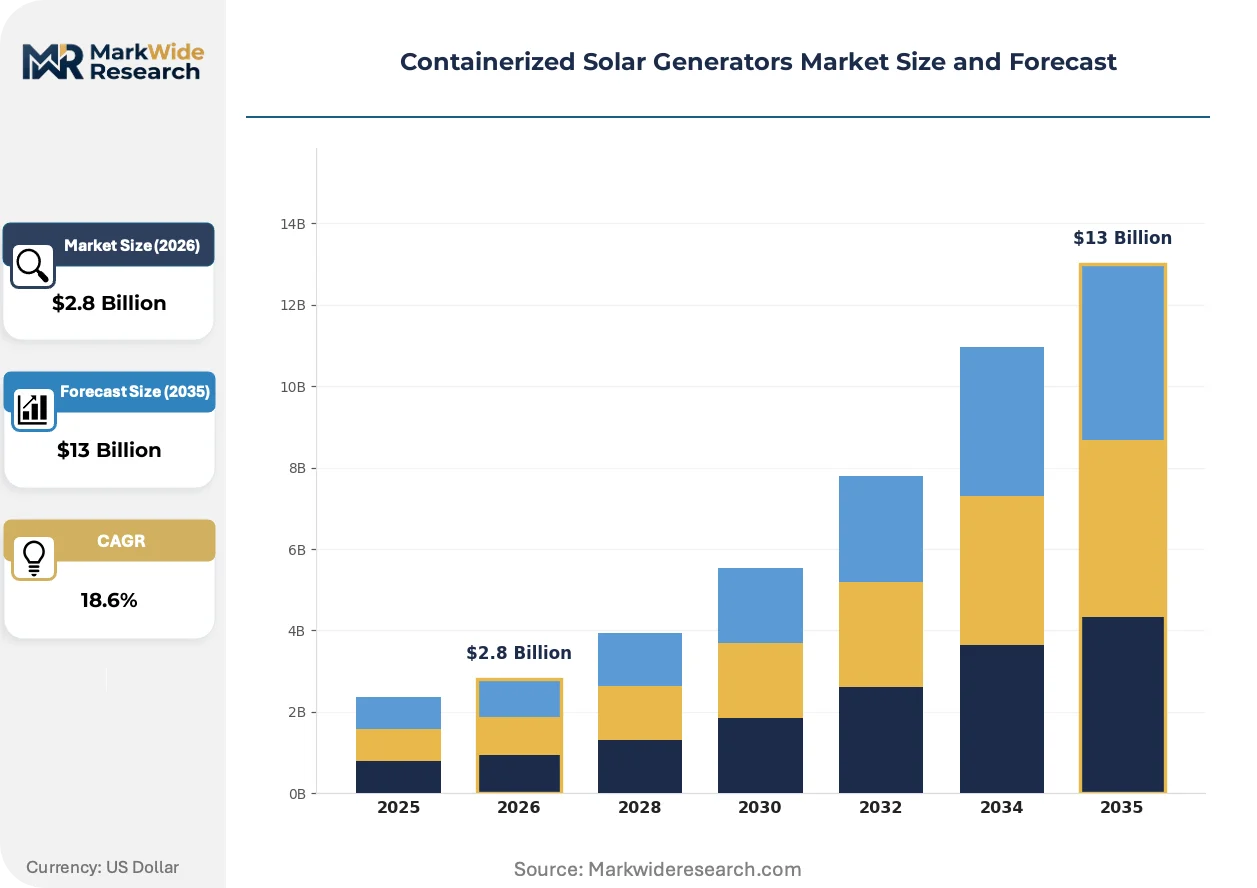
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Units, Stationary Units, Hybrid Systems, Off-Grid Systems End User: Construction Sites, Mining Operations, Events, Emergency Services Technology: Thin Film, Crystalline Silicon, Concentrated Photovoltaics, Bifacial Modules Power Rating: 5 kW, 10 kW, 20 kW, 50 kW |
| Companies Covered | Yangzhou CIMC New Energy Equipment Co., Ltd., Intech Clean Energy Pty Ltd, HCI Energy LLC, REC Solar Holdings AS, Off Grid Energy Limited, Silicon CPV plc, Ecosun Innovations, Jakson Group, Ameresco, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Containerized Solar Generators Market Emerging Trajectories
Intelligent power management software is compressing the operational gap between containerized assets and permanent grid infrastructure. Vendors are racing to embed predictive load balancing and automated dispatch algorithms that reduce manual intervention at remote sites.
Containerized inverters with integrated maximum power point tracking are automating voltage optimization across variable irradiance conditions. Mining operators in Western Australia are deploying these units at haul road maintenance camps where grid extension remains uneconomical. The technology is automating fuel consumption forecasting that previously required on-site engineering oversight.
China's dual carbon goals are accelerating domestic manufacturing scale-up under MIIT equipment certification pathways. Export-oriented producers must now maintain parallel quality documentation for GB standards compliance and destination-market electrical codes. European-deployable units face additional EMA medical-device equivalency protocols when configured for hospital backup power.
Consolidated procurement by diversified mining majors is compressing vendor negotiation cycles from multi-year frameworks to annual volume commitments. Equipment lessors are responding with power-by-the-hour contracts that bundle maintenance and fuel risk. This restructuring is most visible across the African copperbelt, where Glencore and Anglo American operations have centralized mobile power sourcing under group sustainability mandates.
Containerized Solar Generators Market Segmentation
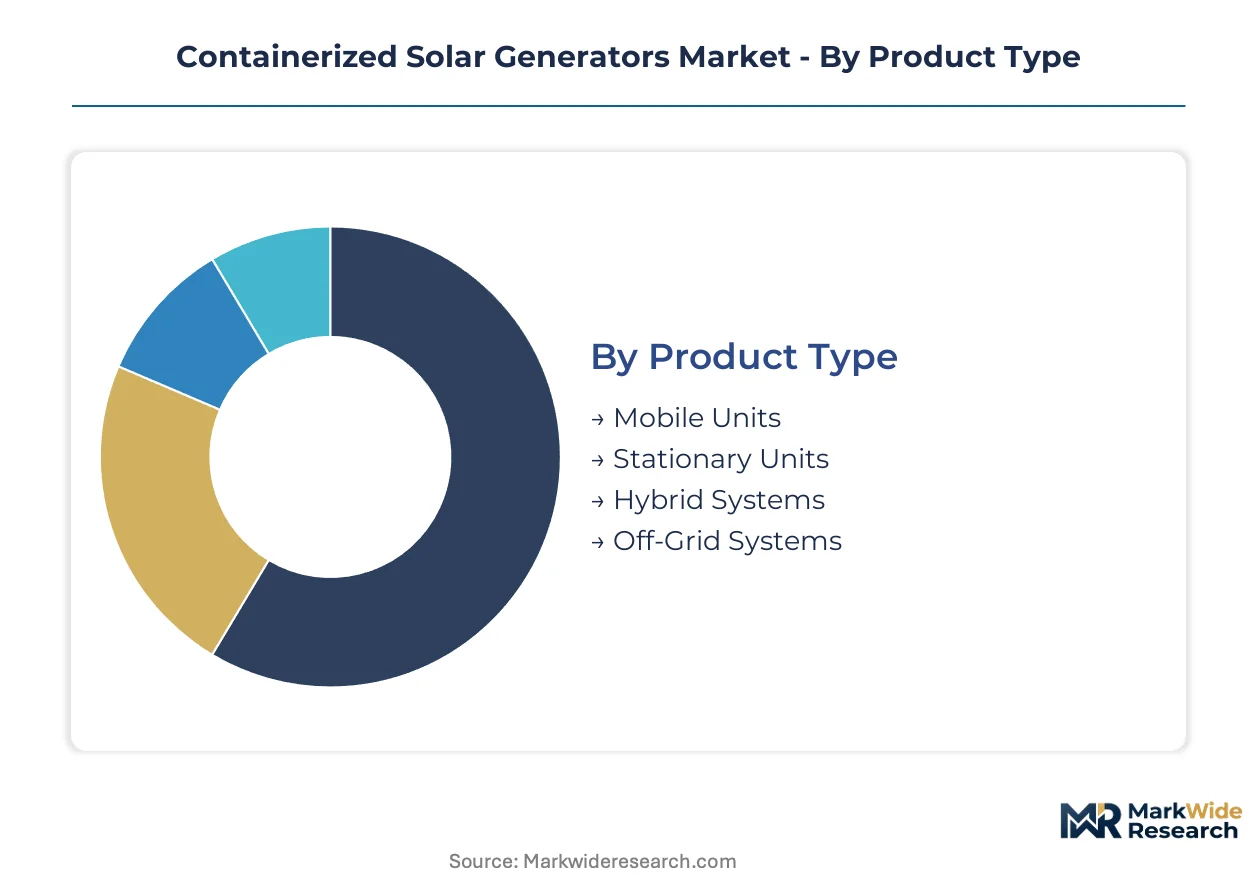
Containerized solar generators serve divergent operational requirements across mobility constraints, power continuity needs, and site permanence. Procurement patterns fragment sharply between fleet-based mining operators seeking standardized mobile assets and fixed industrial installations demanding maximized output density per footprint.
Product Type:
Capital deployment horizons and fuel substitution mandates drive buyer preference across mobility and hybridization options.
- Hybrid Systems:Diesel-solar-battery stacks integrate combustion backup with photovoltaic generation and lithium-ion storage, achieving continuous power through variable irradiance. Mining conglomerates across Australia's Pilbara corridor prioritize these configurations for haul road camps where grid extension remains uneconomical and fuel displacement ratios outweigh upfront capital metrics.
- Mobile Units:Trailer-mounted or skidded containers enable rapid relocation between extraction sites, typically housing 20-50 kW arrays with plug-and-play grid integration. African copperbelt operators deploy these assets sequentially across exploration phases, consolidating procurement under group sustainability mandates that mandate surface power substitution for underground diesel particulate reduction.
- Stationary Units:Fixed-installation containers maximize panel density and structural anchoring for permanent industrial power.
- Off-Grid Systems:Pure solar-battery configurations serve humanitarian and remote construction applications where fuel logistics prove prohibitive.
Volume sits with Mobile Units; growth tilts toward Hybrid Systems.
End User:
Site electrification timelines and regulatory exposure shape demand concentration across temporary and emergency power applications.
- Mining Operations:Surface extraction and underground ventilation systems require ruggedized 50 kW-class units with IP65 enclosure ratings and passive cooling for desert thermal cycling. South African platinum belt operators face diesel particulate exposure regulations that mandate power substitution at shaft heads, while Australian iron ore majors consolidate fleet procurement under Scope 1 reduction targets.
- Emergency Services:Federal disaster-response agencies pre-position containerized assets at regional caches for grid-down scenarios, requiring rapid-deployment skids and military environmental stress protocol compliance. North American contracting channels prioritize units with synchronized output enabling mesh networking across distributed arrays.
- Construction Sites:Temporary electrification for remote infrastructure projects drives demand for mid-scale 10-20 kW units.
- Events:Festival and exhibition power needs favor quieter, lower-emission alternatives to diesel gensets for public-facing installations.
Revenue concentrates in Mining Operations; steepest expansion trajectory belongs to Emergency Services.
Technology:
Module efficiency and supply chain maturity determine technology selection against terrain-specific irradiance capture requirements.
- Crystalline Silicon:Monocrystalline and polycrystalline cells dominate current deployments through proven 19-22% conversion efficiency and established wafer supply chains. Standard containers achieve 20-50 kW output within footprint constraints, with procurement officers prioritizing bankable degradation warranties over incremental efficiency gains.
- Bifacial Modules:Dual-sided photovoltaic panels capture reflected irradiance from high-albedo desert and high-altitude terrain, improving output density per container footprint by 8-15% depending on ground surface reflectivity. Western Australian mining operators deploy these at haul road maintenance camps where terrain albedo enhances generation economics.
- Thin Film:Cadmium telluride and CIGS technologies offer flexible form factors and improved low-light performance for specific niche applications.
- Concentrated Photovoltaics:Lens-based concentration systems target utility-scale installations with dual-axis tracking, rarely deployed in containerized formats due to mechanical complexity.
Shipment volume favors Crystalline Silicon; technology substitution pressure concentrates on Bifacial Modules.
Power Rating:
Load profiling accuracy and intermodal weight constraints govern scale selection across deployment scenarios.
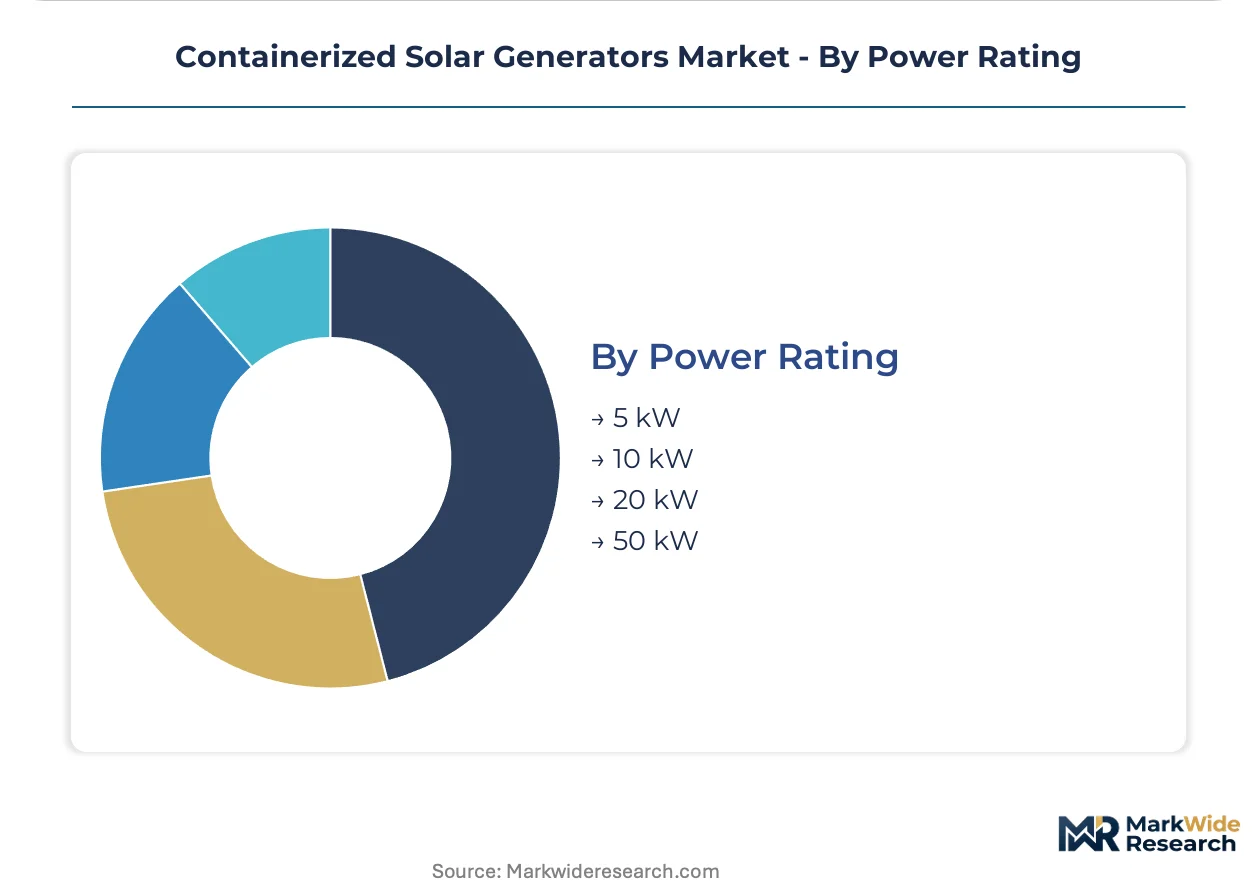
- 50 kW:Fully equipped containers approach intermodal weight limits, requiring specialized flatbed haulage that fragments distribution economics. Mining logistics operators absorb this premium for centralized camp electrification where single-unit output minimizes site infrastructure.
- 20 kW:Standard shipping container compatibility with conventional crane handling enables cost-effective repositioning between construction phases. This rating captures the broadest cross-section of hybrid diesel-solar displacement applications.
- 10 kW:Compact footprints suit rapid-deployment emergency response and small-scale remote monitoring stations.
- 5 kW:Entry-level units serve humanitarian aid and individual facility backup with minimal logistics burden.
Unit economics favor 20 kW; procurement scale aggregates around 50 kW for mining fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers dominate container shell fabrication while Australian and African mining operators absorb the majority of deployed units. This production-consumption split concentrates supply chain leverage in Yangzhou and Ningbo industrial zones.
Australia
Pilbara iron ore operators drive fleet procurement under Scope 1 reduction mandates. The Clean Energy Regulator administers carbon credit frameworks that subsidize diesel displacement ratios. Perth-based logistics hubs coordinate rapid redeployment across the Hamersley Basin extraction corridor.
China
Dual carbon targets accelerate MIIT-certified manufacturing scale-up for export markets. GB standards compliance creates parallel documentation tracks alongside destination-market electrical codes. Yangzhou container fabrication clusters integrate panel mounting and power electronics under single-facility output.
South Africa
Platinum belt underground operators face diesel particulate exposure regulations mandating surface power substitution. The Department of Mineral Resources enforces occupational exposure limits at shaft heads. Rustenburg and Limpopo mining clusters centralize mobile power sourcing under Anglo American and Sibanye-Stillwater sustainability mandates.
United States
Federal disaster-response agencies pre-position containerized assets at regional caches for grid-down scenarios. FERC interconnection standards and OSHA temporary power regulations govern construction site acceptance. Texas and California emergency management authorities lead procurement volume for wildfire and hurricane response.
Germany
EU Green Deal carbon border adjustments favor deployable renewable assets at temporary industrial installations. EMA medical-device equivalency protocols apply to hospital backup configurations. Industrial Rhine-Ruhr clusters test hybrid diesel-solar units for steel and chemical plant maintenance outages.
Containerized Solar Generators Market Vendor Landscape
The competitive structure tilts toward integrated container fabricators with captive shell production. Market concentration remains moderate, with tiered positioning across premium-certified and cost-optimized segments. Three archetypes dominate: diversified equipment conglomerates leveraging manufacturing heritage, specialized off-grid power vendors, and energy service companies bundling deployment with fuel risk. Capacity expansion and strategic certification investments constitute the primary competitive vectors.
Among Asia-Pacific fabricators, Yangzhou CIMC New Energy Equipment Co., Ltd. exemplifies the integrated manufacturing archetype through its container production heritage. Off Grid Energy Limited and HCI Energy LLC occupy positions within the specialized deployment tier, anchoring regional demand concentration in mining and emergency response channels respectively. These three entities represent distinct strategic postures: backward integration into shell production, ruggedized unit specialization, and defense contracting channel capture.
| Leading Market Players |
|---|
| Yangzhou CIMC New Energy Equipment Co., Ltd. |
| Intech Clean Energy Pty Ltd |
| HCI Energy LLC |
| REC Solar Holdings AS |
| Off Grid Energy Limited |
| Silicon CPV plc |
| Ecosun Innovations |
| Jakson Group |
| Ameresco, Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap container fabricators in Yangzhou and Ningbo anchor shell production, translating captive manufacturing into pricing discipline that resists commoditization pressure from pure-play assemblers lacking backward integration.
Pricing Analysis
Margin tightening in mid-tier units reflects lithium-ion cell supply concentration, where cathode material refining in Chinese industrial zones exposes non-Chinese assemblers to input volatility. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade levels separates mining fleet procurement from humanitarian deployment budgets. Cost-down pressure on hybrid configurations accelerates because Australian iron ore operators now consolidate annual volume commitments rather than multi-year frameworks. Construction site buyers exhibit highest price sensitivity due to temporary power duration limits, while defense contracting channels absorb premium tiers for military environmental stress protocol compliance.
Supply Chain Analysis
Regional distribution centers in Perth, Johannesburg, and Houston coordinate hub-and-spoke patterns for rapid redeployment between extraction sites and emergency response zones. Manufacturing gravity centers on China for container shell fabrication and power electronics assembly, with South Korea and Japan contributing high-efficiency cell supply. Raw material dependencies span polysilicon ingots, lithium carbonate, and aluminum extrusion profiles for frame assemblies. Single-source vulnerability in cathode precursor refining creates supply chain risk for battery pack producers outside Chinese industrial zones. Distribution runs through mining conglomerate procurement offices and federal emergency management authorities rather than traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized solar generator supply remains constrained by qualified field technician scarcity for hybrid system commissioning, a capacity bottleneck that props pricing power for vendors with cross-training certification programs.
For Market Incumbents: Deploy captive container fabrication capacity to defend margin position against emerging pure-play assemblers dependent on third-party shell sourcing. Mining conglomerate fleet standardization mandates threaten vendor fragmentation, while MIIT certification investments create switching costs for Asia-sourced hardware. Prioritize diesel-solar integration engineering talent retention as the scarcest competitive resource. For New Entrants and Emerging Players: Disaster-response agency contracting channels offer the most penetrable entry vector, with FEMA and state emergency authorities establishing regional equipment caches for grid-down scenarios. South African platinum belt decarbonization presents adjacent white-space as underground diesel particulate regulations tighten. Pursue power-by-the-hour leasing structures that bundle maintenance and fuel risk to differentiate from capital-sale incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor ruggedized mobile unit specialists with proven mining logistics deployment records in Western Australia and the African copperbelt. Long-term viability hinges on software-enabled virtual power plant aggregation capability for utility-scale offtake. Watch container-to-container mesh networking adoption rates as the inflection signal for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | GB standards compliance unlocks Chinese domestic procurement and accelerates export market entry timelines. |
| Hybrid System Engineering Talent Acquisition | Cross-trained diesel-solar commissioning technicians command scarcity premiums across Pilbara and copperbelt deployments. |
| Power-by-the-Hour Contract Structuring | Equipment lessors absorb fuel price volatility and maintenance burden, aligning revenue with mining operator sustainability mandates. |
| Bifacial Module Integration | Albedo capture technology improves output density per container footprint in desert mining environments like Western Australia's Hamersley Basin. |
| Mesh Networking Software Development | Container-to-container synchronization enables virtual power plant aggregation for utility-scale offtake and grid services revenue. |
Methodological Framework
Trade customs data, MIIT equipment certification registries, and mining industry procurement databases formed the secondary backbone for supply-side capacity assessment. Primary interviews with hybrid system commissioning technicians, mining fleet procurement officers, and federal emergency management contracting leads validated deployment economics and channel structures. EIA distributed generation statistics, IEA off-grid power reports, and FERC interconnection filings anchored demand-side triangulation. Bottom-up unit shipment estimates across power ratings and top-down value reconciliation against disclosed contract values ensured convergence.
Historical trendline analysis of diesel displacement ratios and solar-battery cost curves informed the projection framework across the analysis window. Segmentation modeling incorporated product type, power rating tier, end-use application, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to validated base-year estimates, with technology substitution rates for bifacial modules and hybrid configurations as key forecast inputs.
Several conditions sit outside the modeled scope, including potential tariff restructuring on Chinese container components, lithium-ion cell chemistry disruptions, and military procurement priority shifts. Forecasts reflect documented assumptions regarding mining electrification timelines and carbon border adjustment implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Telecom Generator Market
Generators
Gas Generator Market
Generators
Onboard Marine Gensets Market
Generators
Residential Generators Market
Generators
Generator Sets Market
Generators
Tri Fuel Generators Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Global Diesel Gensets Market
Generators
Portable Inverter Generators Market
Generators
Construction Portable Generators Market
Generators
Africa Diesel Generator Market
Generators
East Africa Diesel Generator Market
Generators
Generator Belt Market
Generators
Electric Generators Market
Generators
Construction Generator Sets Market
Generators
Industrial Generator Market