
 United Kingdom Power Market | 2026-2036
United Kingdom Power Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Power Market Analytics
Grid-scale battery storage specification-tier procurement is rotating toward four-hour duration systems as developers chase enhanced frequency response contracts. EDF Energy leverages its nuclear fleet to anchor baseload power supply while co-locating storage at existing sites. Octopus Energy competes through proprietary Kraken platform technology that optimizes residential demand-side response. SSE Business Energy dominates offshore wind development with active projects in the Dogger Bank zone.
The United Kingdom Power Market encompasses electricity generation, transmission, distribution, and retail supply across England, Scotland, Wales, and Northern Ireland, operating at 50 Hz frequency with nominal voltages from 230 V domestic to 400 kV supergrid. Its primary purpose is delivering reliable, decarbonized electrons to end users while integrating variable renewable output through balancing mechanisms and ancillary services. Renewable generation leads capacity additions with offshore wind commanding premium strike prices in Contracts for Difference auctions, while distributed generation segments grow fastest behind commercial and industrial meter points seeking price hedge certainty. Microgrid applications remain nascent but concentrate margin pools in islanded communities and critical infrastructure campuses.
Ofgem enforces network price controls through RIIO frameworks that reward grid modernization and net-zero alignment, while BEIS and the Climate Change Committee set legally binding carbon budgets that phase unabated gas generation. The Electricity System Operator's 2035 decarbonization target shapes investment timelines and technology qualification standards. Stakeholders must monitor capacity market auction clearing prices and interconnector flow dynamics to calibrate asset commissioning schedules.
Market Dynamics
The United Kingdom Power Market is undergoing structural recalibration as offshore wind lease rounds redirect capital toward East Anglia and Scottish waters, while grid-scale battery procurement specifications extend duration requirements to capture ancillary service revenues.
Growth Catalysts
- RIIO-2 Price Control Framework:Ofgem's regulatory mechanism redirects network investment toward grid flexibility assets, rewarding distribution operators for net-zero alignment and demand-side integration capabilities.
- Data Centre Expansion:Operators across England and Scotland are contracting record volumes of firm capacity, creating anchor demand for new generation and storage co-location projects.
- Offshore Wind Lease Rounds:The Crown Estate's competitive seabed auctions in Dogger Bank and East Anglia zones attract developer consortia seeking long-term CfD-backed revenue streams.
Market Restraints
- Grid Connection Queues:Transmission network capacity constraints in Scotland and northern England delay project energization, with some developers facing multi-year waits for substation availability.
- Supply Chain Concentration:High-voltage cable manufacturing and offshore installation vessel capacity concentrate among North Sea-based suppliers, creating bottleneck risk for serialized project delivery.
- Balancing Cost Volatility:Intermittent renewable output increases system operator procurement of frequency response and reserve services, compressing merchant revenue margins for uncontracted assets.
Strategic Opportunities
- Industrial Microgrids:Critical infrastructure campuses and islanded Scottish communities present underpenetrated demand for behind-the-meter generation and storage integration.
- Demand-Side Response Platforms:Aggregator-enabled residential load flexibility creates new revenue pools as distribution network operators procure virtual capacity under RIIO-2 innovation stimulus mechanisms.
- Hydrogen-to-Power Pathways:BEIS hydrogen production contracts and power sector decarbonization mandates converge to create electrolyzer-to-turbine project development opportunities at existing thermal sites.
Industry Challenges
- Skills Pipeline Constraints:Specialist offshore installation technicians and high-voltage cable jointers face acute supply shortages, extending project commissioning timelines.
- Legacy Asset Stranding:Unabated gas generation capacity must navigate carbon budget compliance and capacity market qualification changes while managing residual debt obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Power Market |
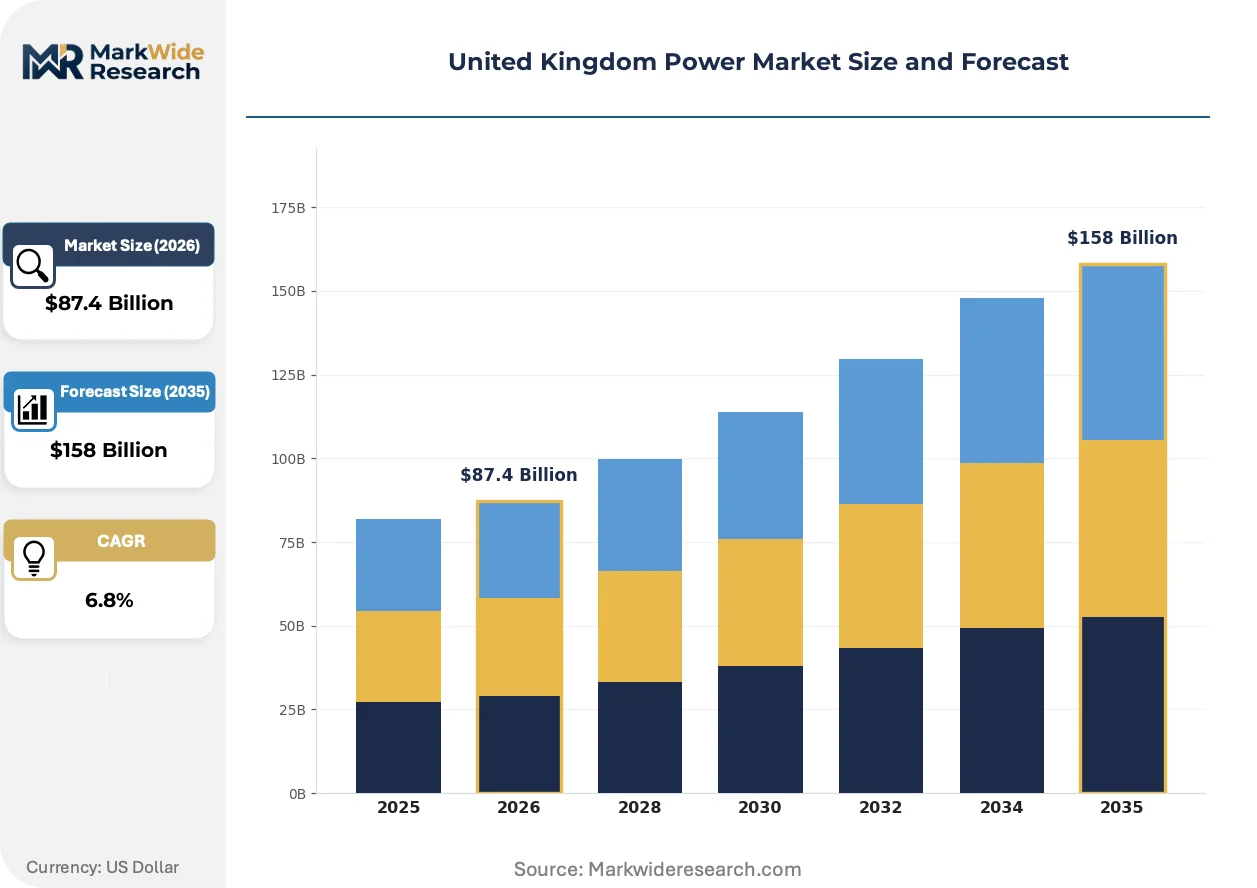
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-renewable, Hybrid, Distributed Generation Application: Residential, Commercial, Industrial, Microgrids Technology: Solar, Wind, Hydropower, Biomass End User: Utilities, Corporations, Households, Government |
| Companies Covered | EDF Energy, OVO Energy, Octopus Energy, SSE Business Energy, TotalEnergies, British Gas, ScottishPower, National Grid, E.ON Next, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Power Market Evolving Landscape
Technology convergence and regulatory redesign are compressing traditional asset lifecycles and rewiring competitive advantage around digital orchestration capabilities rather than pure scale.
Grid-scale battery storage is decomposing the traditional separation between generation and network services. Four-hour duration lithium-ion systems now dominate procurement specifications as developers chase enhanced frequency response contracts and wholesale arbitrage revenues. Distribution network operators in England are piloting these assets as non-wires alternatives to conventional reinforcement, compressing capital deployment timelines from years to months.
BEIS carbon budget mechanisms and the Climate Change Committee's statutory advice are accelerating unabated gas phase-out timelines. The Electricity System Operator's 2035 decarbonization target shapes investment qualification standards and capacity market auction design, forcing thermal asset owners to retrofit or retire. Scottish generators face additional net-zero statutory duties that influence fuel-switching decisions at combined-cycle plants.
Corporate power purchase agreements are displacing traditional utility supply contracts for commercial and industrial offtakers. Large energy users in manufacturing and data processing verticals now procure directly from renewable projects, unbundling commodity and balancing services. This pattern concentrates in England's southeast where grid constraints and price volatility create strongest hedge demand.
United Kingdom Power Market Segmentation
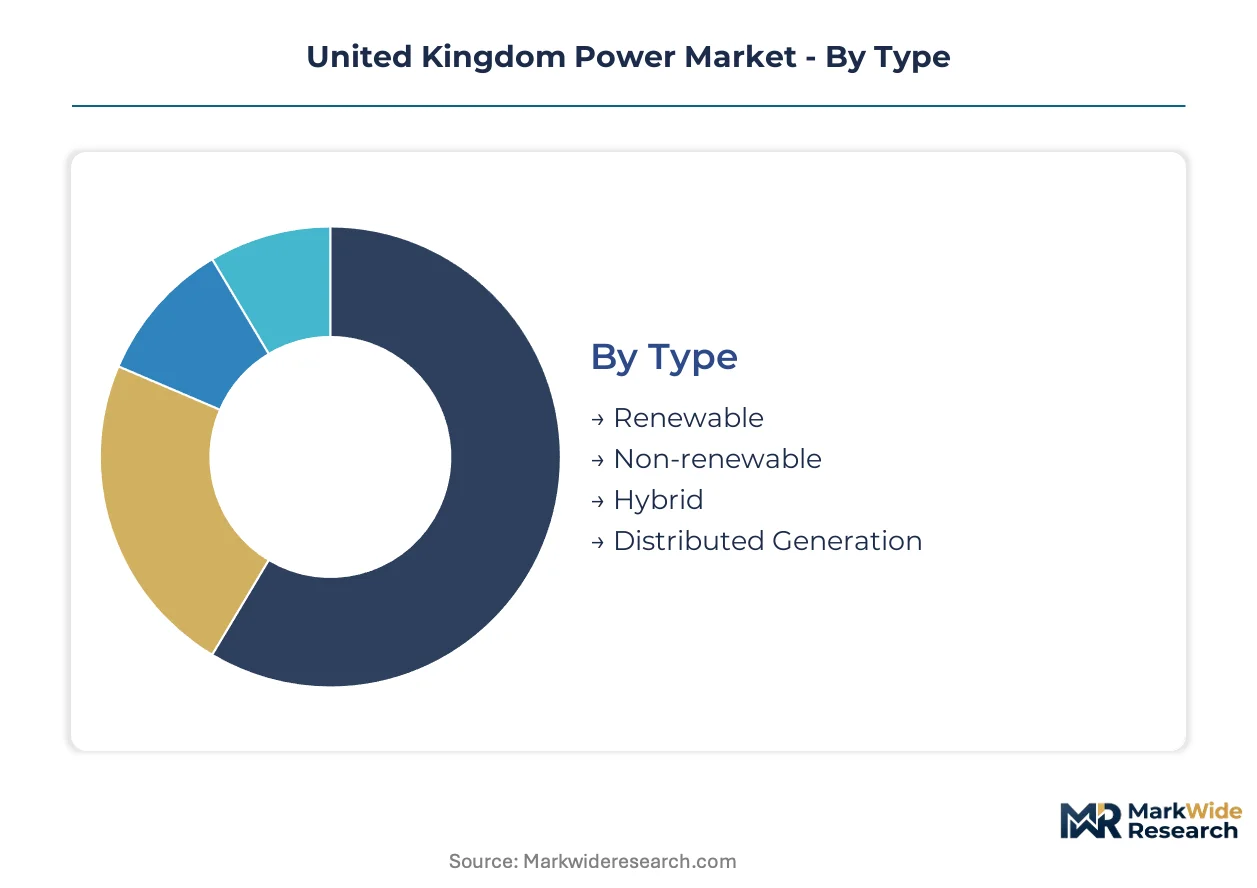
Segmentation in the United Kingdom Power Market reveals how Ofgem's RIIO-2 framework and BEIS carbon budgets differentially incentivize technology pathways. Each dimension exposes distinct margin pools, connection queue priorities, and offtake contracting patterns across England, Scotland, Wales and Northern Ireland.
Type:
BEIS carbon budget enforcement and Ofgem network price controls create asymmetric returns across generation categories, with flexibility premiums diverging renewable from thermal asset economics.
- Renewable:Offshore wind dominates capacity additions, with Dogger Bank and East Anglia lease rounds attracting CfD-backed developer consortia. Scotland's seabed auctions concentrate floating wind innovation where water depths exceed 60 meters.
- Non-renewable:Unabated gas plants face statutory phase-out timelines under Climate Change Committee advice, forcing operators toward carbon capture retrofits or managed retirement before 2035.
- Hybrid:Co-located solar-plus-storage and wind-plus-battery configurations optimize grid connection utilization, with four-hour lithium-ion systems qualifying for enhanced frequency response contracts.
- Distributed Generation:Behind-the-meter solar and small-scale wind concentrate in commercial and industrial campuses seeking price hedge certainty against volatile wholesale markets.
Renewable handles the majority of throughput; Hybrid is expanding most quickly on share as developers chase co-location synergies.
Application:
Demand-side response platform economics vary sharply by load profile predictability and aggregation scale.
- Residential:Octopus Energy's Kraken platform optimizes millions of smart meter-enabled households for peak shaving, with distribution network operators procuring virtual capacity under RIIO-2 innovation mechanisms.
- Commercial:Data centre operators across Slough, London and Edinburgh contract record firm capacity volumes, creating anchor demand for new generation and storage projects with 24/7 baseload requirements.
- Industrial:Manufacturing verticals in England's Midlands and northern England procure corporate power purchase agreements directly from renewable projects, unbundling commodity and balancing services.
- Microgrids:Islanded Scottish communities and critical infrastructure campuses present underpenetrated demand for behind-the-meter generation integration where grid extension costs prove prohibitive.
Commercial absorbs the largest capacity volumes; Microgrids are gaining share fastest as resilience premiums justify capital deployment.
Technology:
Supply chain bottlenecks and installation vessel availability differentially constrain deployment timelines across generation technologies.
- Solar:Utility-scale ground-mount projects concentrate in England's south and east where irradiance levels support merchant revenue stacking with wholesale arbitrage and ancillary services.
- Wind:Fixed-bottom offshore installations in shallow North Sea waters command premium strike prices in CfD auctions, while floating technology unlocks deeper Scottish waters previously inaccessible.
- Hydropower:Existing pumped storage assets in Scotland and Wales provide system inertia, with new run-of-river development limited by environmental permitting constraints.
- Biomass:Drax Power Station anchors national supply, with sustainability certification requirements under BEIS rules shaping feedstock procurement from domestic forestry and agricultural residues.
Wind carries the dominant capacity share; Solar is climbing the fastest as interconnection queues and planning timelines compress relative to offshore alternatives.
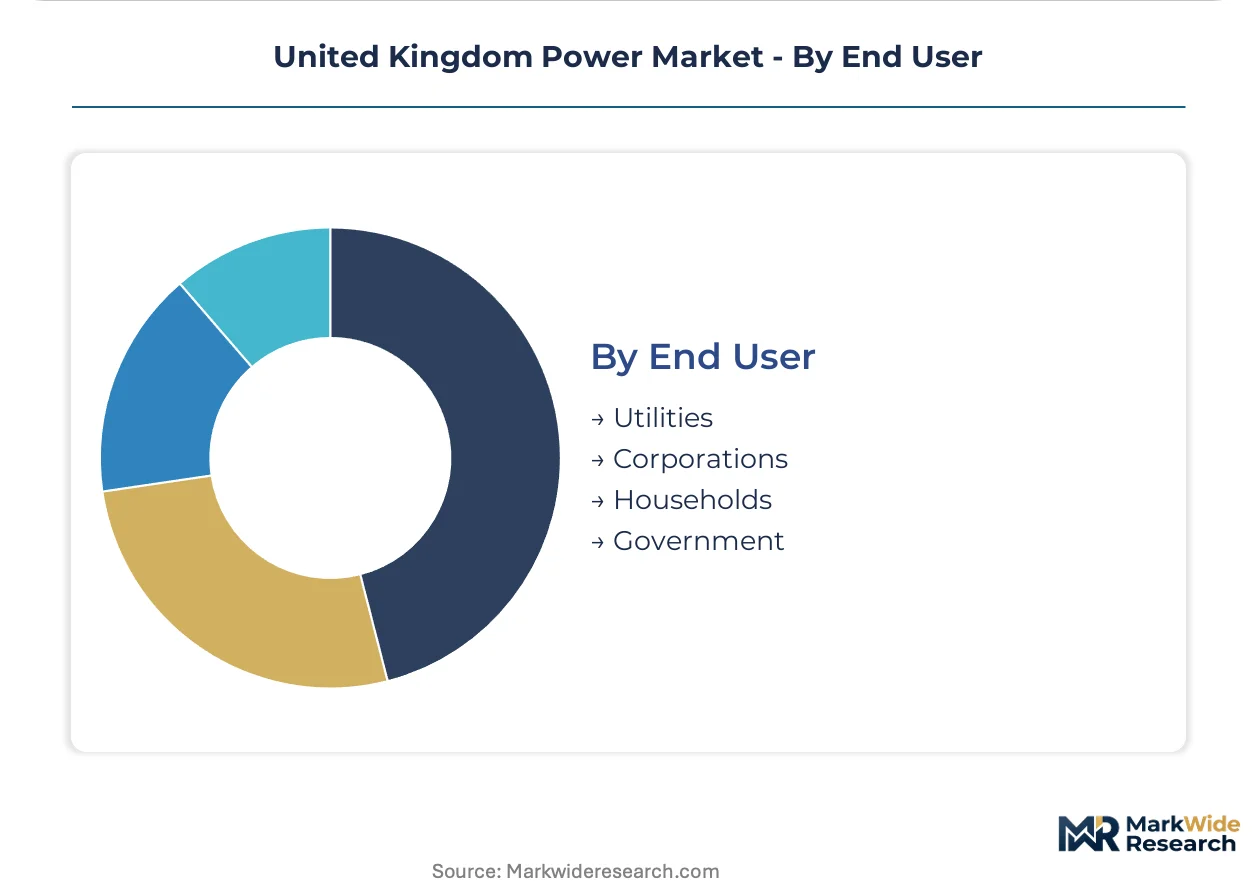
End User:
Contracting sophistication and creditworthiness segment offtake markets, with direct procurement displacing traditional utility supply arrangements.
- Utilities:Incumbent suppliers manage balancing responsibility and system charges, procuring wholesale power through power exchange markets and bilateral contracts with embedded generation.
- Corporations:Large energy users in data processing and manufacturing verticals execute corporate power purchase agreements directly with renewable projects, concentrating in England's southeast where grid constraints create strongest hedge demand.
- Households:Smart meter rollout enables time-of-use tariff participation, with Octopus Energy and OVO Energy competing on proprietary platform technology for demand-side response aggregation.
- Government:Public sector procurement frameworks prioritize net-zero alignment, with NHS estates and defence installations piloting microgrid configurations for resilience and carbon budget compliance.
Utilities retain the largest contracted volumes; Corporations are capturing share fastest as direct procurement unbundles traditional supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial offtakers in Scotland and northern England exhibit lowest price elasticity due to grid constraint premiums, while residential segments in London and the Southeast show highest sensitivity to tariff fluctuations.
Scotland
Floating offshore wind development in deeper North Sea waters drives capital deployment beyond fixed-bottom limits. The Scottish Government's net-zero statutory duties accelerate thermal fuel-switching at combined-cycle plants. Aberdeen and the Moray Firth anchor installation vessel servicing and subsea cable manufacturing clusters.
North England
Transmission network capacity constraints delay project energization with multi-year substation waits. Ofgem's RIIO-2 framework rewards distribution operators for demand-side integration in this constrained zone. Teesside and Humber host hydrogen-to-power pilot projects at repurposed thermal sites.
East Anglia
Dogger Bank lease rounds attract CfD-backed developer consortia seeking long-term revenue streams. The Crown Estate's competitive seabed auctions concentrate fixed-bottom installations in shallow waters. Norwich and Great Yarmouth form the primary operations and maintenance hub for offshore construction.
London and Southeast
Data centre operators in Slough contract record firm capacity volumes with 24/7 baseload requirements. BEIS carbon budget mechanisms shape capacity market auction design for thermal asset qualification. The M4 corridor concentrates hyperscale facility development with dedicated substation investments.
Wales
Pumped storage assets in Snowdonia provide system inertia services to the national grid. Environmental permitting constraints limit new run-of-river hydropower development. Milford Haven anchors LNG import terminal operations with power sector fuel supply linkages.
United Kingdom Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom Power Market. Vertically integrated utilities with generation portfolios compete against platform-native retailers with proprietary demand-side orchestration systems. Three archetypes dominate: legacy integrated suppliers with nuclear and renewable assets, agile retail platforms with digital customer acquisition engines, and network operators controlling transmission infrastructure access. Competitive moves concentrate on strategic partnerships for co-located storage and geographic expansion into microgrid services.
Within the legacy integrated tier, EDF Energy and SSE Business Energy exemplify generation-backed supply models. Octopus Energy occupies a distinct position as a platform-native retailer leveraging proprietary technology for demand aggregation. These three represent the primary competitive anchors shaping procurement patterns and customer segmentation across England, Scotland and Wales.
| Leading Market Players |
|---|
| EDF Energy |
| OVO Energy |
| Octopus Energy |
| SSE Business Energy |
| TotalEnergies |
| British Gas |
| ScottishPower |
| National Grid |
| E.ON Next |
| Others |
Value Network & Pricing Analysis
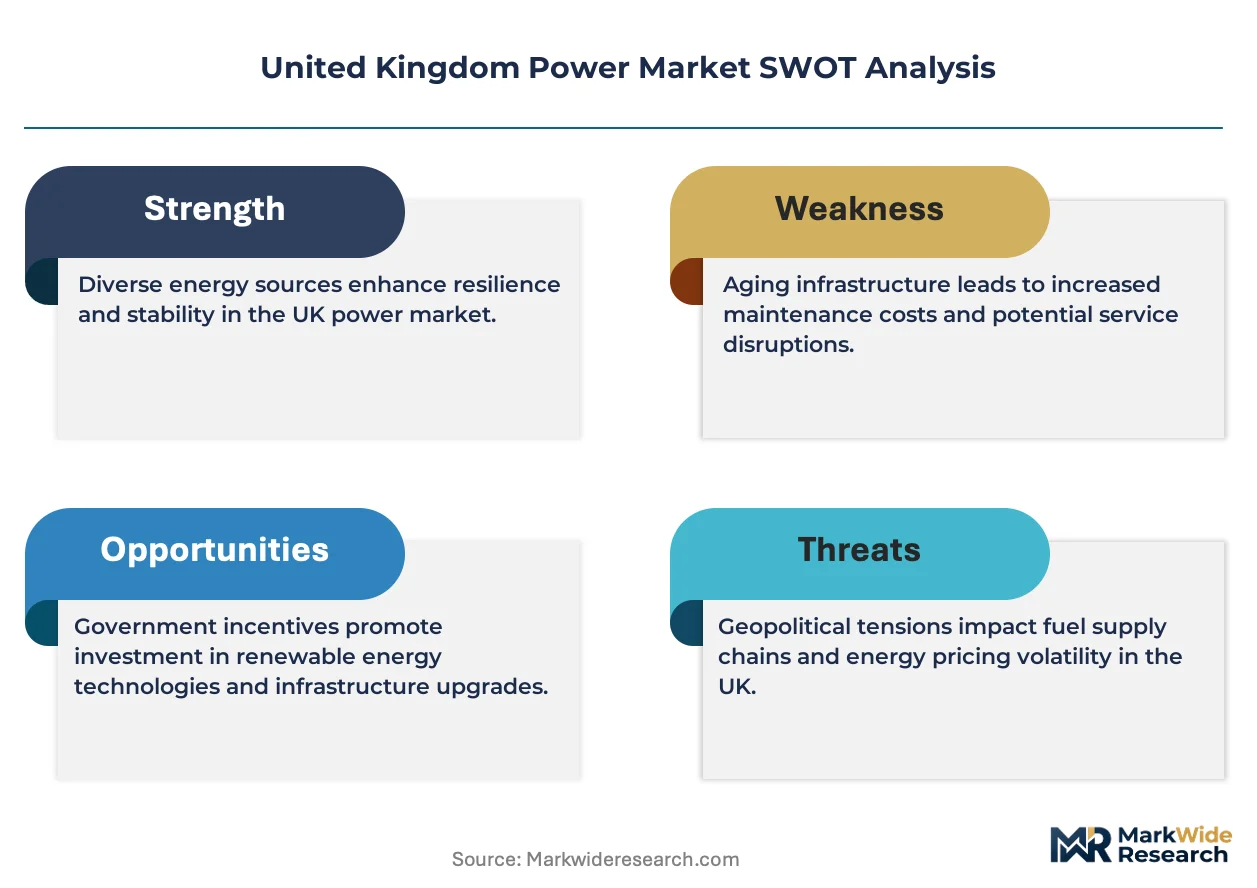
Ofgem's RIIO-2 price control framework gates both network operator qualification and tariff differentiation, compressing margin pools for non-compliant assets while rewarding flexibility-enabled pricing premiums. This regulatory architecture simultaneously constrains supply-side participation and segments end-user rates by grid service contribution.
Pricing Analysis
Ancillary service contracts and balancing mechanism revenues drive lifetime asset value, with four-hour battery duration specifications commanding enhanced frequency response premiums above shorter-duration alternatives. Price differentiation rests on grid connection timing and carbon intensity certification under BEIS rules, with pre-2035 commissioned assets facing qualification pressure. Cost compression in unabated gas generation is intensifying because carbon budget compliance costs accumulate without CfD backing. Data centre operators in England's southeast exhibit lowest price sensitivity due to 24/7 baseload requirements, while residential aggregators face highest sensitivity to tariff fluctuations.
Supply Chain Analysis
Denmark and Germany anchor offshore wind turbine nacelle assembly and blade manufacturing, with South Korea and Japan feeding high-voltage cable and power electronics components. The UK supply chain draws from Norwegian steel for monopile foundations, Chinese rare earth processing for permanent magnet generators, and Dutch installation vessel capacity. Single-source vulnerability concentrates in heavy-lift vessel availability, where North Sea-based fleets face serialized project scheduling conflicts. Distribution runs through EPC contractor consortiums that bundle turbine supply with installation and long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among data centre operators and corporate offtakers executing direct procurement, fragmenting traditional utility supply relationships. This shift rewards asset owners with contracted revenue streams and penalizes merchant-exposed capacity.
For Market Incumbents: Consolidate generation portfolios around nuclear baseload and offshore wind assets with CfD backing to anchor revenue certainty. Acquire grid-scale battery developers to capture ancillary service premiums before connection queues extend further. EDF Energy's co-location model at existing sites demonstrates defensive positioning against pure-play storage entrants.
For New Entrants and Emerging Players: Lead with industrial microgrid configurations targeting Scottish islanded communities and critical infrastructure campuses where grid extension costs justify behind-the-meter premiums. The residential demand-side response segment offers lowest competitive density, with proprietary platform technology enabling rapid customer acquisition against incumbent suppliers.
For Investors and Strategic Acquirers: The Electricity System Operator's 2035 decarbonization target reshapes the acquisition landscape toward flexibility assets and hydrogen-ready thermal sites. Long-term viability favors developers with secured grid connection agreements and contracted offtake structures. Monitor capacity market auction clearing prices as the inflection signal for thermal asset stranding risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Dogger Bank and East Anglia lease rounds anchor CfD-backed revenue streams for developer consortia. |
| Grid-Scale Battery Co-location | Four-hour lithium-ion systems at existing generation sites capture enhanced frequency response contracts. |
| Demand-Side Response Platform Integration | Octopus Energy's Kraken technology optimizes residential load for distribution network operator procurement. |
| Hydrogen-to-Power Pilot Development | Teesside and Humber sites leverage BEIS production contracts for electrolyzer-to-turbine project economics. |
| Corporate Power Purchase Agreement Expansion | Direct procurement from renewable projects unbundles commodity and balancing services for manufacturing offtakers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, grid operators, and fuel supply specialists. Secondary validation drew from Ofgem regulatory filings, BEIS carbon budget publications, Crown Estate lease round documentation, and interconnector flow databases. Bottom-up project pipeline analysis triangulated against top-down capacity market auction clearing data.
Across the analysis window, forecasts model generation capacity by fuel source, project scale tier, regulatory framework qualification, and regional grid constraint severity. CAGRs derive from installed capacity trajectory analysis against decommissioning timelines and connection queue progression. Input assumptions incorporate CfD strike price evolution, RIIO-2 innovation stimulus mechanism uptake, and data centre load growth projections.
Forecasts assume regulatory continuity in Ofgem price controls and BEIS carbon budget enforcement; material policy shifts would require re-modeling. Specific risks include interconnector flow disruption, offshore installation vessel availability constraints, and capacity market design changes affecting thermal asset economics. Recalibration cycles align with material shifts in auction clearing prices and lease round award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Marine Power Plant Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Gas Gensets Market
Power Generation
Stirling Engine Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Captive Power Plant Market
Power Generation
India Gas Generator Market
Power Generation
Iraq Power EPC Market
Power Generation
Algeria Power Market
Power Generation
Distributed Generation Market
Power Generation
Captive Power Generation Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Subsea Power Grid System Market
Power Generation
Global Power Generation Market
Power Generation
Southeast Asia Power Generation EPC Market