
 Utility Battery Market | 2026-2036
Utility Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Battery Market Analysis
China's gigafactory corridor is tilting the cost curve for lithium-ion phosphate systems. CATL leverages captive cathode material production to sustain margin compression. LG Energy Solution anchors North American assembly through joint ventures with domestic automakers-turned-battery suppliers. Samsung SDI competes on nickel-cobalt-aluminum chemistry for high-duration utility contracts.
A utility battery is an electrochemical or flow-cell system rated for grid-connected operation, typically exceeding 1 MWh per containerized unit, designed for frequency regulation, peak shaving, and renewable firming across transmission and distribution networks. Lithium-ion variants dominate installed capacity due to energy density above 150 Wh/kg and declining cell costs, while flow batteries capture long-duration applications above six hours where cycle life exceeds 15,000 charge events. The end-user dimension shows utility providers commanding procurement volume through regulated rate-base treatment, though commercial and industrial off-takers are expanding behind-the-meter deployments to manage demand charges. Installation type segmentation reveals combined renewable-plus-storage configurations leading new project announcements as developers optimize investment tax credit stacking.
The US Federal Energy Regulatory Commission Order 841 mandates storage participation in wholesale markets, while the EPA greenhouse gas performance standards for existing power plants create compliance-driven procurement timelines. China's MIIT battery passport requirements and the EU's forthcoming Carbon Border Adjustment Mechanism reshape supply chain disclosure obligations for cell manufacturers. Stakeholders must monitor interconnection reform progress and raw material offtake contracting as the primary variables determining deployment velocity and capital allocation efficiency.
Market Dynamics
Interconnection queue backlogs in high-renewable penetration zones are forcing storage developers to front-load procurement decisions before transmission capacity clears, compressing project timelines and amplifying working capital requirements.
Growth Catalysts
- Investment Tax Credit Stacking:The US Inflation Reduction Act permits additive credits for domestic content and energy communities, redirecting capital toward vertically integrated supply chains.
- Frequency Regulation Markets:Grid operators in Texas and California now compensate fast-ramping battery assets for ancillary services, creating dispatch revenue streams independent of energy arbitrage.
- Lithium Iron Phosphate Chemistry:Cell manufacturers have scaled LFP production for six-to-eight hour duration applications, undercutting nickel-cobalt-aluminum on cycle life and thermal stability.
Market Restraints
- Lithium Carbonate Volatility:Spodumene concentrate pricing swings between Australian and African mine supply create margin unpredictability for cell producers without captive offtake.
- Transformer and Switchgear Lead Times:Medium-voltage equipment from European and Asian foundries now stretches eighteen to twenty-four months, gating project energization regardless of battery delivery schedules.
- Interconnection Study Delays:Regional transmission organizations have accumulated multi-year queues for impact assessments, freezing capital deployment until system upgrade costs are allocated.
Strategic Opportunities
- Long-Duration Flow Batteries:Vanadium and iron-chromium systems above ten hours duration address seasonal renewable shifting where lithium-ion degradation economics fail.
- Behind-the-Meter C&I Aggregation:Virtual power plant software stacks distributed commercial storage into wholesale market participation, bypassing utility procurement cycles.
- EU Battery Passport Mandates:The forthcoming Carbon Border Adjustment Mechanism creates first-mover advantage for manufacturers with verified supply chain carbon accounting.
Industry Challenges
- Power Electronics Integration:Inverter and battery management system interoperability remains fragmented across vendor protocols, requiring custom engineering for each project configuration.
- Fire Safety Certification:UL 9540A test data gaps for large-format LFP rack configurations delay permitting in jurisdictions with stringent fire code enforcement.
- Recycling Infrastructure:End-of-life cell processing capacity has not scaled with deployment volumes, creating liability exposure for asset owners under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Battery Market |
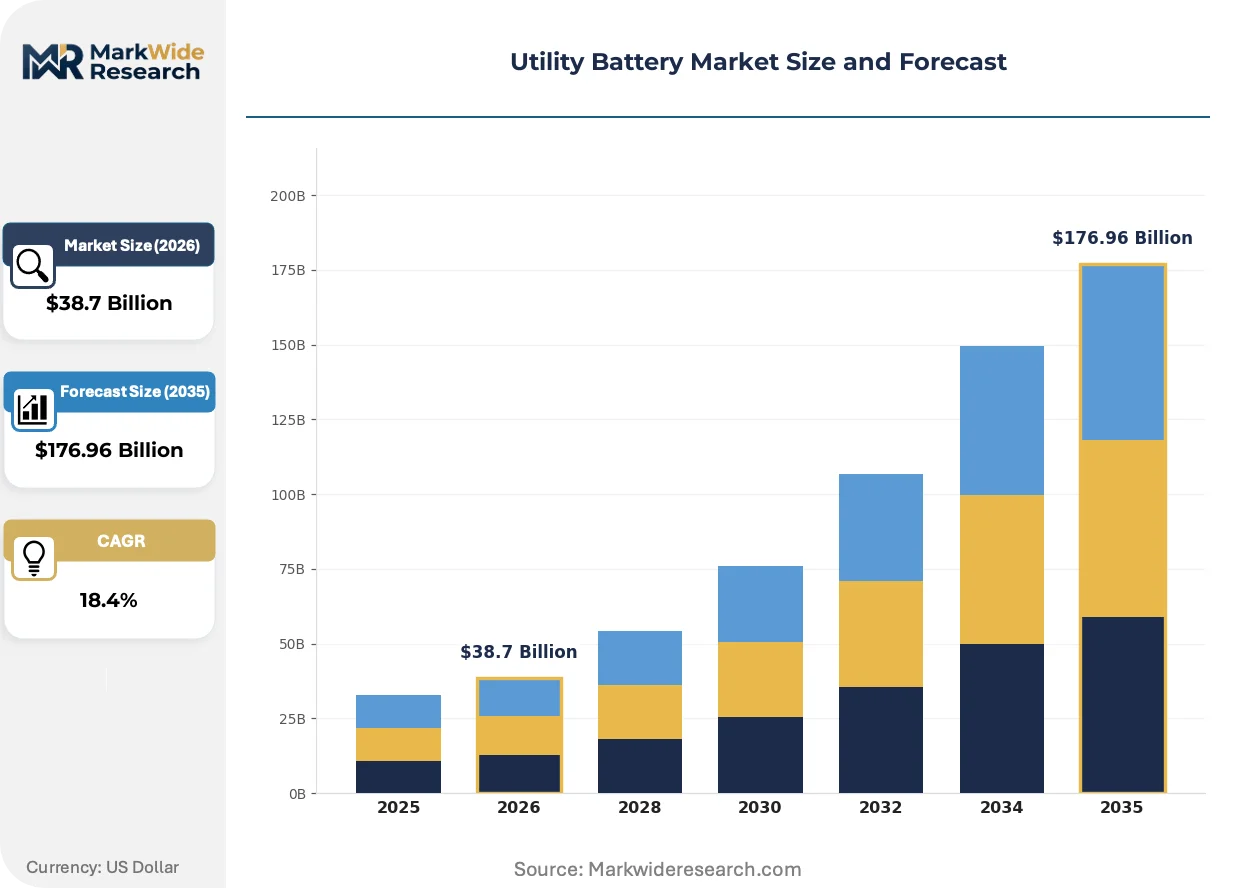
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lead-Acid, Flow, Nickel-Cadmium End User: Utility Providers, Commercial, Industrial, Residential Installation Type: Onshore, Offshore, Combined Renewable, Standalone Capacity: 10-50 kWh, 51-100 kWh, 101-500 kWh, Others |
| Companies Covered | SK On, EVE Energy, CATL, Gotion High-Tech, Samsung SDI, BYD, Panasonic, Sungrow, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Battery Market Emerging Trajectories
Digital twins and predictive analytics are compressing operational risk premiums for utility-scale storage, enabling merchant financing structures that were previously restricted to contracted revenue streams.
Containerized battery systems equipped with edge computing modules are digitizing fleet management across geographically dispersed assets. Independent power producers now deploy these platforms to optimize dispatch decisions against real-time price signals. The resulting data granularity is digitizing insurance underwriting and debt covenants for project finance.
The EU's forthcoming Carbon Border Adjustment Mechanism will impose embodied carbon tariffs on imported cells and modules, reshaping supplier qualification criteria. Developers with European offtake agreements are now requiring supply chain disclosure down to cathode precursor refiners. German and Dutch grid operators have begun incorporating carbon intensity metrics into storage procurement scoring.
Merchant offtake structures are displacing traditional power purchase agreements for new capacity additions in deregulated markets. Investors in Texas and the UK now underwrite projects based on volatility capture models rather than fixed-price contracts. This shift concentrates development activity in nodal pricing zones with demonstrated price spread duration.
Utility Battery Market Segmentation
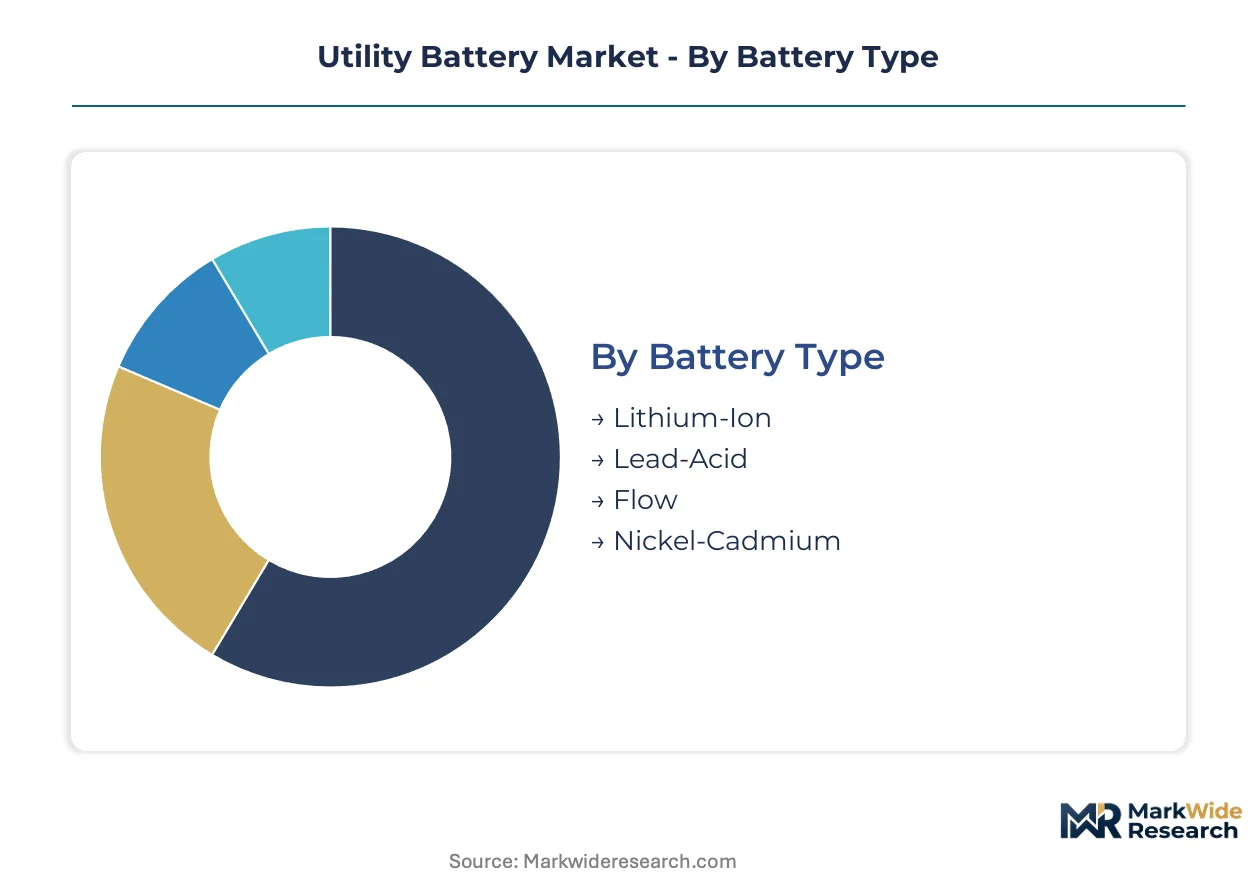
Utility battery procurement splits across multiple technical and commercial dimensions. Developers must align cell chemistry, installation topology, and customer contracting structure to capture available revenue streams.
Battery Type:
The use-case spectrum spans frequency regulation through seasonal shifting, with each chemistry optimizing for specific duration and cycle requirements.
- Lithium-Ion:Lithium iron phosphate and nickel-cobalt-aluminum cathodes deliver 150-300 Wh/kg energy density for four-to-eight hour applications. Texas and California grid operators procure these systems for ancillary services and renewable firming where fast ramp rates command premium pricing.
- Flow:Vanadium and iron-chromium redox systems separate power and energy scaling, enabling ten-plus hour durations with 15,000-plus cycle life. Germany's transmission system operators are piloting these for winter renewable shifting where lithium-ion degradation economics prove prohibitive.
- Lead-Acid:Mature flooded and valve-regulated designs serve backup power in regulated rate-base environments with lower cycling requirements.
- Nickel-Cadmium:Sintered plate construction withstands extreme temperatures in remote substation installations where maintenance access is limited.
The dominant share belongs to Lithium-Ion, while Flow is closing the gap fastest.
End User:
Customer type determines procurement channel, contracting structure, and regulatory treatment across deployment models.
- Utility Providers:Vertically integrated and independent power producers deploy rate-base or merchant assets with FERC Order 841 market access. PJM and ERCOT interconnection queues show these offtakers commanding multi-hundred megawatt procurement volumes.
- Commercial:Behind-the-meter installations at data centers, retail chains, and logistics facilities manage demand charges through peak shaving. California's SGIP incentive program has accelerated these deployments for commercial load centers.
- Industrial:Heavy manufacturing and mining operations install containerized systems for power quality and backup during grid disturbances.
- Residential:Single-family and multi-family aggregated virtual power plant participation remains nascent outside Australia and select US utility territories.
Utility Providers hold the installed base majority, though Commercial is expanding most quickly behind-the-meter.
Installation Type:
Project configuration shapes interconnection complexity, permitting timeline, and revenue stack optimization.
- Combined Renewable:Co-located solar-plus-storage or wind-plus-storage configurations dominate new announcements. Developers in Texas and California optimize investment tax credit stacking while sharing interconnection infrastructure.
- Standalone:Merchant battery assets participate solely in wholesale energy and ancillary service markets. UK and Texas nodal pricing zones support these structures where volatility capture models replace fixed-price contracts.
- Onshore:Land-based installations at substations or industrial sites represent the conventional deployment topology.
- Offshore:Floating and platform-mounted systems serve island grids and offshore wind integration where land constraints apply.
Combined Renewable captures the deployment momentum, with Standalone climbing fastest in deregulated markets.
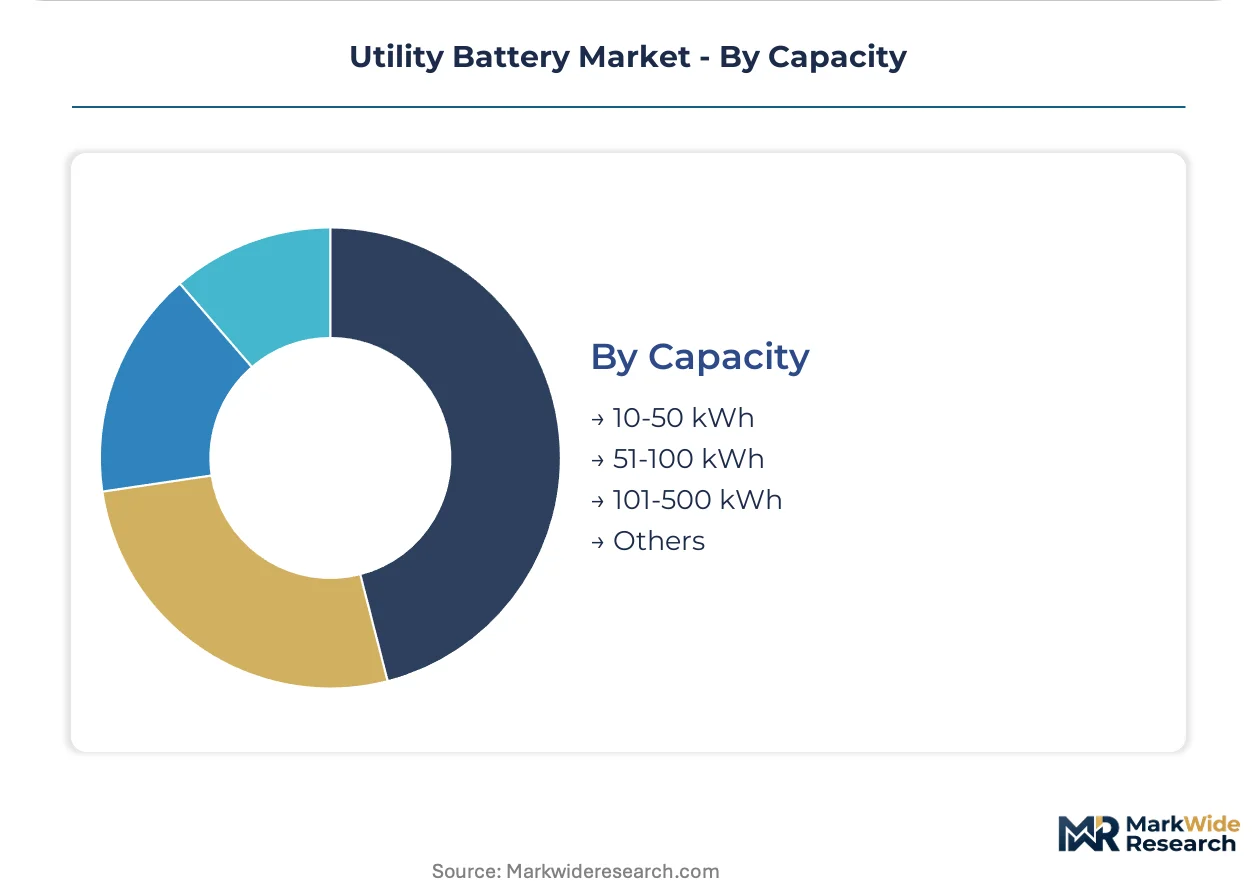
Capacity:
System scale determines containerization approach, power electronics architecture, and grid connection voltage level.
- 101-500 kWh:Containerized units with integrated inverters serve commercial and industrial peak shaving. German and Dutch distribution system operators are standardizing these for grid services procurement.
- 51-100 kWh:Skid-mounted or cabinet systems address smaller commercial loads and residential aggregation pilots.
- 10-50 kWh:Rack-mounted residential and small commercial units participate in virtual power plant programs where software aggregation enables wholesale market access.
- Others:Sub-10 kWh modular units and multi-megawatt direct grid connections occupy the scale extremes.
The 101-500 kWh band leads utility-scale procurement, while 10-50 kWh systems are gaining share fastest through distributed aggregation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 841 anchors procurement momentum in the United States, where interconnection reform and renewable curtailment create urgent storage needs. The Inflation Reduction Act's domestic content bonuses redirect supply chain localization across multiple geographies.
United States
Texas and California dominate deployment volumes through ERCOT and CAISO market structures. The IRA's investment tax credit stacking accelerates combined renewable-plus-storage configurations. Houston and Austin clusters host independent power producers front-loading procurement ahead of transmission capacity clearance.
China
MIIT battery passport requirements reshape supply chain disclosure obligations for cell manufacturers. Domestic gigafactory corridors tilt cost curves for lithium iron phosphate systems. Shenzhen and Ningbo industrial zones concentrate cathode material production and containerized system assembly.
Germany
Transmission system operators pilot vanadium flow systems for winter renewable shifting. The EU Carbon Border Adjustment Mechanism imposes embodied carbon tariffs on imported cells. North Rhine-Westphalia and Bavaria host grid operators incorporating carbon intensity metrics into procurement scoring.
South Korea
Industrial policy supports nickel-cobalt-aluminum chemistry for high-duration utility contracts. Kepco rate-base treatment enables regulated utility procurement at scale. Seoul Capital Area and Busan-Ulsan corridors anchor joint ventures with North American automakers-turned-battery suppliers.
Australia
AEMO market reforms compensate fast-ramping assets for frequency regulation services. Virtual power plant aggregation of distributed commercial storage bypasses traditional utility procurement cycles. New South Wales and Victoria transmission networks accumulate multi-year interconnection queues that freeze capital deployment.
Utility Battery Market Vendor Landscape
Vertically integrated conglomerates and specialized cell manufacturers split the market through divergent approaches to chemistry and geography. Tier-one players command multi-hundred megawatt procurement relationships with independent power producers. Three archetypes dominate: captive cathode producers sustaining margin compression, joint-venture assemblers anchoring regional supply, and chemistry specialists capturing long-duration niches. Capacity expansion and strategic partnerships represent the dominant competitive moves as developers secure raw material offtake ahead of project commissioning.
Within the captive production tier, CATL and BYD exemplify backward integration into cathode material refining. LG Energy Solution occupies a position representing joint-venture assembly structures with domestic partners in target markets. Samsung SDI anchors the chemistry-specialist archetype through nickel-cobalt-aluminum systems for extended-duration contracts.
| Leading Market Players |
|---|
| SK On |
| EVE Energy |
| CATL |
| Gotion High-Tech |
| Samsung SDI |
| BYD |
| Panasonic |
| Sungrow |
| LG Energy Solution |
| Others |
Supply Flow & Price Mechanics
EU Carbon Border Adjustment Mechanism tariff exposure determines both pricing tier spreads and supply chain shape by forcing developers to source cathode materials from verified low-carbon refiners or absorb embodied carbon penalties that compress margins on standard-tier offerings.
Pricing Analysis
Chinese-manufactured lithium iron phosphate cells trade at substantial discounts to South Korean nickel-cobalt-aluminum equivalents in North American markets. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified domestic-assembled systems from imported containerized units and refurbished second-life assets. Cost compression in the standard tier intensifies because CATL and BYD have scaled captive cathode production. Utility providers show highest price sensitivity due to rate-base scrutiny, while merchant developers absorb premium pricing for fast-track delivery.
Supply Chain Analysis
Spodumene concentrate from Australian and African hard-rock mines feeds Chinese refineries producing battery-grade lithium carbonate. Cathode precursor processing concentrates in China, South Korea, and Japan, with European developers now requiring supply chain disclosure down to refiner level. Single-source vulnerability around transformer and switchgear procurement from European and Asian foundries creates project energization bottlenecks. Distribution runs through joint-venture assembly partnerships that anchor regional supply in target markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FERC Order 841 and domestic content bonuses creates sticky procurement relationships that resist new entrant displacement.
For Market Incumbents: Insulate rate-base positions by securing captive cathode offtake from Australian spodumene producers before interconnection queues clear. Accelerate UL 9540A fire safety certification investment to preempt jurisdiction-level permitting delays that threaten project timelines.
For New Entrants and Emerging Players: Pursue long-duration flow battery niches above ten hours where lithium-ion degradation economics fail, particularly in German transmission system operator pilot programs. Target behind-the-meter commercial aggregation through virtual power plant software stacks that bypass traditional utility procurement cycles entirely.
For Investors and Strategic Acquirers: FERC interconnection reform reshapes the acquisition landscape by determining which project pipelines achieve energization before transmission capacity constraints harden. Five-to-ten year viability hinges on raw material offtake contracting discipline rather than technology differentiation alone. Monitor transformer and switchgear delivery schedules as the primary inflection signal for project commissioning risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive lithium carbonate refining insulates margin compression from Australian spodumene volatility. |
| Domestic Content Certification Program | IRA bonus qualification redirects capital toward vertically integrated North American assembly corridors. |
| Long-Duration Flow Battery Scale-Up | Vanadium and iron-chromium systems address seasonal renewable shifting where lithium-ion fails. |
| Virtual Power Plant Platform Launch | Software aggregation of distributed commercial storage bypasses utility procurement cycles in deregulated markets. |
| Fire Safety Certification Investment | UL 9540A test data accelerates permitting in California and Texas jurisdictions with stringent enforcement. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against EIA deployment data, FERC interconnection filings, IEA storage reports, and project development databases. Bottom-up capacity and revenue modeling triangulated against top-down market sizing across chemistry, installation type, and end-user segments.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include battery chemistry, installation topology, end-user contracting structure, capacity tier, and regional regulatory framework. CAGRs were derived from deployment trajectory analysis against interconnection queue progression and raw material supply expansion. Industry-specific forecast inputs incorporated IRA domestic content bonus qualification timelines and EU Carbon Border Adjustment Mechanism implementation phasing.
Sensitivities concentrate around interconnection study delay resolution, lithium carbonate price volatility, and transformer procurement lead time normalization. Cross-checking against EIA Monthly Energy Review storage deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
North America Battery Market
Batteries
Secondary Battery Market
Batteries
Battery Simulator Market
Batteries
India Lead-Acid Battery Market
Batteries
High Voltage Battery Market
Batteries
HIT Battery Market
Batteries
Home Inverter Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Nimh Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Inverter Battery Market
Batteries
Europe Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Industrial Backup Battery Market