
 Global Electricity Ancillary Services Market | 2026-2036
Global Electricity Ancillary Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electricity Ancillary Services Market Analysis
China's massive grid modernization is reshaping competitive dynamics across electricity ancillary services. NextEra Energy leverages its renewable-plus-storage portfolio to dominate frequency regulation procurement in North American ISO markets. Siemens Energy anchors European voltage support contracts through its synchronous condenser installations. Tesla competes aggressively on grid-scale battery response speed, positioning its Megapack systems as substitutes for traditional spinning reserves.
Electricity ancillary services encompass the technical capabilities that maintain grid stability through real-time balancing of frequency, voltage, and reactive power, typically requiring response times from milliseconds to thirty minutes depending on service classification. These functions prevent cascading failures when supply-demand mismatches emerge across interconnected transmission networks. Frequency regulation commands premium pricing in restructured markets due to sub-second response requirements, while voltage support generates stable returns from utility-scale synchronous equipment deployments. Demand response is accelerating fastest among technology segments as virtual power plants aggregate distributed resources into dispatchable capacity.
FERC, EMA, and China's National Energy Administration each enforce distinct market designs that determine ancillary service procurement mechanisms and compensation structures. FERC Order 841 and Order 2222 explicitly require ISOs to remove barriers for energy storage and aggregated distributed resources, directly expanding addressable market scope. Stakeholders must monitor how carbon border adjustments and capacity market reforms alter the relative economics of battery-based versus conventional generator-provided reserves.
Market Dynamics
Grid-forming inverter technology is compressing response times for frequency regulation from mechanical governor speeds to millisecond-scale power electronics, fundamentally altering procurement economics for spinning reserves and battery storage across restructured electricity markets.
Growth Catalysts
- FERC Order 2222:Mandates ISOs to remove barriers for aggregated distributed energy resources, expanding addressable market scope for virtual power plants and behind-the-meter battery participation in wholesale ancillary service markets.
- Germany's grid balancing market reforms:Creates transparent procurement platforms for primary frequency control, attracting battery storage operators and demand response aggregators into previously closed turbine-dominated auctions.
- Synchronous condenser retirements:Coal plant closures across the United Kingdom and Australia eliminate traditional sources of reactive power support, forcing grid operators to procure voltage regulation from STATCOM and battery-based alternatives.
Market Restraints
- Lithium supply concentration:Battery storage deployment for fast frequency response depends on processing capacity concentrated in China, exposing project timelines to export restriction risks and price volatility in cathode material markets.
- Interconnection queue backlogs:Grid operators in Texas and California face 3-5 year delays for new storage assets seeking to provide ancillary services, compressing developer returns and limiting competitive entry.
- Legacy turbine maintenance:Natural gas and hydro generators providing spinning reserves face rising operations costs from aging equipment, narrowing the cost gap with battery alternatives more slowly than capital cost curves suggest.
Strategic Opportunities
- Brazil's underpenetrated northeast region:Wind penetration exceeds 70% in some transmission zones without proportional frequency regulation procurement, creating first-mover advantage for battery developers targeting ANEEL-regulated balancing markets.
- Hybrid renewable-plus-storage PPAs:Solar and wind developers in India are bundling ancillary service capabilities into energy contracts, capturing premium capacity payments from state load dispatch centers beyond energy-only revenues.
- Vehicle-to-grid integration:Aggregators in Denmark and the Netherlands are piloting EV fleets as distributed frequency regulation resources, leveraging existing battery assets without dedicated stationary storage capital deployment.
Industry Challenges
- Power systems engineering talent scarcity:Grid operators and developers face acute shortages of engineers trained in inverter-based resource modeling, slowing project development and control system integration timelines.
- Dual-use asset optimization:Battery owners must simultaneously manage energy arbitrage, capacity market, and ancillary service revenues with conflicting dispatch signals, requiring sophisticated software stacks most mid-scale operators lack.
- Harmonic resonance mitigation:Massive inverter deployment introduces oscillation risks in weak grid areas of Australia and Texas, demanding additional filter equipment and grid code compliance testing that delays commercial operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electricity Ancillary Services Market |
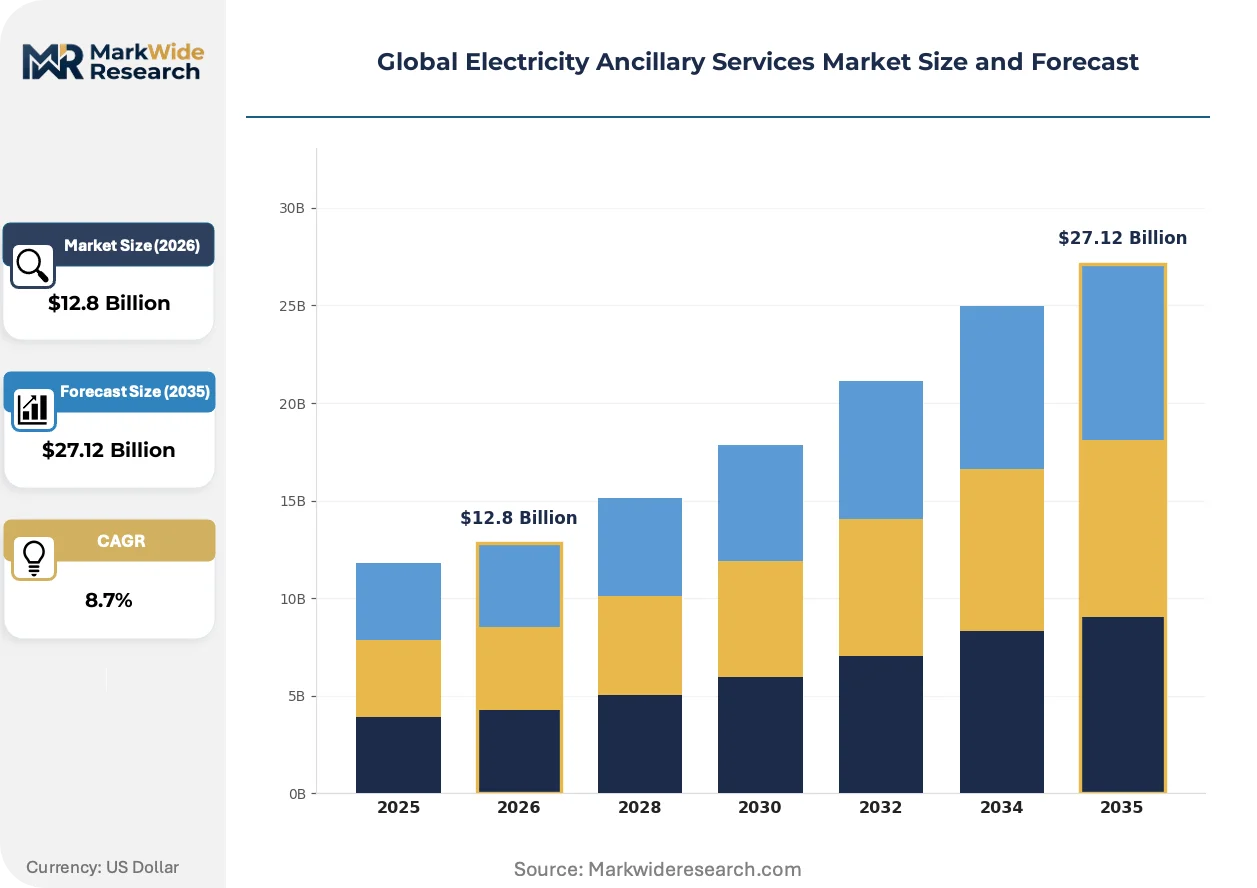
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
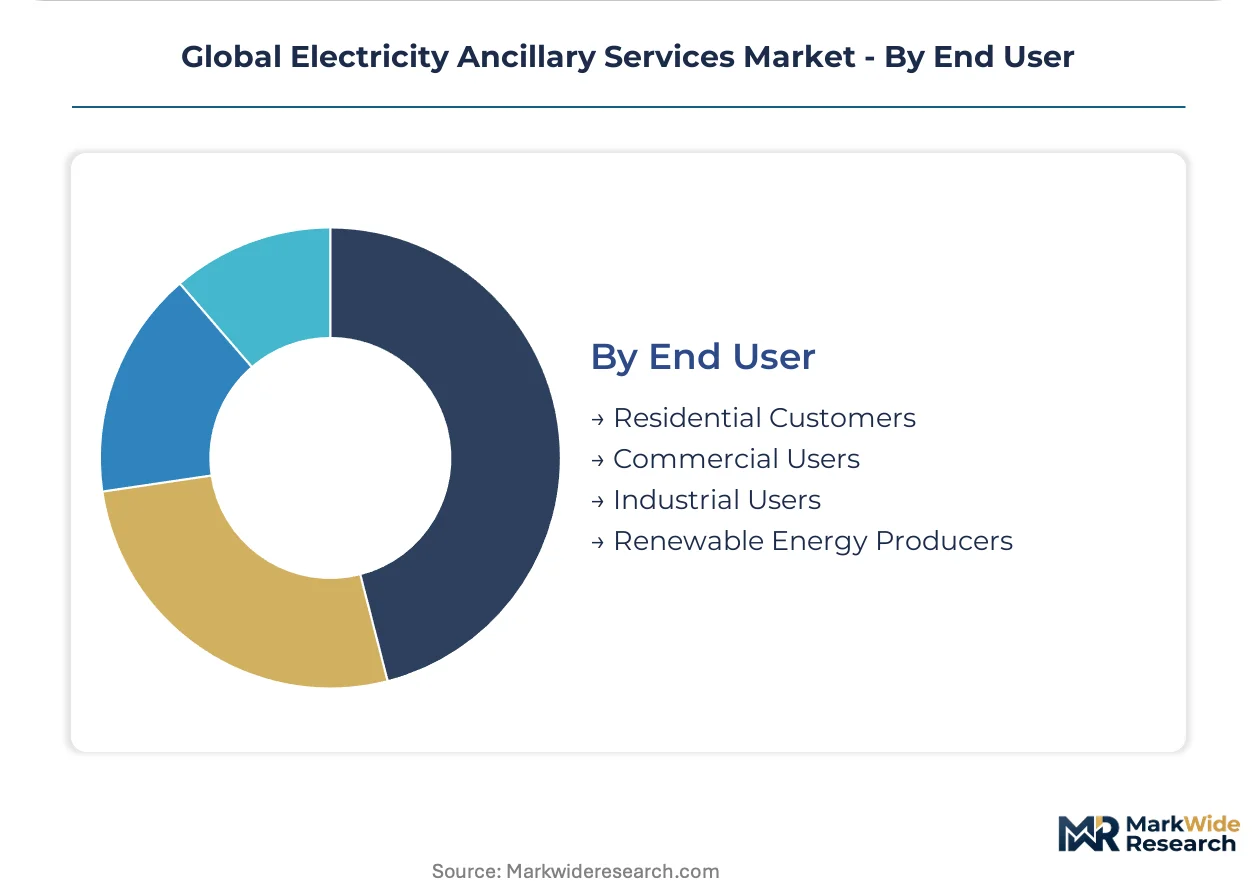
| Segmentation | Service Type: Frequency Regulation, Voltage Support, Spinning Reserves, Non-Spinning Reserves Utility Type: Public Utilities, Private Utilities, Cooperative Utilities, Independent System Operators Technology: Grid-Scale Batteries, Demand Response, Flywheel Energy Storage, Synchronous Generators End User: Residential Customers, Commercial Users, Industrial Users, Renewable Energy Producers |
| Companies Covered | PJM Interconnection, NextEra Energy, General Electric, Tesla, Schneider Electric, Siemens Energy, CAISO, Enel, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electricity Ancillary Services Market Emerging Trajectories
Digital twin technology is compressing commissioning timelines for ancillary service assets while artificial intelligence reshapes dispatch optimization. These forces are converging to displace manual bidding and static reserve scheduling across competitive electricity markets.
Synthetic inertia from grid-forming inverters is migrating from pilot demonstrations to commercial procurement requirements. Transmission operators in the United Kingdom and Ireland now mandate this capability for new renewable connections, forcing turbine manufacturers to develop firmware-based emulation of rotational mass. Grid codes across 12 countries have incorporated synthetic inertia specifications since 2022, establishing a de facto global standard that battery and inverter suppliers must meet for market access.
China's National Energy Administration has implemented mandatory ancillary service cost allocation rules requiring all load-serving entities to pay for frequency regulation and reserve procurement. This policy eliminates historical cross-subsidies from industrial consumers and creates transparent price signals for storage investment in provincial markets. Developers in Guangdong and Jiangsu provinces are responding with gigawatt-scale battery projects targeting the newly monetized primary frequency response segment.
Virtual power plant business models are consolidating distributed energy resources into single bidding entities that compete directly with centralized generators. Aggregators in California and Texas now control hundreds of megawatts of responsive capacity from residential batteries, commercial HVAC systems, and industrial loads. This organizational innovation compresses minimum viable scale for ancillary service participation from 50 MW utility assets to sub-1 MW resource clusters, fragmenting supplier concentration in frequency regulation markets.
Global Electricity Ancillary Services Market Segmentation
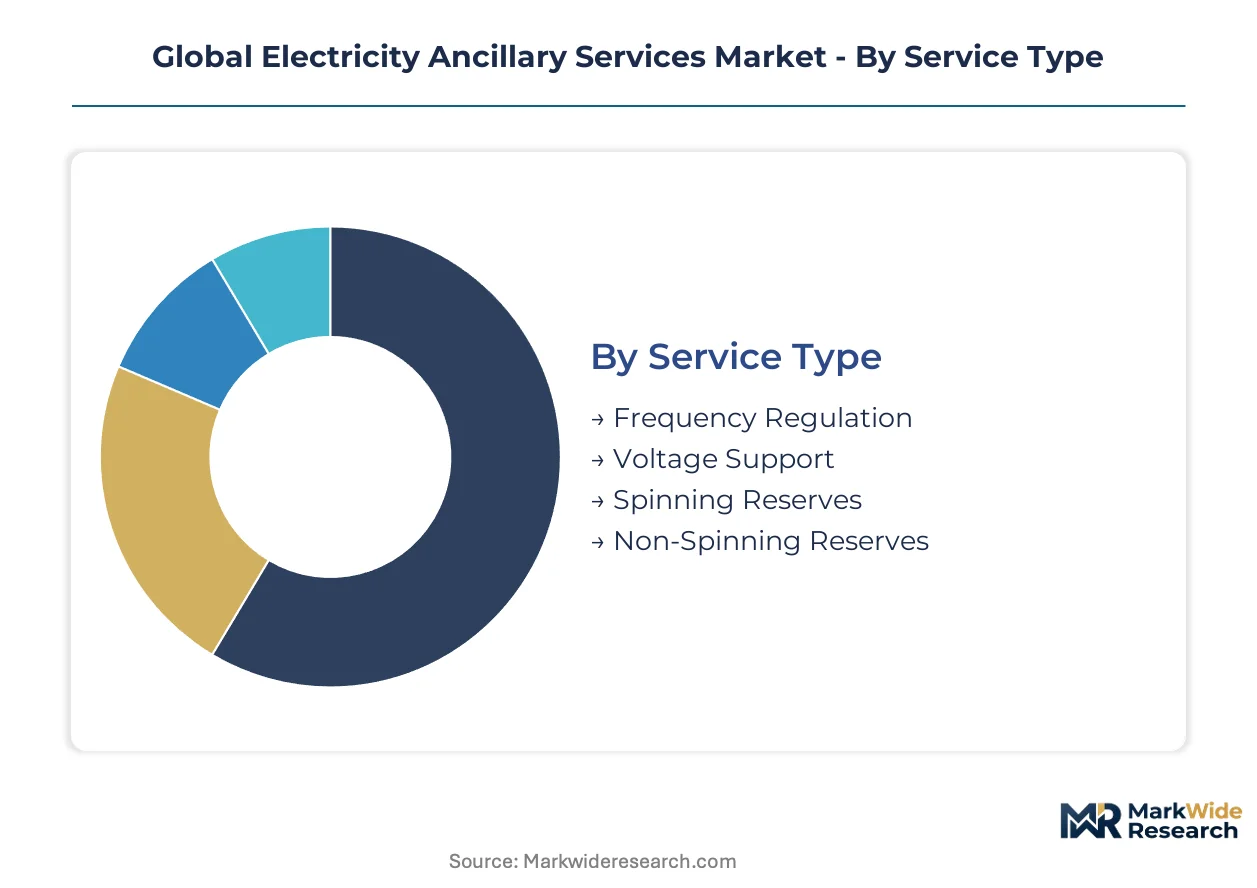
Ancillary service procurement cycles vary dramatically across technical categories, with millisecond-response products commanding premium clearing prices while slower reserves trade at energy-parity rates. Understanding these temporal hierarchies reveals where battery storage displaces thermal assets fastest and where legacy infrastructure retains structural advantages.
Service Type:
Frequency regulation contracts turn over every 4-15 minutes in real-time markets, while spinning reserve obligations stretch across hours and seasonal capacity payments span years, creating layered investment horizons for asset owners.
- Frequency Regulation:Sub-second response services maintain grid frequency within tight tolerance bands through automatic generation control signals. Procurement concentrates in Texas ERCOT and California CAISO markets where FERC Order 841 mandates storage participation, with battery operators capturing premium payments for fast-ramping capability that displaces traditional governor response from gas turbines.
- Voltage Support:Reactive power services stabilize transmission voltage profiles through VAR injection or absorption. Demand clusters in the United Kingdom and Australia where synchronous condenser retirements at coal plant sites force National Grid ESO and AEMO to procure STATCOM and inverter-based alternatives for grid strength maintenance in weak network areas.
- Spinning Reserves:Synchronized generation capacity responds to contingency events within 10 minutes. Procurement persists in Germany and Brazil where thermal fleets remain contracted for system inertia despite battery cost declines.
- Non-Spinning Reserves:Offline capacity achieves full output within 30 minutes of dispatch instruction. Deployment focuses on Texas and Midwest ISO regions where quick-start gas turbines and emerging battery resources compete for supplemental reserve designations.
Spinning reserves anchor the volume base while frequency regulation gains share at the steepest rate.
Utility Type:
Procurement sophistication stratifies sharply across ownership structures, with ISO-operated markets enabling granular price discovery while vertically integrated utilities internalize ancillary costs through regulated rate bases.
- Public Utilities:Municipal and state-owned entities procure ancillary services through integrated resource planning processes with multi-year contracting horizons. Procurement concentrates in California SMUD and Texas LCRA territories where renewable mandates accelerate storage procurement for local reliability.
- Private Utilities:Investor-owned entities participate in organized wholesale markets or self-provide reserves through owned generation. Activity centers on NextEra Energy and Duke Energy territories across Florida and the Carolinas where hybrid solar-storage plants capture stacked revenue streams from energy and ancillary products.
- Cooperative Utilities:Rural electric cooperatives aggregate demand across dispersed membership territories with limited transmission access. Procurement focuses on Great Plains and Mountain West regions where Tri-State G&T and Associated Electric Cooperative deploy distributed battery systems for transmission deferral and frequency response.
- Independent System Operators:Regional transmission organizations operate transparent procurement platforms with locational marginal pricing for reserves. Dominant platforms include PJM Interconnection, MISO, and CAISO where FERC-jurisdictional market designs determine technology-neutral clearing mechanisms.
Independent system operators anchor the volume base while cooperative utilities gain share at the steepest rate.
Technology:
Capital intensity and operational flexibility create divergent deployment economics across technology classes, with lithium-ion systems achieving 4-hour duration at parity with gas peakers while mechanical storage retains niche advantages in cycling tolerance.
- Grid-Scale Batteries:Lithium-ion systems provide multi-service capability through power conversion systems enabling frequency regulation, voltage support, and energy arbitrage from shared hardware. Deployment concentrates in California and Texas where Tesla Megapack and Fluence Gridstack installations dominate interconnection queues for ERCOT and CAISO ancillary service markets.
- Demand Response:Aggregated load curtailment and modulation displace generation-based reserves through virtual power plant architectures. Growth centers on California and New York where AutoGrid and OhmConnect aggregate residential and commercial flexibility into wholesale market participation.
- Flywheel Energy Storage:Kinetic energy systems deliver high-power, short-duration frequency regulation with unlimited cycle life. Installations persist in Pennsylvania and New York where Beacon Power operates regulation-dedicated facilities for PJM markets.
- Synchronous Generators:Rotating machines provide inherent inertia and fault current contribution unavailable from inverter-based resources. Retention focuses on Germany and the United Kingdom where grid codes mandate minimum system inertia and short-circuit ratio requirements.
Synchronous generators anchor the volume base while grid-scale batteries gain share at the steepest rate.
End User:
Behind-the-meter participation expands fastest among customer classes with controllable loads and storage assets, while utility-scale renewable developers internalize ancillary obligations through hybrid project structures.
- Residential Customers:Distributed battery and smart thermostat aggregation enables wholesale market participation through virtual power plant programs. Enrollment concentrates in California and Vermont where Sunrun and Tesla Virtual Power Plant programs aggregate home storage systems into frequency regulation bids for CAISO and Green Mountain Power.
- Commercial Users:C&I facilities with HVAC, refrigeration, and on-site generation provide demand response and emergency capacity. Participation clusters in Texas and Illinois where Enel X and CPower manage commercial load curtailment for ERCOT and PJM ancillary service programs.
- Industrial Users:Large manufacturing loads with process interruption tolerance offer bulk responsive capacity for contingency reserves. Contracts focus on aluminum smelters and chemical plants in the Pacific Northwest and Gulf Coast where aluminum production and petrochemical facilities provide interruptible load for BPA and ERCOT.
- Renewable Energy Producers:Wind and solar developers contract for ancillary services to meet interconnection requirements and capture capacity payments. Procurement centers on India and Brazil where ReNew Power and Omega Energia bundle frequency regulation capabilities into hybrid renewable PPAs for state utilities and ANEEL-regulated markets.
Industrial users anchor the volume base while renewable energy producers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 841 and Order 2222 anchor the United States as the regulatory benchmark for ancillary service market design, with procurement platforms in Texas and California establishing clearing price mechanisms that influence reform trajectories across Germany, Australia, and Brazil.
United States
ERCOT and CAISO operate the most liquid frequency regulation markets globally, with battery storage capturing over half of fast-ramping procurement. FERC Order 2222 mandates ISOs to remove barriers for aggregated distributed resources. Developers in Texas face 3-5 year interconnection queues despite surging demand for spinning reserve alternatives.
Germany
Grid balancing market reforms created transparent procurement platforms for primary frequency control, attracting battery operators into previously turbine-dominated auctions. The country's national energy regulator enforces strict grid codes mandating synthetic inertia for new renewable connections. Industrial clusters in Bavaria and North Rhine-Westphalia deploy synchronous condensers to maintain voltage stability as coal plants retire.
China
The National Energy Administration implemented mandatory ancillary service cost allocation rules requiring all load-serving entities to pay for frequency regulation and reserve procurement. Provincial markets in Guangdong and Jiangsu provinces attract gigawatt-scale battery projects targeting newly monetized primary frequency response segments. State Grid Corporation procures voltage support services through centralized auctions.
Australia
AEMO faces acute challenges maintaining grid strength in weak network areas of South Australia and Queensland where wind and solar penetration exceeds 50%. Synchronous condenser retirements at coal plant sites force procurement of STATCOM and battery-based alternatives. The national electricity market redesign incorporates fast frequency response products with sub-second settlement intervals.
Brazil
Wind penetration exceeds 70% in northeast transmission zones without proportional frequency regulation procurement, creating first-mover advantage for battery developers. ANEEL regulates balancing markets with capacity payment mechanisms that favor hybrid renewable-plus-storage configurations. Omega Energia and other developers bundle ancillary capabilities into state utility contracts.
Global Electricity Ancillary Services Market Vendor Landscape
Capability concentration sits with technology-integrated energy majors; scale advantage sits with specialized grid operators and independent system operators. The vendor base stratifies into three tiers: ISOs and transmission operators controlling market platforms, integrated utilities with renewable-plus-storage portfolios, and pure-play technology suppliers providing hardware and software stacks. Dominant competitive moves include portfolio diversification into hybrid asset development and strategic partnerships between battery manufacturers and virtual power plant aggregators.
Within the integrated utility tier, NextEra Energy and Enel exemplify scale-driven positioning through bundled renewable and storage development. Among technology suppliers, Tesla occupies a position representing pure-play battery response speed, while Siemens Energy anchors European voltage support contracting through synchronous condenser and STATCOM installations. PJM Interconnection and CAISO sit within the platform operator archetype, controlling procurement mechanisms that determine technology-neutral clearing prices across multiple service categories.
| Leading Market Players |
|---|
| PJM Interconnection |
| NextEra Energy |
| General Electric |
| Tesla |
| Schneider Electric |
| Siemens Energy |
| CAISO |
| Enel |
| ABB Ltd. |
| Others |
Supply Flow & Price Mechanics
Fujian province's cathode material processing clusters determine downstream pricing power for battery-based frequency regulation assets across Texas, California, and German balancing markets. Lithium hydroxide conversion capacity concentration in Xiamen and Ningde feeds directly into Megapack and Gridstack procurement economics, compressing margins for developers without offtake agreements with CATL or BYD.
Pricing Analysis
Texas-to-Germany price spreads for fast frequency response services exceed 3x when normalized for grid size, with ERCOT's 4-second settlement intervals capturing premium returns against slower European procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates sub-second synthetic inertia providers from 10-minute spinning reserve contracts and seasonal capacity payments. Cost compression in standard-tier battery storage is intensifying because Chinese processing overcapacity is exporting deflation through cathode supply agreements. Industrial load aggregators exhibit highest price sensitivity due to thin margins on demand response arbitrage, while ISO platform operators show lowest sensitivity given pass-through rate structures.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for grid-scale battery deployments targeting FERC-jurisdictional markets. Manufacturing concentration in China, South Korea, and Japan draws from lithium spodumene feedstock anchored in Australia, Chile, and Argentina. Single-source vulnerability in electrolyte salt production rests on processing assets concentrated in Japanese chemical complexes. Distribution runs through EPC contractors with utility relationships in Texas and California, bypassing direct OEM-to-developer channels for projects above 100 MW scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electricity ancillary services markets fragment as virtual power plants collapse minimum viable scale thresholds from 50 MW utility assets to sub-1 MW clusters, creating specialized niches for software-aggregated distributed resources.
For Market Incumbents: Build switching-cost moats through proprietary dispatch optimization software that locks battery operators into multi-year platform agreements. Deepen backward integration into grid-forming inverter firmware development to differentiate from commodity hardware suppliers. FERC Order 2222 compliance investments serve as the priority lever for locking out emerging virtual power plant aggregators lacking ISO certification histories. For New Entrants and Emerging Players: Establish a beachhead in Brazil's northeast transmission zones where wind penetration exceeds 70% without proportional frequency regulation procurement. Target ANEEL-regulated balancing markets with hybrid solar-plus-storage configurations that capture capacity payments unavailable to pure energy developers. Partner with established EPC contractors possessing interconnection queue priority in ERCOT and CAISO territories to bypass 3-5 year development timelines. For Investors and Strategic Acquirers: Long-term, this sits as a grid-software play because dispatch optimization and bidding algorithms determine returns more than hardware cost curves. Acquisition targets should emphasize virtual power plant platforms with demonstrated CAISO or ERCOT market participation rather than pure battery hardware manufacturers. Watch for synthetic inertia procurement mandates spreading beyond United Kingdom and Ireland grid codes as the signal indicating technology transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | Unlocks synthetic inertia revenue streams in United Kingdom and Ireland procurement frameworks. |
| Virtual Power Plant Platform Integration | Aggregates residential Tesla and Sunrun batteries into CAISO frequency regulation bids. |
| Hybrid Renewable-Plus-Storage PPA Structuring | Captures stacked capacity payments from Indian state load dispatch centers beyond energy revenues. |
| Synchronous Condenser Fleet Acquisition | Positions Siemens Energy and ABB for United Kingdom voltage support contract renewals. |
| Behind-the-Meter Battery Aggregation Partnership | Enables Enel X and AutoGrid to scale ERCOT demand response without dedicated storage capital. |
Methodological Framework
Desk research of FERC filings, EIA project databases, and interconnection queue records preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Texas, California, Germany, and Australia. Secondary validation drew from IEA reports, national regulator submissions to European Commission, and provincial energy administration disclosures in China. Bottom-up project economics modeling triangulated against top-down market sizing from transmission operator procurement data.
Assumptions held fixed include current FERC Order 841 and Order 2222 implementation timelines, lithium carbonate price bands within historical volatility ranges, and grid code synthetic inertia mandates spreading to 12 additional countries. Segmentation dimensions modeled encompass service type, utility ownership structure, technology class, and end-user category across the projection horizon. CAGRs derived from capacity deployment pipelines, interconnection queue velocities, and technology cost curve trajectories. Forecast inputs incorporated battery duration preferences shifting from 2-hour to 4-hour systems and vehicle-to-grid pilot scalability in Denmark and Netherlands.
Stress conditions across lithium export restriction scenarios, interconnection queue extension beyond 5 years, and synchronous condenser retirement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory stability and technology cost curves that could revise materially with trade policy shifts or breakthrough storage chemistries. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
India Gas Generator Market
Power Generation
Hydrogenerators Market
Power Generation
Retail Electricity Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Variable Speed Generator Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Mobile Power Plant Market
Power Generation
Subsea Power Grid System Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Oilfield Power Generation Market
Power Generation
Thermal Power Market