
 Sweden Electric Vehicle Charging Equipment Market | 2026-2036
Sweden Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Electric Vehicle Charging Equipment Market Insights
Subscription-based load management software is pivoting charger vendors from hardware-only sales to recurring revenue models. Zaptec leverages cloud-based energy balancing to sustain customer retention across Nordic residential clusters. Kempower anchors its position through modular DC fast-charging architecture designed for fleet depots. ABB competes on manufacturing scale, operating integrated production lines that extend cost advantages into commercial installation channels.
Sweden electric vehicle charging equipment encompasses conductive power transfer systems rated from 3.7 kW residential AC to 350 kW commercial DC outputs, incorporating power electronics, cable assemblies, and communications modules that enable grid-interactive vehicle energy exchange. DC Fast Chargers command premium positioning due to highway corridor deployment mandates and fleet electrification timelines, while Home Chargers occupy volume leadership through Sweden's single-family housing density and overnight charging preferences. IoT-enabled connectivity segments are capturing margin pools as utilities and charge point operators demand real-time telemetry for demand response programs.
The Swedish Energy Agency, the Swedish Transport Administration, and the EU Alternative Fuels Infrastructure Regulation collectively shape deployment obligations, subsidy frameworks, and interoperability standards across the national charging network. The EU AFIR mandates minimum power output requirements at public locations, while the Swedish Transport Administration directs corridor planning along European route E4 and E6 highways. Stakeholders must monitor grid connection queue timelines and evolving smart charging tariff structures as distributed energy resources reshape utility procurement criteria.
Market Dynamics
Sweden's fossil-free vehicle mandate is compressing fleet electrification timelines, forcing charge point operators to front-load highway corridor infrastructure ahead of vehicle deployment curves.
Growth Catalysts
- The Swedish Transport Administration corridor planning:Highway E4 and E6 fast-charging mandates are pulling forward depot procurement by logistics operators.
- EU Alternative Fuels Infrastructure Regulation power floors:Minimum output requirements at public locations are disqualifying legacy hardware and accelerating replacement cycles.
- Stockholm metropolitan cluster density:Grid reinforcement investments in the capital region are unlocking multi-megawatt fleet hub installations.
Market Restraints
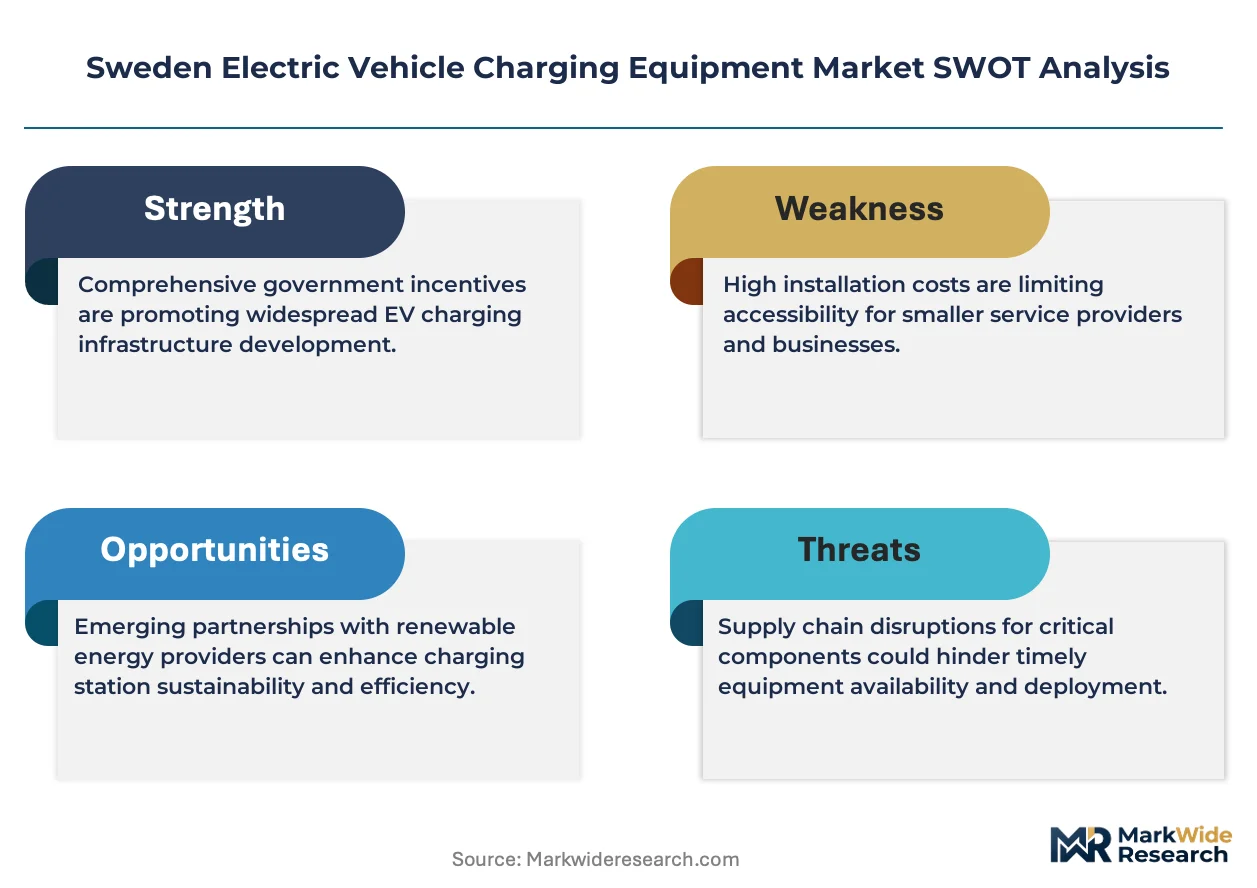
- Copper and silicon carbide cost volatility:Power electronics input prices are squeezing margins on DC fast-charger production.
- Nordic grid connection queues:Utility interconnection timelines in northern counties are extending project payback periods.
- Legacy AC hardware substitution:Existing 11 kW residential units are delaying 22 kW upgrade demand in single-family housing zones.
Strategic Opportunities
- Gothenburg industrial port electrification:Heavy freight corridors around the harbor present untapped depot charging demand.
- Vehicle-to-grid tariff reform:The Swedish Energy Agency's smart charging pilot programs are creating revenue stacking models for bidirectional hardware.
- Modular DC architecture convergence:Scalable power electronics are enabling charger-as-a-service offerings for mid-sized fleet operators.
Industry Challenges
- Grid integration engineering talent scarcity:Power systems specialists with EV-specific load management expertise command premium compensation in Stockholm and Malmö labor markets.
- CE marking plus Swedish Electrical Safety Authority dual certification:Parallel compliance timelines are extending product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Electric Vehicle Charging Equipment Market |
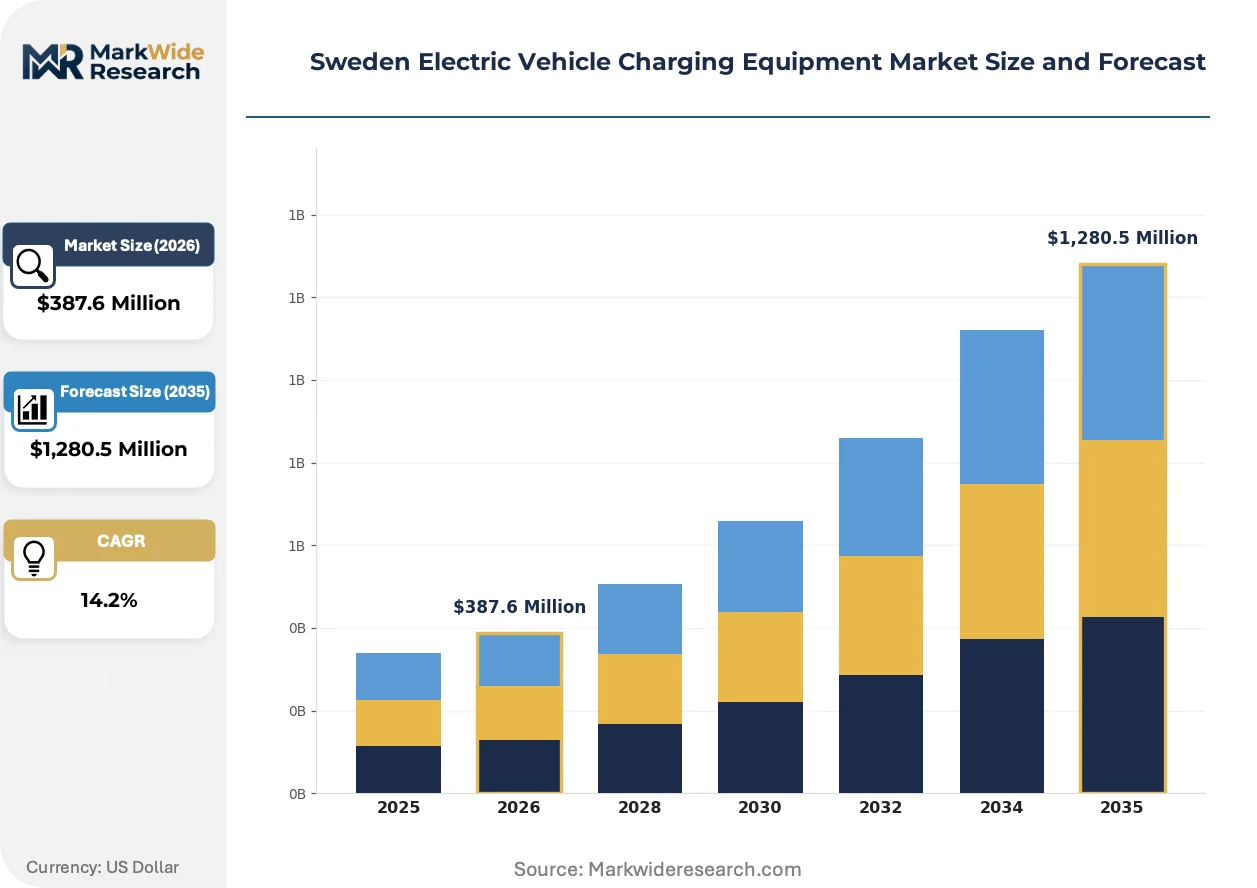
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Home Chargers, Commercial Chargers Installation Type: Wall-mounted, Standalone, Embedded, Networked End User: Residential Users, Fleets, Commercial Properties, Public Charging Stations Connectivity: Wired, Wireless, IoT-enabled, Smart Grid Compatible |
| Companies Covered | Zaptec, Kempower, Vattenfall, CTEK, Charge Amps, GARO, Wallbox Chargers, ABB, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware commoditization is pushing vendors toward software-defined charging architectures that monetize energy management rather than power electronics alone.
Vehicle-to-grid (V2G) bi-directional charging is converging with cloud-based load aggregation platforms. Fleet operators in Skåne County are piloting aggregated bidirectional capacity for frequency regulation services. This convergence is compressing the payback period for high-cost DC hardware from infrastructure spend to revenue-generating asset.
The EU AFIR's 2025 power output mandates are forcing hardware refresh cycles at public charging locations. Operators must replace sub-150 kW units along priority corridors. Swedish charge point networks are responding by pre-positioning 350 kW-capable sites ahead of vehicle battery acceptance rates.
Subscription-based energy management is displacing upfront hardware purchases among residential cooperatives. Housing associations in Uppsala and Linköping are procuring charging-as-a-service bundles that include installation, maintenance, and dynamic load balancing. This shift is most visible in multi-unit dwellings where capital constraints previously blocked individual owner installations.
Sweden Electric Vehicle Charging Equipment Market Segmentation
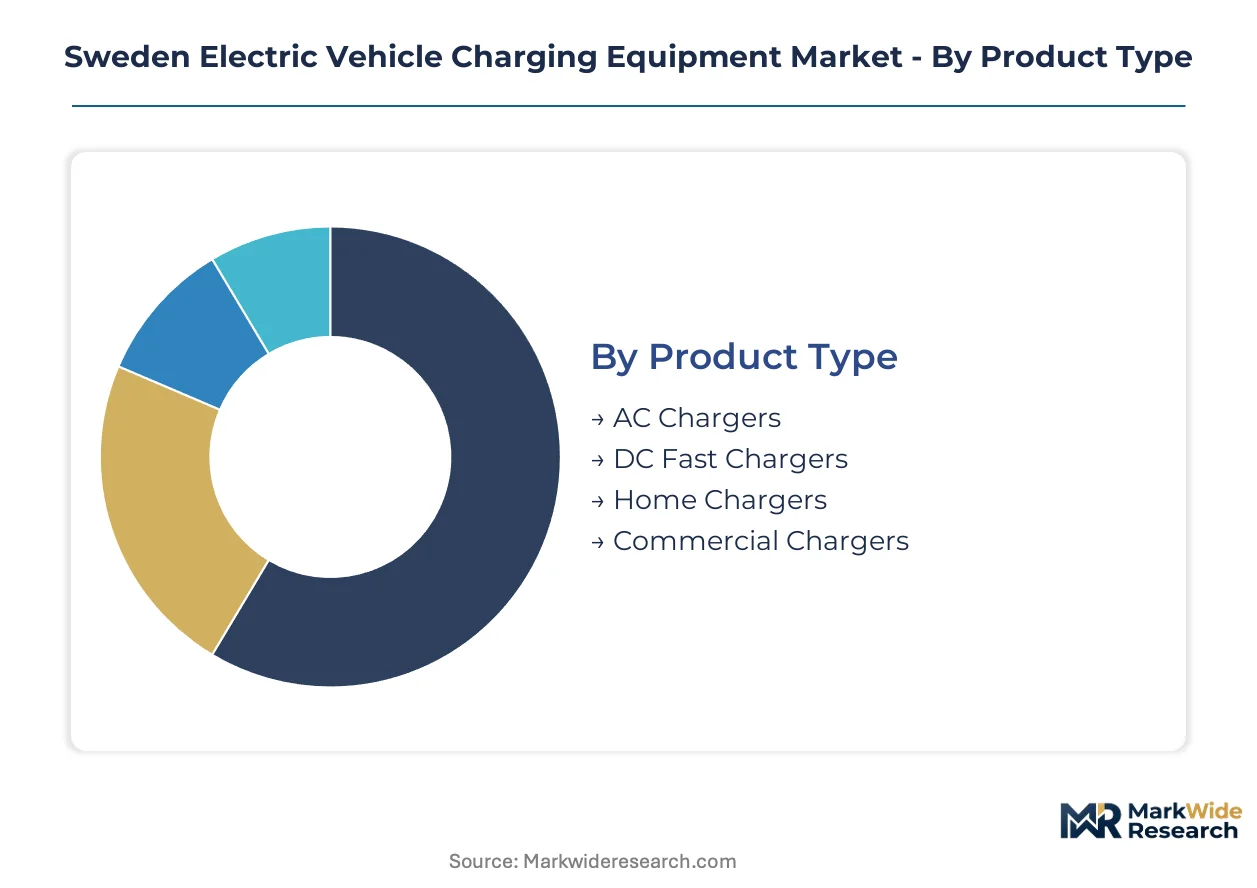
Sweden's charging equipment market fragments across power output tiers, installation architectures, and connectivity standards that determine grid integration complexity. Each segment carries distinct procurement rhythms and margin structures shaped by the Swedish Energy Agency's subsidy frameworks and the EU AFIR's infrastructure mandates.
Product Type:
Fleet operators and housing associations prioritize power output and utilization rates when selecting charging hardware for Swedish deployment.
- DC Fast Chargers:High-power conductive systems rated 150-350 kW deliver highway corridor charging and depot turnaround for logistics fleets. Demand concentrates along European route E4 and E6 corridors where the Swedish Transport Administration mandates minimum power floors, with procurement accelerating ahead of heavy-duty vehicle electrification timelines.
- Home Chargers:Residential AC units at 3.7-22 kW dominate unit volumes through Sweden's single-family housing density and overnight charging preferences. Stockholm metropolitan clusters show strongest uptake where grid reinforcement investments have reduced interconnection delays for housing cooperatives.
- AC Chargers:Commercial-grade alternating current systems serve workplace and retail parking installations with 11-43 kW outputs.
- Commercial Chargers:Multi-port pedestal units serve retail and hospitality locations with load management capabilities.
Volume sits with Home Chargers; growth tilts toward DC Fast Chargers.
Installation Type:
Physical mounting architecture determines site preparation costs and grid connection complexity across Swedish deployment contexts.
- Networked:Cloud-connected systems with centralized load management and payment processing enable demand response participation and subscription billing. Fleet depots in Gothenburg industrial zones prioritize networked architectures for energy cost optimization and utility tariff stacking.
- Standalone:Grid-tied units without backhaul connectivity serve locations with limited telecommunications infrastructure. Northern counties facing extended utility interconnection queues favor standalone configurations for faster commissioning despite limited smart charging capabilities.
- Wall-mounted:Space-efficient bracket installations dominate residential garages and multi-unit parking structures.
- Embedded:Infrastructure-integrated charging points built into parking surfaces or architectural elements.
Standalone units retain volume leadership; networked configurations are climbing the fastest as fleet electrification compresses payback requirements.
End User:
Procurement authority and utilization intensity create divergent specification requirements across Swedish customer segments.
- Fleets:Logistics operators and municipal vehicle pools demand high-availability charging with 95%+ uptime guarantees and depot-scale power aggregation. Malmö metropolitan corridor logistics hubs are front-loading DC infrastructure ahead of delivery vehicle deployment curves.
- Public Charging Stations:Highway service area and urban curbside operators prioritize interoperability and payment system integration under EU AFIR accessibility mandates.
- Residential Users:Single-family homeowners and apartment dwellers purchasing through housing associations or individual installation contracts.
- Commercial Properties:Retail, office, and hospitality locations installing charging as tenant amenity or customer acquisition tool.
Fleets command the steepest expansion trajectory; residential channels sustain absolute volume.
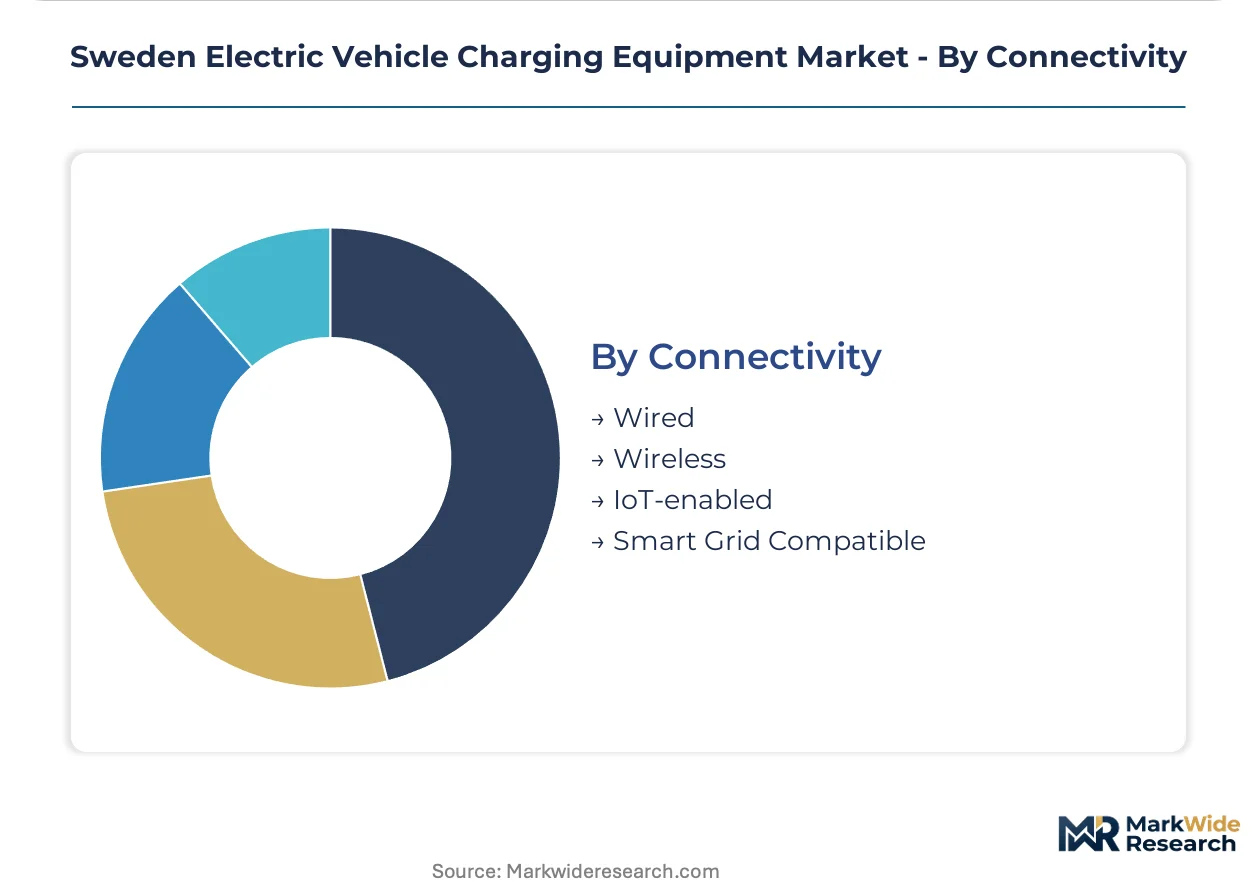
Connectivity:
Communications capability determines revenue model flexibility and grid services market access for Swedish charge point operators.
- IoT-enabled:Cellular and ethernet-connected units transmit real-time telemetry for predictive maintenance and dynamic pricing. Skåne County fleet pilots leverage IoT-enabled bidirectional hardware for frequency regulation revenue stacking.
- Smart Grid Compatible:Units with OpenADR or proprietary utility interfaces enable automated demand response and variable tariff optimization.
- Wired:Ethernet or powerline communication systems for locations with reliable fixed infrastructure.
- Wireless:Inductive power transfer and communication systems for automated parking applications.
Wired connectivity retains installed base dominance; IoT-enabled segments are gaining share fastest as subscription revenue models displace hardware-only sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish equipment consumption outpaces domestic manufacturing capacity, forcing reliance on Nordic supply chains and German component imports. Grid interconnection bottlenecks in northern counties create deployment friction absent in metropolitan corridors.
Stockholm Metropolitan Cluster
Single-family housing density and housing cooperative procurement drive residential AC charger volumes. The Swedish Energy Agency's installation subsidies prioritize grid-reinforced zones, accelerating uptake in Stockholm, Uppsala, and Linköping where utility infrastructure investments have reduced interconnection delays.
Gothenburg Industrial Corridor
Harbor freight electrification and logistics fleet depot construction command multi-megawatt DC installations. The Swedish Transport Administration's E6 highway corridor mandates pull forward procurement by shipping operators and last-mile delivery networks around the port zone.
Malmö-Skåne County
Cross-border freight flows and Øresund Bridge connectivity position the region for heavy-duty vehicle charging hubs. EU AFIR power floor requirements and Danish-Swedish interoperability standards shape hardware specifications for corridor operators.
Västra Götaland and Northern Counties
Extended utility interconnection queues in Västerbotten and Norrbotten compress deployment timelines for standalone configurations. The national fossil-free vehicle mandate forces fleet operators here to front-load infrastructure despite grid reinforcement lags.
Sweden Electric Vehicle Charging Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across hardware manufacturing and software platform layers. The vendor base concentrates around Nordic specialists with grid-integration expertise and European electrical conglomerates with manufacturing scale. Three archetypes dominate: modular DC fast-charging architects, cloud-native residential platform operators, and integrated industrial automation suppliers. Competitive intensity manifests through subscription revenue model adoption and fleet-centric service bundling rather than pure hardware pricing.
Among Nordic specialists, Zaptec and Kempower occupy distinct positioning within the residential and fleet segments respectively. Zaptec leverages Norwegian cloud-native architecture for housing cooperative deployments across Swedish multi-unit dwellings. Kempower anchors the modular DC tier with scalable power electronics designed for depot-scale installations. ABB represents the integrated industrial tier, drawing on Swiss-Swedish manufacturing scale and automation heritage to serve commercial installation channels with standardized product platforms.
| Leading Market Players |
|---|
| Zaptec |
| Kempower |
| Vattenfall |
| CTEK |
| Charge Amps |
| GARO |
| Wallbox Chargers |
| ABB |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement mandates for 350 kW highway corridor infrastructure are compressing supplier lead times and forcing DC fast-charger vendors to absorb silicon carbide and copper volatility through contract restructuring. This demand-side specification tightening feeds directly into margin pressure across Nordic production networks.
Pricing Analysis
Cost-down pressure on DC fast-charger tiers accelerates because EU AFIR power floor mandates are disqualifying sub-150 kW legacy units and triggering replacement procurement waves. Pricing stratifies across premium 350 kW modular systems, standard 150-200 kW highway units, and economy 11-22 kW residential tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Margin tightening in residential AC segments traces to housing cooperative volume aggregation and subscription-based charging-as-a-service displacement of upfront hardware purchases. Fleet operators show lowest price sensitivity due to uptime guarantee requirements and depot-scale power aggregation needs, while individual residential buyers in northern counties face highest sensitivity given grid interconnection cost uncertainty.
Supply Chain Analysis
Single-source vulnerability sits with German power electronics component suppliers and Chinese rare earth magnet providers for high-efficiency motor drives. Manufacturing concentration spans Germany for IGBT and silicon carbide modules, China for magnetic components and cable assemblies, and domestic Swedish facilities for final system integration and software loading. Raw material dependencies include copper for conductor assemblies, silicon carbide substrates for next-generation inverters, and high-grade aluminum for thermal management housings. Tariff exposure on Chinese electrical components presents structural risk as EU trade remedy investigations expand. Distribution runs through specialized electrical wholesalers serving installation contractors, direct OEM relationships with fleet operators, and utility-aligned channel partners for residential deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's charging equipment sector is transitioning from hardware-centric sales to software-defined energy management platforms, with cloud-native load aggregation replacing standalone unit procurement as the dominant technology architecture.
For Market Incumbents: Deploy backward integration into silicon carbide semiconductor sourcing to defend margins against raw material volatility and emerging Asian power electronics entrants. Prioritize certification investment for Swedish Electrical Safety Authority dual-marking acceleration to compress product launch windows. Channel control through exclusive installer network agreements in Stockholm and Gothenburg corridors limits disintermediation by modular DC specialists.
For New Entrants and Emerging Players: The 150-200 kW gap between premium 350 kW highway systems and economy 11-22 kW residential units offers white-space positioning for mid-sized fleet operators in Västra Götaland industrial zones. Northern counties with extended grid connection queues present penetrable geography for standalone configurations with simplified commissioning. Charging-as-a-service bundling for housing cooperatives provides go-to-market angle with recurring revenue foundation.
For Investors and Strategic Acquirers: Re-rating potential sits with Nordic cloud-native platform operators given vehicle-to-grid tariff reform creating revenue stacking models for bidirectional hardware. Long-term viability favors software-defined architectures with utility integration depth over pure hardware manufacturers facing commoditization pressure. Acquisition target archetype: modular DC fast-charging designers with fleet depot reference installations. Signal to watch: Swedish Energy Agency smart charging pilot program expansion into frequency regulation markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Charging Platform Development | Cloud-native load aggregation enables recurring revenue displacement of hardware-only sales for housing cooperatives. |
| Backward Integration into Power Electronics | In-house silicon carbide sourcing mitigates margin compression from German and Chinese component volatility. |
| Vehicle-to-Grid Certification Investment | Swedish Electrical Safety Authority bidirectional approval unlocks frequency regulation revenue stacking for fleet operators. |
| Modular DC Architecture Scaling | Scalable power electronics enable charger-as-a-service offerings compressing payback periods for mid-sized logistics depots. |
| Utility Channel Partnership Expansion | Direct integration with Vattenfall and regional grid operators accelerates residential procurement through tariff-aligned offerings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across charge point operators, fleet procurement directors, utility planning officers, and electrical installation contractors. Swedish Energy Agency subsidy disbursement records, EU AFIR implementation guidance documents, and Nordic customs import classifications for charging equipment provided demand-side validation. Bottom-up unit deployment tracking across Stockholm, Gothenburg, and Malmö metropolitan corridors was triangulated against top-down manufacturer shipment data from Nordic production facilities.
Granularity-level modeling addressed power output tiers, installation architectures, connectivity standards, and end-user segments throughout the forecast period. The analytical framework derived expansion rates through equipment replacement cycle analysis, fleet electrification timeline alignment, and grid reinforcement investment correlation. Industry-specific inputs included Swedish Transport Administration corridor planning schedules, housing cooperative procurement pattern shifts, and silicon carbide supply availability projections.
Underlying measurement precision varies by segment; DC fast-charger deployment carries tighter precision than residential AC unit estimates due to mandatory public reporting requirements. Forecasts reflect assumptions around EU AFIR enforcement timing, grid interconnection queue resolution, and vehicle battery acceptance rate evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market