
 India Gensets Market | 2026-2036
India Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
India Gensets Market Outlook
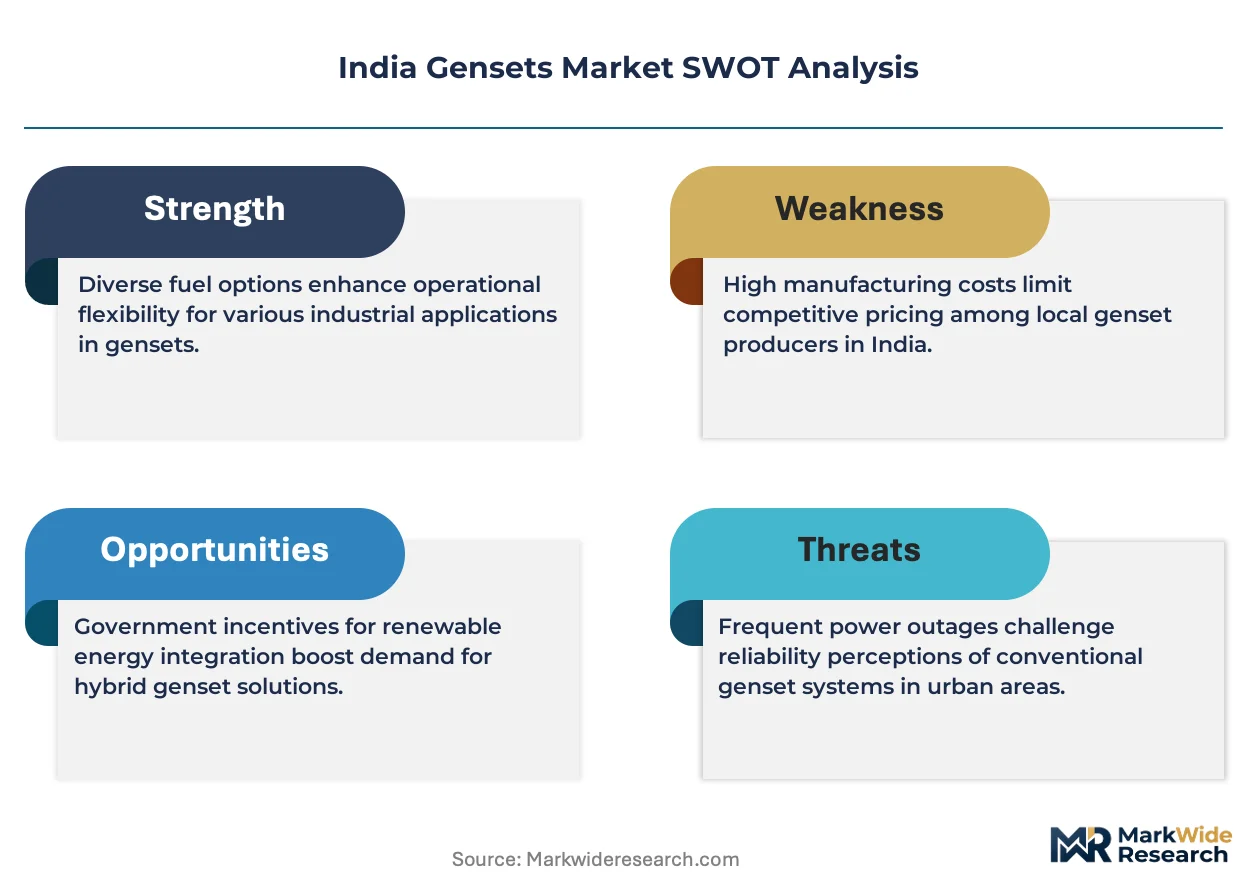
Healthcare infrastructure expansion is repositioning genset procurement priorities across India. Cummins India leverages its nationwide service network to dominate hospital and diagnostic center installations. Kirloskar Oil Engines Ltd. anchors the industrial segment with heavy-duty diesel platforms engineered for continuous operation. Mahindra Powerol competes aggressively in the telecom tower segment with compact, fuel-efficient units designed for remote site reliability.
Gensets are electromechanical devices comprising an internal combustion engine coupled to an alternator, producing electrical power typically ranging from 0.5 kVA to 3,000 kVA for standby, prime, or emergency applications. Diesel gensets remain the installed base majority, though gas and bi-fuel configurations are gaining share where pipeline infrastructure permits cleaner combustion. Hybrid systems integrating battery storage with conventional generator sets represent the fastest-growing technology segment, particularly for data center customers seeking emission reductions and fuel cost optimization. Portable gensets occupy a mature, price-sensitive niche serving construction contractors and rural residential users.
CPCB, BIS, and CEA frameworks govern emission thresholds, product certification, and grid interconnection standards for genset deployment across Indian states. CPCB Stage IV norms are forcing product redesigns and accelerating retirement of older diesel units in Delhi-NCR, Mumbai, and Bengaluru metropolitan regions. Stakeholders must monitor state-level renewable energy mandates and gas infrastructure buildouts to calibrate technology portfolios between conventional and hybrid power solutions.
Market Dynamics
CPCB Stage IV emission norms are compressing diesel genset deployment timelines across Indian metropolitan regions. The regulatory pressure is accelerating technology portfolio pivots toward gas and hybrid configurations while forcing premature retirement of installed base assets in Delhi-NCR, Mumbai, and Bengaluru.
Growth Catalysts
- Data center power reliability mandates:Hyperscale operators in Maharashtra and Karnataka are mandating N+1 backup configurations, doubling genset procurement volumes per facility.
- CPCB Stage IV compliance deadlines:The 2024-2025 enforcement window is triggering replacement cycles for pre-2016 diesel units across industrial clusters.
- Biogas and natural gas pipeline expansion:Gujarat's city gas distribution network extension is enabling gas genset deployment for textile processing units seeking fuel cost arbitrage.
Market Restraints
- Diesel fuel price volatility:Indian Oil Corporation's monthly pricing adjustments expose operator margins to unrecoverable operating cost spikes in continuous-duty applications.
- Import dependency for high-kVA alternators:European and Chinese suppliers control critical components above 1,000 kVA, creating forex exposure and lead time uncertainty.
- Grid parity pressure from solar-plus-storage:Falling lithium-ion battery costs and open-access solar tariffs are narrowing the economic window for prime-power genset deployment.
Strategic Opportunities
- Eastern and northeastern state electrification gaps:Bihar, Odisha, and Assam present underserved captive power demand from manufacturing units facing grid instability.
- Hybrid genset-battery systems:Integration of lithium-ion storage with conventional diesel platforms enables load optimization and emission reduction for data center customers.
- PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives will localize hybrid system supply chains and compress total cost of ownership.
Industry Challenges
- Emission testing infrastructure scarcity:CPCB-certified testing facilities are concentrated in Delhi, Mumbai, and Chennai, delaying product certification for regional manufacturers.
- Skilled technician shortages for gas genset commissioning:Pipeline fuel system integration and carburetion calibration require specialized expertise absent in traditional diesel service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gensets Market |
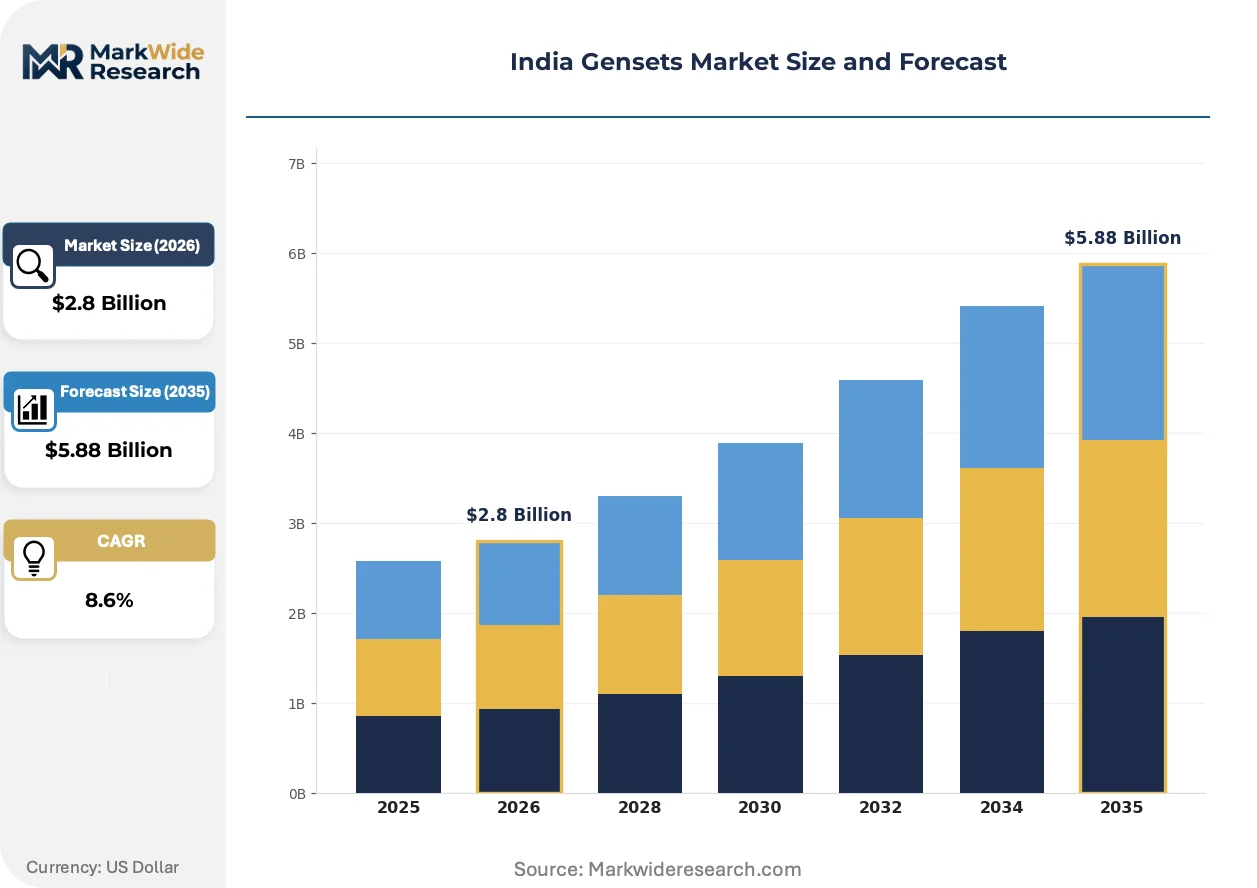
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Gas, Bi-Fuel, Portable End User: Construction, Healthcare, Industrial, Residential Technology: Generator Sets, Hybrid Systems, Renewable Source, Conventional Installation: Fixed, Mobile, Stationary, Containerized |
| Companies Covered | Cummins India, Kirloskar Oil Engines Ltd., Mahindra Powerol, Caterpillar Inc., Greaves Cotton Limited, Ashok Leyland Ltd., MTU Onsite Energy, Honda Siel Power Products Ltd., Kohler Power Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gensets Market Strategic Shifts
Technology convergence between conventional combustion platforms and electrochemical storage is redefining genset architecture. The shift is compressing product development cycles and forcing recalibration of service revenue models across the value chain.
Hybrid genset-battery systems are electrifying backup power architecture for mission-critical infrastructure. Data center operators in Hyderabad and Chennai are specifying 30-minute battery ride-through paired with downsized diesel engines. The configuration is electrifying traditional N+1 redundancy designs by reducing engine run hours and maintenance frequency.
CPCB Stage IV emission norms are mandating selective catalytic reduction and diesel particulate filter integration for gensets above 800 kVA. The compliance burden is compressing product portfolios as smaller manufacturers exit the heavy-duty segment. Maharashtra's industrial belt is witnessing accelerated fleet turnover as state pollution control boards intensify enforcement.
Telecom tower companies are unbundling genset ownership from fuel supply and maintenance contracts. Tower Infrastructure Providers in Gujarat and Rajasthan are migrating to opex-based power-as-a-service agreements with integrated remote monitoring. The model is concentrating procurement authority at holding company level while displacing decentralized site-level decision-making.
India Gensets Market Segmentation
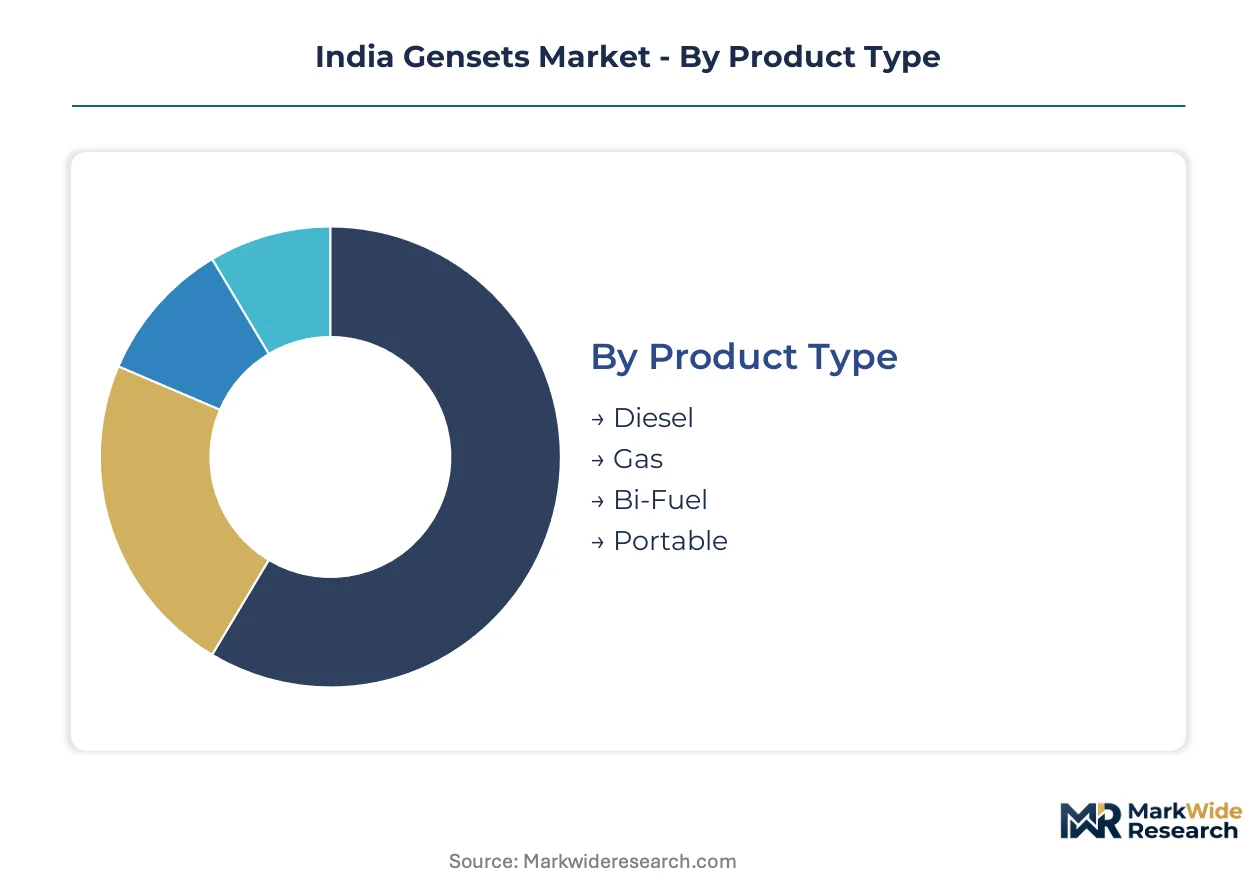
Genset procurement patterns in India diverge sharply across fuel types, end-use applications, and deployment configurations. Understanding these fault lines reveals where CPCB compliance costs, infrastructure maturity, and customer operating models reshape competitive positioning.
Product Type:
Buyers in this category separate by fuel access infrastructure and emission tolerance thresholds.
- Diesel:Compression-ignition engines dominate the installed base from 15 kVA to 2,000 kVA ratings. Demand concentrates in Maharashtra's automotive component clusters where grid instability forces continuous-duty operation despite CPCB Stage IV retrofit costs.
- Gas:Spark-ignited natural gas and biogas configurations eliminate particulate matter emissions. Gujarat's city gas distribution corridors are absorbing volumes from textile processors seeking fuel cost arbitrage against diesel price volatility.
- Bi-Fuel:Dual-fuel carburetion permits diesel-gas blending ratios from 30% to 70%. These units serve Karnataka food processing units transitioning incrementally toward pipeline fuel dependence.
- Portable:Compact single-cylinder units below 10 kVA target construction contractors and rural residential backup. Price sensitivity here compresses margins to single digits.
Diesel leads volumes today; hybrid gas-diesel configurations are gaining share fastest.
End User:
Application-specific duty cycles and redundancy requirements fragment procurement specifications.
- Construction:Rental fleet operators in Delhi-NCR and Hyderabad specify ruggedized skid-mounted units for 16-hour daily operation. CPCB enforcement in these metros is accelerating fleet turnover toward Stage IV compliance.
- Healthcare:NABH-accredited hospitals mandate zero-transfer-time backup with 72-hour fuel autonomy. Tamil Nadu's diagnostic center expansion is concentrating demand for 500-800 kVA silent-canopy installations.
- Industrial:Continuous-duty prime power applications in Odisha's aluminum smelting and Jharkhand's steel processing require 1,000+ kVA heavy-duty platforms. These buyers prioritize mean time between failures over capital expenditure.
- Residential:Apartment complexes in Bengaluru and Pune specify 125-250 kVA units for common area backup. RERA-mandated infrastructure standards are formalizing procurement specifications.
Industrial applications anchor revenue today; healthcare infrastructure is expanding most quickly.
Technology:
Architecture choices hinge on emission reduction mandates versus capital budget constraints.
- Generator Sets:Conventional engine-alternator packages without storage integration remain the default for cost-constrained buyers. These dominate Bihar and Uttar Pradesh where grid extension lags industrial demand.
- Hybrid Systems:Lithium-ion battery banks paired with downsized diesel engines enable 30-minute silent ride-through. Data center operators in Chennai and Mumbai are specifying these for N+1 redundancy with reduced engine runtime.
- Renewable Source:Solar-diesel or wind-diesel hybrids incorporate photovoltaic arrays or small wind turbines. These serve remote telecom towers in Rajasthan and Madhya Pradesh where grid connection is uneconomical.
- Conventional:Basic mechanical-governing gensets without electronic control modules persist in price-sensitive rural markets. Maintenance simplicity overrides efficiency considerations.
Conventional gensets retain volume leadership; hybrid systems are climbing the fastest.
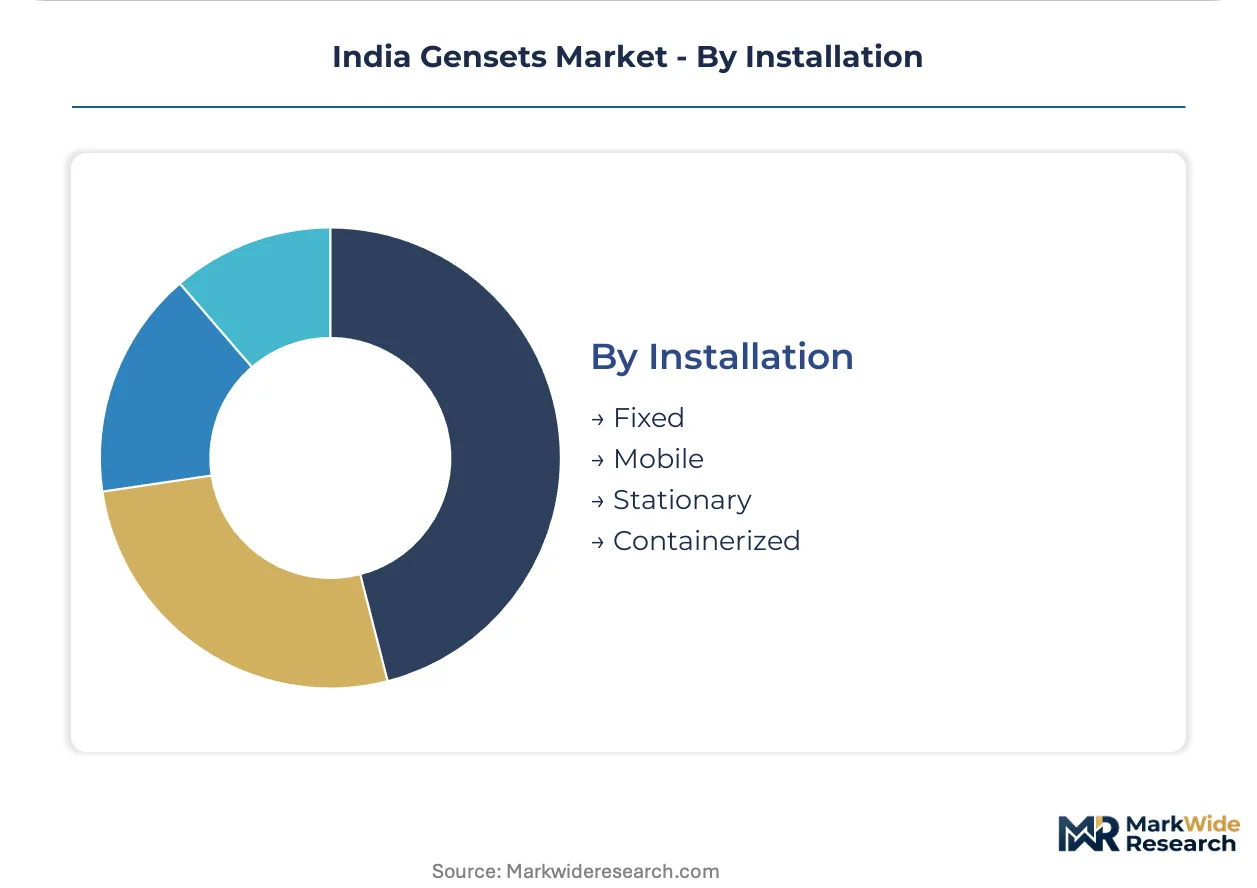
Installation:
Deployment mobility requirements and site tenure duration determine enclosure and transport specifications.
- Fixed:Permanent concrete foundation installations with integrated fuel tanks serve manufacturing facilities with 20-year asset horizons. These dominate Gujarat's chemical processing corridors.
- Mobile:Trailer-mounted units with highway-certified towing configurations target infrastructure contractors on 6-18 month project cycles. Highway toll exemptions for power equipment influence procurement decisions.
- Stationary:Non-transportable skid-mounted units without permanent foundations serve semi-permanent industrial installations. These balance relocation flexibility against weather protection.
- Containerized:ISO-standard shipping container enclosures with integrated acoustic treatment and fuel systems. Hyperscale data centers in Hyderabad specify these for rapid deployment and standardized site preparation.
Fixed installations dominate current deployment; containerized solutions are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit compliance-cost arbitrage between states with stringent CPCB enforcement and those with relaxed inspection regimes. Gujarat and Maharashtra attract capital investment from operators retiring Delhi-NCR fleets. Southern states leverage port infrastructure for component import while eastern markets remain underserved.
Maharashtra
Data center construction in Mumbai and Pune drives demand for containerized gensets above 1,000 kVA. MIDC industrial zones mandate captive power for pharmaceutical and automotive component clusters. Thane-Belapur chemical belt operators face accelerated replacement timelines under Maharashtra Pollution Control Board directives.
Gujarat
City gas distribution networks enable natural gas genset deployment across Surat and Ahmedabad textile corridors. GIDC estates offer subsidized land for captive power installations. Dahej and Hazira petrochemical complexes require continuous-duty prime power configurations with 99.5% availability guarantees.
Karnataka
Bengaluru's hyperscale data center expansion consumes 500-800 kVA hybrid configurations with lithium-ion ride-through. Karnataka State Pollution Control Board enforces Stage IV norms across Electronics City and Peenya industrial areas. Mysuru food processing units trial biogas gensets under state renewable energy purchase obligations.
Tamil Nadu
Chennai's medical device and diagnostic center construction concentrates demand for 72-hour fuel-autonomous backup systems. SIPCOT industrial parks in Sriperumbudur and Oragadam enforce noise emission limits below 75 dB at one meter. Coimbatore pump manufacturing clusters deploy skid-mounted units for export-oriented production lines.
Telangana
Hyderabad's pharmaceutical formulation facilities require zero-transfer-time UPS-genset integration for FDA compliance. TS-iPASS incentives attract data center operators to Maheshwaram and Adibatla corridors. Telangana State Pollution Control Board mandates online emission monitoring for gensets above 800 kVA in Patancheru bulk drug zone.
India Gensets Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The market exhibits moderate concentration with three domestic conglomerates commanding industrial and telecom verticals while multinational engine licensors dominate premium ratings above 1,500 kVA. Two strategic archetypes prevail: integrated engine-alternator fabricators with captive foundry capacity, and technology licensees assembling imported powerheads with localized enclosures. Competitive intensity manifests through distribution network expansion into tier-2 cities and service contract bundling with fuel supply arrangements.
Among domestic engine specialists, Kirloskar Oil Engines Ltd., Mahindra Powerol, and Greaves Cotton Limited exemplify the integrated fabrication archetype. These Pune-headquartered entities leverage in-house casting and machining capabilities to control cost structures in the 15-500 kVA range. Their position reflects decades of agricultural pump-set engineering translated into industrial power generation, with nationwide service density as the primary retention mechanism against multinational entrants.
| Leading Market Players |
|---|
| Cummins India |
| Kirloskar Oil Engines Ltd. |
| Mahindra Powerol |
| Caterpillar Inc. |
| Greaves Cotton Limited |
| Ashok Leyland Ltd. |
| MTU Onsite Energy |
| Honda Siel Power Products Ltd. |
| Kohler Power Systems |
| Others |
Value Chain & Pricing Dynamics
Hybrid genset-battery integration is compressing manufacturing cost structures while redistributing value capture toward lithium-ion cell suppliers and power electronics specialists. This technology shift simultaneously elevates working capital requirements for assemblers and fragments pricing power across the value chain as battery costs decouple from engine-alternator economics.
Pricing Analysis
Distributor margins in the 15-500 kVA segment absorb 12-18 percent of ex-factory value before reaching industrial end-users. Pricing stratifies across CPCB Stage IV-certified premium tiers, basic mechanical-governing economy units, and mid-range electronic-governed configurations with remote monitoring. Cost compression in the portable segment is intensifying because Chinese single-cylinder imports are penetrating construction rental fleets. Healthcare and data center buyers exhibit lowest price sensitivity, prioritizing 99.5 percent availability guarantees over capital expenditure minimization.
Supply Chain Analysis
High-kVA alternator supply rests on European and Chinese electromagnetic component specialists with limited Indian domestic alternatives. Engine castings and forgings draw from foundry clusters in Maharashtra and Gujarat, while electronic control modules hinge on Taiwanese and South Korean semiconductor packaging. Single-source vulnerability concentrates in permanent magnet alternators above 1,000 kVA where two German suppliers dominate global capacity. Distribution runs through manufacturer-owned branches in tier-1 cities, authorized dealers in industrial corridors, and rental fleet operators for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India gensets market functions as a regulatory compounder where CPCB Stage IV enforcement is accelerating replacement demand and compressing product lifecycles.
For Market Incumbents: Cement service network density in western and southern industrial corridors to lock in aftermarket revenue as hardware margins compress. Acquire certified testing capabilities ahead of competitors to reduce product launch delays under tightened emission protocols. Prioritize backward integration into alternator winding and electronic governor assembly to mitigate forex exposure on imported powerheads above 1,000 kVA. For New Entrants and Emerging Players: Biogas genset commissioning expertise offers entry into Karnataka food processing and Maharashtra distillery captive power segments where pipeline infrastructure is immature and incumbent service capacity is shallow. Target eastern state electrification gaps in Odisha and Jharkhand aluminum-steel clusters where grid instability forces continuous-duty prime power procurement. Lead with opex-based power-as-a-service contracts to bypass capital-constrained buyer procurement committees. For Investors and Strategic Acquirers: Roll-up economics work for regional genset rental fleet operators because asset utilization rates vary predictably across construction cycles and emission compliance deadlines force fleet refresh timing. The 5-10 year viability window favors platform consolidation around telemetry-enabled remote monitoring capabilities that differentiate service contracts. Watch CPCB Stage V announcement timing as the signal for accelerated replacement cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Battery-diesel pairing reduces engine runtime for N+1 data center redundancy mandates in Hyderabad and Chennai. |
| Biogas Genset Deployment | Karnataka renewable energy purchase obligations create captive demand for agricultural waste-to-power conversion. |
| Containerized Rapid Deployment | ISO-standard enclosures compress site preparation timelines for hyperscale data center construction in Mumbai. |
| Service Contract Bundling | Fuel supply integration locks in recurring revenue from telecom tower operators in Gujarat and Rajasthan. |
| Emission Testing Certification | CPCB-certified facilities accelerate product launch velocity under Stage IV compliance deadlines. |
Study Parameters
Direct dialogue with plant engineers at aluminum smelters and steel processors, genset rental fleet operators, CPCB certification laboratory directors, and data center facility managers grounded qualitative findings in operational reality. Secondary validation drew from Central Electricity Authority grid reliability statistics, CPCB emission compliance bulletins, state pollution control board enforcement circulars, and customs import data for high-kVA alternators. Bottom-up and top-down triangulation reconciled unit shipment estimates with fuel consumption patterns and captive power registration filings.
Bottom-up modeling aggregated segment-level demand across diesel, gas, bi-fuel, and hybrid configurations by end-use application and installation type. Top-down cross-checks applied macroeconomic sensitivities to industrial production indices, data center capacity additions, and healthcare infrastructure investment flows. CAGRs were derived from fitted growth curves calibrated to historical replacement cycles and regulatory milestone timing. The forecast framework incorporated state-level gas pipeline buildout trajectories and lithium-ion battery cost decline curves as technology transition inputs.
The model holds under continued CPCB enforcement intensity and grid reliability stagnation in industrial corridors; deviation in accelerated renewable-plus-storage grid parity or natural gas price collapse would shift technology adoption timelines. Forecasts reflect documented assumptions about emission norm implementation schedules and infrastructure investment continuity. A small set of triggers—CPCB Stage V pre-announcement, interstate transmission corridor completion, and domestic battery cell PLI scheme utilization rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Micro CHP Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Hydrogenerators Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Global Gensets Market
Power Generation
Power Generation Technologies Market
Power Generation
Subsea Power Grid System Market
Power Generation
Distributed Generation Market
Power Generation
Residential Solar Generator Market
Power Generation
Global Black Start Generator Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Global Turbines Market
Power Generation
Stirling Engine Market
Power Generation
On-Grid Combined Heat and Power Market