
 Oman Power Market | 2026-2036
Oman Power Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Power Market Analytics
Modular generation bundling with desalination and industrial steam is rebalancing buyer choice across Oman's power procurement landscape. OPWP anchors long-term capacity planning through competitive tenders that emphasize integrated water-power solutions. ACWA Power leverages its track record in Saudi Arabia to compete for independent power producer slots in Salalah and Sohar. Mazoon Electricity Distribution Company sustains rural electrification across Al Batinah and Al Dakhiliyah governorates with grid extension programs.
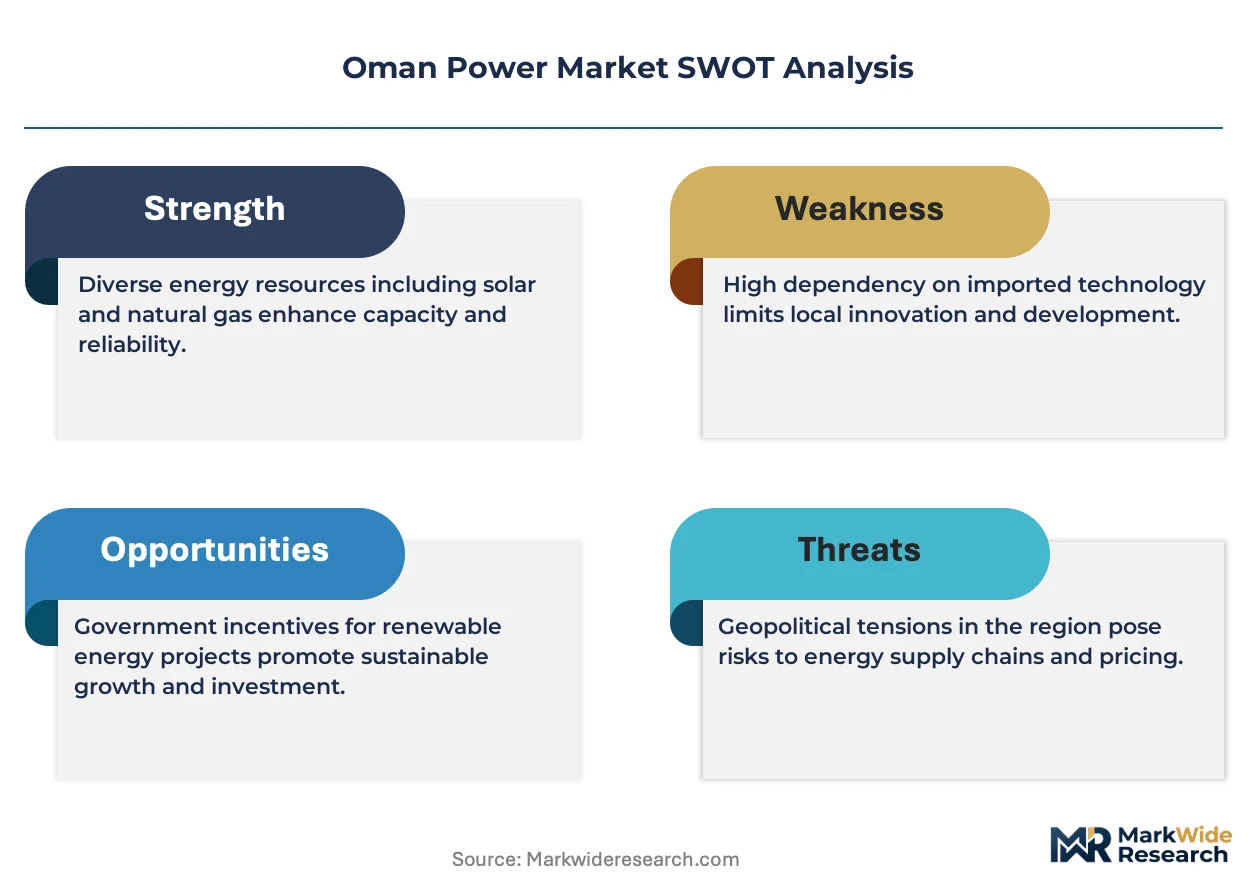
Oman power encompasses electricity generation, transmission, and distribution infrastructure operating at 132 kV to 400 kV transmission voltages with diesel, natural gas, and renewable feedstocks. The system serves industrial, commercial, and residential loads across a territory where summer peak demand frequently exceeds winter baselines by forty percent. Solar PV installations dominate new capacity additions as levelized costs fall below open-cycle gas alternatives. Thermal power retains baseload responsibility but faces margin compression from carbon intensity regulations. Gas turbine technology occupies the critical flexibility layer, cycling daily to balance intermittent renewable output.
The Authority for Electricity Regulation (AER) sets tariff structures and licensing terms that shape investor returns, while the Ministry of Energy and Minerals oversees national resource allocation and renewable targets. AER's competitive procurement framework requires bidders to meet local content thresholds and grid code compliance that filter out undercapitalized entrants. Stakeholders must monitor how Oman's green hydrogen ambitions redirect gas allocations and transmission planning priorities.
Market Dynamics
OPWP's competitive tender framework is redirecting capital toward integrated water-power complexes as gas allocation constraints tighten feedstock availability for conventional thermal plants.
Growth Catalysts
- Renewable Quota Mandates:AER-enforced procurement targets are accelerating solar PV and wind capacity additions ahead of open-cycle gas economics.
- Industrial Desalination Scaling:Coastal complexes at Sohar and Salalah are bundling electricity offtake with water production, creating anchor demand for new generation.
- Dhofar Wind Resource Clustering:Coastal wind velocities and port-linked industrial zones are concentrating power-intensive activity in the southern governorate.
Market Restraints
- Gas Feedstock Volatility:Domestic natural gas allocation priority for green hydrogen export projects is constraining thermal plant fuel security.
- Grid Code Compliance Burden:AER technical standards for frequency response and voltage regulation filter out undercapitalized independent power producer entrants.
- Transmission Bottlenecks:132 kV to 400 kV interconnection gaps between northern load centers and southern renewable zones limit resource dispatch.
Strategic Opportunities
- Green Hydrogen Power Integration:Electrolyzer load profiles create flexible demand that can absorb surplus renewable generation and stabilize grid frequency.
- Rural Electrification Extension:Mazoon Electricity Distribution Company's Al Batinah and Al Dakhiliyah programs offer modular microgrid deployment channels.
- Hybrid Storage Convergence:Battery co-location with solar PV is compressing evening peak pricing and displacing gas turbine cycling duty.
Industry Challenges
- Specialized Technician Scarcity:Grid code compliance and renewable inverter maintenance require skills absent from traditional thermal plant workforces.
- Integrated Project Complexity:Water-power-steam bundling demands cross-disciplinary engineering coordination that stretches EPC contractor capabilities.
- Legacy Asset Stranding Risk:Carbon intensity regulations threaten residual value of existing open-cycle gas plants before debt retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Power Market |
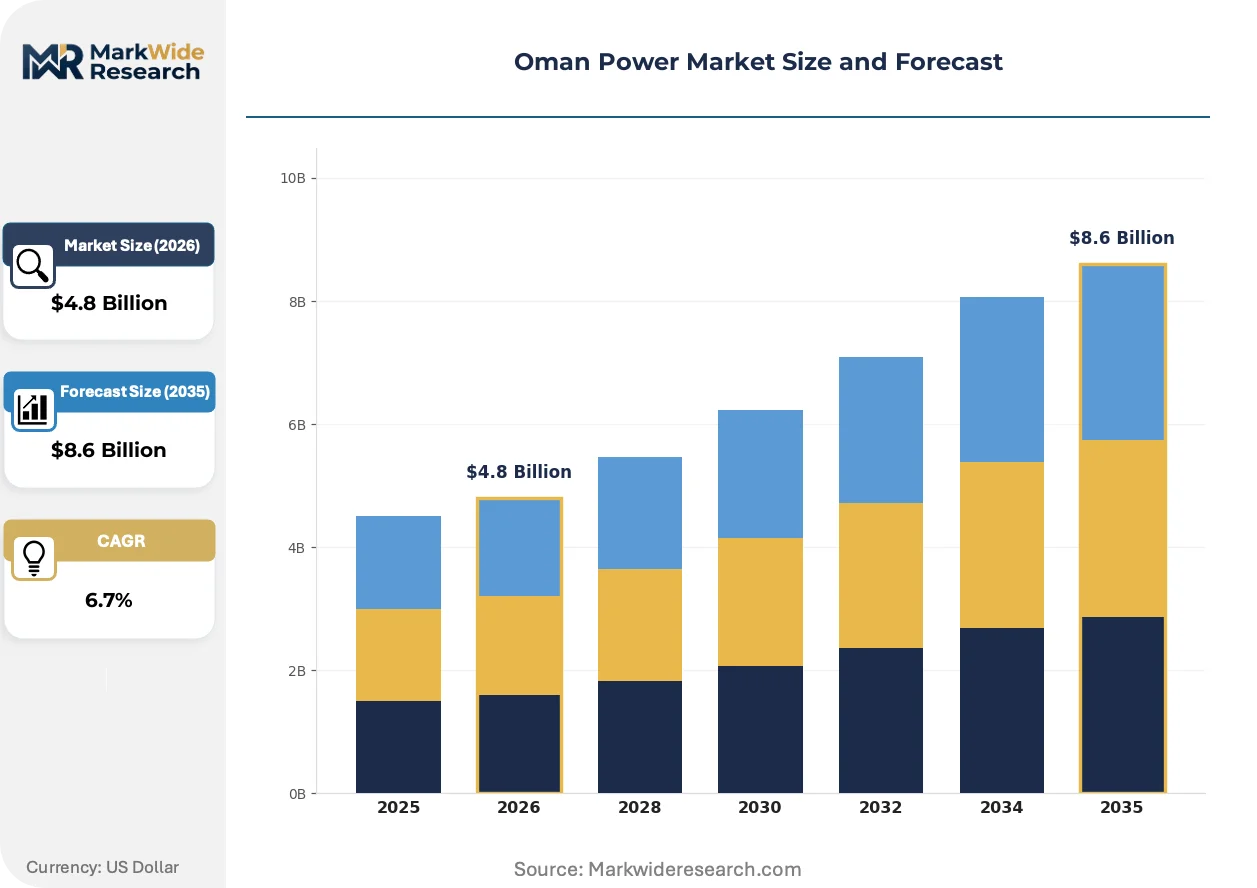
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Thermal Power, Hydropower, Nuclear Energy Technology: Solar PV, Wind Turbines, Gas Turbines, Biomass End User: Commercial, Industrial, Residential, Utilities Installation: Onshore, Offshore, Grid-Connected, Off-Grid |
| Companies Covered | Majan Electricity Distribution Company (SAOC), ACWA Power, Mazoon Electricity Distribution Company, Oman Power & Water Procurement Company (OPWP), Sohar Power Company SAOG, Oman Electricity Transmission Company (SAOC), Dhofar Power Company (DGC), United Power Company (SAOC), Muscat Electricity Distribution Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Power Market Evolving Landscape
Solar PV technology is compressing thermal plant margins while regulatory pressure on carbon intensity rewrites procurement criteria across Oman's power sector.
Bifacial solar modules with tracking systems are consolidating utility-scale project economics in Dhofar and Al Wusta governorates. IPP developers are specifying these configurations in OPWP tender responses to undercut levelized costs of gas alternatives. The technology is consolidating market share in new capacity allocations and forcing thermal incumbents into flexibility-service pricing.
AER's competitive procurement framework now embeds local content thresholds and grid code compliance standards that filter bidder pools. These requirements extend project development timelines but raise technical performance benchmarks for frequency regulation. Industrial offtakers in Sohar Port are responding by pre-qualifying suppliers against AER standards before tender participation.
Power purchase agreement structures are unbundling capacity payments from energy charges to reward dispatch flexibility. Industrial buyers in Salalah Free Zone are negotiating contracts that penalize inflexible thermal output and reward renewable-plus-storage combinations. This restructuring is most visible in Dhofar Governorate, where port-linked desalination complexes prioritize variable-cost indexed supply over baseload commitments.
Oman Power Market Segmentation
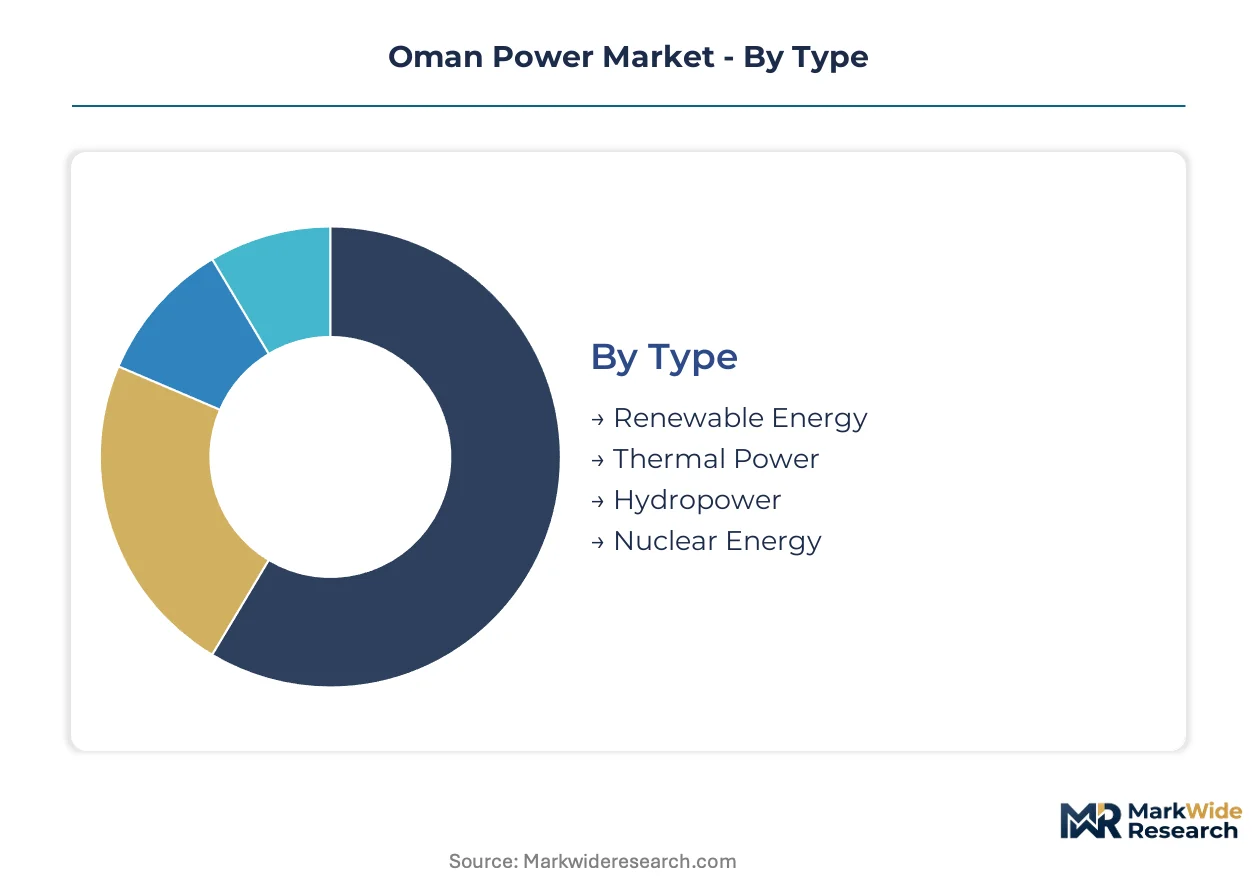
Oman's power market segmentation reveals how technology cycles and infrastructure maturity create divergent investment profiles across generation types. Each category maps distinct upgrade timelines and procurement patterns that shape OPWP's capacity planning decisions.
Type:
Replacement cycles in Oman's generation fleet are accelerating as carbon intensity regulations compress residual value of aging thermal assets.
- Renewable Energy:Solar PV and wind installations operate with 25-year asset lives and minimal fuel exposure. Dhofar Governorate's coastal wind corridors and Al Wusta's solar zones concentrate new procurement under AER quota mandates.
- Thermal Power:Combined-cycle and open-cycle gas plants provide frequency response and evening peak coverage. Gas allocation constraints for green hydrogen exports are forcing earlier-than-planned retirement evaluations for baseload units.
- Hydropower:Limited to small run-of-river installations in Al Dakhiliyah's wadi systems. Seasonal flow variability restricts capacity factors below utility-scale viability thresholds.
- Nuclear Energy:No operational capacity exists; policy discussions remain exploratory with no committed development timeline.
Renewable Energy sits at the top of the volume ranking, with Thermal Power facing the steepest replacement pressure.
Technology:
Cost tier differentiation separates utility-scale solar from flexibility-premium gas turbine solutions in OPWP tender responses.
- Solar PV:Bifacial modules with single-axis tracking dominate new capacity allocations. Levelized costs below open-cycle gas alternatives are consolidating market share in Dhofar and Al Wusta governorates.
- Wind Turbines:Coastal installations at Salalah and Duqm exploit sustained wind velocities. Grid code compliance requirements for frequency regulation filter out undercapitalized developers.
- Gas Turbines:Aeroderivative units provide daily cycling to balance intermittent renewable output. Margins compress as capacity payments unbundle from energy charges in industrial offtake contracts.
- Biomass:Agricultural residue feedstocks from Al Batinah's date palm operations support small distributed generation. Scale limitations prevent utility-scale deployment.
Solar PV commands the largest share of new capacity additions, with Wind Turbines expanding most quickly in coastal zones.
End User:
Application-specific load profiles determine tariff structures and contract duration across Oman's customer segments.
- Industrial:Desalination complexes at Sohar Port and Salalah Free Zone bundle water-power-steam offtake. Variable-cost indexed supply contracts are displacing baseload commitments.
- Commercial:Retail and hospitality loads in Muscat Governorate drive summer peak demand forty percent above winter baselines. Time-of-use pricing structures shape consumption patterns.
- Residential:Subsidized tariffs in rural Al Dakhiliyah and Al Batinah governorates sustain Mazoon Electricity Distribution Company's grid extension programs.
- Utilities:OPWP's central procurement aggregates capacity for system-wide dispatch. Competitive tenders emphasize integrated water-power solutions.
Industrial offtake leads absolute consumption volumes, with Commercial demand showing the steepest tariff sensitivity.
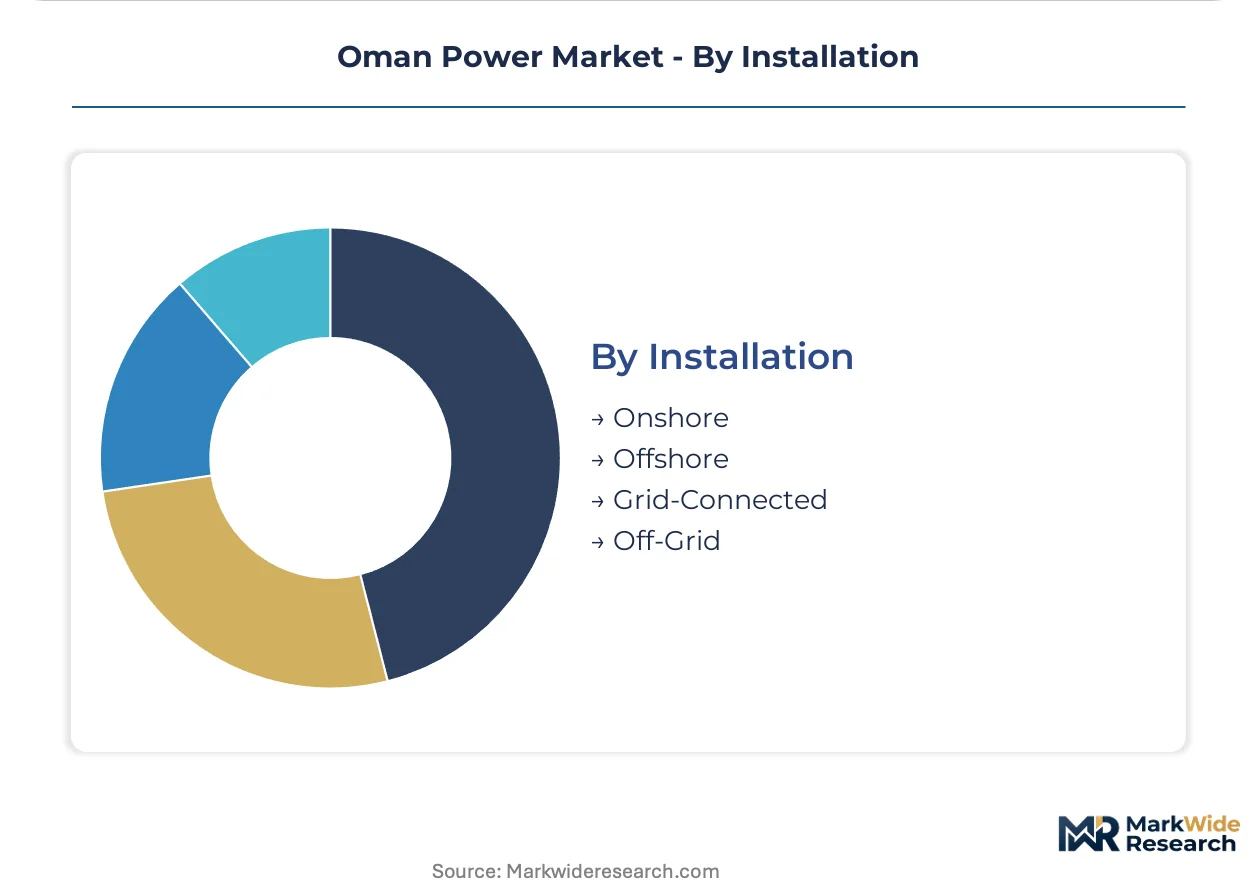
Installation:
Geography and grid connectivity determine project economics and regulatory treatment across Oman's territory.
- Onshore:Utility-scale solar and wind installations dominate new capacity. Land availability in Al Wusta and Dhofar supports gigawatt-scale project development.
- Offshore:No operational capacity; seabed depth and cyclone exposure complicate feasibility. Early-stage studies examine floating wind potential.
- Grid-Connected:132 kV to 400 kV interconnection enables central dispatch from northern load centers. Transmission bottlenecks to southern renewable zones limit resource utilization.
- Off-Grid:Diesel-battery hybrid systems serve remote settlements in Al Wusta and Dhofar's interior. Mazoon's rural electrification programs prioritize grid extension where economically viable.
Grid-Connected installations absorb the majority of capital deployment, with Off-Grid solutions addressing final-mile coverage gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman's power sector traces its modern expansion to the 1970s rural electrification programs that established the national grid backbone. The current landscape reflects decades of centralized planning now pivoting toward competitive procurement and renewable integration.
Muscat Governorate
Commercial and residential loads concentrate in the capital region, where summer air conditioning drives peak demand forty percent above winter baselines. The Authority for Electricity Regulation enforces time-of-use tariffs that shape consumption patterns across retail and hospitality sectors. Muscat Electricity Distribution Company manages dense urban networks where grid stability requirements filter technology choices.
Dhofar Governorate
Coastal wind resources and port-linked industrial zones cluster power-intensive desalination and manufacturing activity in the southern region. AER-mandated renewable quotas accelerate solar PV and wind procurement ahead of conventional thermal economics. Salalah Free Zone anchors variable-cost indexed supply contracts that penalize inflexible baseload commitments.
Al Batinah Governorate
Agricultural processing and expanding residential settlements sustain rural electrification demand across Oman's northern coastal plain. Mazoon Electricity Distribution Company extends 132 kV interconnections to replace diesel-battery hybrid systems in remote settlements. Sohar Port's integrated water-power-steam complexes bundle industrial offtake that reshapes procurement priorities.
Al Wusta Governorate
Vast land availability supports gigawatt-scale solar PV development with bifacial tracking configurations dominating utility-scale allocations. OPWP's competitive tenders emphasize grid code compliance that filters undercapitalized developers from project participation. Duqm Special Economic Zone concentrates new generation capacity to serve port-linked industrialization.
Al Dakhiliyah Governorate
Small run-of-river hydropower installations exploit wadi systems with seasonal flow variability restricting capacity factors. Mazoon's grid extension programs prioritize economically viable interconnection over off-grid diesel alternatives in mountainous terrain. Traditional agricultural communities sustain distributed generation demand from date palm residue biomass systems.
Oman Power Market Competitive Landscape
The competitive structure tilts toward state-linked utilities and international independent power producers bidding through OPWP's tender framework. Procurement concentration around integrated water-power complexes favors developers with multi-asset construction track records. Two archetypes dominate: Gulf-based IPPs leveraging regional project finance relationships, and established Omani distribution utilities with captive grid access. Competitive moves center on consortia formation for tender participation and backward integration into engineering procurement construction capabilities.
Among Saudi Arabia-linked developers, ACWA Power occupies a position exemplifying the Gulf-based IPP archetype with renewable-plus-desalination bundling expertise. Within Omani state-linked utilities, Majan Electricity Distribution Company and Mazoon Electricity Distribution Company represent the established distribution tier with rural electrification mandates and grid extension programs. Dhofar Power Company anchors southern generation capacity under the regional utility model. These entities collectively illustrate how procurement centralization through OPWP channels competitive positioning toward integrated solution delivery.
| Leading Market Players |
|---|
| Majan Electricity Distribution Company (SAOC) |
| ACWA Power |
| Mazoon Electricity Distribution Company |
| Oman Power & Water Procurement Company (OPWP) |
| Sohar Power Company SAOG |
| Oman Electricity Transmission Company (SAOC) |
| Dhofar Power Company (DGC) |
| United Power Company (SAOC) |
| Muscat Electricity Distribution Company |
| Others |
Value Network & Pricing Analysis
OPWP's centralized procurement concentrates buyer power among industrial offtakers at Sohar Port and Salalah Free Zone, anchoring long-term power purchase agreements that unbundle capacity payments from energy charges to reward dispatch flexibility.
Pricing Analysis
Long-term offtake contracts with variable-cost indexing dominate procurement structures for desalination and industrial complexes. Price differentiation rests on dispatch flexibility and renewable energy bundling rather than baseload guarantees. Cost compression in thermal generation is intensifying because carbon intensity regulations compress residual value of open-cycle gas assets. Industrial offtakers in Dhofar Governorate exhibit highest price sensitivity, while utilities accepting system-wide dispatch obligations show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturing for bifacial solar modules and inverter electronics. Equipment sourcing draws from China, South Korea, and Germany for turbine and balance-of-system components. Raw material dependencies include polysilicon, rare earth magnets, and high-grade steel forgings. Tariff exposure on solar module imports complicates project economics. Distribution runs through EPC contractors with integrated construction capabilities serving OPWP tender requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's power sector offers margin expansion through renewable-plus-storage bundling as levelized costs fall below thermal alternatives and industrial buyers prioritize flexible procurement structures.
For Market Incumbents: Anchor competitive position through backward integration into engineering procurement construction capabilities for integrated water-power complexes. Defend against Gulf-based IPP entrants by locking in long-term fuel supply agreements before green hydrogen export projects divert gas allocations. Prioritize grid code compliance investments that filter undercapitalized competitors from OPWP tenders. For New Entrants and Emerging Players: Begin with modular microgrid deployment in Mazoon Electricity Distribution Company's Al Batinah and Al Dakhiliyah rural electrification programs. Target off-grid diesel replacement segments where grid extension economics remain marginal. Pursue joint venture structures with established Omani distribution utilities to secure grid interconnection access. For Investors and Strategic Acquirers: Gulf sovereign wealth funds and Saudi-linked developers are the most active acquirers in this space, consolidating renewable-plus-desalination bundling expertise. Acquisition targets should exhibit multi-asset construction track records and competitive tender participation history. Watch for AER renewable quota mandate acceleration as inflection indicator for capacity planning priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable-Plus-Storage Bundling | Compresses evening peak pricing and displaces gas turbine cycling duty in Dhofar. |
| Integrated Water-Power Complex Development | Aligns with OPWP tender priorities at Sohar Port and Salalah Free Zone. |
| Grid Code Compliance Certification | Filters undercapitalized entrants from AER-mandated competitive procurement. |
| Backward Integration into EPC Capabilities | Captures construction margin and accelerates project development timelines. |
| Green Hydrogen Power Integration | Creates flexible electrolyzer demand that absorbs surplus renewable generation. |
Research Methodology
Coverage spans Muscat, Dhofar, Al Batinah, Al Wusta, and Al Dakhiliyah governorates, with primary inputs from each. The approach combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from OPWP tender documents, AER regulatory filings, and IEA regional power sector reports. Bottom-up capacity addition tracking and top-down demand forecasting provide triangulation across data sources.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include generation type, technology configuration, end-user category, and grid connectivity status. CAGRs derive from capacity addition pipelines, demand elasticity estimates, and regulatory mandate trajectories. Industry-specific inputs incorporate solar irradiance data for Al Wusta and wind velocity measurements for Dhofar coastal zones.
Several conditions sit outside the modeled scope, including unannounced policy shifts in green hydrogen export priorities and unforeseen transmission infrastructure delays. Forecasts reflect assumptions about AER quota enforcement continuity and OPWP tender schedule adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Wind Power EPC Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Canada Power EPC Market
Power Generation
Captive Power Generation Market
Power Generation
North America Distributed Power Generation Market
Power Generation
South America Thermal Power Market
Power Generation
Global Power Grid System Market
Power Generation
Venezuela Power Market
Power Generation
Global Power Generation Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Power Generation Technologies Market
Power Generation
Marine Power Plant Market
Power Generation
Variable Speed Generator Market
Power Generation
Coal Fired Power Generation Market
Power Generation
India Gensets Market
Power Generation
Algeria Power Market