
 Mobile Point of Sale (POS) Market | 2026-2036
Mobile Point of Sale (POS) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Point of Sale (POS) Market Intelligence
Small boutiques and solo freelancers are unwinding the historical dominance of fixed-location retail in mobile POS procurement. Square (Block, Inc.) leverages its integrated software-hardware stack to anchor seller ecosystems across fragmented merchant categories. Toast competes through restaurant-specialized workflows that extend beyond pure payment acceptance into order management and kitchen display systems.
A mobile point of sale system comprises portable hardware terminals, card readers, or consumer-grade smartphones and tablets paired with cloud-native software to process card, NFC, and digital wallet transactions at variable locations. These systems typically integrate EMV chip authentication, Bluetooth or 4G LTE connectivity, and PCI-DSS-validated encryption to secure cardholder data during transit. Card reader and smartphone-based deployments dominate transaction volume due to minimal capital outlay, while cloud-based technology architectures capture expanding margin pools through recurring software fees rather than one-time hardware sales.
The Federal Trade Commission enforces data security standards that shape vendor liability frameworks in the United States, while the European Banking Authority's PSD2 strong customer authentication rules dictate multi-factor login requirements for EU-deployed mobile POS applications. India's Reserve Bank India issues tokenization mandates that constrain how card data traverses domestic mobile payment infrastructure. Stakeholders must monitor evolving interoperability standards between proprietary closed-loop wallets and open banking protocols to preserve transaction routing flexibility.
Market Dynamics
PCI DSS compliance deadlines and EMV contactless mandates are forcing hardware vendors to redesign certification pathways before legacy devices lose network acceptance. Food truck operators and pop-up retailers now drive procurement volumes that previously flowed to fixed-location terminals.
Growth Catalysts
- FTC data security enforcement:The Federal Trade Commission's liability frameworks push vendors toward PCI-DSS-validated encryption architectures. Merchant acquirers now bundle compliance services with terminal leases.
- Cloud-native software stacks:Recurring SaaS fees displace one-time hardware margins. Toast and Square anchor seller ecosystems through integrated order management.
- India's tokenization infrastructure:The Reserve Bank of India's domestic card-data rules expand addressable merchant bases for locally certified terminals.
Market Restraints
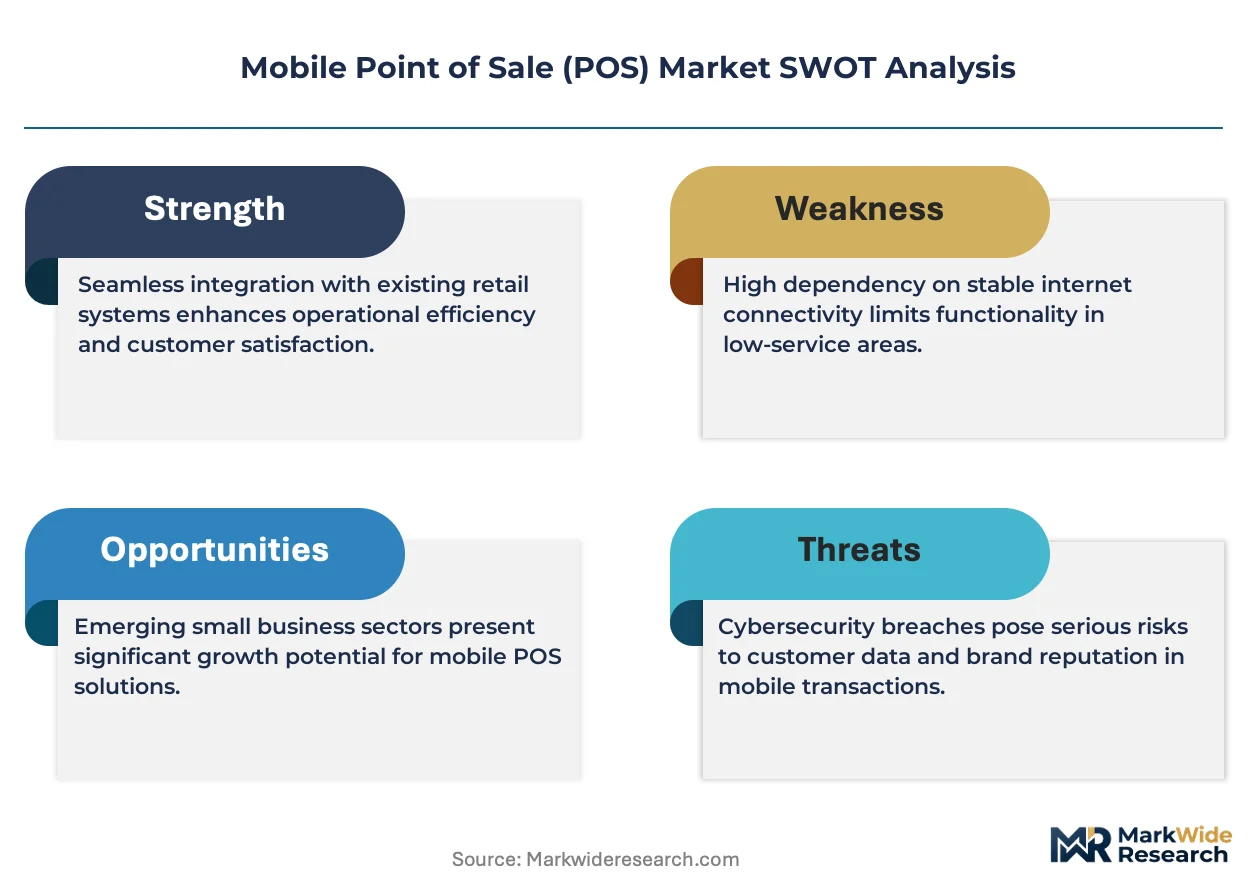
- Semiconductor supply concentration:Taiwan-based chip fabrication creates vulnerability for NFC controller availability. Lead times for EMV-certified chipsets extend procurement cycles.
- PSD2 authentication friction:The European Banking Authority's multi-factor login requirements add latency to EU-deployed applications. Small merchants abandon checkout flows with excessive steps.
- Smartphone substitution threat:Consumer-grade iOS and Android devices with soft-POS apps compress demand for dedicated hardware terminals.
Strategic Opportunities
- Indonesia's underpenetrated archipelago:Island logistics and limited banking infrastructure create whitespace for 4G LTE-enabled portable terminals. Local fintech partnerships bypass traditional acquirer networks.
- Kitchen display convergence:Mobile POS integration with KDS and inventory systems captures restaurant back-of-house workflows. Hardware vendors bundle thermal printers and label makers.
- India's PLI scheme for electronics:Production-linked incentives for domestic manufacturing reduce import duties on certified terminals. Local assembly cuts landed cost for price-sensitive merchants.
Industry Challenges
- EMV certification timeline compression:Major card networks accelerate deprecation schedules for magnetic-stripe-only devices. Vendors must recertify hardware variants across multiple laboratory test houses simultaneously.
- Legacy ERP integration complexity:Mid-market retailers run on-premise Oracle and SAP systems that resist cloud-native POS APIs. Middleware development consumes implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Point of Sale (POS) Market |
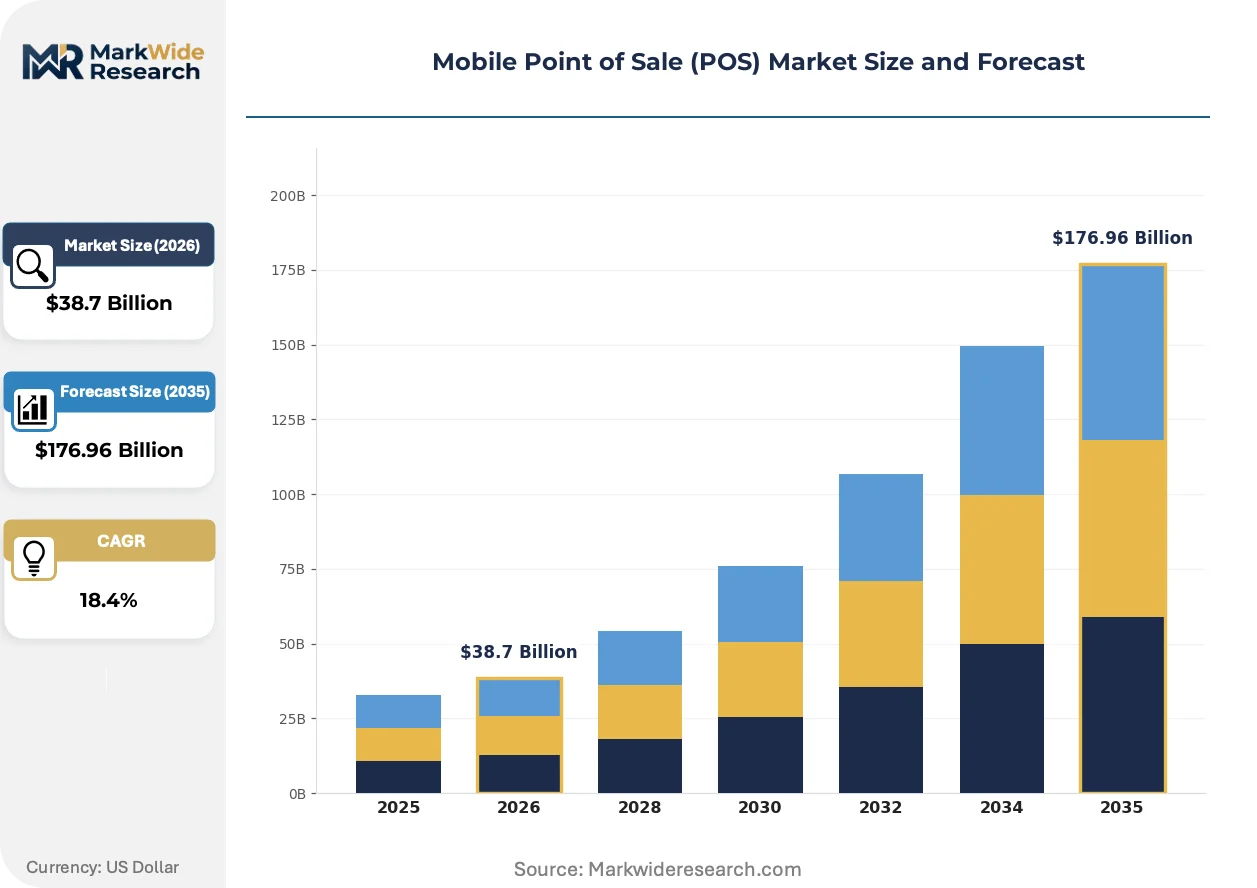
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
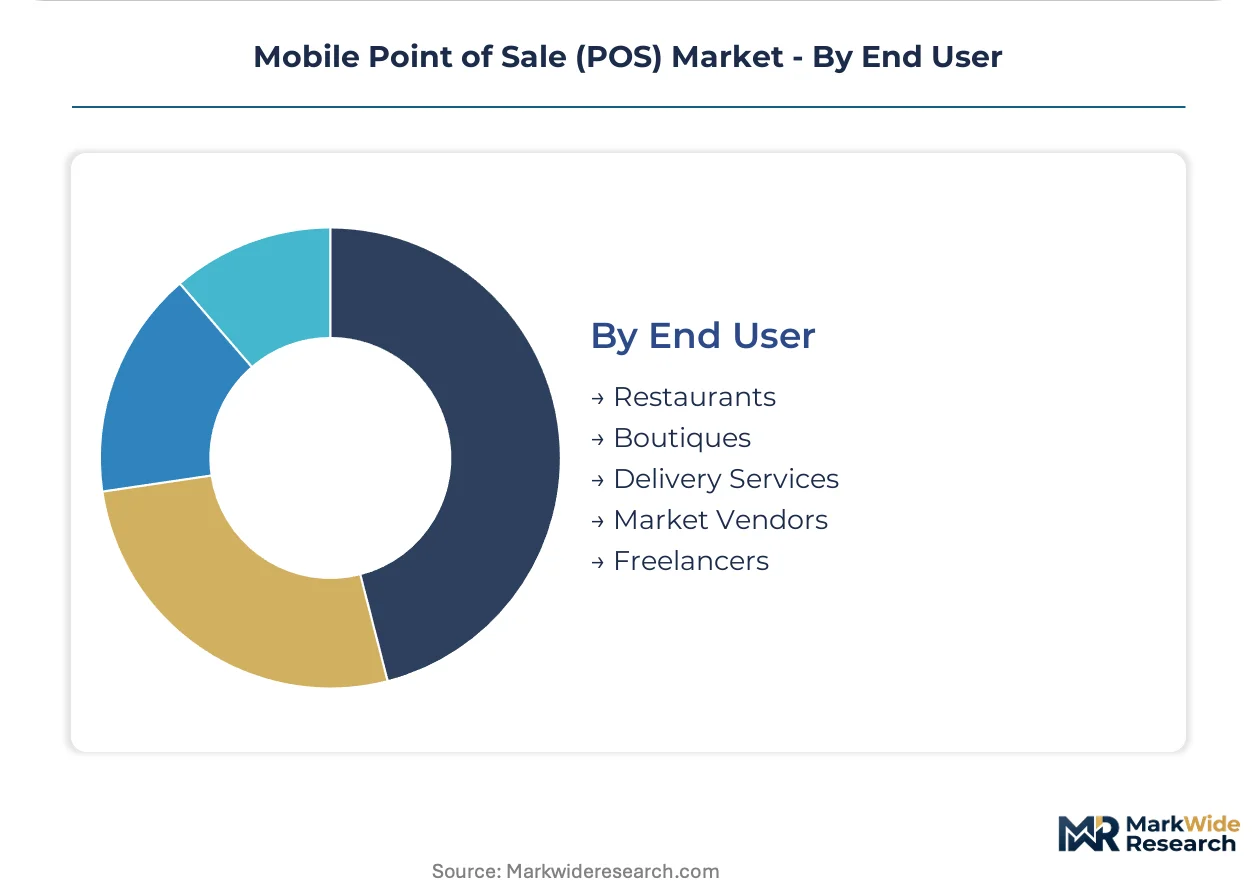
| Segmentation | Product Type: Smartphones, Tablets, Card Readers, Portable Printers, Mobile POS Terminals Technology: Bluetooth, NFC, Wi-Fi, 4G LTE, EMV Chip, Cloud-Based Application: Food Trucks, Event Ticketing, Mobile Retail, On-Demand Services, Field Sales End User: Restaurants, Boutiques, Delivery Services, Market Vendors, Freelancers |
| Companies Covered | Square (Block, Inc.), Fiserv (Clover), Verifone, PAX Technology, Ingenico, Toast, Lightspeed Commerce, Newland Payment, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Point of Sale (POS) Market Strategic Shifts & Innovations
Hardware form factors and authentication protocols are converging around biometric verification and soft-POS deployment. Vendors race to embed fingerprint sensors and facial recognition into terminals before network operators mandate stronger cardholder verification.
Biometric cardholder verification is miniaturizing. Fingerprint sensors now embed into compact Bluetooth card readers without expanding chassis dimensions. Food truck operators and market stall vendors adopt these devices for line-speed throughput. The technology is miniaturizing security hardware into accessories that pair with merchant smartphones.
The European Banking Authority's PSD2 strong customer authentication rules now extend to unattended terminals and vending integrations. Issuers decline transactions lacking biometric or PIN verification for purchases above contactless limits. Restaurant chains and petrol retailers in Germany and France accelerate replacement of signature-capture devices.
Merchant acquisition patterns are fragmenting across vertical-specialized software platforms. Boutique fitness studios and salon operators now select POS providers based on scheduling and membership management features rather than payment rates alone. This behavior concentrates in the United States and United Kingdom where SaaS-embedded finance has matured.
Mobile Point of Sale (POS) Market Segmentation
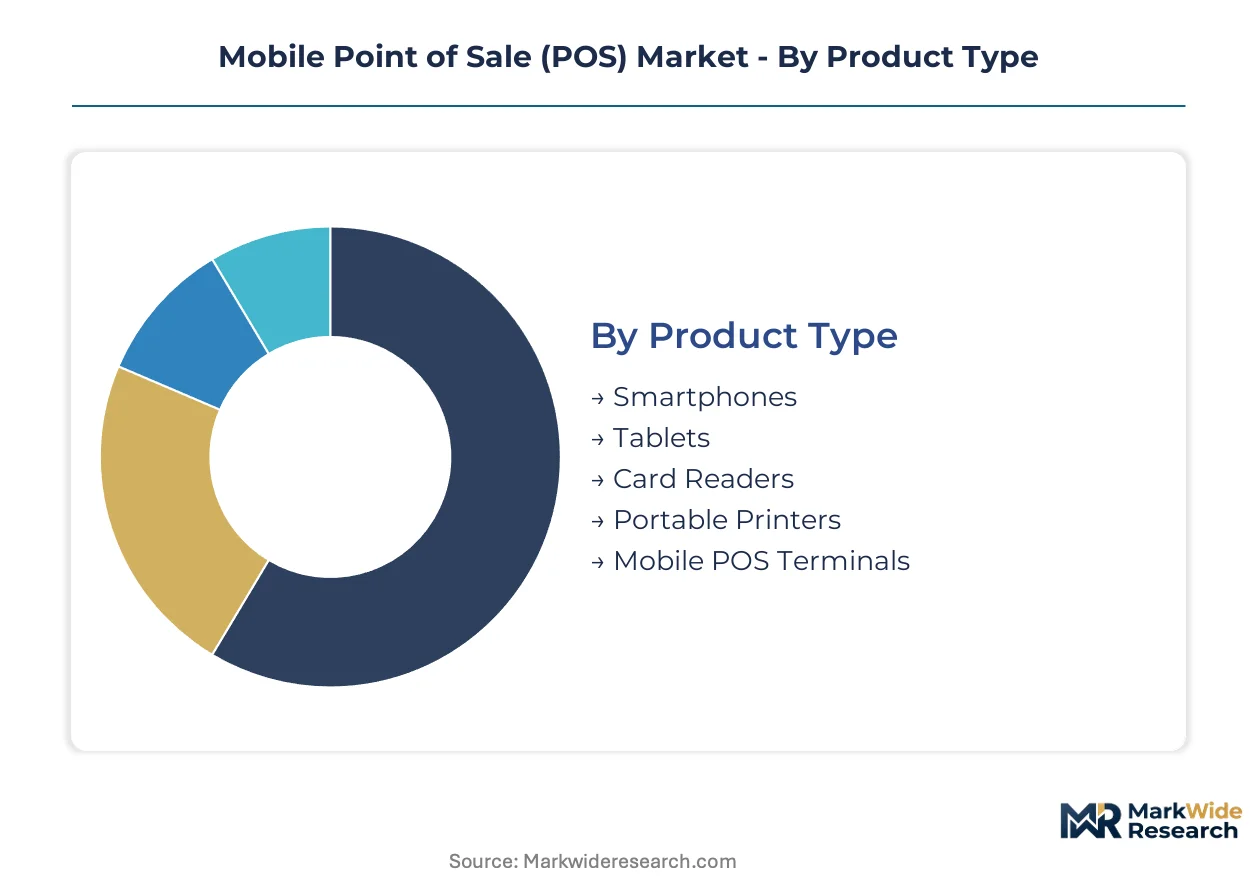
Mobile POS procurement channels diverge sharply by merchant sophistication and transaction velocity. Hardware vendors calibrate distribution strategies around capital constraints, connectivity requirements, and vertical-specific workflow integration.
Product Type:
Channel mix varies by upfront capital tolerance and mobility requirements, with smartphone-based deployments flowing through carrier partnerships while dedicated terminals move through acquirer leasing programs.
- Smartphones:Consumer-grade iOS and Android devices paired with soft-POS applications eliminate hardware procurement entirely. Demand concentrates among Indian street vendors and US gig-economy freelancers where capital constraints block dedicated terminal adoption.
- Card Readers:Compact Bluetooth peripherals with EMV-NFC dual capability authenticate transactions while offloading display and connectivity to paired phones. Food truck operators in Texas and California drive volume for line-speed portability.
- Tablets:Larger screens support menu browsing and signature capture for seated service environments. Boutique retailers in Paris and Milan favor this form factor for customer-facing interaction.
- Portable Printers:Battery-powered thermal units generate physical receipts for regulatory compliance or customer preference. German petrol stations and French market stalls require these for tax documentation.
- Mobile POS Terminals:All-in-one devices with integrated printers, displays, and payment modules serve high-volume mobile merchants. Indian quick-service restaurants and Indonesian island retailers adopt these for standalone operation.
Card readers dominate installed base. Mobile POS terminals are where expansion concentrates.
Technology:
Cost tier stratification separates premium connectivity stacks from commodity authentication modules, with cloud-native architectures capturing recurring revenue pools that hardware-centric technologies cannot access.
- Bluetooth:Short-range pairing between card readers and merchant smartphones minimizes power consumption and hardware cost. Market vendors in Indonesia and Philippines rely on this for intermittent connectivity in archipelago logistics.
- NFC:Contactless card and wallet authentication at sub-100 millisecond latency enables tap-to-pay throughput. European PSD2 mandates accelerate replacement of signature-based devices in Germany and France.
- Wi-Fi:High-bandwidth connectivity supports cloud synchronization of transaction data and inventory updates. US coffee chains and UK co-working spaces deploy this for reliable indoor coverage.
- 4G LTE:Cellular connectivity untethers merchants from fixed infrastructure for true mobility. Indian food trucks and Brazilian pop-up retailers require this for variable location operation.
- EMV Chip:Chip-card authentication protocols mandated by major networks for liability shift compliance. Certification timelines constrain vendor release cycles across all hardware categories.
- Cloud-Based:Software architectures delivering SaaS fee structures displace one-time hardware margins. Toast and Square anchor restaurant ecosystems through integrated order management and kitchen display convergence.
EMV chip authentication underpins network acceptance. Cloud-based delivery is climbing the fastest as vendors pivot to recurring revenue models.
Application:
Volume concentration tracks merchant mobility patterns, with fixed-location applications ceding share to variable-location use cases that legacy terminals cannot serve.
- Food Trucks:High-velocity order environments demand line-speed payment acceptance with offline transaction caching. Operators in Austin, Portland, and Mumbai represent the core addressable base for portable terminal vendors.
- Mobile Retail:Pop-up boutiques and seasonal market stalls require rapid deployment without infrastructure installation. UK high-street traders and US craft fair vendors drive seasonal procurement spikes.
- Event Ticketing:Temporary admission environments with time-gated entry windows need queue-optimized throughput. Stadium operators in Brazil and India favor rental models for tournament-duration deployment.
- On-Demand Services:Ride-hailing and delivery drivers accept payment at customer locations without fixed terminals. Indonesian Gojek drivers and US DoorDash couriers rely on smartphone-based acceptance.
- Field Sales:B2B representatives process orders at client sites with immediate payment authorization. German industrial distributors and Indian pharmaceutical reps require signature capture and receipt generation.
Food trucks anchor current deployment volume. On-demand services represent the steepest expansion trajectory as gig platforms embed payment infrastructure.
End User:
Customer type determines feature prioritization, with restaurants demanding kitchen integration while freelancers minimize capital outlay.
- Restaurants:Full-service and quick-service operators require order management, kitchen display system integration, and tip adjustment workflows. Toast captures this segment through specialized software stacks in the US.
- Boutiques:Small apparel and specialty retailers prioritize inventory synchronization and customer relationship management over pure payment rates. Paris fashion retailers and Tokyo design shops select platforms based on aesthetic alignment.
- Delivery Services:Third-party logistics providers need driver-mounted acceptance with route optimization and cash management. Indian Swiggy and Zomato fleets drive demand for ruggedized smartphone peripherals.
- Market Vendors:Informal and semi-formal traders in developing economies require low-cost entry with minimal documentation. Nigerian open-air markets and Indian bazaars adopt basic card readers through fintech partnerships.
- Freelancers:Solo professionals invoice and accept payment for project-based work without fixed business premises. UK consultants and US creative contractors favor smartphone apps with instant settlement.
Restaurants command the highest software attach rates. Freelancers are gaining share fastest as sole proprietorship expands across developed economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense 4G LTE coverage and cloud data center infrastructure underwrites North American dominance in mobile-first commerce deployment. Merchant adoption concentrates where cellular backbone density supports variable-location transaction processing.
United States
Food truck clusters in Austin and Portland drive portable terminal procurement volumes. The FTC enforces data security standards that shape vendor liability frameworks across merchant acquirer networks. Square and Toast anchor seller ecosystems through integrated software-hardware stacks in major metropolitan corridors.
China
MIIT's telecommunications infrastructure standards accelerate 5G-enabled soft-POS deployment among street vendors and delivery fleets. Zhejiang and Guangdong provinces concentrate manufacturing capacity for Bluetooth card reader peripherals. Shenzhen-based terminal producers supply domestic quick-service restaurant chains.
India
The Reserve Bank of India's tokenization mandates expand addressable merchant bases for locally certified terminals. Maharashtra and Karnataka street vendors adopt basic smartphone-based acceptance through fintech partnerships. The PLI scheme for electronics manufacturing reduces import duties on certified devices.
Germany
The European Banking Authority's PSD2 strong customer authentication rules accelerate replacement of signature-capture devices in restaurant chains. Bavaria and North Rhine-Westphalia petrol retailers deploy biometric-enabled terminals for unattended payment environments. Frankfurt's financial infrastructure supports acquirer network consolidation.
Indonesia
Island logistics and limited banking infrastructure across the archipelago create whitespace for 4G LTE-enabled portable terminals. Jakarta and Surabaya fintech partnerships bypass traditional acquirer networks for market vendor onboarding. Local assembly operations cut landed costs for price-sensitive merchants.
Mobile Point of Sale (POS) Market Key Industry Players
Concentration sits with integrated software-hardware stacks that anchor seller ecosystems across fragmented merchant categories. The vendor base spans payment network incumbents, cloud-native platform specialists, and Asian hardware fabricators. Two strategic archetypes dominate: vertical-integrated ecosystem builders and restaurant-specialized workflow providers. Competitive moves center on kitchen display system convergence and strategic fintech partnerships for emerging market penetration.
Among the ecosystem-builder tier, Square (Block, Inc.) exemplifies the integrated software-hardware archetype through its seller platform spanning fragmented merchant categories. Toast occupies a position within the vertical-specialized tier, representing restaurant-focused workflow integration beyond pure payment acceptance. Fiserv (Clover) sits within the financial infrastructure tier, anchoring acquirer-integrated terminal distribution.
| Leading Market Players |
|---|
| Square (Block, Inc.) |
| Fiserv (Clover) |
| Verifone |
| PAX Technology |
| Ingenico |
| Toast |
| Lightspeed Commerce |
| Newland Payment |
| Panasonic Holdings Corporation |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with Taiwan-based semiconductor foundries lock in NFC controller supply for terminal vendors while capping price volatility exposure. These arrangements tether hardware procurement costs to wafer allocation schedules rather than spot-market chip pricing, compressing margin flexibility for vendors serving price-sensitive Indian street vendors.
Pricing Analysis
Volume-discount tiering structures stratify across three performance levels: premium terminals with integrated biometric sensors, standard EMV-NFC devices, and economy Bluetooth card readers. Certification grade serves as the primary price differentiation driver, with PCI DSS Level 1 validation commanding substantial premiums over basic EMV compliance. Cost compression in the economy tier is intensifying because Indian fintech partnerships are subsidizing terminal deployment for merchant acquisition. Freelancers and solo proprietors exhibit the highest price sensitivity, while restaurant chains prioritize kitchen integration features over per-unit hardware costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate among US and European terminal assemblers, while Chinese manufacturers maintain strategic stockpiles of EMV-certified chipsets to buffer certification timeline volatility. Supply concentration rests on Taiwan for NFC controllers, China for PCB fabrication and final assembly, and South Korea for memory components. Raw material dependencies include silicon wafers, lithium-ion battery cells, and thermal receipt paper. Single-source vulnerability in Taiwan-based chip fabrication creates procurement risk. Distribution runs through acquirer leasing programs in developed markets and fintech direct channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-based soft-POS applications threaten dedicated hardware terminal demand, forcing incumbents to defend through ecosystem lock-in and workflow integration beyond pure payment acceptance.
For Market Incumbents: Consolidate seller ecosystems by deepening software-hardware integration into kitchen display systems and inventory management. Acquire or partner with vertical-specific SaaS providers in fitness and salon management to preempt platform substitution. Channel control through exclusive acquirer relationships defends against fintech disintermediation in emerging markets. For New Entrants and Emerging Players: EMV certification fast-tracks through accredited test houses in India and Indonesia unlock addressable merchant bases ahead of incumbent localization. Target Indonesian archipelago logistics providers with 4G LTE-enabled portable terminals bundled with local fintech onboarding. Partner with domestic electronics manufacturers under India's PLI scheme to neutralize import duty cost disadvantages. For Investors and Strategic Acquirers: Capital is best deployed toward vertical-integrated ecosystem builders with demonstrated SaaS attach rates above hardware-centric vendors. Long-term viability hinges on recurring revenue share expansion rather than terminal shipment volume. Watch for biometric authentication mandate announcements from European and Asian card networks as inflection signals for premium hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Display System Integration | Toast and Square anchor restaurant retention through order-to-kitchen workflow convergence. |
| Biometric Sensor Embedding | Fingerprint-enabled terminals preempt PSD2 strong authentication mandates in Germany and France. |
| PLI Scheme Localization | Domestic Indian assembly cuts landed costs for price-sensitive merchant segments. |
| Fintech Partnership Channels | Indonesian archipelago penetration bypasses traditional acquirer network infrastructure gaps. |
| Cloud-Native Platform Migration | Recurring SaaS fees displace one-time hardware margins across merchant categories. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with restaurant technology directors, payment processor product managers, fintech partnership leads, and terminal hardware procurement officers. Secondary validation drew from PCI Security Standards Council certification databases, Reserve Bank of India tokenization circulars, European Banking Authority PSD2 technical standards, and SEC filings of publicly traded payment platforms. Bottom-up merchant adoption modeling triangulated against top-down payment volume projections.
Across the analysis window, forecasts incorporated hardware shipment trajectories by form factor, SaaS revenue per merchant by vertical, and regional regulatory compliance deadlines. Segmentation dimensions modeled include product type, connectivity technology, application use case, and end-user sophistication tier. CAGRs were derived from logistic diffusion curves fitted to mobile-first commerce infrastructure deployment patterns, with cross-checks against cellular coverage expansion and EMV certification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained 4G LTE infrastructure rollout or accelerated EMV deprecation schedules would require recalibration. Forecasts reflect assumptions regarding fintech partnership durability and acquirer network consolidation trajectories. Revision becomes warranted when semiconductor supply concentration or regulatory authentication mandates cross thresholds that alter hardware replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Singapore Payments Market
Payments
Canada Buy Now Pay Later Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Portugal Mobile Payments Market
Payments
Global Master Card Market
Payments
Credit Card Issuance Services Market
Payments
Cyprus POS Terminals Market
Payments
Canada Gift Card and Incentive Card Market
Payments
China Prepaid Cards Market
Payments
Electronic Payment System for Transportation Market
Payments
Europe Real Time Payments Market
Payments
Australia Payments Market
Payments
Argentina Mobile Wallet Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
3D Secure Payment Authentication Market