
 China Financial Planning Software Market | 2026-2036
China Financial Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
China Financial Planning Software Market Insights
Wealth management divisions at regional commercial banks are hardening their procurement standards for integrated planning platforms. Kingdee International Software Group leverages its domestic ERP installed base to cross-sell financial planning modules. SAP SE sustains competitive relevance through localized compliance templates aligned with Chinese accounting standards. Oracle Corporation anchors its position via database-layer integration with treasury and risk systems at state-owned enterprises.
China Financial Planning Software comprises modular applications that automate budgeting cycles, cash-flow projection, regulatory reporting, and scenario analysis through algorithmic engines and multi-dimensional data models. These systems serve chief financial officers and planning departments by compressing forecast cycle times and enforcing audit-ready calculation trails. Cloud-Based deployment now captures the fastest expansion as state-backed banks pilot SaaS instances under sandbox approvals from the People's Bank of China. Budgeting and Forecasting solution types retain the largest revenue footprint, while Compliance Tracking features command premium pricing amid intensified CSRC disclosure mandates.
SAMR enforces algorithmic transparency rules that affect AI-driven forecasting modules, while the PBOC governs cross-border data flows for cloud-hosted financial tools. The CAC's data localization requirements compel vendors to maintain domestic server infrastructure or forfeit access to sensitive enterprise clients. Stakeholders must weigh the trade-off between subscription agility and captive data sovereignty as regulatory scrutiny tightens.
Market Dynamics
Wealth management divisions at regional commercial banks are hardening procurement standards for integrated planning platforms, forcing vendors to demonstrate simultaneous compliance with the Personal Information Protection Law and Data Security Law before contract award.
Growth Catalysts
- Dual carbon accounting mandates:The MIIT's emissions disclosure rules for listed enterprises require automated carbon-footprint modules within financial planning suites.
- Shanghai Lujiazui concentration:Headquarters clustering of asset management firms generates dense demand for real-time portfolio stress-testing tools.
- Cloud sandbox approvals:PBOC-supervised pilot programs at state-backed banks legitimize SaaS deployment models previously restricted to on-premise installations.
Market Restraints
- Domestic server infrastructure mandates:CAC data localization requirements compel foreign vendors to build captive data centers or exit sensitive enterprise segments.
- Algorithmic transparency compliance costs:SAMR's explainability rules for AI-driven forecasting modules force expensive model-documentation retrofits.
- Cross-border data flow restrictions:PBOC governance of cloud-hosted financial tools blocks multinational treasury consolidation for Chinese subsidiaries.
Strategic Opportunities
- Shenzhen Qianhai zone expansion:The special economic zone's fintech licensing regime attracts foreign-Chinese joint ventures seeking sandboxed market entry.
- ESG integration modules:CSRC's expanding disclosure mandates create premium pricing power for compliance-tracking feature sets.
- Scenario analysis convergence:Integration of Monte Carlo engines with climate risk datasets addresses emerging stress-testing requirements for insurance asset-liability management.
Industry Challenges
- Legacy ERP integration complexity:State-owned enterprises maintain decades-old treasury systems requiring costly middleware development for API connectivity.
- Certified actuarial talent scarcity:Qualified professionals capable of validating stochastic models under SAMR guidelines command compensation premiums that compress vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Financial Planning Software Market |
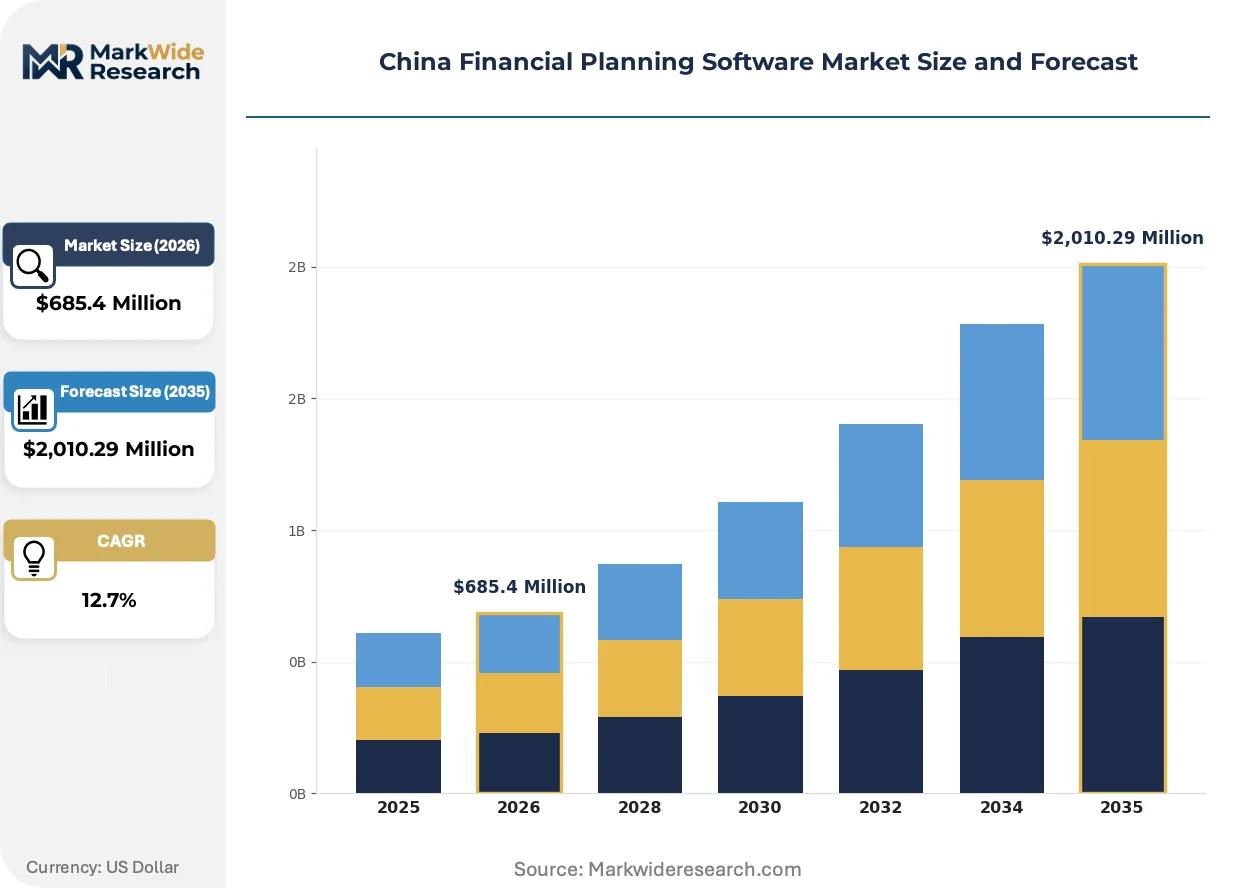
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,010.29 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Budgeting, Forecasting, Reporting, Analysis End User: SMEs, Corporations, Freelancers, Individuals Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS Feature Set: Data Integration, Risk Assessment, Compliance Tracking, Custom Reporting |
| Companies Covered | Shenzhen Sunline Tech Co. Ltd., Kingdee International Software Group, Anaplan, Workday Adaptive Planning, Oracle Corporation, SAP SE, FinAlyzer, Qvinci, Yusys Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Financial Planning Software Market Trends and Innovations
Algorithmic forecasting engines and multi-dimensional data models are compressing planning cycle times while regulatory pressure forces architectural redesigns around audit-ready calculation trails.
Cloud-native microservices architecture is modularizing core financial planning functions into independently deployable components. Regional commercial banks in Jiangsu and Zhejiang provinces are adopting these modules faster than their northern counterparts. This architectural shift is modularizing vendor competitive positioning, allowing best-of-breed point solutions to displace monolithic suites in procurement evaluations.
CSRC disclosure mandates for listed companies are tightening audit trail requirements for algorithmic calculations. Financial planning software vendors must now embed immutable logging at the calculation-cell level. Budgeting and Forecasting solution providers serving A-share listed enterprises face the steepest compliance retrofit costs.
Subscription pricing models are displacing perpetual license structures among mid-tier city commercial banks. Vendors are unbundling implementation services from software fees to accelerate customer acquisition. This behavioral shift concentrates in second-tier financial centers like Hangzhou and Chengdu where procurement autonomy exceeds Beijing-headquartered policy banks.
China Financial Planning Software Market Segmentation
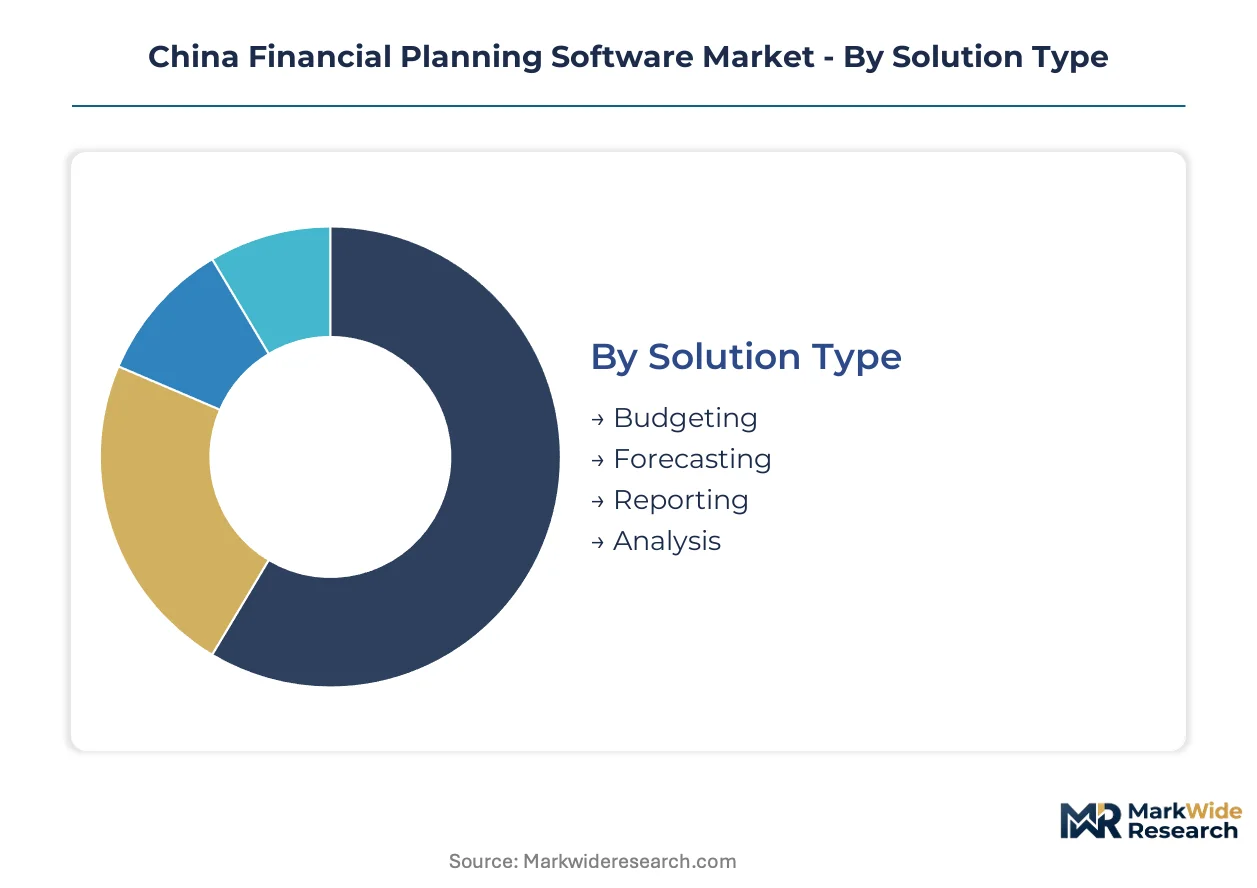
Segmentation in China's financial planning software market reveals how regulatory fragmentation and data sovereignty requirements create distinct procurement corridors. Vendors must align certification portfolios with segment-specific compliance burdens to secure contract awards.
Solution Type:
Budgeting modules require SAMR algorithmic transparency certification, while compliance-tracking features demand additional CSRC disclosure validation before deployment at listed enterprises.
- Budgeting:Core modules automate capital allocation cycles and variance analysis through multi-dimensional data models. Regional commercial banks in Jiangsu province concentrate procurement here, driven by MIIT dual carbon accounting mandates that require granular spend categorization.
- Forecasting:Stochastic engines project cash flows and scenario outcomes using Monte Carlo simulations. Asset management firms in Shanghai's Lujiazui district drive demand, compelled by PBOC sandbox approvals that legitimize AI-driven predictive tools previously restricted to manual methods.
- Reporting:Automated generation of regulatory filings and board presentations with immutable audit trails.
- Analysis:Ad-hoc query tools and visualization dashboards for strategic decision support.
Leading the category by volume: Budgeting. Growing fastest: Forecasting.
End User:
Procurement scale and compliance intensity diverge sharply across customer tiers, with state-linked entities imposing the most stringent vendor qualification protocols.
- SMEs:Cloud-native solutions with subscription pricing dominate this tier. Hangzhou and Chengdu city commercial banks adopt these fastest, attracted by unbundled implementation services that reduce upfront capital commitment.
- Corporations:Enterprise-grade platforms integrate with legacy ERP systems through API middleware. State-owned enterprises anchor demand here, though decades-old treasury infrastructure forces costly connectivity development that compresses vendor margins.
- Freelancers:Lightweight mobile-first applications with basic cash-flow tracking and tax estimation.
- Individuals:Personal wealth management tools focused on investment portfolio visualization and retirement planning.
Highest procurement velocity: SMEs. Steepest compliance burden: Corporations.
Deployment Model:
Data localization mandates from the CAC and cross-border flow restrictions from the PBOC reshape architectural choices across all customer tiers.
- On-Premises:Traditional server installations within client data centers. Northern state-owned banks retain this model longest, constrained by legacy security protocols that resist cloud migration despite higher total cost of ownership.
- Cloud-Based:Scalable infrastructure with elastic compute resources. Shenzhen's Qianhai zone fintech licensees pilot these deployments most aggressively, leveraging special economic zone regulatory flexibility to test SaaS configurations.
- Hybrid:Sensitive data remains on-premise while analytics workloads shift to cloud instances.
- SaaS:Fully managed subscription services with automatic updates and shared infrastructure.
Widest installed base: On-Premises. Climbing the fastest: Cloud-Based.
Feature Set:
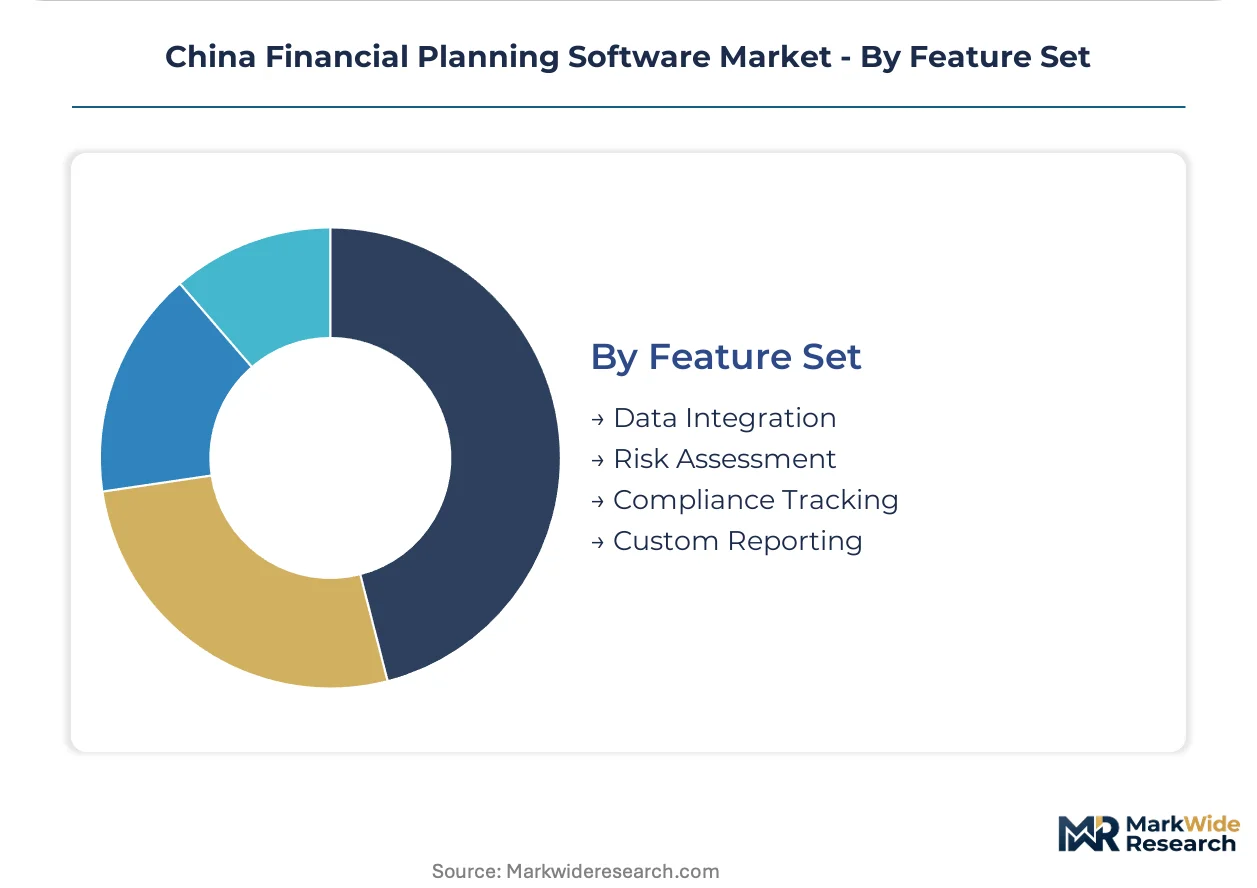
Premium pricing power concentrates in modules that automate regulatory compliance, with CSRC disclosure mandates creating vendor differentiation through audit-ready calculation trails.
- Data Integration:ETL pipelines and API connectors unify disparate financial systems. A-share listed enterprises require this capability most urgently, as CSRC mandates force consolidation of previously siloed subsidiary reporting.
- Risk Assessment:Quantitative models evaluate credit, market, and operational exposures. Insurance asset-liability management divisions in Shanghai drive adoption here, responding to climate risk stress-testing requirements that demand stochastic scenario engines.
- Compliance Tracking:Automated monitoring of regulatory deadlines and disclosure obligations.
- Custom Reporting:User-configurable output formats and visualization templates.
Commanding premium pricing: Compliance Tracking. Expanding most quickly: Risk Assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai special economic zone attracts fintech licensees seeking sandboxed market entry, while Shanghai's Lujiazui financial district concentrates asset management headquarters demanding real-time portfolio tools. State-backed banks in Beijing pilot cloud deployments under PBOC supervision.
Shanghai
Asset management firms in Lujiazui drive demand for stochastic scenario engines and stress-testing modules. CSRC disclosure mandates for A-share listed enterprises headquartered here force vendors to embed immutable audit trails at the calculation-cell level. The Pudong New Area hosts the densest cluster of foreign-Chinese joint ventures seeking localized compliance templates.
Shenzhen
Qianhai's fintech licensing regime permits SaaS configurations restricted elsewhere, accelerating cloud-native adoption among city commercial banks. CAC data localization requirements nonetheless compel domestic server infrastructure for sensitive enterprise clients. The Pearl River Delta integration initiative funnels cross-border treasury consolidation demand from Hong Kong-linked subsidiaries.
Beijing
Policy banks and state-owned enterprises anchor on-premise installations, constrained by legacy security protocols resisting cloud migration. SAMR algorithmic transparency rules affect AI-driven forecasting modules deployed at financial holding companies in the financial street district. Zhongguancun technology corridor vendors supply middleware for decades-old ERP connectivity.
Jiangsu Province
Regional commercial banks in Nanjing and Suzhou harden procurement standards for integrated planning platforms. MIIT dual carbon accounting mandates require automated carbon-footprint modules that categorize granular spend patterns. The Yangtze River Delta integration scheme positions Jiangsu as a testbed for unbundled subscription pricing among mid-tier city commercial banks.
Sichuan-Chongqing
Second-tier financial centers in Chengdu adopt cloud-native solutions faster than northern counterparts, attracted by unbundled implementation services reducing upfront capital commitment. Western China development programs channel subsidies toward SME-focused subscription models. The Chengdu-Chongqing economic circle generates procurement autonomy exceeding Beijing-headquartered policy banks.
China Financial Planning Software Market Competitive Landscape
Top-tier vendors anchor state-owned enterprise accounts, while mid-tier specialists capture regional commercial bank procurement through modular microservices. The vendor base stratifies across three tiers: multinational platforms with localized compliance templates, domestic ERP incumbents cross-selling financial modules, and cloud-native challengers unbundling implementation services. Strategic archetypes include database-layer integrators, compliance-tracking specialists, and SaaS-first entrants. Dominant competitive moves center on sandboxed regulatory approvals and middleware development for legacy system connectivity.
Within the domestic ERP incumbent tier, Kingdee International Software Group leverages its installed base to cross-sell financial planning modules, while SAP SE sustains relevance through localized compliance templates aligned with Chinese accounting standards. Oracle Corporation anchors the database-layer integration archetype, occupying a position that connects treasury and risk systems at state-linked entities. These three exemplify how foreign and domestic players navigate divergent data sovereignty requirements.
| Leading Market Players |
|---|
| Shenzhen Sunline Tech Co. Ltd. |
| Kingdee International Software Group |
| Anaplan |
| Workday Adaptive Planning |
| Oracle Corporation |
| SAP SE |
| FinAlyzer |
| Qvinci |
| Yusys Technologies |
| Others |
Pricing and Supply Chain Analysis
MIIT dual carbon accounting mandates gate both qualified supply and premium-tier pricing access, as vendors must embed automated carbon-footprint modules to serve Jiangsu-based regional commercial banks while compliance-certified deployments command subscription premiums above standard SaaS tiers.
Pricing Analysis
Short lead-time delivery premiums distinguish procurement evaluations, with state-backed banks piloting cloud deployments under PBOC sandbox approvals paying 15-25% above baseline for accelerated implementation schedules. Three-tier pricing structure across premium, standard, and economy levels aligns with SAMR algorithmic transparency certification tiers, where fully documented AI forecasting modules attract enterprise-grade rates. Cost compression in mid-tier city commercial bank segments intensifies because Kingdee and domestic ERP incumbents unbundle implementation services to accelerate land-and-expand cycles. SMEs in Hangzhou and Chengdu exhibit highest price sensitivity, while northern state-owned enterprises anchored to on-premise legacy systems demonstrate lowest elasticity.
Supply Chain Analysis
CAC data localization requirements reshape sourcing architectures, compelling foreign vendors to establish captive domestic server infrastructure or forfeit access to sensitive enterprise accounts. Software development concentrates in China, with specialized compliance engineering talent clustering in Beijing's Zhongguancun corridor and Shenzhen's Qianhai zone. Cloud compute resources draw from state-backed telecommunications providers, while stochastic modeling engines rest on licensed quantitative libraries subject to export control screening. Single-source vulnerability runs through SAMR-certified algorithmic transparency auditors, whose scarcity extends vendor qualification timelines. Distribution runs through direct enterprise sales teams for state-owned accounts and channel partners for mid-tier city commercial banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with database-layer control over treasury and risk systems emerging as the decisive downstream lever separating tier-one vendors from modular point-solution challengers.
For Market Incumbents: Acquire middleware connectivity assets to bridge decades-old ERP installations at state-owned enterprises, insulating core accounts from cloud-native disintermediation while embedding immutable audit-trail capabilities that satisfy tightening CSRC disclosure mandates. For New Entrants and Emerging Players: Regional system integrators in Jiangsu and Zhejiang provinces offer the most penetrable channel infrastructure, as their relationships with city commercial banks bypass entrenched procurement committees at Beijing-headquartered policy institutions. Target Shenzhen Qianhai fintech licensees with sandbox-ready SaaS configurations that exploit special economic zone regulatory flexibility unavailable to northern competitors. For Investors and Strategic Acquirers: PBOC cloud sandbox approval announcements are the leading indicator that SaaS deployment models have achieved regulatory legitimacy sufficient to support scaled recurring revenue platforms. Long-term viability centers on vendors combining domestic data center infrastructure with SAMR-certified algorithmic transparency documentation, positioning for consolidation as CAC localization requirements eliminate pure foreign-cloud players.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Buildout | CAC compliance mandates require captive server infrastructure for sensitive enterprise access. |
| SAMR Certification Investment | Algorithmic transparency documentation creates defensible pricing tiers against unlicensed competitors. |
| Legacy ERP Middleware Development | API connectivity to decades-old treasury systems secures state-owned enterprise retention. |
| Qianhai Zone Market Entry | Special economic zone licensing permits SaaS configurations restricted elsewhere. |
| Carbon Accounting Module Integration | MIIT emissions disclosure rules create mandatory attach rates for listed enterprise sales. |
Research Methodology
CSRC disclosure filings, PBOC sandbox approval registers, and MIIT dual carbon policy circulars formed the secondary backbone, cross-referenced against primary interviews with CTOs at regional commercial banks, SAMR compliance officers, and fintech licensing specialists in Shenzhen Qianhai. Bottom-up and top-down triangulation validated vendor revenue estimates against procurement velocity indicators from Jiangsu and Zhejiang provincial banking associations.
Bottom-up modeling segmented the market by deployment model, organization tier, solution type, and integration complexity, while top-down approaches cross-checked aggregate figures against PBOC-supervised cloud pilot disclosures. CAGRs were derived from regression analysis of subscription pricing trajectories and on-premise license conversion rates across the projection horizon. Industry-specific inputs included SAMR algorithmic transparency certification timelines and CAC data center establishment requirements.
Caveats apply where regulatory enforcement intensity around cross-border data flows or sudden shifts in CSRC disclosure mandates could materially shift the outlook. Forecasts reflect assumptions about sandbox approval expansion and legacy system replacement cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Household Finances Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market