
 North America Fintech Cloud Market | 2026-2036
North America Fintech Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fintech Cloud Market Analytics
Cloud distribution channels between core banking infrastructure and front-end fintech applications is tilting toward API-first platforms that bypass traditional middleware. Amazon Web Services leverages its FedRAMP authorizations to anchor public-sector adjacent financial workloads. Microsoft Azure competes through dedicated financial services compliance regions in the US and Canada. Google Cloud differentiates via BigQuery analytics integrations tailored to real-time fraud detection pipelines.
North America Fintech Cloud denotes the delivery of financial technology services through virtualized compute, storage, and networking resources hosted across geographically distributed data centers, typically operating under SOC 2 Type II and PCI DSS Level 1 certification requirements. These platforms enable real-time transaction processing, regulatory reporting automation, and elastic scaling during peak settlement windows. Payment processing and fraud detection service types command the largest current revenue pools, while lending solutions and wealth management segments show the fastest expansion as credit unions and regional banks modernize legacy core systems. Hybrid cloud deployments lead in enterprise banking due to data sovereignty requirements, though multi-cloud strategies are gaining traction among investment firms seeking vendor diversification.
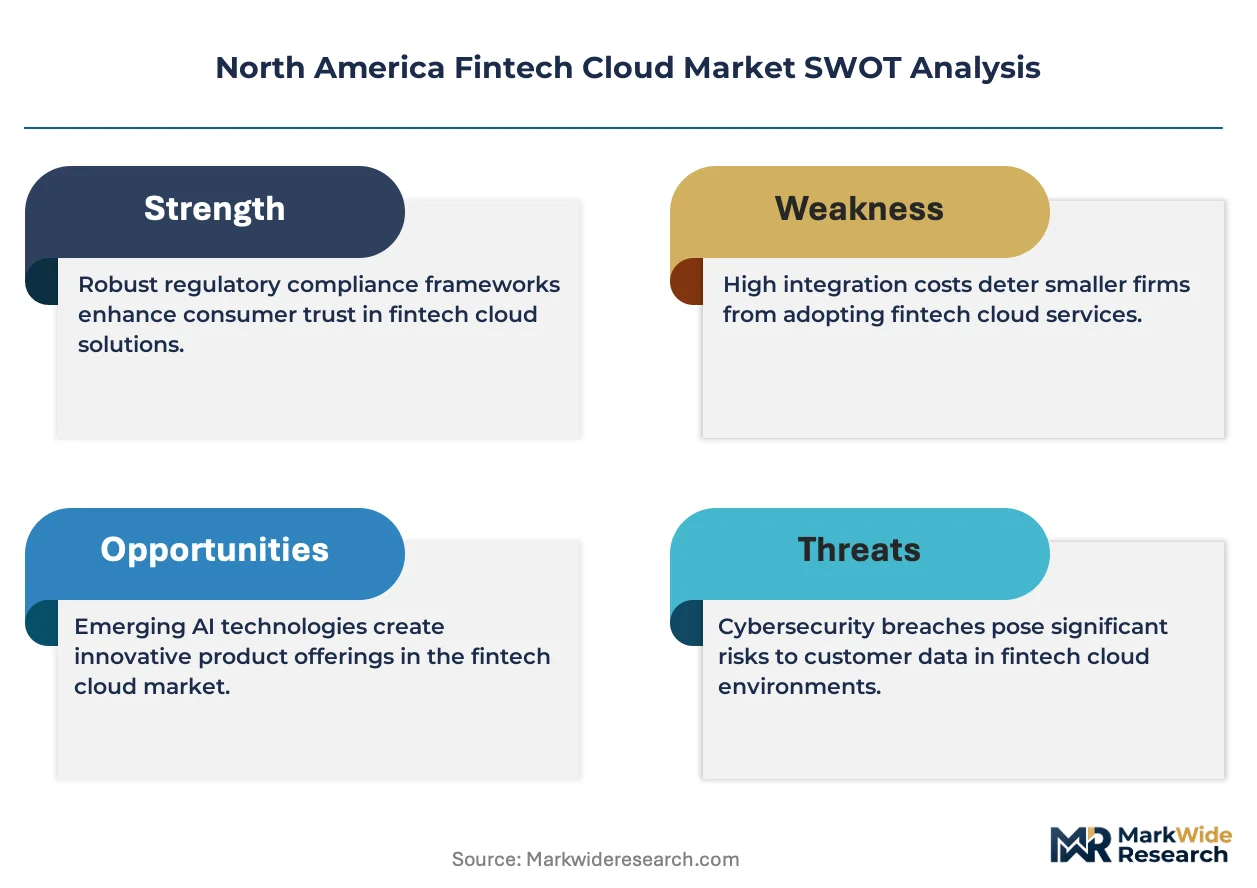
The US Federal Reserve, Office of the Comptroller of the Currency, and Canada's Office of the Superintendent of Financial Institutions collectively shape cloud adoption through cybersecurity assessment frameworks and third-party risk management guidelines. PCI DSS compliance and state-level data privacy laws in California and New York add layered certification burdens that favor established providers with dedicated compliance teams. Stakeholders must monitor evolving AI governance rules from US federal agencies and Canadian regulators as machine learning models increasingly automate credit decisions and anti-money laundering screening.
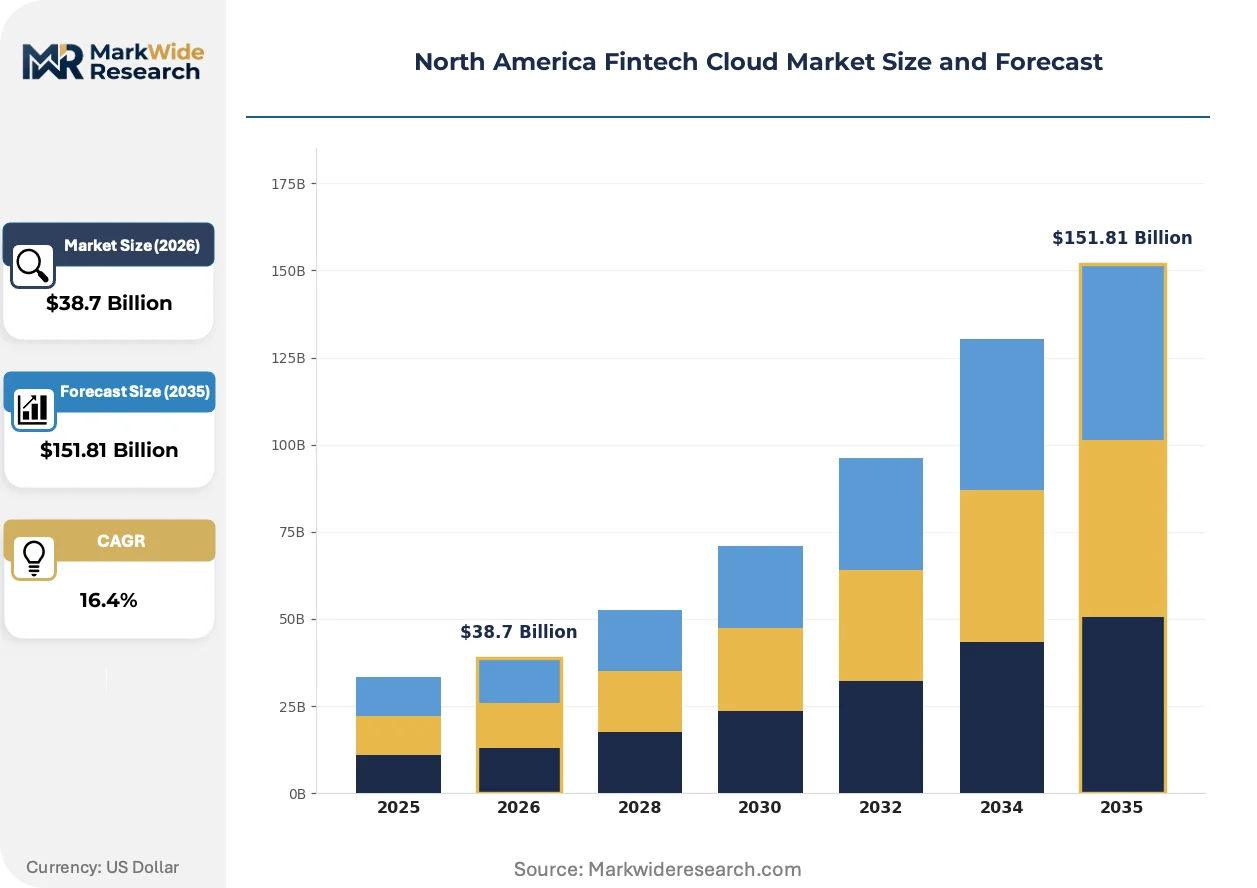
Market Dynamics
API-first cloud architectures are compressing the middleware layer between core banking systems and fintech front-ends, forcing infrastructure providers to reconfigure their service delivery models around real-time data pipelines rather than batch processing workflows.
Growth Catalysts
- FedNow instant payment infrastructure:The US Federal Reserve's real-time settlement rails mandate cloud-native processing capabilities that legacy on-premise systems cannot support, accelerating replacement cycles among community banks.
- Credit unions:These member-owned institutions are modernizing core lending platforms through cloud deployments to compete with neobanks on origination speed and member experience.
- PCI DSS Level 1 certification:The stringent payment card security standard creates competitive moats for established cloud providers, concentrating procurement decisions among certified vendors.
Market Restraints
- Data sovereignty requirements:Hybrid cloud deployments dominate enterprise banking as institutions maintain sensitive customer records within jurisdictional boundaries, limiting pure public cloud adoption.
- Specialized compliance talent scarcity:The shallow labor pool for professionals versed in both cloud architecture and financial services regulation inflates implementation timelines and service costs.
- State-level privacy fragmentation:California's CCPA and New York's SHIELD Act impose overlapping compliance burdens that complicate multi-state cloud service provisioning.
Strategic Opportunities
- Wealth management modernization:Registered investment advisors and broker-dealers lag retail banks in cloud adoption, presenting greenfield deployment opportunities for portfolio analytics and client onboarding platforms.
- AI governance frameworks:Anticipated US federal agency guidance on machine learning in credit decisions will create demand for explainable AI cloud services that automate compliance documentation.
- Canada's open banking framework:The federal consumer-directed finance mandate will require cloud infrastructure upgrades among Canadian credit unions and mid-tier banks by 2025.
Industry Challenges
- Core system integration complexity:Decades-old COBOL-based banking platforms resist API connectivity, forcing costly middleware development or risky rip-and-replace migrations.
- SOC 2 Type II audit timelines:The six-to-twelve month certification window delays product launches and extends sales cycles for emerging cloud providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fintech Cloud Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Wealth Management, Fraud Detection, Lending Solutions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Banks, Credit Unions, Investment Firms, Insurance Companies Technology: Blockchain, Artificial Intelligence, Machine Learning, Big Data |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Cloud, Oracle Cloud, Fiserv, FIS, Stripe, PayPal, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fintech Cloud Market Evolving Landscape
Real-time fraud detection pipelines and embedded finance architectures are redefining how financial institutions evaluate cloud service providers, shifting procurement criteria from cost-per-compute to latency-sensitive performance guarantees.
BigQuery analytics integrations are digitizing fraud detection workflows across North American payment processors. Regional banks and fintech startups are adopting these real-time data warehouse solutions to replace overnight batch risk scoring. The technology is digitizing transaction monitoring from retrospective review to instantaneous intervention, compressing fraud loss windows from days to milliseconds.
The US Federal Reserve's third-party risk management guidelines are tightening oversight of cloud service providers serving federally chartered banks. These rules now mandate continuous monitoring of subcontractor security postures rather than point-in-time assessments. Community banks with limited vendor management resources are consolidating supplier relationships to reduce compliance burden.
Subscription-based infrastructure pricing is displacing consumption-metered models among mid-market financial institutions. Credit unions and regional banks prefer predictable monthly fees for core processing capacity over variable costs tied to transaction volumes. This preference is most visible in the US Midwest and Southeast, where conservative treasury management practices dominate institutional procurement committees.
North America Fintech Cloud Market Segmentation
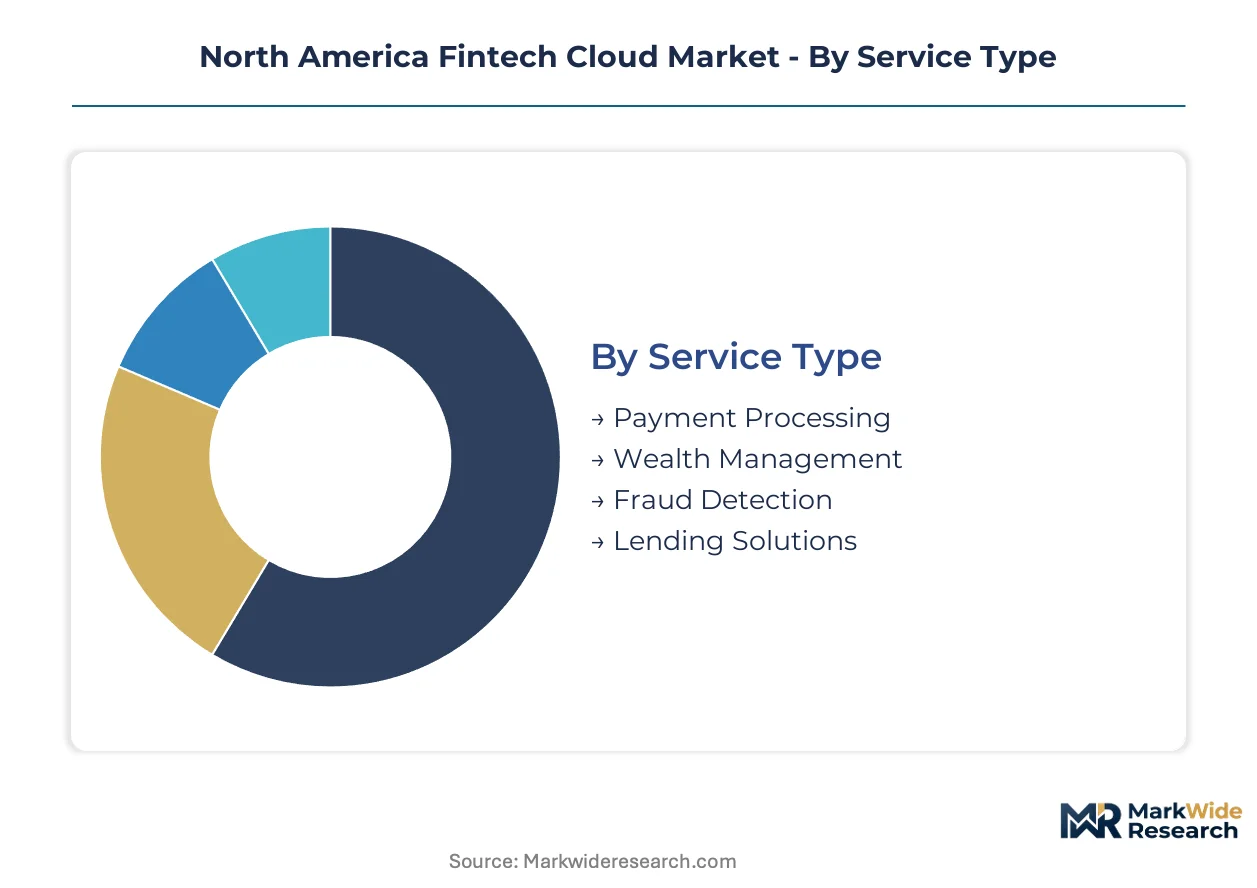
Cloud service procurement in North American financial services diverges sharply by institutional risk tolerance and legacy system burden. Segmentation reveals how FedNow compliance deadlines and open banking mandates are reshaping vendor selection criteria across service tiers and deployment models.
Service Type:
Application focus determines compliance overhead and integration complexity for financial institutions modernizing core operations.
- Payment Processing:Real-time transaction settlement engines require PCI DSS Level 1 certification and FedRAMP authorization for Federal Reserve interoperability. Demand clusters among community banks in US metropolitan corridors replacing batch-based ACH systems with instant payment rails.
- Fraud Detection:Machine learning pipelines analyze transaction streams in sub-100-millisecond windows to flag anomalous patterns before settlement completion. Canadian payment processors and US regional banks prioritize these capabilities as real-time fraud losses escalate.
- Wealth Management:Portfolio analytics and client onboarding platforms serve registered investment advisors lagging retail banks in cloud adoption.
- Lending Solutions:Cloud-native origination platforms enable credit unions to compete with neobanks on approval velocity.
Payment Processing commands the established base. The steepest expansion runs through Fraud Detection.
Deployment:
Infrastructure architecture selection reflects data sovereignty requirements and vendor diversification strategies across institutional tiers.
- Hybrid Cloud:Sensitive customer records remain in private data centers while compute-intensive workloads burst to public infrastructure. Enterprise banks in New York and Toronto favor this model for regulatory audit trail preservation.
- Multi-Cloud:Investment firms distribute workloads across AWS, Azure, and Google Cloud to mitigate concentration risk and negotiate favorable pricing. Hedge funds and asset managers in Chicago and Boston lead this approach.
- Public Cloud:Fintech startups and neobanks operate entirely on shared infrastructure with SOC 2 Type II certification.
- Private Cloud:Dedicated single-tenant environments serve insurers with legacy policy administration systems requiring customized compliance configurations.
Hybrid Cloud anchors current procurement volumes. Multi-Cloud is climbing the fastest as vendor lock-in concerns intensify.
End User:
Institutional category shapes cloud migration urgency based on competitive pressure and regulatory examination intensity.
- Banks:Federally chartered institutions face OCC third-party risk management guidelines mandating continuous subcontractor monitoring. Community banks across the US Southeast accelerate core system replacements to meet FedNow deadlines.
- Credit Unions:Member-owned institutions modernize lending platforms to match neobank origination speeds. The US Midwest and Canadian prairie provinces show concentrated deployment activity.
- Investment Firms:Broker-dealers and registered investment advisors adopt portfolio analytics platforms with lighter compliance burdens than deposit-taking institutions.
- Insurance Companies:Property-casualty and life insurers migrate actuarial modeling to cloud infrastructure while maintaining on-premise policyholder data repositories.
Banks represent the dominant revenue pool. Credit Unions are expanding most quickly as modernization budgets release from pent-up depreciation cycles.
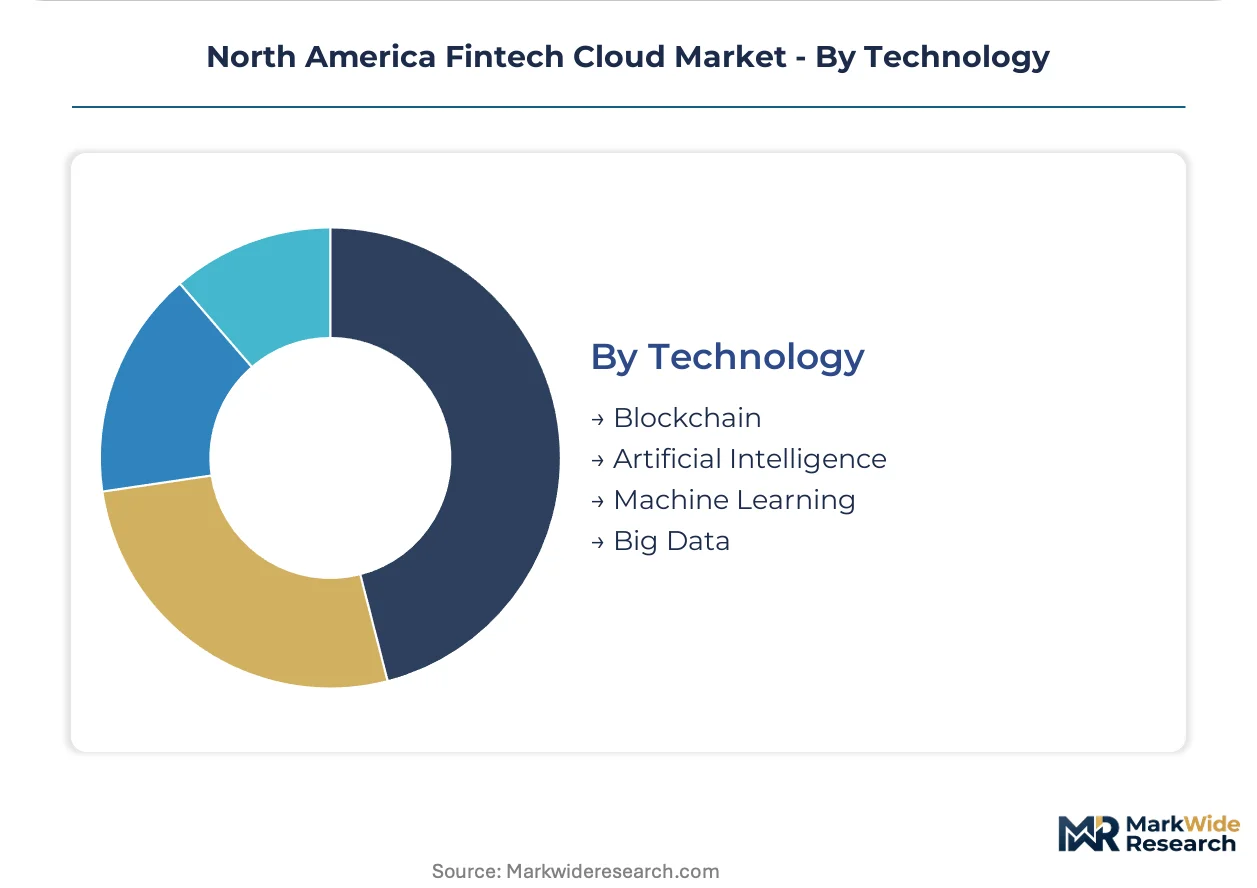
Technology:
Underlying technical capability determines latency performance and regulatory defensibility for automated financial decisions.
- Artificial Intelligence:Explainable credit scoring and anti-money laundering screening face emerging US federal agency governance requirements. Institutions in California and New York preemptively document model decision trails.
- Machine Learning:Real-time pattern recognition powers fraud detection pipelines with continuous model retraining on streaming transaction data. Payment processors prioritize sub-second inference latency.
- Big Data:Data warehouse solutions replace overnight batch risk scoring with instantaneous transaction monitoring.
- Blockchain:Distributed ledger infrastructure supports cross-border settlement and trade finance documentation with immutable audit trails.
Artificial Intelligence captures strategic investment focus. Machine Learning is gaining share fastest as production deployment accelerates beyond pilot phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Reserve's FedNow infrastructure and Canada's open banking mandates anchor North American cloud adoption patterns. Community banks across both nations accelerate core system replacements to meet real-time payment deadlines. Regulatory sandboxes in major financial centers concentrate procurement decisions among certified providers.
United States
Community banks in the US Southeast and Midwest modernize lending platforms to match neobank origination speeds. The Federal Reserve's third-party risk management guidelines mandate continuous subcontractor monitoring for federally chartered institutions. New York and San Francisco financial centers host dense clusters of fintech incubators where cloud-native payment processors cluster near FedNow interoperability testing facilities.
Canada
Credit unions across the Prairie Provinces upgrade core systems to comply with the federal consumer-directed finance mandate by 2025. The Office of the Superintendent of Financial Institutions issues cybersecurity assessment frameworks that favor established cloud providers with dedicated compliance teams. Toronto's financial district concentrates procurement activity among mid-tier banks seeking vendor diversification strategies.
Mexico
Fintech startups in Mexico City leverage public cloud infrastructure to bypass legacy banking infrastructure gaps. The country's national banking regulator implements tiered licensing frameworks that reduce barriers for cloud-native payment aggregators. Nuevo León's emerging technology corridor attracts regional data center investments serving cross-border remittance flows.
North America Fintech Cloud Market Competitive Landscape
Hyperscale cloud providers and specialized financial technology vendors split the market along compliance-capability lines. AWS, Microsoft Azure, and Google Cloud dominate public infrastructure through FedRAMP authorizations and dedicated financial services regions. Tier-two positions cluster among core banking modernization specialists and payment processing platforms. Competitive moves concentrate on API-first architecture development and strategic partnerships with regional banks facing FedNow deadlines.
Within the hyperscale tier, Amazon Web Services and Microsoft Azure exemplify the compliance-heavy positioning required for Federal Reserve interoperability. Google Cloud occupies a differentiated position through analytics-integrated offerings. Among specialized financial technology providers, Fiserv and FIS represent the legacy-core modernization archetype, while Stripe exemplifies the API-native payment infrastructure approach. These named entities anchor broader industry patterns rather than indicating specific strategic actions or market shares.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Cloud |
| Oracle Cloud |
| Fiserv |
| FIS |
| Stripe |
| PayPal |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud infrastructure concentration in US West Coast and Northern Virginia data center corridors anchors margin capture among FedRAMP-authorized providers, while Canadian credit unions and US community banks absorb tiered compliance premiums downstream. Certification scarcity for PCI DSS Level 1 and SOC 2 Type II auditors compresses vendor choice, concentrating pricing power with established platforms serving federally chartered institutions.
Pricing Analysis
US metropolitan financial centers command 15-25% premiums over Canadian prairie provinces and US Midwest community bank markets for equivalent cloud compute workloads. Subscription-based SaaS tiers dominate procurement, separating FedRAMP-authorized premium tiers from standard SOC 2 offerings and economy-grade uncertified infrastructure. Price differentiation rests on compliance certification depth and geographic proximity to FedNow interoperability testing facilities. Pricing pressure stems from credit union budget constraints as these member-owned institutions modernize core systems. Community banks exhibit highest price sensitivity due to limited vendor management resources, while investment firms in New York and Chicago show lowest sensitivity given vendor diversification mandates.
Supply Chain Analysis
US export controls on advanced AI accelerators and quantum-resistant cryptography components restrict flows to Canadian and Mexican financial infrastructure providers, forcing reliance on domestic US supply channels. Hardware supply concentrates in Taiwan for advanced semiconductors, South Korea for memory modules, and the United States for specialized networking equipment. Raw material dependencies span rare earth elements for magnetic storage, high-purity silicon for compute chips, and copper for data center power distribution. Single-source vulnerability runs through Taiwan Semiconductor Manufacturing capacity for custom AI inference chips deployed in fraud detection pipelines. Distribution runs through direct enterprise sales teams for hyperscale providers and regional systems integrators for mid-tier credit unions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shallow labor pool for professionals versed in both cloud architecture and financial services regulation constrains implementation velocity across institutional tiers, creating sustained capability premiums for certified providers. This scarcity dynamic rewards early certification investments and punishes delayed compliance commitments.
For Market Incumbents: Harden FedRAMP authorization portfolios against emerging AI governance requirements from US federal agencies by pre-positioning explainable model documentation capabilities. Defend position by acquiring specialized compliance audit firms to internalize SOC 2 Type II certification timelines, compressing six-to-twelve month windows that delay product launches. Channel control through exclusive partnerships with regional systems integrators serving US Southeast community banks anchors replacement cycle capture ahead of FedNow deadlines. For New Entrants and Emerging Players: Canadian prairie provinces and US Midwest credit union markets offer underpenetrated deployment opportunities as these conservative institutions release pent-up modernization budgets. Wealth management platforms for registered investment advisors present the most penetrable segment, given lighter compliance burdens than deposit-taking institutions and lagging cloud adoption relative to retail banking. A go-to-market angle anchored to subscription-based pricing with predictable monthly fees aligns with treasury management preferences in these regions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed core banking modernization specialists carrying legacy COBOL migration expertise and established OCC relationships. Long-term viability hinges on these targets' capacity to bridge API-first architectures with decades-old banking platforms without risky rip-and-replace disruptions. The signal to watch is accelerated FedNow interoperability testing facility certifications among regional banks, indicating replacement cycle timing and vendor consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Expansion | AWS and Azure anchor public-sector adjacent workloads through dedicated financial services compliance regions. |
| API-First Architecture Development | Stripe and specialized fintech platforms compress middleware layers between core banking systems and front-end applications. |
| Core Banking Modernization Partnership | Fiserv and FIS bridge COBOL legacy platforms with cloud-native lending origination systems for credit unions. |
| Real-Time Fraud Detection Integration | Google Cloud BigQuery deployments digitize transaction monitoring from overnight batch to sub-100-millisecond intervention. |
| Canada Open Banking Compliance Program | Mid-tier Toronto banks upgrade infrastructure to meet federal consumer-directed finance mandate deadlines. |
Research Methodology
Initial hypotheses were tested against primary input from cloud infrastructure procurement officers at US regional banks, compliance audit leads at Canadian credit unions, fintech platform engineers, and FedNow interoperability testing facility administrators, then refined through secondary validation. Primary fieldwork combined structured interviews with SEC 10-K filings from hyperscale providers, Office of the Comptroller of the Currency third-party risk management guideline releases, and Federal Reserve payment system development reports. Bottom-up triangulation across institutional deployment timelines and top-down validation through regulatory mandate scheduling anchored market sizing.
Demand-supply balance framing structured the analytical framework across service type, deployment model, end user category, and underlying technology capability dimensions. CAGRs were derived through segment-level growth rate reconciliation against macroeconomic drivers and regulatory deadline clustering. Cloud-native payment processing adoption curves and AI governance framework anticipation patterns served as industry-specific forecast inputs throughout the modeling period.
The forecast holds incumbent behavior within observed patterns; aggressive certification acceleration by tier-two providers or sudden FedRAMP authorization streamlining would shift outcomes. Material shifts in US federal agency AI governance rulemaking timelines or Canadian open banking mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Latin America AI in Fintech Market
FinTech
IoT for Finance Market
FinTech
Digital Banking Platform Market
FinTech
Robo-Advisory Software Market
FinTech
AI Finance Market
FinTech
India AI in Fintech Market
FinTech
Fintech Crisis Management Market
FinTech
United States Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Europe AI in Fintech Market
FinTech
Financial Analytics Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Europe Fintech Cloud Market
FinTech
Stock Trading App Market
FinTech
Malaysia Fintech Market
FinTech
Asia-Pacific Neo Banking Market