
 Electronic Payment System for Transportation Market | 2026-2036
Electronic Payment System for Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Payment System for Transportation Market Foresight
Multi-source technology procurement is restructuring vendor relationships across the electronic payment system for transportation sector. Cubic Transportation Systems leverages its integrated fare collection platforms to sustain dominance in North American transit agencies. Kapsch TrafficCom AG anchors European tolling and urban mobility contracts through specialized roadside-to-back-office architectures. Thales Group competes on security-certified embedded systems for rail operators requiring EMV compliance.
An electronic payment system for transportation comprises hardware terminals, secure communication protocols, and back-end settlement platforms that process fare transactions across buses, trains, toll roads, and shared mobility fleets. These systems typically operate on PCI-DSS certified infrastructure with sub-300-millisecond transaction authorization cycles to maintain passenger throughput during peak hours. Contactless system types currently occupy the largest installed base among transit operators migrating from magnetic stripe tickets, while mobile wallet payment methods represent the fastest-growing transaction channel as NFC-enabled smartphones displace physical cards. Cloud-based technology types are capturing margin pools through software-as-a-service deployment models that reduce capital expenditure for mid-sized public transport operators.
The Federal Transit Administration, the European Commission's Mobility Package regulations, and PCI Security Standards Council frameworks collectively shape product certification requirements and market access conditions for transportation payment vendors. EMVCo specifications and GDPR data handling rules further constrain how biometric and location data from fare transactions may be stored or monetized. Stakeholders must monitor evolving open banking API standards and central bank digital currency pilots that could fundamentally alter settlement architectures and interchange economics across transit networks.
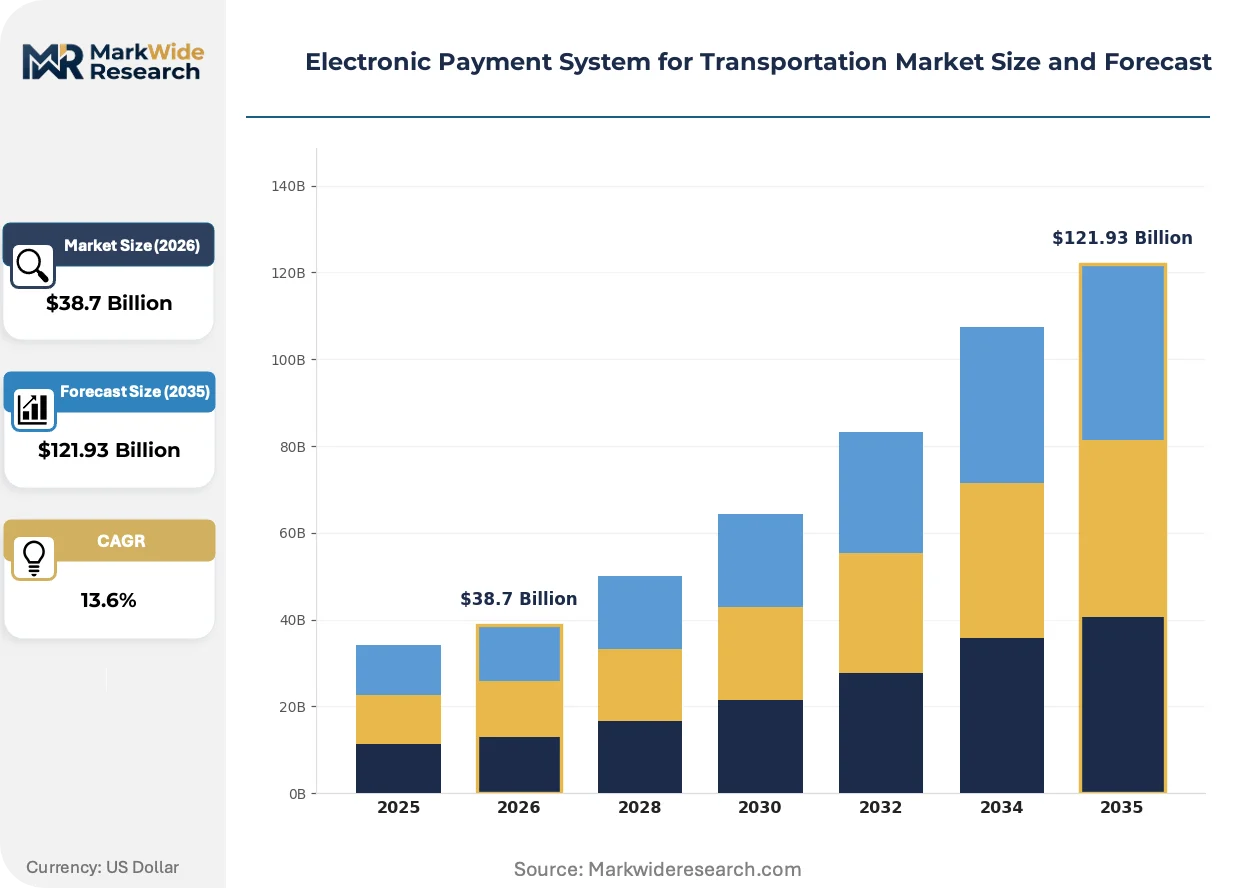
Market Dynamics
Transit authorities in Europe and Asia are mandating open-loop payment architectures that dismantle proprietary closed-loop systems, forcing hardware vendors to restructure terminal portfolios around EMV certification and interoperable protocols.
Growth Catalysts
- PCI-DSS certification mandates:Transit operators in Germany, France, and the United Kingdom now require payment infrastructure meeting PCI Security Standards Council frameworks, accelerating terminal replacement cycles.
- Mobile wallet penetration:China's rail and bus networks process the majority of fares through Alipay and WeChat Pay, creating template deployments that operators in Southeast Asia replicate.
- NFC-enabled smartphones:Device manufacturers embed secure elements that displace physical transit cards, reducing card issuance and distribution costs for municipal operators.
Market Restraints
- Semiconductor supply concentration:Secure element and NFC controller fabrication concentrates in Taiwan and South Korea, exposing terminal manufacturers to allocation constraints.
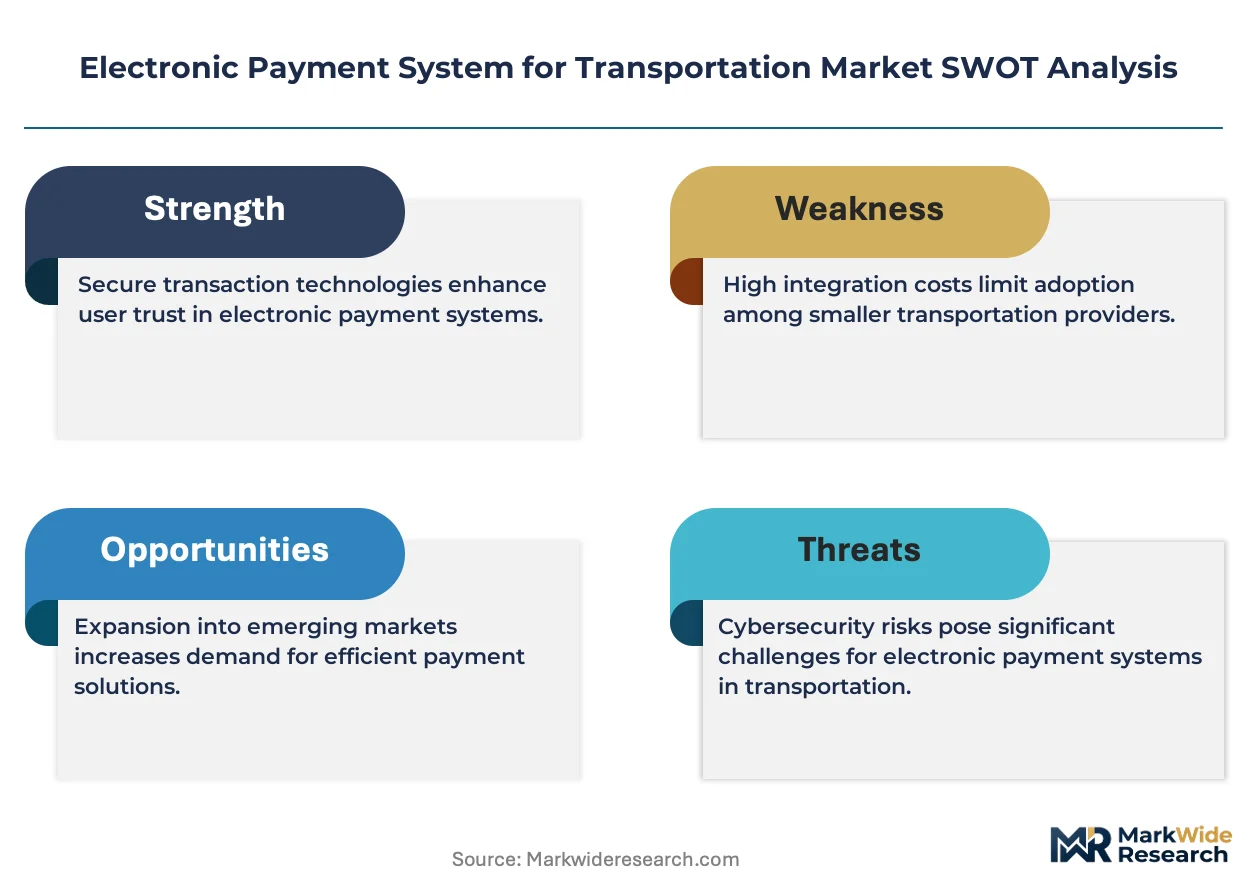
- GDPR data handling friction:Biometric fare authentication and location tracking trigger Article 6 lawful basis requirements that complicate back-end analytics monetization.
- Legacy magnetic stripe infrastructure:Decades-old ticket vending machines and gate mechanisms in Eastern European and Latin American networks resist firmware upgrades.
Strategic Opportunities
- Central bank digital currency pilots:China's digital yuan testing in Shenzhen and Suzhou transit corridors creates settlement architecture templates for programmable transit subsidies.
- India's urban metro expansion:The National Metro Rail Policy mandates unified payment interfaces across 27 operational and planned networks, opening integrated mobility-as-a-service platforms.
- Convergence of account-based ticketing and mobility-as-a-service:Helsinki, Singapore, and Tokyo operators bundle public transit with bike-share and ride-hail through single-app orchestration.
Industry Challenges
- EMV certification timeline compression:Laboratory testing and type approval for contactless terminals now stretches 14-18 months, delaying revenue recognition for hardware vendors.
- Interoperability protocol fragmentation:Calypso, ITSO, and OSPT Alliance standards coexist uneasily, forcing multi-protocol firmware stacks that inflate engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Payment System for Transportation Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $121.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Wallet, Credit Card, Bank Transfer, NFC System Type: Contactless, Online, In-Vehicle, Integrated End User: Public Transport Operators, Ride-Sharing Services, Logistics Providers, Fleet Managers Technology Type: Blockchain, QR Code, RFID, Cloud-based |
| Companies Covered | Scheidt & Bachmann, Kapsch TrafficCom AG, Cubic Transportation Systems, Masabi Ltd., Conduent Incorporated, Siemens AG, Transcore, Vix Technology, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Payment System for Transportation Market Shifts & Advancements
Payment infrastructure is converging with identity verification and urban data platforms, transforming fare collection from a transactional utility into a node for mobility analytics and public policy instrumentation.
Account-based ticketing is unifying previously siloed fare products across bus, rail, and micro-mobility modes. Transport for London's capping and journey history APIs demonstrate the architecture's scalability. Mid-sized European operators in the Netherlands and Scandinavia are migrating from card-centric to passenger-centric systems, compressing the addressable market for physical ticket media suppliers.
GDPR and the EU AI Act constrain how biometric data from facial recognition fare gates may be stored or algorithmically processed. The European Commission's Mobility Package regulations now embed data portability requirements that prevent vendor lock-in through proprietary passenger accounts. French and German transit authorities are restructuring procurement specifications to mandate open APIs and passenger data sovereignty.
Riders now expect fare products to integrate with banking and loyalty applications rather than standalone transit apps. Urban millennials in Seoul, Stockholm, and Sydney demonstrate willingness to abandon physical cards entirely when mobile wallet acceptance reaches full network coverage. This behavioral shift pressures operators to deprecate closed-loop card programs and redirect capital toward cloud-based clearinghouse infrastructure.
Electronic Payment System for Transportation Market Segmentation
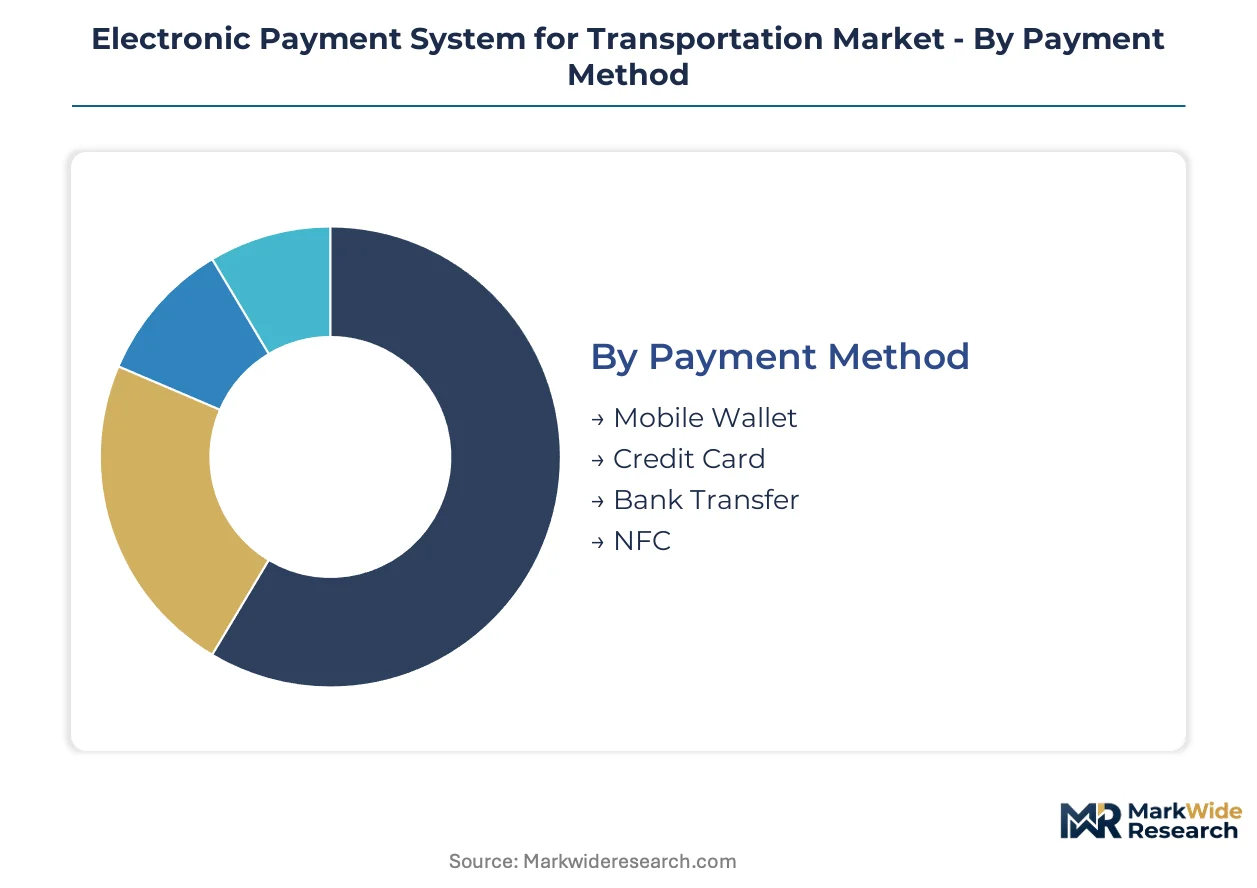
Transportation payment infrastructure fragments across four critical dimensions that determine procurement priorities, certification requirements, and capital deployment cycles. Payment method and system type decisions cascade through terminal hardware specifications, back-end settlement architectures, and regulatory compliance obligations. End user profiles and technology type selections further constrain vendor selection and integration complexity across urban transit networks.
Payment Method:
Standardization pressure from EMVCo specifications collides with regional mobile wallet dominance, creating divergent deployment templates across operator procurement cycles.
- Mobile Wallet:Smartphone-based fare authentication leverages NFC secure elements and tokenized credentials to displace physical card issuance. China's rail and bus networks process dominant transaction volumes through Alipay and WeChat Pay, establishing reference architectures that Southeast Asian operators replicate under PCI-DSS certification timelines.
- Credit Card:Open-loop EMV contactless acceptance mandates from European transit authorities require terminal hardware capable of sub-300-millisecond authorization cycles. German, French, and British operators now mandate PCI Security Standards Council compliance, accelerating replacement of proprietary closed-loop infrastructure.
- Bank Transfer:Account-based ticketing architectures enable post-ride fare calculation and automatic capping through direct debit linkages. Netherlands and Scandinavian operators favor this method for its reduced card distribution costs.
- NFC:Near-field communication protocols embedded in wearables and transit cards persist in hybrid deployments during mobile wallet transition periods.
Leading the category by volume: Mobile Wallet. Expanding most quickly: Credit Card.
System Type:
Deployment location and passenger throughput requirements segment hardware procurement across terminal form factors and communication protocols.
- Contactless:Terminal hardware at fare gates and onboard validators processes tap-to-pay transactions through ISO 14443 protocols. Urban metro networks in London, Seoul, and Tokyo anchor installed base volumes as operators migrate from magnetic stripe tickets.
- Online:Pre-purchase and account management platforms enable fare product selection before physical journey commencement. Ride-sharing services and logistics providers concentrate demand here for trip authorization and dynamic pricing integration.
- In-Vehicle:Onboard validation units in buses and trams require ruggedized hardware with cellular backhaul for real-time transaction clearing. Fleet managers specify these systems for toll road and parking integration.
- Integrated:Unified platforms spanning multiple transport modes demand middleware capable of reconciling disparate fare structures across rail, bus, and micro-mobility networks.
Dominant by installed base: Contactless. Gaining share fastest: Integrated.
End User:
Procurement scale and integration complexity separate municipal operators from commercial mobility providers across contract structures.
- Public Transport Operators:Municipal and regional transit authorities issue multi-year tenders for fare collection infrastructure serving millions of daily passengers. India's National Metro Rail Policy mandates unified payment interfaces across 27 operational and planned networks.
- Ride-Sharing Services:Platform-native payment orchestration prioritizes seamless in-app transactions over hardware terminal deployment. These providers drive API standardization for mobility-as-a-service bundling.
- Logistics Providers:Fleet-scale tolling and fuel payment automation require back-office integration with enterprise resource planning systems.
- Fleet Managers:Commercial vehicle operators seek consolidated expense management across driver reimbursement and vehicle-specific charging.
Largest contract values: Public Transport Operators. Fastest procurement cycle acceleration: Ride-Sharing Services.
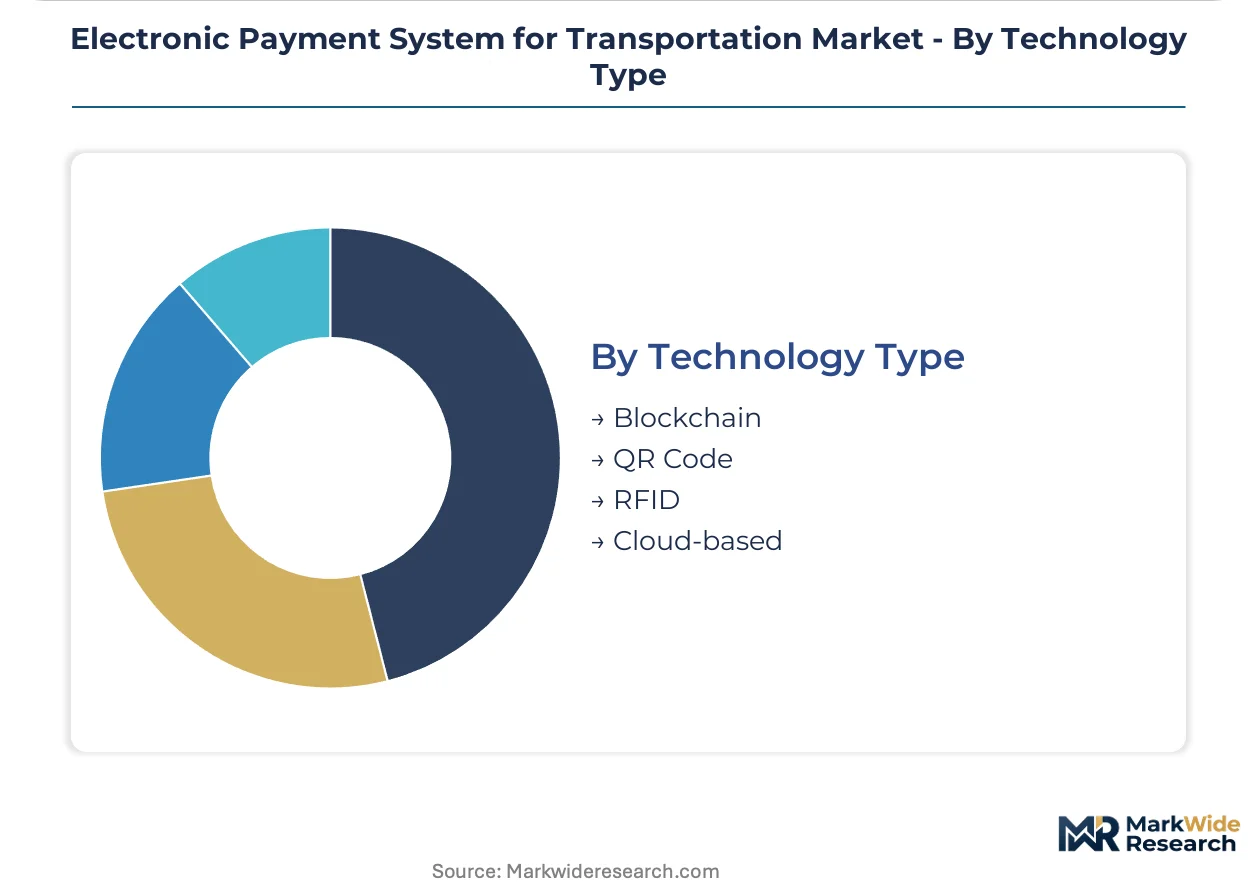
Technology Type:
Legacy protocol maturity versus emerging architecture risk defines vendor roadmaps and operator upgrade timelines.
- Cloud-based:Software-as-a-service deployment models reduce capital expenditure for mid-sized operators through subscription-based clearinghouse access. Transport for London's journey history APIs demonstrate scalability for account-based ticketing at volume.
- QR Code:Optical scanning infrastructure enables low-cost smartphone acceptance without NFC hardware requirements. Emerging market bus operators favor this method for minimal terminal cost.
- RFID:Radio-frequency identification persists in closed-loop transit card programs and vehicle-mounted toll tags despite gradual displacement by open-loop alternatives.
- Blockchain:Distributed ledger pilots for programmable transit subsidies and cross-operator settlement remain experimental, with China's digital yuan testing in Shenzhen and Suzuo corridors providing limited production templates.
Widest production deployment: Cloud-based. Steepest expansion trajectory: QR Code.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Taiwan and South Korea anchors the semiconductor supply chain for NFC controllers and secure elements that power transportation payment terminals worldwide.
United States
The Federal Transit Administration accelerates contactless fare collection deployment across metropolitan rail networks in New York, Chicago, and San Francisco. Transit agencies now mandate PCI-DSS certification for all new terminal procurements, compressing vendor qualification timelines. Los Angeles Metro and Washington Metropolitan Area Transit Authority anchor West Coast and Mid-Atlantic demand clusters respectively.
Germany
Deutsche Bahn and municipal operators in Berlin, Munich, and Hamburg drive EMV contactless migration from proprietary closed-loop systems. The KBA enforces transport data interoperability standards that prevent vendor lock-in through proprietary passenger accounts. Bavaria's transit consortiums lead southern German deployment volumes for integrated mobility-as-a-service platforms.
China
Mobile wallet penetration through Alipay and WeChat Pay processes dominant fare volumes across Shenzhen, Beijing, and Shanghai metro networks. The People's Bank of China pilots digital yuan settlement in Suzhou and Shenzhen transit corridors, testing programmable subsidy architectures. Yangtze River Delta and Pearl River Delta urban clusters generate the largest terminal procurement contracts in Asia.
India
The National Metro Rail Policy mandates unified payment interfaces across 27 operational and planned metro networks in Delhi, Mumbai, Bangalore, and Hyderabad. RBI regulations govern wallet-based transit payment interoperability with banking infrastructure. Maharashtra and Karnataka state transit authorities lead procurement acceleration for account-based ticketing systems.
United Kingdom
Transport for London's capping and journey history APIs demonstrate account-based ticketing scalability that operators in Manchester, Birmingham, and Glasgow replicate. The Financial Conduct Authority and Information Commissioner's Office jointly supervise open banking API standards and GDPR compliance for transit data monetization. London anchors European demand for cloud-based clearinghouse infrastructure.
Electronic Payment System for Transportation Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware vendors align with cloud platform providers to deliver software-as-a-service fare collection models. The vendor base organizes around three tiers: integrated platform specialists with end-to-end system capabilities, component suppliers focused on terminal hardware and secure elements, and regional system integrators serving municipal procurement cycles. Two strategic archetypes predominate: EMV-certified hardware manufacturers competing on laboratory approval speed, and API-first software vendors capturing recurring revenue through clearinghouse subscriptions. Geographic expansion and technology licensing represent the primary competitive vectors as vendors seek to replicate proven deployment templates across emerging metro markets.
Among European-headquartered specialists, Kapsch TrafficCom AG and Thales Group occupy positions within the integrated platform tier, with the former exemplifying roadside-to-back-office architecture specialization and the latter representing security-certified embedded systems for rail compliance. Cubic Transportation Systems anchors the North American vendor landscape as a representative of consolidated fare collection platforms serving large municipal agencies. Siemens AG sits within the industrial conglomerate archetype, leveraging cross-divisional capabilities across rail signaling and payment infrastructure.
| Leading Market Players |
|---|
| Scheidt & Bachmann |
| Kapsch TrafficCom AG |
| Cubic Transportation Systems |
| Masabi Ltd. |
| Conduent Incorporated |
| Siemens AG |
| Transcore |
| Vix Technology |
| Thales Group |
| Others |
Supply & Pricing Matrix
Municipal transit authorities in Germany, France, and the United Kingdom concentrate procurement volumes through multi-year framework agreements, anchoring a subscription-based SaaS pricing model where cloud-based clearinghouse access displaces perpetual license structures. This buyer concentration forces terminal manufacturers to unbundle hardware from software maintenance, creating tiered service packages that separate EMV-certified platform tiers from basic validation-only configurations.
Pricing Analysis
Warranty and field service bundling separates premium-tier vendors from economy positioning in terminal procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects EMV certification grade and after-sales response time commitments. Cost compression in mid-sized European operator segments is intensifying because SaaS entrants undercut legacy perpetual-license vendors on total cost of ownership. Municipal transit authorities in Scandinavia demonstrate highest price sensitivity due to budget constraints, while Asian mega-metro operators in Shenzhen and Shanghai prioritize certification speed over unit cost.
Supply Chain Analysis
Secure element and NFC controller fabrication rests on Taiwanese and South Korean semiconductor foundries, with packaging and testing operations concentrated in Malaysia and Vietnam. Terminal assembly draws from Chinese PCB manufacturing, German industrial enclosure suppliers, and Japanese connector specialists. Single-source vulnerability in 14nm secure element production exposes hardware vendors to allocation constraints during demand surges. Distribution runs through authorized regional system integrators who manage installation and certification compliance for municipal procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Account-based ticketing architectures are displacing card-centric legacy systems, compressing the addressable market for physical ticket media while expanding recurring revenue pools for cloud-native platform vendors.
For Market Incumbents: Anticipate margin erosion in proprietary closed-loop card programs as open-loop EMV mandates spread across European and Asian transit authorities. Consolidate through acquisition of API-first clearinghouse specialists to defend against SaaS entrants capturing mid-sized operator contracts. Deepen backward integration into secure element sourcing to mitigate Taiwanese foundry allocation risks. For New Entrants and Emerging Players: India's National Metro Rail Policy opens a window for unified payment interface specialists to capture 27-network procurement cycles across Delhi, Mumbai, Bangalore, and Hyderabad. Target QR-code-enabled bus operators in Southeast Asian emerging markets where minimal terminal cost overrides NFC hardware requirements. Lead with mobile wallet integration expertise to differentiate from hardware-centric incumbents. For Investors and Strategic Acquirers: The window for entry favors cloud-native platform vendors with demonstrated account-based ticketing deployments at scale. Long-term viability hinges on clearinghouse subscription retention as operators deprecate capital-intensive perpetual-license models. Watch central bank digital currency pilot expansion as the inflection signal for programmable subsidy architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Acceleration | Shortens laboratory approval timelines to capture European open-loop mandate windows. |
| Cloud Clearinghouse Migration | Converts capital expenditure contracts to recurring SaaS revenue from mid-sized operators. |
| Mobile Wallet Integration | Positions platforms for Alipay and WeChat Pay replication across Southeast Asian networks. |
| API-First Architecture Development | Enables mobility-as-a-service bundling with ride-share and bike-share providers. |
| Regional System Integrator Partnership | Secures installation and compliance capabilities for India's metro expansion pipeline. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for terminal hardware import volumes and component sourcing patterns. Primary interviews with transit authority procurement directors, fare collection system engineers, and EMV certification laboratory managers combined with PCI Security Standards Council documentation and European Commission Mobility Package regulatory texts. Bottom-up triangulation validated against top-down spending estimates from national transport ministry budgets.
Data-stream reconciliation across payment method adoption curves, system type deployment timelines, and technology type migration rates informed the analytical framework. Segmentation dimensions modeled include payment method, system type, end user category, and technology architecture across the projection horizon. CAGRs derived from operator replacement cycle analysis and open-loop mandate implementation schedules, with terminal shipment data and cloud subscription growth trajectories as core forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for central bank digital currency settlement would alter the outlook if programmable subsidy architectures displace conventional clearinghouse models. Forecasts reflect assumptions about EMV certification timeline compression and semiconductor supply normalization. A small set of named triggers—CBDC pilot expansion, GDPR enforcement actions on biometric data, and Taiwan supply allocation disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Africa Gift Card and Incentive Card Market
Payments
Russia Payments Market
Payments
Egypt Mobile Payments Market
Payments
Global Accounts Payable Automation Market
Payments
Retail POS Terminals Market
Payments
Global Gift Card Market
Payments
Buy Now Pay Later Platform Market
Payments
Romania POS Terminals Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Europe Virtual Cards Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Crypto Payment Gateway Market
Payments
France Buy Now Pay Later Services Market
Payments
Sweden POS Terminals Market