
 Canada Gift Card and Incentive Card Market | 2026-2036
Canada Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Gift Card and Incentive Card Market Outlook
Corporate gifting is hardening as the dominant demand vertical for Canadian incentive card platforms. EML Payments leverages its prepaid processing infrastructure to anchor enterprise payroll and rewards distribution across major employers. Blackhawk Network competes through broad retail network access, while Neo Financial differentiates via mobile-native card issuance tied to its digital banking ecosystem.
Canada gift and incentive cards are stored-value instruments carrying prepaid monetary balances redeemable through open-loop networks or closed-loop merchant systems, typically encoded with magnetic stripes, EMV chips, or digital token credentials for POS and e-commerce authentication. The primary commercial purpose centers on transferring purchasing power from institutional buyers to individual recipients without direct cash disbursement. Open-loop cards command the widest redemption flexibility and sustain premium positioning, while digital delivery through email and mobile app channels is displacing physical mail as the fastest-growing distribution mode. Closed-loop configurations retain stronger margin pools through merchant-specific breakage economics and captive redemption ecosystems.
The Bank of Canada oversees systemic payment infrastructure stability, while the Financial Consumer Agency of Canada enforces disclosure standards for prepaid product terms, collectively elevating compliance costs for non-bank issuers seeking national scale. Provincial consumer protection statutes across Ontario, Quebec, and British Columbia impose varying expiration and dormancy fee restrictions that fragment operational standardization. Stakeholders must monitor whether federal open banking implementation alters data-sharing protocols underlying personalized incentive card targeting and loyalty integration.
Market Dynamics
The Bank of Canada's retail payment oversight framework is forcing non-bank issuers to restructure compliance infrastructure around systemic stability mandates, compressing operational margins while elevating barriers to national scale.
Growth Catalysts
- Digital wallet penetration:Mobile credential issuance is automating last-mile distribution across Ontario and British Columbia, where fintech clustering accelerates closed-loop adoption.
- Corporate payroll digitization:Enterprise incentive programs are hardening as the dominant demand channel, with prepaid cards displacing direct deposit for contractor and seasonal worker compensation.
- FCAC disclosure harmonization:Standardized fee transparency rules are reducing consumer friction and building institutional buyer confidence in prepaid program administration.
Market Restraints
- Provincial fragmentation:Ontario, Quebec and British Columbia maintain divergent dormancy fee statutes, forcing issuers to operate three distinct compliance templates.
- Breakage economics compression:Consumer protection litigation in Quebec is narrowing the margin pool from unused card balances, historically a profit anchor for closed-loop merchants.
- Interchange rate volatility:Open-loop issuers face margin pressure from network fee renegotiations with Visa and Mastercard payment rails.
Strategic Opportunities
- Alberta energy sector incentives:Oil sands employers are piloting prepaid wellness and safety reward cards for remote workforce retention, creating a white-space vertical.
- Real-time payment convergence:Integration between prepaid card rails and Interac e-Transfer infrastructure is enabling instant issuance for emergency disbursement use cases.
- Open banking data protocols:Pending federal implementation of consumer-directed financial data sharing is unlocking personalized incentive targeting based on transaction history.
Industry Challenges
- EMV chip supply bottlenecks:Physical card production faces extended lead times from semiconductor procurement constraints, delaying enterprise program launches.
- Legacy core banking integration:Regional credit unions and mid-tier banks struggle to API-connect prepaid platforms to decades-old deposit account systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Gift Card and Incentive Card Market |
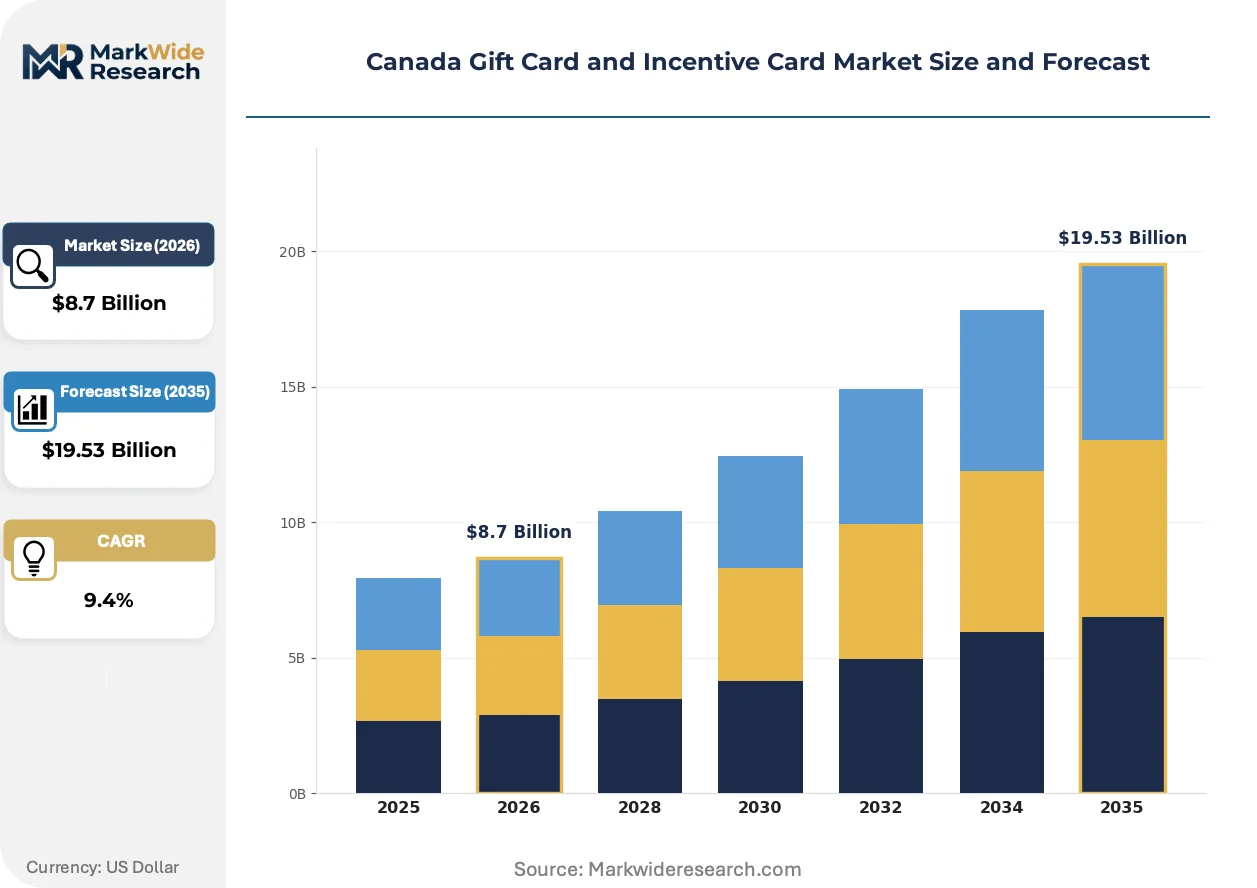
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Open-Loop, Closed-Loop, Digital, Physical Delivery Method: Email, SMS, Physical Mail, Mobile App Usage Occasion: Holidays, Birthdays, Corporate Gifting, Loyalty Rewards Industry Vertical: Retail, Hospitality, Entertainment, E-Commerce |
| Companies Covered | EML Payments, Paystone, Blackhawk Network, Neo Financial, Buyatab, InComm Payments, Giftogram, Giftbit, Givex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Gift Card and Incentive Card Market Strategic Shifts
Tokenized mobile credentialing is compressing physical card lifecycles, while regulatory pressure on fee transparency is reshaping issuer revenue models away from breakage dependence.
API-native card management platforms are automating real-time balance tracking, instant virtual issuance and programmable spending controls. Mid-market employers in Toronto and Vancouver are adopting these tools at the fastest clip, replacing manual gift card fulfillment. The technology is automating procurement workflows that previously required dedicated administrative staff.
The Financial Consumer Agency of Canada is enforcing stricter disclosure timelines for dormancy and maintenance fee activation. This policy shift is forcing issuers to front-load revenue recognition and accelerate card utilization marketing. Quebec-based programs face the steepest compliance cost escalation due to bilingual mandate requirements.
Enterprise buyers are consolidating vendor relationships and demanding consolidated reporting across prepaid, merchandise and experience reward categories. This procurement consolidation is displacing single-product gift card specialists in favor of full-suite incentive platforms. The shift is most visible in Ontario's financial services and technology sectors, where procurement teams are reducing supplier counts by half.
Canada Gift Card and Incentive Card Market Segmentation
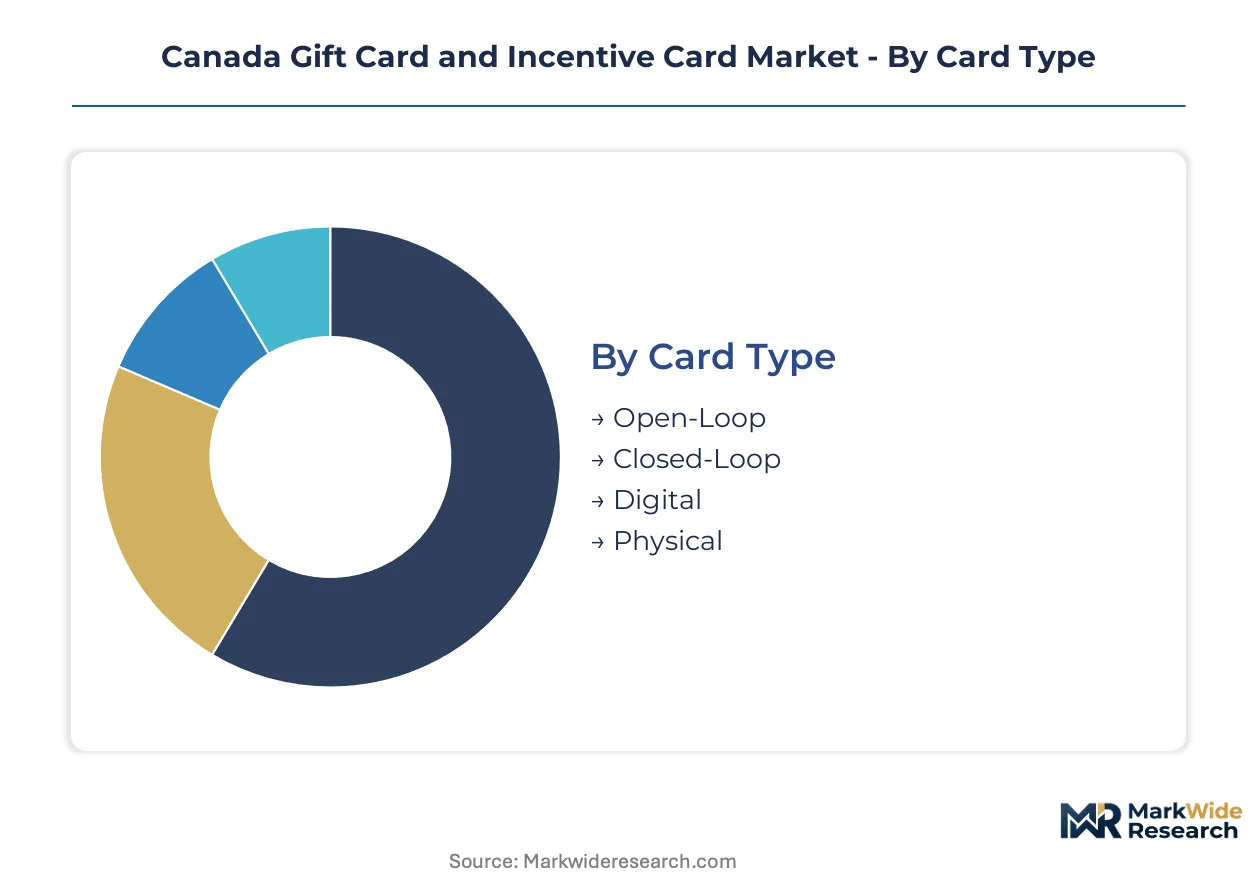
Segmentation in the Canadian gift card market reveals how issuer business models align with redemption economics and distribution infrastructure. Each dimension carries distinct compliance obligations under federal and provincial frameworks.
Card Type:
Customization intensity spans from fully interoperable network credentials to merchant-captive instruments with proprietary settlement rails.
- Open-Loop:Network-branded instruments redeemable across Visa, Mastercard, or Interac acceptance locations. Corporate procurement teams in Toronto's financial district favor these for contractor compensation programs where recipient flexibility outweighs premium pricing.
- Closed-Loop:Single-merchant stored value with captive redemption ecosystems. British Columbia's retail concentration around Vancouver generates dense closed-loop adoption where breakage economics fund loyalty program subsidies.
- Digital:Tokenized credentials delivered through mobile wallets and email. The format eliminates EMV chip supply constraints while enabling real-time balance tracking.
- Physical:Magnetic stripe or chip-encoded plastic cards. Enterprise buyers still specify physical delivery for ceremonial recognition events despite higher fulfillment costs.
Most installed capacity flows through Open-Loop. Expansion is steepest in Digital.
Delivery Method:
Channel selection tracks enterprise digitization maturity and workforce dispersion patterns.
- Email:Instant credential transmission with embedded redemption links. Ontario technology firms deploy this channel for remote employee onboarding kits.
- SMS:Text-delivered token strings with shortened URLs. The format penetrates seasonal retail hiring surges where workers lack corporate email addresses.
- Physical Mail:Card-present delivery through postal infrastructure. Quebec's bilingual packaging mandates elevate per-unit compliance costs for national issuers.
- Mobile App:Native wallet integration with push notification activation. Fintech clustering in Vancouver accelerates adoption among digitally native employers.
Procurement volume concentrates in Email. Adoption velocity peaks in Mobile App.
Usage Occasion:
Occasion-based segmentation separates consumer discretionary purchases from institutional program administration.
- Holidays:Seasonal volume spikes concentrated in Q4 retail calendars. Grocery and department store chains preload inventory ahead of Thanksgiving and Christmas redemption windows.
- Birthdays:Individual gift purchases with lower average transaction values. Digital delivery displaces physical cards fastest in this occasion category.
- Corporate Gifting:Enterprise procurement of standardized denominations for client and employee recognition. This occasion commands the highest per-card values and multi-year program contracts.
- Loyalty Rewards:Points-to-card conversions within airline, hotel, and retail coalition programs. Breakage-sharing negotiations between issuers and program operators determine margin allocation.
Program revenue concentrates in Corporate Gifting. Volume expansion runs strongest in Loyalty Rewards.
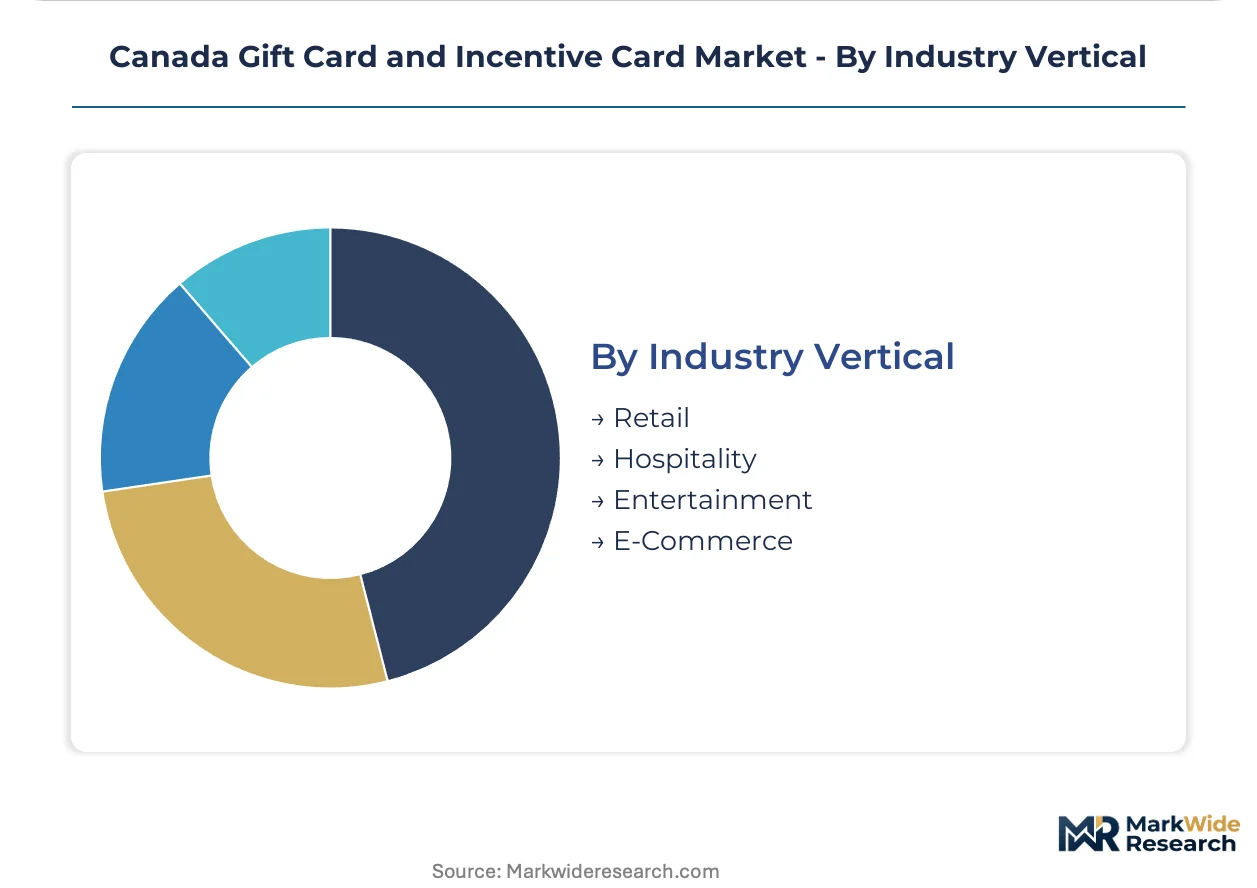
Industry Vertical:
Vertical alignment determines interchange rate exposure and regulatory scrutiny intensity.
- Retail:General merchandise and grocery redemption networks. The vertical faces the steepest FCAC disclosure compliance costs due to high transaction frequency.
- Hospitality:Hotel, restaurant, and travel experience cards. Seasonal demand fluctuation forces working capital intensity that favors larger issuers with balance sheet capacity.
- Entertainment:Cinema, streaming, and live event credentials. Digital delivery penetration reaches highest levels here as younger demographics dominate.
- E-Commerce:Pure-play online merchant cards with no physical POS presence. The vertical escapes provincial dormancy fee fragmentation by operating outside traditional retail statutes.
Transaction volume concentrates in Retail. Platform investment intensity peaks in E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial compliance cost differentials are redistributing issuer operational footprints across Canada. The Bank of Canada's federal oversight framework establishes baseline stability mandates, while provincial consumer protection statutes create fragmented operational templates that favor scale players with multi-jurisdictional infrastructure.
Ontario
Toronto's financial district concentrates corporate procurement demand for open-loop contractor compensation programs. The Financial Consumer Agency of Canada enforces standardized fee disclosure timelines that reduce buyer friction. Fintech clustering around the Waterloo-Toronto corridor accelerates API-native card management platform adoption among mid-market employers.
Quebec
Bilingual packaging mandates elevate per-unit compliance costs for national issuers operating loyalty reward programs. The province's consumer protection litigation narrows breakage margin pools from unused card balances. Montreal's retail concentration sustains closed-loop merchant adoption where captive redemption ecosystems fund program subsidies.
British Columbia
Vancouver's digital wallet penetration drives mobile app credential issuance for digitally native employers. Provincial dormancy fee statutes diverge from Ontario templates, forcing distinct compliance infrastructure. The Lower Mainland's technology sector procurement teams consolidate vendor relationships across prepaid and experience reward categories.
Alberta
Oil sands employers pilot prepaid wellness and safety reward cards for remote workforce retention. The province escapes Quebec-style consumer protection litigation intensity, preserving breakage economics. Calgary's energy sector procurement offices anchor enterprise incentive program administration for distributed field operations.
Canada Gift Card and Incentive Card Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-suite incentive platforms displacing single-product gift card specialists in enterprise procurement. The vendor base organizes around three archetypes: bank-anchored issuers leveraging deposit infrastructure, fintech-native platforms with mobile-first credentialing, and retail network aggregators with broad merchant acceptance. Consolidation pressure intensifies as enterprise buyers demand unified reporting across reward categories. Strategic partnerships between prepaid processors and digital banking ecosystems represent the dominant competitive vector.
Within the bank-anchored tier, EML Payments occupies a position exemplifying enterprise payroll and rewards distribution infrastructure. Neo Financial sits within the fintech-native archetype, representing mobile-native card issuance tied to digital banking ecosystems. Blackhawk Network anchors the retail network aggregation segment, occupying a position characterized by broad merchant access and closed-loop program administration.
| Leading Market Players |
|---|
| EML Payments |
| Paystone |
| Blackhawk Network |
| Neo Financial |
| Buyatab |
| InComm Payments |
| Giftogram |
| Giftbit |
| Givex |
| Others |
Value Chain & Pricing Dynamics
Prepaid platform engineering talent clustering in Toronto and Vancouver creates labor-cost differentials that widen pricing-tier spreads between premium API-native solutions and legacy card fulfillment services.
Pricing Analysis
Distributor margin compression in retail network channels is forcing open-loop issuers toward direct-to-enterprise contracting models. Three-tier pricing structure across premium, standard, and economy levels stratifies by API integration depth and real-time balance tracking capability. Pricing pressure stems from Interac network fee renegotiations and FCAC compliance cost front-loading. Mid-market employers in Ontario exhibit highest price sensitivity, while energy sector buyers in Alberta prioritize reliability over unit economics.
Supply Chain Analysis
Domestic-content mandates under the Bank of Canada retail payment oversight framework are reshaping issuer sourcing toward domestic EMV chip personalization facilities and local data residency infrastructure. Semiconductor supply draws from Taiwan, South Korea, and domestic Canadian foundries for chip encoding. Cardstock and magnetic stripe materials rest on US and European specialty paper suppliers. Single-source vulnerability concentrates in EMV chip procurement, where semiconductor bottlenecks delay enterprise program launches. Distribution runs through direct API integration with enterprise HR platforms, supplemented by retail network aggregation for closed-loop merchant programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada gift card market represents a late-cycle quality story, as enterprise procurement teams consolidate vendor relationships and demand premium specifications around real-time issuance and programmable spending controls.
For Market Incumbents: Lock in enterprise multi-year contracts before open banking data protocols enable new competitive entrants. Consolidate compliance infrastructure across Ontario, Quebec, and British Columbia templates to capture scale efficiencies. Vertical integration into domestic EMV chip personalization capacity mitigates semiconductor supply risk. For New Entrants and Emerging Players: FCAC disclosure harmonization in Canada opens a window for API-native platforms to displace legacy gift card specialists. Target Alberta energy sector wellness incentive programs as the most penetrable white-space vertical. Pursue strategic partnerships with Interac for real-time payment rail integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Full-suite incentive platforms are the most active acquirer in this space, consolidating single-product gift card vendors. Five-to-ten year viability hinges on open banking data access enabling personalized targeting. Acquisition target archetype: API-native card management platforms with enterprise HR system integrations. Watch federal open banking implementation timeline as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Payment Rail Integration | Interac e-Transfer connectivity enables instant emergency disbursement use cases for enterprise clients. |
| API-Native Platform Development | Programmable spending controls automate procurement workflows for Toronto and Vancouver mid-market employers. |
| Domestic EMV Personalization Capacity | Local chip encoding facilities reduce lead times from semiconductor supply bottlenecks affecting national issuers. |
| Open Banking Data Partnership | Consumer-directed financial data sharing unlocks personalized incentive targeting based on transaction history patterns. |
| Multi-Jurisdictional Compliance Infrastructure | Unified Ontario-Quebec-British Columbia templates capture operational efficiencies as provincial statutes diverge. |
Study Parameters
Bottom-up enterprise procurement modeling reconciled against top-down prepaid processing capacity tracking forms the analytical core of this study. Primary interviews with prepaid platform executives, FCAC regulatory affairs leads, enterprise HR procurement managers, and Interac network operations specialists combined with secondary validation from Bank of Canada payment system reports, Financial Consumer Agency disclosure filings, provincial consumer protection statutes, and enterprise incentive program RFP databases. Top-down triangulation against Visa and Mastercard network volume disclosures anchors scale estimates.
Historical trendline analysis of corporate gifting program adoption rates and digital wallet penetration trajectories informed projection assumptions across the analysis window. Segmentation dimensions modeled include card type, delivery method, usage occasion, and industry vertical, with additional granularity around provincial regulatory cluster and enterprise size tier. CAGRs derived from curve-fitting against observed digitization inflection points in comparable payment instrument markets. Forecast inputs incorporate Interac real-time payment infrastructure rollout timelines and federal open banking implementation progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated open banking adoption or prolonged semiconductor supply constraints. Assumptions reflect current regulatory frameworks and observed enterprise procurement patterns. A small set of triggers—federal payment oversight enforcement intensity, provincial consumer protection litigation trends, and EMV chip supply normalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United States Clearing Houses and Settlements Market
Payments
EMV Card Market
Payments
Consumer Mobile Payment Market
Payments
India Buy Now Pay Later Services Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Mobile Card Reader Market
Payments
Japan Real Time Payment Market
Payments
Forex Prepaid Cards Market
Payments
Germany Real Time Payments Market
Payments
Smart Bands Payments Market
Payments
Mobile POS Market
Payments
Denmark POS Terminals Market
Payments
Bitcoin Payments Market
Payments
Electronic Payment Processing Software Market
Payments
Contactless Payment Market
Payments
POS Terminals Market