
 Cyprus POS Terminals Market | 2026-2036
Cyprus POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Cyprus POS Terminals Market Outlook
Market Context
Banking channel partnerships is rewriting how terminal vendors reach Cypriot merchants. VeriFone Inc leverages its acquiring-bank alliances to secure premium placement in hotel chains. JCC Payment Systems Ltd anchors the domestic infrastructure through its long-standing clearing relationships. DATECS Ltd competes on price for small retail deployments outside the two major cities.
Technical Definition and Segment Structure
Cyprus POS terminals are electronic payment devices that capture card data through magnetic stripe, chip, or near-field communication interfaces, typically processing transactions via encrypted dial-up, Ethernet, or cellular connectivity to banking networks. These systems authenticate payments, generate receipts, and reconcile batches for retail, hospitality, and service-sector merchants. Contactless terminals lead transaction volume in tourism corridors where tap-to-pay speed matters at point of sale. Mobile terminals represent the fastest-expanding category as food delivery and pop-up vendors abandon fixed counter installations. Self-service kiosks remain nascent in Cyprus, concentrated in airport and ferry terminal environments where labor costs and passenger throughput create viable payback periods.
Regulatory Environment and Outlook
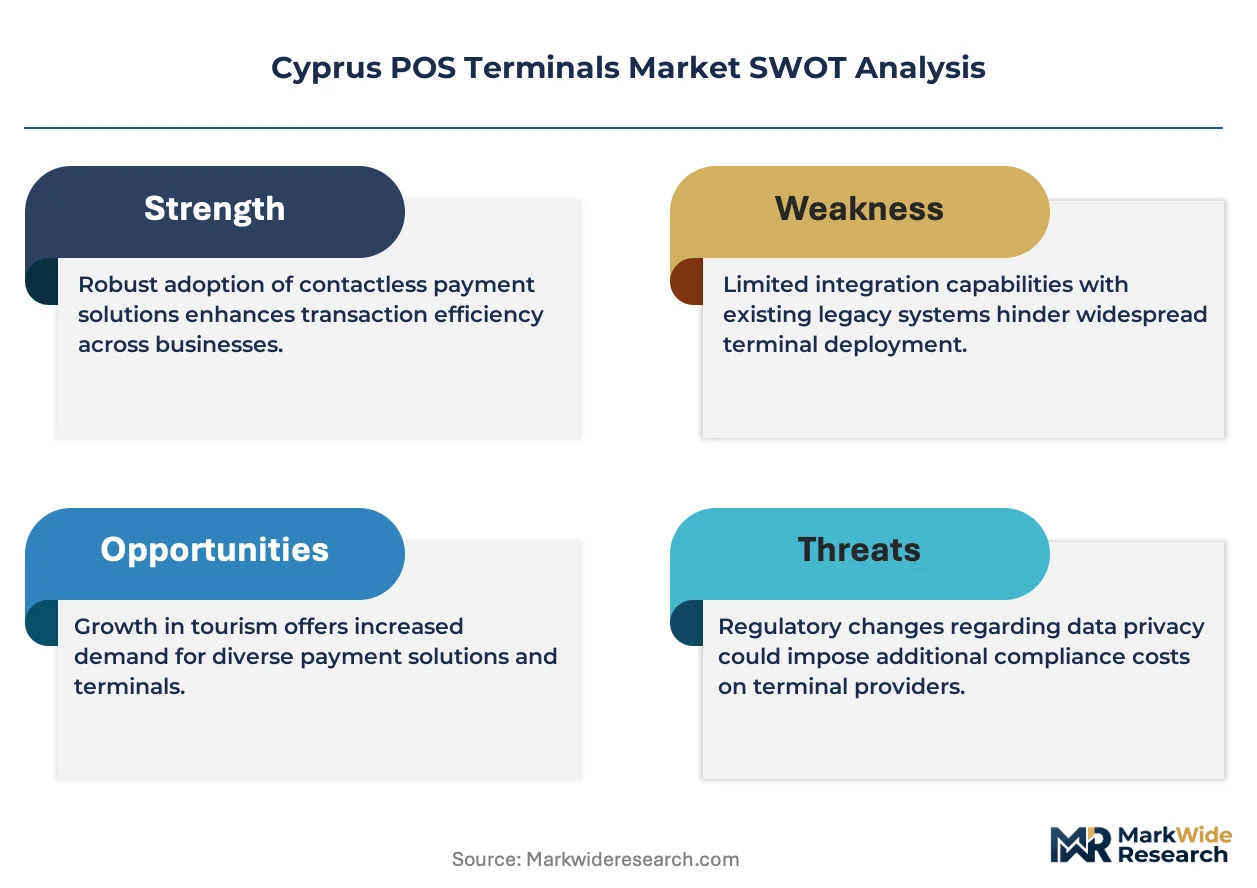
The Central Bank of Cyprus enforces PSD2 strong customer authentication rules that shape terminal firmware requirements and transaction routing protocols. PCI DSS certification gates market access, filtering out uncertified hardware imports from non-EU manufacturing centers. EMVCo specifications further constrain which chip architectures gain acceptance across domestic acquiring networks. Stakeholders must monitor evolving EU digital identity wallet integration timelines and assess whether terminal estates require premature replacement cycles.
Market Dynamics
Banking channel partnerships are rewriting how terminal vendors reach Cypriot merchants. VeriFone Inc leverages its acquiring-bank alliances to secure premium placement in hotel chains. JCC Payment Systems Ltd anchors the domestic infrastructure through its long-standing clearing relationships. DATECS Ltd competes on price for small retail deployments outside the two major cities.
Growth Catalysts
- PSD2 Strong Customer Authentication:The Central Bank of Cyprus mandates firmware upgrades that accelerate hardware replacement cycles across hospitality and retail estates.
- Tourism corridor density:Coastal districts from Limassol to Ayia Napa concentrate merchant demand where tap-to-pay speed drives terminal refresh decisions.
- SoftPOS adoption:Smartphone-based card acceptance eliminates dedicated hardware costs for food delivery vendors and pop-up merchants.
Market Restraints
- PCI DSS certification gates:Uncertified hardware imports from non-EU manufacturing centers face automatic market exclusion, limiting supplier diversity.
- Acquiring network concentration:Domestic clearing relationships concentrate through JCC Payment Systems Ltd, creating dependency risk for terminal vendors seeking bank placement.
- EMVCo specification constraints:Chip architecture approvals filter hardware options, extending product development timelines for new market entrants.
Strategic Opportunities
- Paphos and Larnaca retail corridors:Secondary cities outside Limassol-Nicosa axis remain underpenetrated for contactless terminal deployment.
- EU digital identity wallet integration:Terminal estates may require premature replacement cycles as authentication protocols evolve, creating hardware demand pull-forward.
- Self-service kiosk deployment:Airport and ferry terminal environments present viable payback periods where labor costs and passenger throughput justify capital investment.
Industry Challenges
- Firmware integration complexity:PSD2 compliance requirements demand real-time authentication protocol updates that strain legacy terminal architectures.
- Certification timeline compression:EMVCo and PCI DSS recertification cycles must accelerate to match regulatory mandate deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyprus POS Terminals Market |
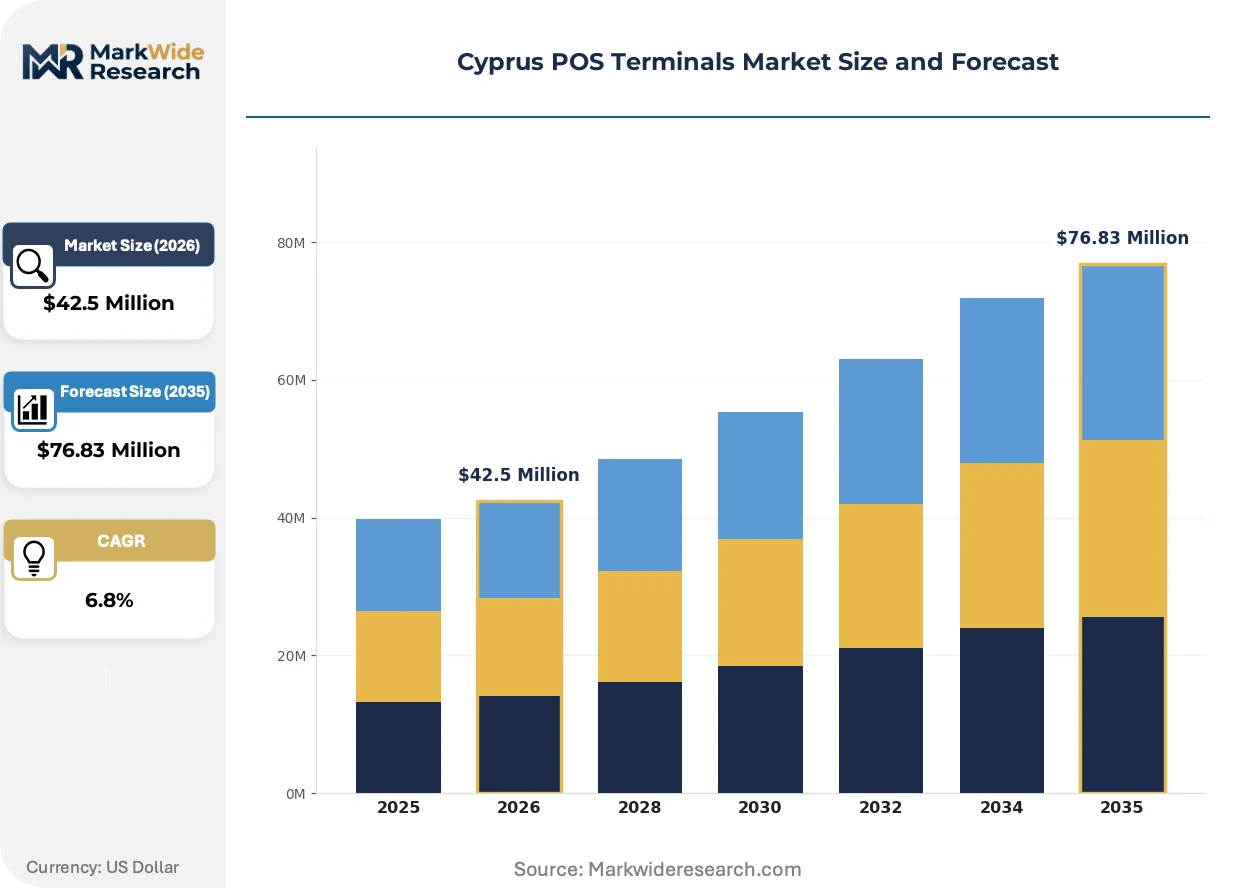
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $76.83 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Self-service Kiosks, Contactless Terminals Technology: EMV, NFC, QR Code, Bluetooth End User: Retailers, Restaurants, Hospitality, Transportation Installation: On-premise, Cloud-based, Hybrid, Remote Access |
| Companies Covered | Pay Expert, Vpayments (G A P Vassilopoulos Group), VeriFone Inc, PBT Payment Solutions, Omnisys POS Systems Ltd, DATECS Ltd, Link4Pay, Powersoft Computer Solutions Ltd, JCC Payment Systems Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyprus POS Terminals Market Strategic Shifts
Payment infrastructure across Cyprus is converging toward software-defined architectures that decouple transaction processing from dedicated hardware. This shift compresses vendor margins while opening new service revenue streams.
SoftPOS technology is collapsing the distinction between merchant smartphones and dedicated payment terminals. Food delivery platforms and seasonal pop-up vendors in coastal tourism zones are adopting NFC-enabled phones for card acceptance. This compression eliminates hardware procurement barriers for micro-merchants while eroding the addressable market for entry-level terminal manufacturers.
The Central Bank of Cyprus enforces PSD2 strong customer authentication rules that reshape terminal firmware requirements and transaction routing protocols. PCI DSS certification gates market access, filtering uncertified hardware imports from non-EU manufacturing centers. Hospitality merchants in Limassol and Nicosia corridors are responding by accelerating refresh cycles to ensure compliance before enforcement deadlines.
Merchant procurement patterns are fragmenting across channel types. Large hotel chains negotiate directly with terminal vendors through acquiring-bank partnerships, while independent retailers rely on ISOs and payment facilitators. This bifurcation is most visible in coastal tourism districts where chain penetration contrasts with family-owned tavernas and souvenir shops.
Cyprus POS Terminals Market Segmentation
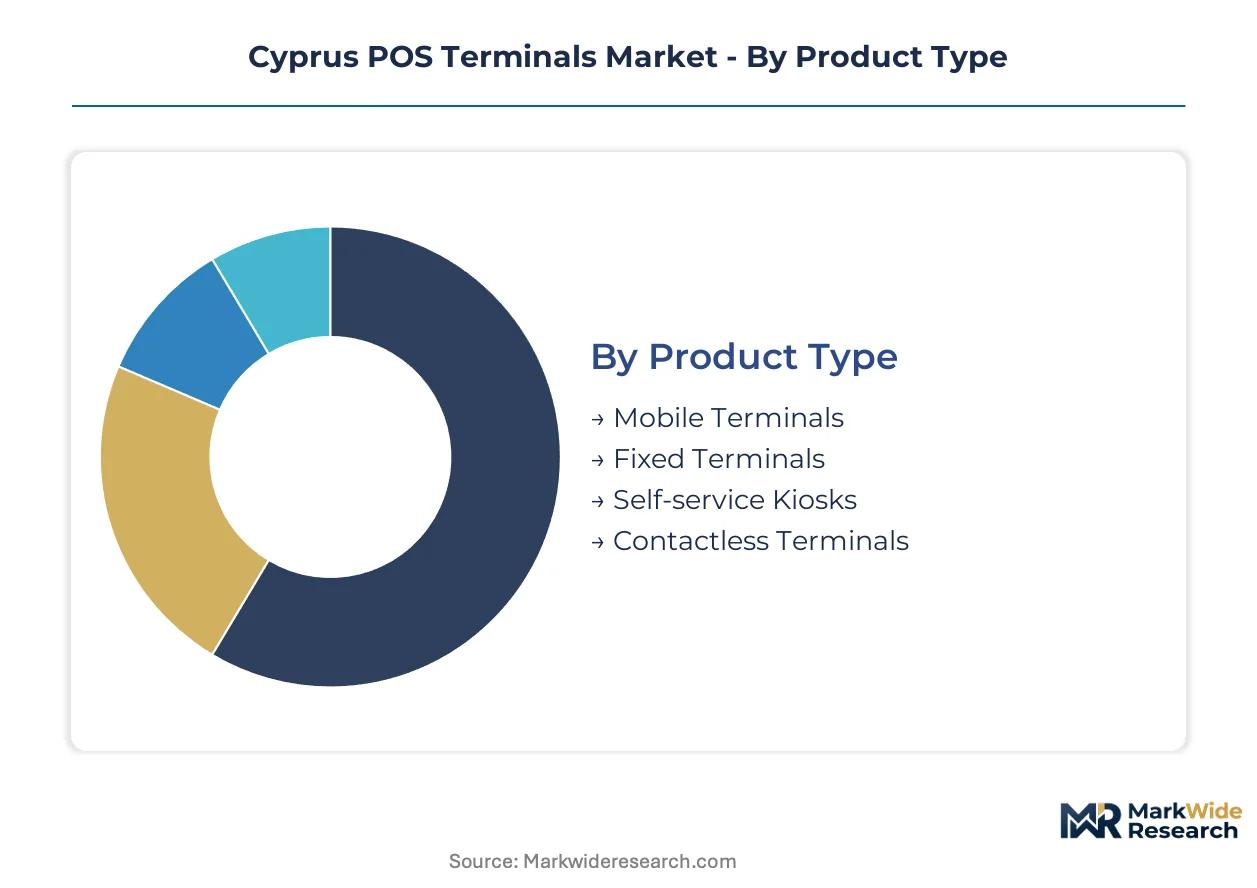
Cyprus POS terminal procurement patterns fragment sharply across merchant scale and operational environment. Coastal tourism corridors concentrate premium hardware demand, while inland retail favors cost-optimized configurations. Understanding these segment boundaries clarifies where firmware compliance costs and channel partnerships reshape competitive outcomes.
Product Type:
Merchant mobility requirements span countertop permanence to fully portable configurations across Cypriot retail and hospitality estates.
- Mobile Terminals:Battery-powered units with cellular or Wi-Fi connectivity enable transaction capture away from fixed counters. Food delivery vendors and seasonal beach concessions in Ayia Napa deploy these to eliminate dedicated hardware overhead. The Central Bank of Cyprus PSD2 firmware mandates accelerate refresh cycles for older Bluetooth-only units lacking secure element architectures.
- Contactless Terminals:NFC-enabled devices process tap-to-pay transactions under EMVCo specifications with sub-second authentication latency. Hotel lobbies and high-volume retail in Limassol corridors prioritize these for tourist throughput speed where queue compression drives revenue protection.
- Fixed Terminals:Ethernet-connected countertop units with integrated receipt printers dominate established retail and supermarket environments. PCI DSS certification gates exclude uncertified imports from Asian manufacturing centers.
- Self-service Kiosks:Unattended payment stations with integrated card readers and touchscreen interfaces. Larnaca International Airport and ferry terminals host the primary installed base where labor substitution justifies capital intensity.
The dominant share belongs to Contactless Terminals, while Mobile Terminals is closing the gap fastest.
Technology:
Authentication protocols and communication standards determine hardware compatibility across Cyprus acquiring networks.
- EMV:Chip card transaction standards mandated by the Central Bank of Cyprus for counterfeit fraud prevention. Terminal estates lacking EMV Level 3 certification face network exclusion, forcing hardware replacement across Nicosia retail corridors.
- NFC:Near-field communication enables contactless payment acceptance at 13.56 MHz frequency with tokenized transaction security. Tourism-dependent merchants in Paphos coastal districts prioritize NFC for Apple Pay and Google Wallet compatibility.
- QR Code:Optical scanning of merchant-presented or customer-presented barcodes for account-to-account transfers. Limited adoption outside Chinese tourist-facing merchants in Limassol.
- Bluetooth:Short-range wireless pairing between payment accessories and host devices. Peripheral connectivity for tablet-based POS systems in boutique retail outside major urban centers.
EMV retains the largest installed base, though NFC is expanding most quickly as contactless transaction volume climbs.
End User:
Vertical-specific operational rhythms shape terminal feature priorities and procurement channel preferences.
- Hospitality:Hotels and resorts require property management system integration with pre-authorization and multi-currency settlement capabilities. Large chains in Limassol negotiate directly through JCC Payment Systems acquiring partnerships.
- Restaurants:Tableside payment acceptance and tip-adjustment workflows dominate specification requirements. Family-owned tavernas in rural districts rely on ISOs for hardware procurement.
- Retailers:Supermarkets and specialty stores prioritize inventory system integration with high-volume transaction throughput. PCI DSS compliance deadlines accelerate refresh decisions.
- Transportation:Ferry operators and airport concessionaires need ruggedized terminals with offline transaction storage. Self-service kiosk deployment concentrates in Larnaca and Paphos aviation infrastructure.
Hospitality commands the deepest terminal penetration per merchant, while Restaurants is gaining share fastest as tableside payment adoption spreads.
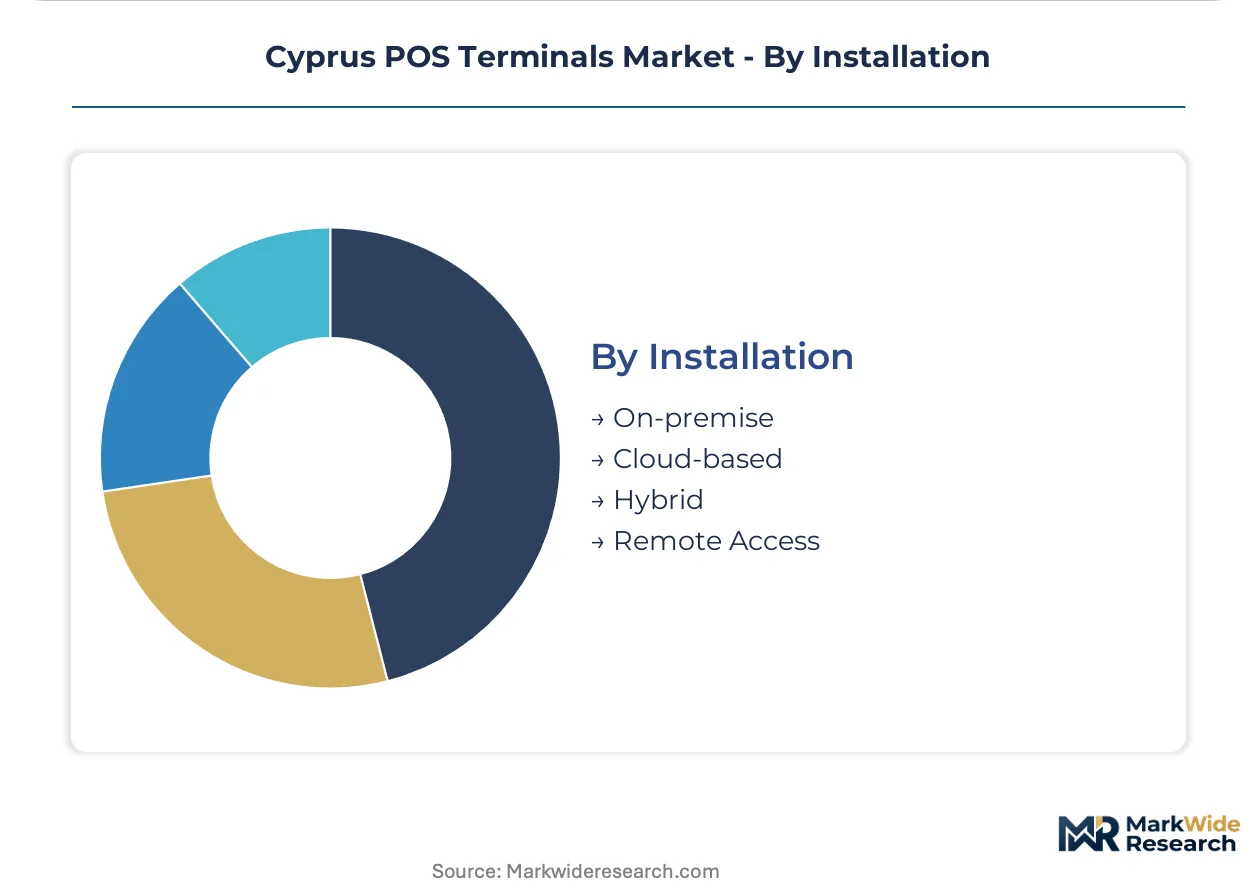
Installation:
Deployment architecture determines capital expenditure patterns and ongoing vendor relationship structures.
- Cloud-based:Transaction data routes to remote servers with software updates delivered over-the-air. Small retail outside Nicosia and Limassol favors this model to minimize IT staffing requirements.
- Hybrid:Local transaction processing with cloud reconciliation and backup functionality. Mid-size hospitality chains balance latency sensitivity with centralized reporting needs.
- On-premise:Dedicated server infrastructure within merchant facilities with full data sovereignty. Large hotel groups with legacy property management investments maintain this architecture.
- Remote Access:Terminal management and troubleshooting conducted via secure VPN connections. ISOs serving dispersed retail estates rely on this capability to reduce field service costs.
Cloud-based deployment holds the dominant position, while Hybrid is climbing the fastest as mid-market merchants seek architectural flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Bank of Cyprus enforces PSD2 strong customer authentication mandates that reshape terminal procurement across all coastal and inland districts. These regulatory deadlines concentrate hardware refresh activity in merchant corridors with the highest transaction volumes. District-level variation in tourism density and retail infrastructure creates distinct deployment patterns.
Limassol
Hotel chains and beachfront hospitality venues drive contactless terminal demand along the southern coast. The Central Bank of Cyprus compliance deadlines accelerate replacement of legacy magnetic-stripe hardware in this high-volume corridor. JCC Payment Systems Ltd maintains dominant acquiring relationships with large resort properties concentrated near the marina district.
Nicosia
Government procurement and financial services anchor fixed terminal installations in the capital's retail banking corridors. PCI DSS certification requirements filter out uncertified hardware imports from non-EU manufacturing centers. DATECS Ltd competes aggressively on price for small retail deployments in suburban shopping districts outside the walled city core.
Paphos
Archeological tourism and seasonal hospitality create intermittent demand spikes for mobile terminal configurations. The Central Bank of Cyprus mandates push family-owned tavernas toward ISO-mediated procurement channels. Coastal concessions in the Kato Paphos tourist zone adopt SoftPOS alternatives to eliminate dedicated hardware overhead.
Larnaca
Airport infrastructure and ferry terminal operations sustain the island's primary self-service kiosk installed base. EMVCo specification constraints limit which chip architectures gain acceptance across domestic acquiring networks. Labor substitution economics justify capital-intensive unattended payment stations where passenger throughput exceeds manual processing capacity.
Ayia Napa
Seasonal beach concessions and nightlife venues concentrate mobile terminal demand during peak tourism months. Food delivery platforms deploy smartphone-based card acceptance to serve dispersed merchant locations. Firmware integration complexity from PSD2 compliance strains legacy Bluetooth-only units lacking secure element architectures.
Cyprus POS Terminals Market Competitive Environment
On the supply side, the industry is bifurcated between bank-anchored infrastructure providers and price-competitive hardware specialists serving fragmented retail. VeriFone Inc leverages acquiring partnerships to secure premium placement in hospitality chains. JCC Payment Systems Ltd controls domestic clearing relationships that gate terminal vendor access to merchant accounts. Strategic archetypes include bank-integrated platform vendors, ISO-dependent hardware suppliers, and emerging SoftPOS enablers. Competitive moves concentrate on firmware certification acceleration and channel partnership exclusivity.
Among the bank-integrated tier, VeriFone Inc and JCC Payment Systems Ltd occupy positions shaped by their respective acquiring alliances. DATECS Ltd exemplifies the price-competitive specialist archetype targeting small retail outside major urban centers. These three anchors illustrate how vendor fortunes tie to channel structure rather than product differentiation alone.
| Leading Market Players |
|---|
| Pay Expert |
| Vpayments (G A P Vassilopoulos Group) |
| VeriFone Inc |
| PBT Payment Solutions |
| Omnisys POS Systems Ltd |
| DATECS Ltd |
| Link4Pay |
| Powersoft Computer Solutions Ltd |
| JCC Payment Systems Ltd |
| Others |
Value Chain & Pricing Dynamics
Piraeus-Limassol maritime freight corridors transmit semiconductor component costs from East Asian manufacturing hubs directly into Cypriot terminal landed prices, compressing margins for distributors serving price-sensitive inland retail while enabling premium positioning for PSD2-compliant hardware in coastal hospitality corridors.
Pricing Analysis
Certification level (PCI DSS/EMVCo/PSD2-compliant) creates the primary spread between hardware tiers. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with firmware-upgradeable units commanding substantial premiums over legacy magnetic-stripe terminals. Cost compression in economy-tier fixed terminals is intensifying because SoftPOS alternatives eliminate dedicated hardware requirements for micro-merchants. Family-owned tavernas and seasonal beach concessions exhibit highest price sensitivity, while large hotel chains negotiating through JCC Payment Systems acquiring partnerships demonstrate lowest sensitivity to unit costs.
Supply Chain Analysis
Secure element chipsets and NFC antenna modules feed from Taiwan, South Korea, and mainland China manufacturing clusters into Cypriot assembly and distribution networks. Terminal production draws from Taiwanese semiconductor foundries for payment processors, Chinese PCB fabrication facilities, and German precision component suppliers for EMV contact assemblies. Single-source vulnerability concentrates in EMVCo-certified secure element supply, where qualified vendors number fewer than six globally. Distribution runs through Athens-based regional hubs into JCC Payment Systems warehousing, with final-mile deployment managed by ISO networks serving dispersed retail estates outside Limassol-Nicosia corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through JCC Payment Systems' dominance of domestic acquiring relationships, fragmenting vendor pricing leverage as merchant procurement consolidates around bank-mediated channels rather than direct hardware negotiations.
For Market Incumbents: Entrench firmware certification capabilities as the primary defensive moat against SoftPOS displacement. Accelerate EMVCo pre-certification pipelines to compress product launch timelines before regulatory deadlines tighten. Channel control through exclusive JCC Payment Systems partnerships represents the critical lever for maintaining hospitality chain placement against DATECS Ltd price competition in secondary cities. For New Entrants and Emerging Players: Paphos and Larnaca retail corridors outside the Limassol-Nicosia axis offer underpenetrated white-space for contactless terminal deployment. Food delivery platform integration presents the most penetrable segment, with API-first terminal architectures enabling rapid merchant onboarding without legacy property management system complexity. ISO-mediated procurement channels in rural districts provide the essential go-to-market angle to bypass bank-anchored incumbent relationships. For Investors and Strategic Acquirers: Firmware-specialist terminal vendors with pre-certified PSD2 compliance pipelines represent the priority acquisition archetype for portfolio positioning ahead of regulatory enforcement windows. Long-term viability hinges on software-defined architecture transitions that decouple recurring service revenue from hardware shipment cyclicality. The signal to watch is Central Bank of Cyprus digital identity wallet integration timelines, which would force premature replacement cycles and hardware demand pull-forward.| Strategic Initiative | Industry Significance |
|---|---|
| PSD2 Firmware Pre-Certification Investment | Accelerates time-to-revenue ahead of Central Bank enforcement deadlines in hospitality corridors. |
| SoftPOS Platform Integration | Captures food delivery and pop-up merchant segments abandoning dedicated hardware procurement. |
| ISO Channel Partnership Expansion | Penetrates family-owned retail in Paphos and Larnaca outside bank-anchored distribution networks. |
| Self-Service Kiosk Deployment | Addresses labor substitution economics at Larnaca International Airport and ferry terminal environments. |
| EU Digital Identity Wallet Readiness | Positions terminal estates for authentication protocol evolution requiring hardware refresh cycles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement directors, retail ISO account managers, JCC Payment Systems integration specialists, and Central Bank of Cyprus regulatory compliance officers. Secondary validation incorporated Central Bank circulars on PSD2 implementation, PCI DSS certification registries, EMVCo product approval listings, and Cyprus Statistical Service retail trade data. Bottom-up merchant installation estimates triangulated against top-down banking channel shipment reports.
Calibration across the analysis window employed segment-specific growth rate derivation from hardware refresh cycle modeling, tourism arrival correlations with terminal density, and regulatory mandate impact assessment. Segmentation dimensions modeled include product mobility configuration, authentication technology standard, end-user vertical, and deployment architecture. CAGRs were computed from installed base evolution and average selling price trajectories, with particular weighting applied to SoftPOS adoption curves and self-service kiosk penetration in transportation infrastructure.
The forecast holds incumbent behavior within observed patterns; aggressive moves by SoftPOS platform providers or accelerated EU digital identity wallet mandates would shift outcomes. Material shifts in Central Bank of Cyprus enforcement timelines or JCC Payment Systems acquiring network restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Japan POS Terminals Market
Payments
United States Clearing Houses and Settlements Market
Payments
China POS Terminals Market
Payments
Europe Credit Cards Market
Payments
In-Vehicle Payment Services Market
Payments
United Kingdom Payment Market
Payments
Freight Audit and Payment Service Market
Payments
New Zealand Payments Market
Payments
Singapore Remittance Market
Payments
United Kingdom Real Time Payments Market
Payments
Social Media Payment Solution Market
Payments
Europe Accounts Payable Automation Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Thailand Mobile Payments Market
Payments
Israel Credit Cards Market