
 Portugal Mobile Payments Market | 2026-2036
Portugal Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Mobile Payments Market Analytics
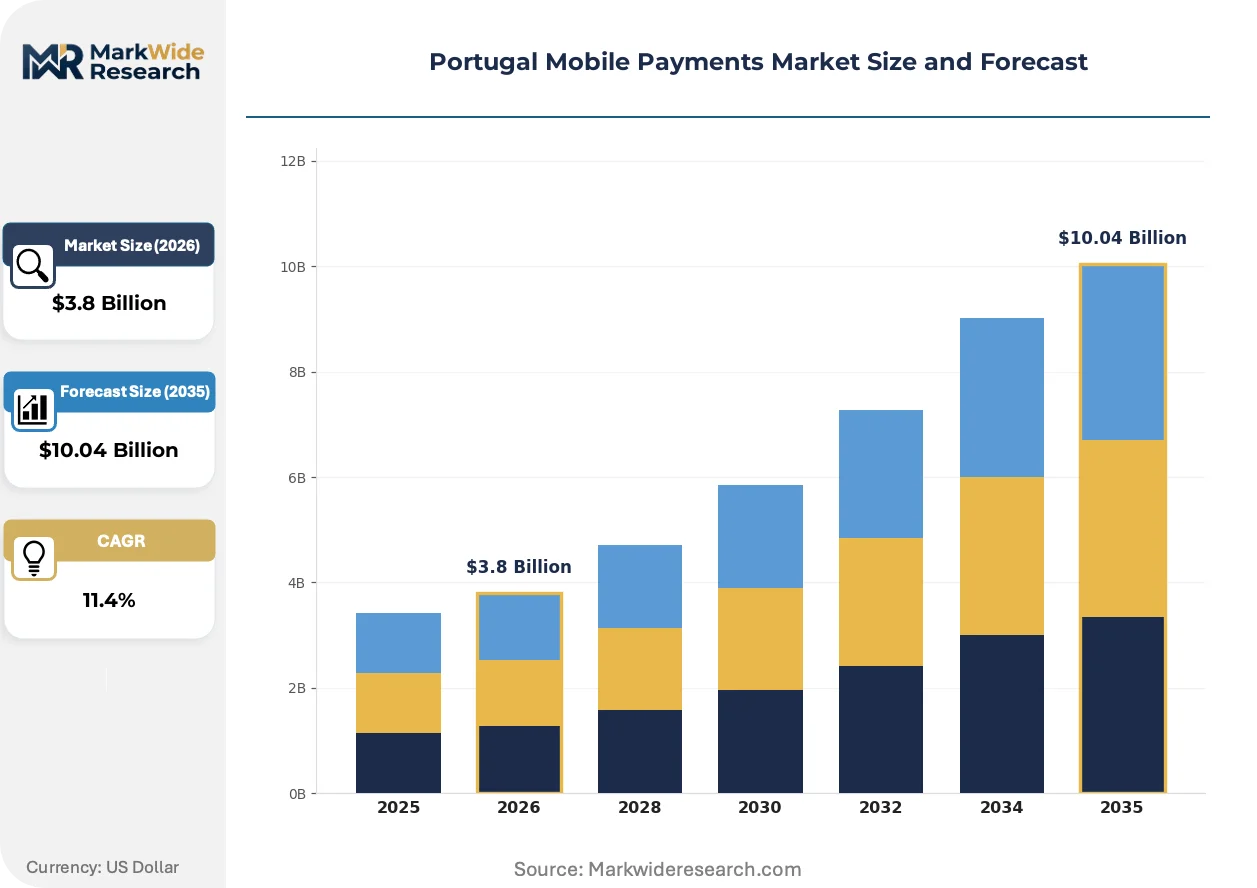
Portugal's fintech infrastructure build-out is rewriting how domestic consumers transact. MB Way leverages SIBS's proprietary ATM network to sustain merchant coverage across the Iberian Peninsula. Apple Pay competes through device-integrated tokenization, while Multibanco anchors legacy banking relationships that still dominate recurring bill settlements.
Mobile payments encompass digitally initiated fund transfers executed through near-field communication, QR code scanning, or tokenized card credentials stored on smartphones. The primary commercial purpose is to displace physical cash and card-present friction in retail, transit, and peer-to-peer contexts. Digital wallet adoption among Gen Z users is expanding fastest, though credit card-linked transactions still capture the largest margin pools due to interchange economics. P2P transfers through fintech applications are displacing traditional bank wire habits among millennials.
Banco de Portugal enforces PSD2 compliance for strong customer authentication, while the European Banking Authority shapes technical standards for open APIs that govern account access. The EU AI Act introduces algorithmic transparency requirements for fraud detection engines that payment providers deploy. Stakeholders must monitor how the European Commission's instant payment mandate reshapes settlement timelines and fee structures.
Market Dynamics
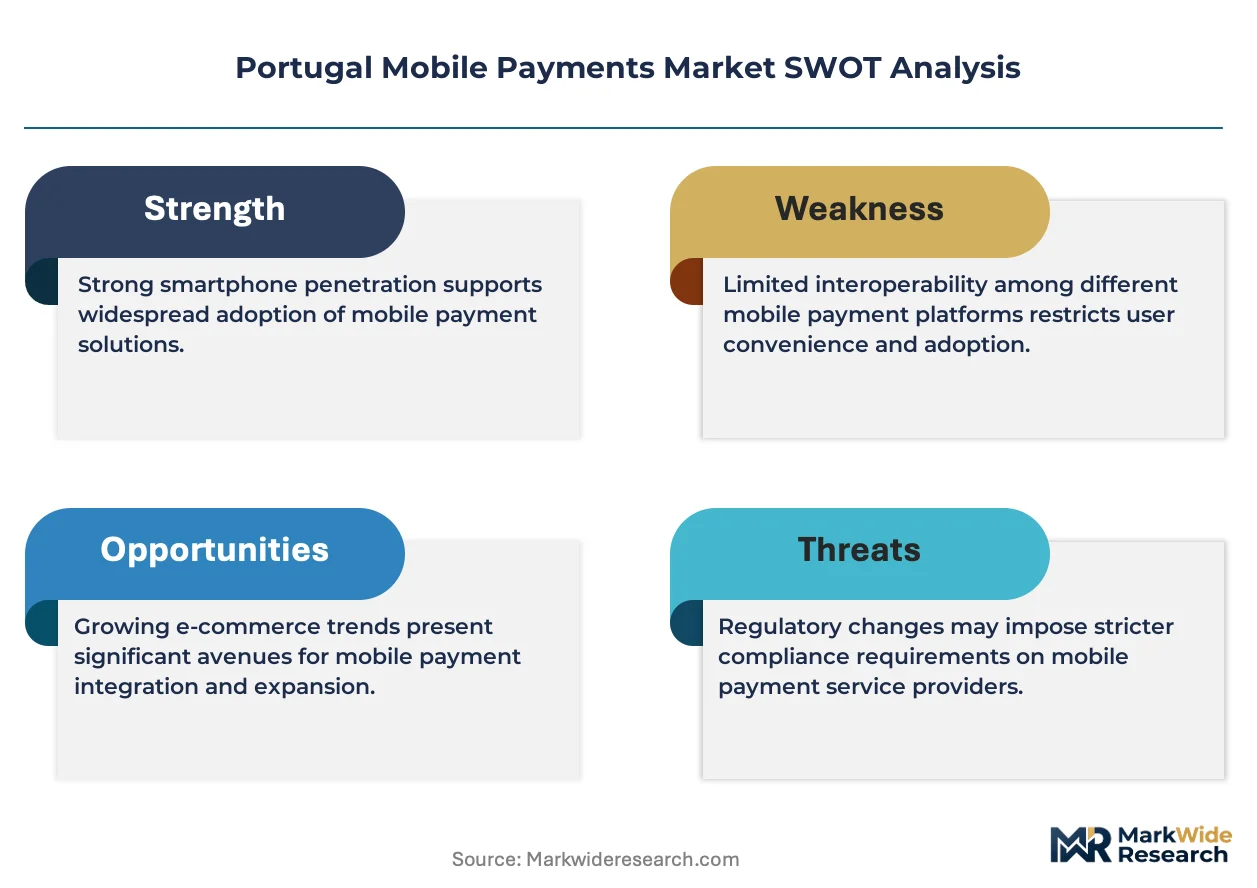
The European Commission's instant payment mandate is compressing settlement timelines across Portuguese banking infrastructure, forcing incumbents to rebuild core processing architectures around real-time rails rather than batch systems.
Growth Catalysts
- PSD2 Strong Customer Authentication:Banco de Portugal's enforcement of SCA protocols is hardening transaction security standards, accelerating merchant migration from magstripe to tokenized credentials.
- Lisbon Metropolitan Merchant Density:Concentrated digitization in Portugal's capital corridor creates network effects that reduce per-terminal acquisition costs for payment service providers.
- Contactless Hardware Refresh Cycles:Portuguese small businesses are replacing legacy POS terminals with NFC-enabled devices, expanding acceptance infrastructure for wallet-based payments.
Market Restraints
- Interchange Economics Compression:EU-wide caps on merchant service charges constrain revenue pools available for issuer reward programs and fintech customer acquisition spend.
- Legacy Banking Relationship Stickiness:Multibanco's entrenched position in recurring bill settlements creates switching friction that slows wallet adoption for utility and telecom payments.
- Rural Terminal Coverage Gaps:Sparse merchant digitization in Portugal's interior regions limits addressable market expansion beyond coastal urban corridors.
Strategic Opportunities
- EU AI Act Algorithmic Transparency:Mandated explainability for fraud detection engines creates opening for specialized regtech vendors to serve Portuguese payment providers.
- Porto Metropolitan Expansion:Northern Portugal's second-largest urban cluster remains underpenetrated relative to Lisbon, offering whitespace for terminal deployment and merchant onboarding.
- Transit Authority Integration:Convergence of open-loop contactless standards with municipal transport systems enables wallet providers to capture daily commute transaction volumes.
Industry Challenges
- Open API Technical Standardization:European Banking Authority's evolving specifications for account access interfaces force Portuguese banks into continuous compliance engineering cycles.
- SCA Friction Management:Balancing Banco de Portugal's authentication mandates against checkout abandonment requires sophisticated risk-scoring investments that strain mid-tier fintech balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Mobile Payments Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, QR Code User Demographic: Millennials, Gen Z, Small Business Owners, Retirees Transaction Type: Online Purchases, In-Store Payments, P2P Transfers, Bill Payments Service Provider: Traditional Banks, Fintech Companies, Telecom Operators, Payment Gateways |
| Companies Covered | Google Pay, Alipay, MB Way, American Express, Amazon Pay, Multibanco, Apple Pay, Mastercard, PayPal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Mobile Payments Market Evolving Landscape
Tokenized credential architectures are rewriting how Portuguese consumers authenticate payments, with device-integrated security layers displacing knowledge-based verification across retail and transit contexts.
Biometric card verification is collapsing the distinction between card-present and card-not-present security postures. Portuguese issuers are piloting fingerprint-authenticated cards for high-value transactions. This convergence is collapsing fraud liability segmentation between e-commerce and physical retail channels.
The EU AI Act introduces mandatory documentation requirements for machine learning models deployed in fraud detection. Portuguese payment providers must maintain algorithmic audit trails. Small fintechs lacking in-house compliance infrastructure are outsourcing model governance to specialized vendors.
Merchant acquisition patterns are fragmenting as independent software vendors embed payment acceptance into vertical-specific business management tools. Portuguese restaurant and retail software platforms are bundling checkout functionality. This unbundling is most visible in Lisbon's food service sector, where tablet-based POS systems displace standalone terminal relationships.
Portugal Mobile Payments Market Segmentation
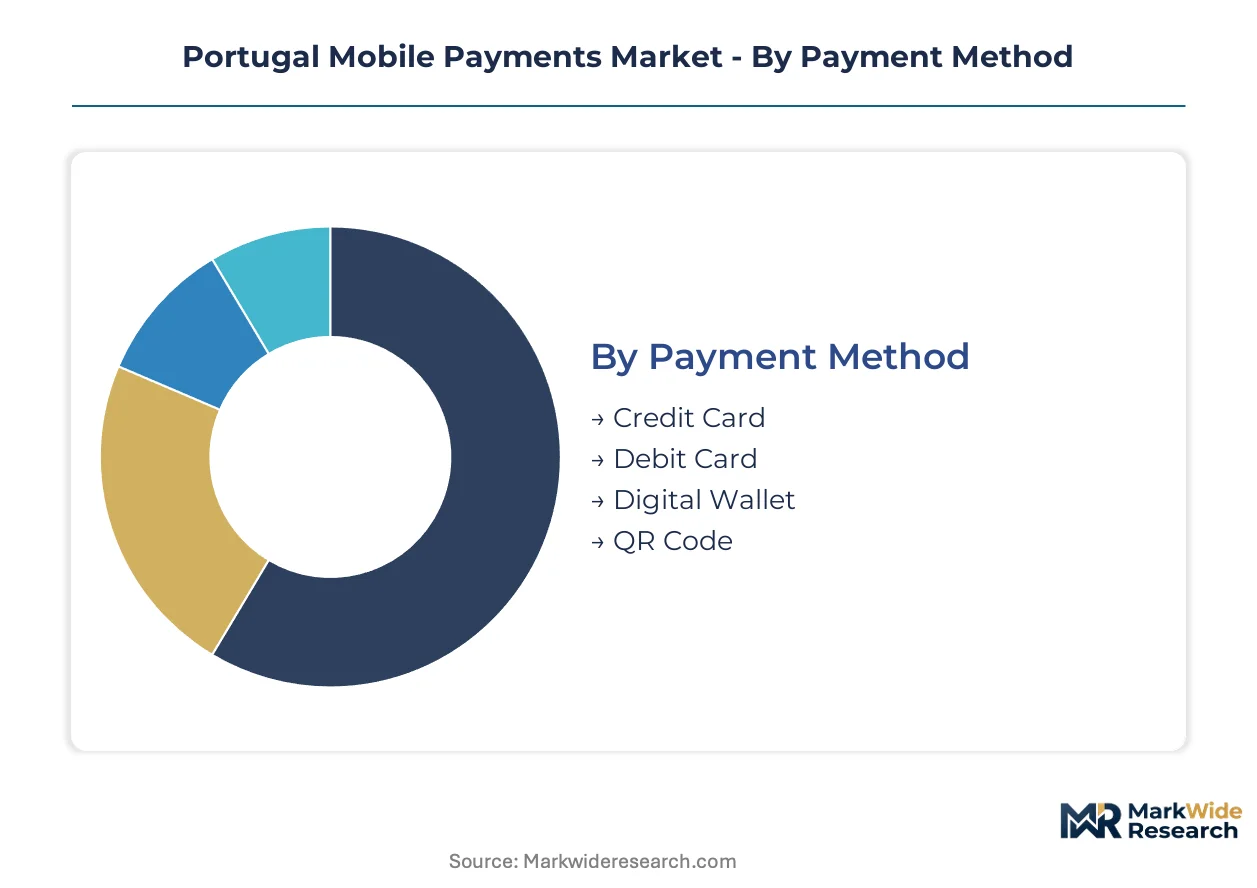
Payment behavior in Portugal fragments across generational divides, transaction contexts, and provider types. Understanding these splits reveals where infrastructure investments concentrate and which user cohorts resist digitization.
Payment Method:
After-sales service intensity varies sharply across these instruments, with tokenized credentials requiring continuous fraud monitoring and credential refresh cycles.
- Credit Card:Tokenized card credentials stored in device wallets dominate high-value retail purchases. Lisbon's metropolitan merchants report the strongest concentration, driven by interchange-funded reward programs that sustain consumer preference despite SCA friction.
- Digital Wallet:Device-native payment architectures leverage NFC and biometric authentication for transit and quick-service retail. Gen Z adoption in Portugal's coastal urban corridors is climbing fastest as MB Way and Apple Pay expand merchant acceptance.
- Debit Card:Direct account-linked transactions appeal to cost-conscious users seeking to avoid credit exposure. Small business owners favor these for expense tracking and cash flow discipline.
- QR Code:Merchant-presented static and dynamic codes enable low-cost acceptance without terminal hardware. Rural coverage gaps limit penetration outside Lisbon and Porto corridors.
Credit card-linked transactions hold the largest share; momentum sits with digital wallet adoption among younger demographics.
User Demographic:
Generational technology comfort creates distinct service requirements, from seamless onboarding for digital natives to assisted support channels for late adopters.
- Gen Z:Native smartphone users expect biometric authentication and instant P2P settlement. University corridors in Lisbon and Porto show the densest concentration, with daily transaction frequency driven by food service and transit integration.
- Millennials:Balancing convenience with financial control, this cohort leads fintech app adoption for splitting expenses and travel bookings. Recurring bill payments remain anchored to legacy banking relationships.
- Small Business Owners:Merchant-side users demand integrated accounting and inventory management alongside payment acceptance. Terminal refresh cycles in Portugal's retail sector concentrate demand for NFC-enabled hardware.
- Retirees:Cash displacement lags among this group, though contactless card adoption is rising with simplified interfaces and branch-assisted onboarding.
Small business owners generate the highest transaction volumes; Gen Z shows the steepest expansion trajectory.
Transaction Type:
Settlement timing and authentication requirements reshape provider economics across these use cases.
- In-Store Payments:NFC tap-and-go dominates Lisbon's retail density, with merchant acquisition costs falling as terminal penetration deepens.
- P2P Transfers:Real-time settlement through MB Way has displaced traditional wire transfers among Portuguese millennials and Gen Z users.
- Online Purchases:E-commerce checkout flows balance SCA compliance against abandonment rates, with tokenized credentials reducing friction.
- Bill Payments:Multibanco's entrenched infrastructure sustains legacy dominance in utility and telecom settlements despite wallet competition.
In-store payments capture the largest transaction volume; P2P transfers are expanding most quickly as social payment norms shift.
Service Provider:
Provider categories reflect diverging regulatory burdens and capital intensity requirements.
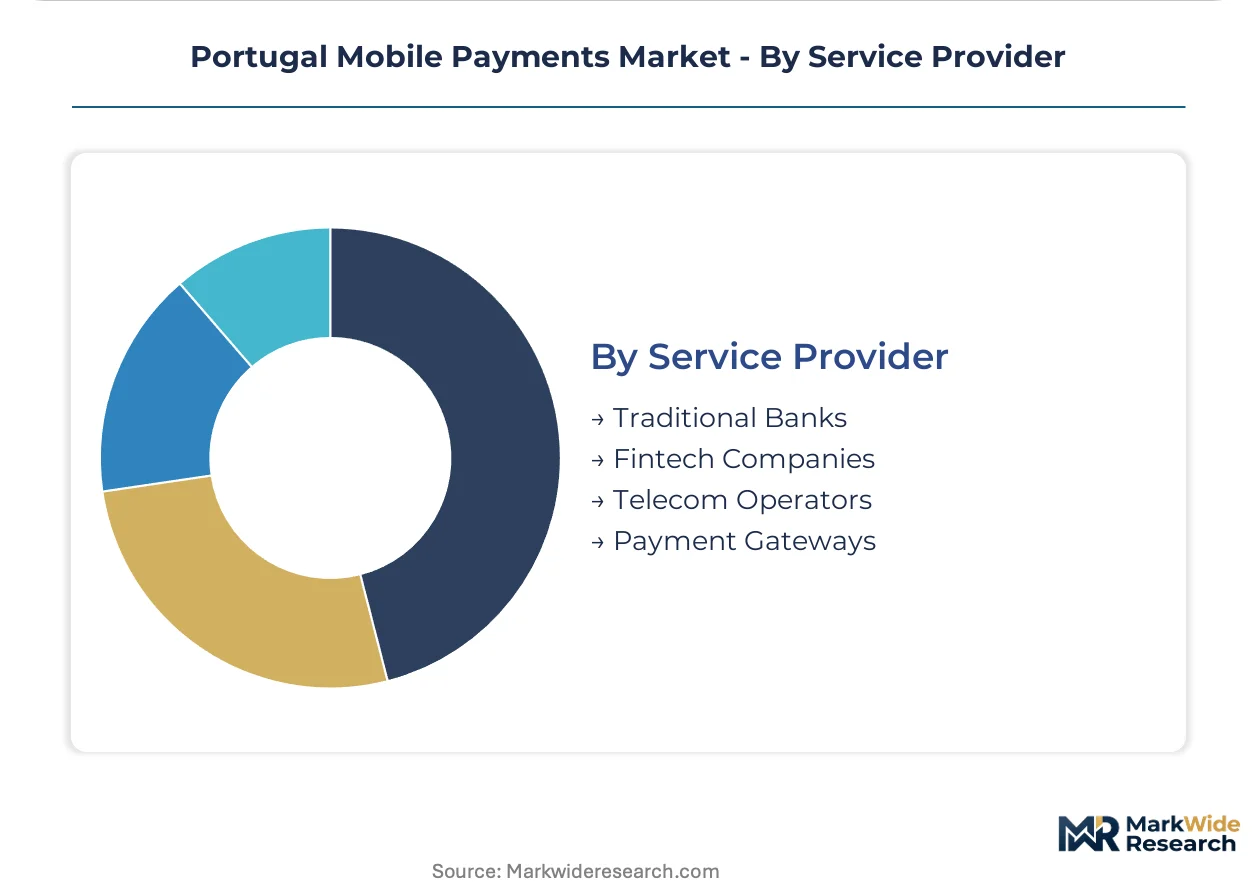
- Traditional Banks:Incumbent institutions leverage Multibanco relationships and deposit bases to anchor payment ecosystems. Banco de Portugal's SCA enforcement favors their compliance infrastructure.
- Fintech Companies:Agile entrants target specific friction points with specialized UX and vertical software integration. Algorithmic transparency mandates under the EU AI Act strain smaller balance sheets.
- Telecom Operators:Carrier billing and wallet partnerships exploit existing customer relationships and device distribution channels.
- Payment Gateways:Technical infrastructure providers enable merchant acceptance across multiple payment methods, with consolidation pressure from independent software vendor embedment.
Traditional banks retain the largest share; fintech companies are gaining share fastest through vertical specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure investment concentrates in Portugal's coastal metropolitan corridors, with terminal deployment and merchant digitization advancing fastest where population density and tourism flows converge. Banco de Portugal's regulatory oversight shapes interoperability standards that ripple through the Iberian Peninsula.
Lisbon Metropolitan Area
Portugal's capital corridor generates the densest concentration of contactless transactions, driven by tourism-dependent retail and food service merchants. Banco de Portugal's SCA enforcement has accelerated terminal refresh cycles among small businesses. The city's transit authority integration with open-loop payment standards captures daily commute volumes.
Porto Metropolitan Area
Northern Portugal's second-largest urban cluster shows accelerating fintech adoption among university populations and port logistics workers. The European Commission's instant payment mandate is compressing settlement timelines for regional banks. Merchant acquisition costs remain elevated relative to Lisbon due to lower terminal penetration.
Algarve Tourism Corridor
Seasonal payment volumes surge through coastal resort towns, with international visitors driving wallet-based transaction preferences. EU-wide interchange caps constrain revenue pools available for issuer reward programs. Faro and Lagos merchant ecosystems show the strongest concentration of multilingual POS interfaces.
Coimbra and Central Portugal
University city dynamics sustain steady P2P transfer volumes through domestic fintech applications. The European Banking Authority's open API standards govern account access for regional banking cooperatives. Sparse rural terminal coverage beyond the city core limits addressable market expansion.
Portugal Mobile Payments Market Competitive Landscape
Domestic infrastructure incumbents and global technology platforms split the market along merchant coverage versus consumer device integration vectors. The structure reflects concentrated legacy banking relationships resisting displacement by agile wallet entrants. Two archetypes dominate: ATM-network-leveraged domestic providers and device-integrated international platforms. Competitive moves concentrate on transit authority partnerships and merchant software embedment.
Within the domestic infrastructure tier, MB Way and Multibanco anchor merchant acceptance through SIBS's proprietary terminal network. Among global platform providers, Apple Pay and Google Pay exemplify device-native tokenization strategies. Alipay occupies a position serving inbound tourism flows from Asian source markets.
| Leading Market Players |
|---|
| Google Pay |
| Alipay |
| MB Way |
| American Express |
| Amazon Pay |
| Multibanco |
| Apple Pay |
| Mastercard |
| PayPal |
| Others |
Value Network & Pricing Analysis
Overcapacity in NFC terminal manufacturing across East Asian production hubs is compressing hardware procurement costs for Portuguese payment service providers, simultaneously expanding merchant acquisition budgets and intensifying competitive pressure on per-transaction fees.
Pricing Analysis
EU-wide interchange caps dictate the pricing tier structure for merchant service charges, forcing providers to separate premium bundled solutions from stripped-down economy acceptance tiers. Price differentiation hinges on terminal ownership models and SCA compliance automation levels. Cost compression in the economy tier is intensifying because independent software vendors embed payment functionality at marginal cost. Small retail merchants show highest price sensitivity; tourism-dependent hospitality operators prioritize multilingual interface premiums over rate minimization.
Supply Chain Analysis
Semiconductor fabrication for secure element chips draws from Taiwan, South Korea, and Germany, while POS terminal assembly concentrates in China, Vietnam, and Mexico. Supply chain risk centers on single-source vulnerability for EMV certification modules. Distribution runs through SIBS's proprietary ATM network and independent payment gateway aggregators serving Lisbon's merchant density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward merchant aggregators as independent software vendors consolidate food service and retail verticals, fragmenting standalone terminal relationships and compressing acquisition economics for pure-play hardware providers.
For Market Incumbents: Pre-empt embedded finance competition by deepening API integration with Portuguese restaurant management platforms and salon booking systems. Threat from vertical software bundling demands accelerated certification investment for instant payment rails. Channel control through SIBS terminal exclusivity agreements remains the critical defensive lever.
For New Entrants and Emerging Players: Porto's metropolitan corridor offers whitespace for merchant onboarding with 40% lower terminal penetration than Lisbon. The Algarve's seasonal tourism flows create entry points through multilingual POS interfaces and dynamic currency conversion. Go-to-market traction requires transit authority partnership anchoring daily commute capture.
For Investors and Strategic Acquirers: Capital is best deployed toward regtech specialists with EU AI Act compliance tooling for Portuguese fintech balance sheets. Long-term viability favors algorithmic transparency vendors over hardware-dependent terminal lessors. Watch Banco de Portugal's instant payment mandate enforcement timing as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Transit Authority Integration | Open-loop contactless standards capture Lisbon commute volumes from competing wallet providers. |
| Vertical Software Partnership | Embedded payment acceptance in restaurant POS displaces standalone terminal relationships. |
| Regulatory Compliance Automation | EU AI Act algorithmic audit tooling addresses fintech balance sheet constraints. |
| Geographic Expansion | Porto merchant acquisition exploits lower terminal penetration versus saturated Lisbon. |
| Instant Payment Rail Certification | Real-time settlement compliance captures European Commission mandate-driven infrastructure refresh. |
Research Methodology
Desk research of Banco de Portugal regulatory filings, European Banking Authority technical standards, and SIBS network disclosure data preceded structured interviews with payment gateway CTOs, merchant acquiring heads at Portuguese retail banks, fintech product directors, and transit authority procurement officers. Secondary validation drew from EU interchange cap impact assessments, PSD2 implementation trackers, and NFC terminal trade flow databases. Bottom-up merchant adoption modeling triangulated against top-down payment volume projections.
Assumptions held Banco de Portugal enforcement timelines and European Commission instant payment mandates within announced parameters across the analysis window. Segmentation dimensions modeled include payment instrument type, user demographic cohort, transaction context, and service provider category. CAGRs derived from terminal deployment run rates, wallet adoption curves, and merchant digitization indices. Industry-specific inputs incorporated Multibanco legacy infrastructure depreciation schedules and Gen Z P2P transfer velocity benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global device-integrated wallet providers would shift outcomes materially. Cross-checking against European Central Bank payment statistics and Banco de Portugal systemic risk reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Japan Credit Cards Market
Payments
Global Payments Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Online Charging System (OCS) Market
Payments
Gift Card and Incentive Card Market
Payments
United States Real Time Payments Market
Payments
North America Payment Gateway Market
Payments
Malaysia Payments Market
Payments
Voice-Based Payments Market
Payments
Retail Point of Sale (POS) Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Italy Payments Market
Payments
Canada Prepaid Cards Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Enterprise Payment Software Market
Payments
Denmark Mobile Payments Market