
 Buy Now Pay Later (BNPL) Services Market | 2026-2036
Buy Now Pay Later (BNPL) Services Market Size, Share, and Industry Trends Forecast 2026-2036
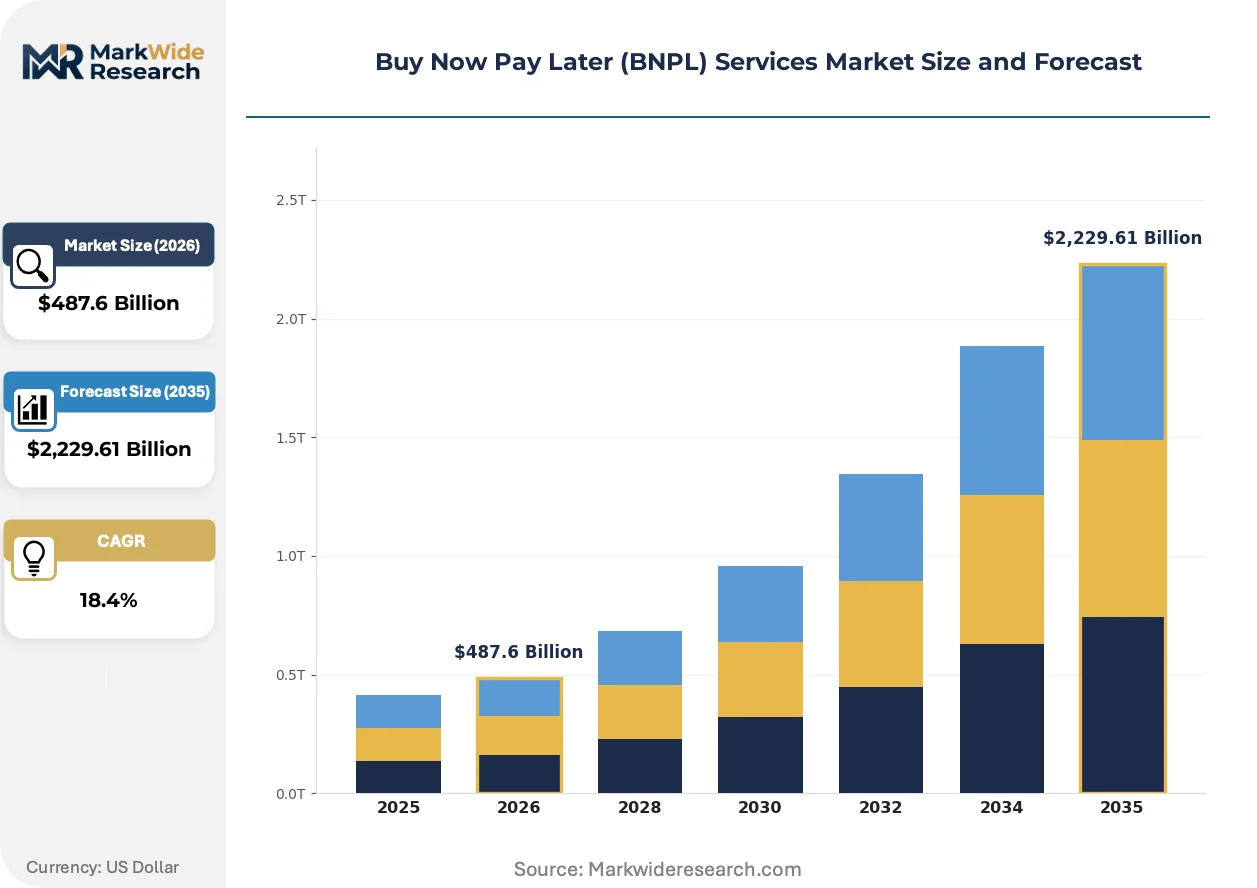
Buy Now Pay Later (BNPL) Services Market Outlook
Embedded checkout financing is reshaping how consumers transact across digital and physical retail. Klarna Bank AB leverages its proprietary risk engine and merchant network to sustain dominance in European apparel and beauty verticals. Affirm Holdings Inc. anchors its position through partnerships with large-ticket retailers, while PayPal Holdings Inc. competes by extending its two-sided network into installment products at existing merchant scale.
Buy Now Pay Later (BNPL) services constitute short-term consumer credit products that split purchase amounts into predetermined installments, typically operating through automated repayment schedules linked to debit cards or bank accounts with real-time eligibility verification. These instruments serve primarily to reduce purchase friction and expand merchant conversion rates at digital and physical points of sale. Point of sale financing occupies the largest transaction volume pool due to its direct integration at merchant checkout, while API integration represents the fastest-growing deployment mode as platforms seek modular, low-latency connectivity. E-commerce shoppers drive the steepest adoption curve among customer types, though small businesses present an emerging margin pool as B2B trade credit digitizes.
The Consumer Financial Protection Bureau in the United States, the Australian Securities and Investments Commission, and the UK Financial Conduct Authority each impose distinct disclosure and affordability standards that shape product design and market access requirements across their jurisdictions. Compliance costs diverge significantly where regulators classify BNPL as credit versus payment instruments, forcing providers to maintain multiple operational templates. Stakeholders must monitor how open banking data-sharing mandates and evolving credit classification rulings alter underwriting economics and competitive moats.
Market Dynamics
Open banking APIs and real-time credit assessment protocols are compressing underwriting timelines from days to milliseconds. This infrastructure shift is redrawing competitive moats around data access and algorithmic risk scoring rather than balance sheet depth.
Growth Catalysts
- PSD2 Data-Sharing Mandates:European open banking regulations force traditional banks to release transaction histories. BNPL providers leverage this feedstock to refine default prediction models without hard credit checks.
- Merchant Conversion Optimization:E-commerce platforms embed installment options at checkout to reduce cart abandonment. The apparel and beauty verticals report measurable lift in average order values when split-payment tools surface pre-purchase.
- Debit-First Repayment Infrastructure:Automated bank account linking via ACH and SEPA protocols eliminates card network interchange. This cost compression expands margin pools for providers operating at sub-prime price points.
Market Restraints
- Regulatory Classification Divergence:The Consumer Financial Protection Bureau treats BNPL as credit products requiring Truth-in-Lending disclosures. Compliance templates multiply where jurisdictions disagree on payment-versus-credit definitions.
- Funding Cost Volatility:Securitization markets for consumer installment receivables tighten during rate cycles. Warehouse line pricing fluctuates with ABS spreads, pressuring unit economics for thin-margin originators.
- Concentrated Merchant Dependence:Large-ticket electronics and furniture retailers anchor transaction volumes. Dependency on discretionary durable goods exposes receivables performance to household balance sheet stress.
Strategic Opportunities
- B2B Trade Credit Digitization:Small business procurement workflows remain paper-intensive. BNPL architectures adapted for net-30 replacement capture working capital float previously locked in supplier relationships.
- India Stack Integration:Account Aggregator frameworks and UPI autopay mandates create rails for real-time underwriting. The country's digital public infrastructure offers a template for emerging market replication.
- Embedded Finance Convergence:API-first deployment meshes with vertical SaaS platforms serving niche retailers. Payroll and inventory systems become distribution channels for white-labeled installment products.
Industry Challenges
- Model Risk Governance:Machine learning underwriting requires explainability frameworks for regulatory examination. Talent scarcity in quantitative risk management and fair-lending compliance constrains scaling velocity.
- Legacy Core Integration:Bank partnerships demand ISO 8583 message compatibility and settlement reconciliation. Technical debt in partner systems extends implementation timelines for real-time disbursement.
- Collections Infrastructure:Soft credit products lack collateral recovery mechanisms. First-party and third-party servicing capabilities must scale proportionally with portfolio growth to maintain net promoter scores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buy Now Pay Later (BNPL) Services Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $2,229.61 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Point of Sale Financing, Online Checkout, In-store Financing, Mobile Payments Customer Type: Retail Consumers, E-commerce Shoppers, Small Businesses, Large Enterprises Payment Frequency: Installments, Single Payment, Deferred Payment, Subscription Model Integration Level: API Integration, Platform Integration, Direct Payment Links, Payment Gateways |
| Companies Covered | PayPal Holdings Inc., Sezzle Inc., Affirm Holdings Inc., Bread Financial Holdings Inc., Zilch Technology Limited, Klarna Bank AB, Zip Co Limited, Amazon.com Inc., Afterpay Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buy Now Pay Later (BNPL) Services Market Strategic Shifts
Real-time data pipelines and algorithmic decisioning are compressing the traditional credit value chain. Three forces dominate: infrastructure convergence, regulatory recalibration, and procurement behavior fragmentation.
Machine learning-based alternative credit scoring is collapsing the latency between application and approval. Subprime and thin-file borrowers gain access previously gated by FICO thresholds. E-commerce merchants adopt these tools to capture sales from customers rejected by legacy card issuers. The structural consequence is a disintermediation of traditional bureau-dependent underwriting.
The UK Financial Conduct Authority's impending BNPL authorization regime mandates affordability assessments and dispute resolution frameworks. Product design must embed cooling-off periods and hardship protocols. Providers operating in British markets are restructuring compliance functions ahead of enforcement timelines.
Buyers increasingly unbundle payment timing from payment instrument selection. Younger demographics prioritize cash-flow management over rewards optimization. This behavioral pivot concentrates demand in markets with high smartphone penetration and underdeveloped credit card infrastructure, particularly in Nordic and Asia-Pacific urban centers.
Buy Now Pay Later (BNPL) Services Market Segmentation
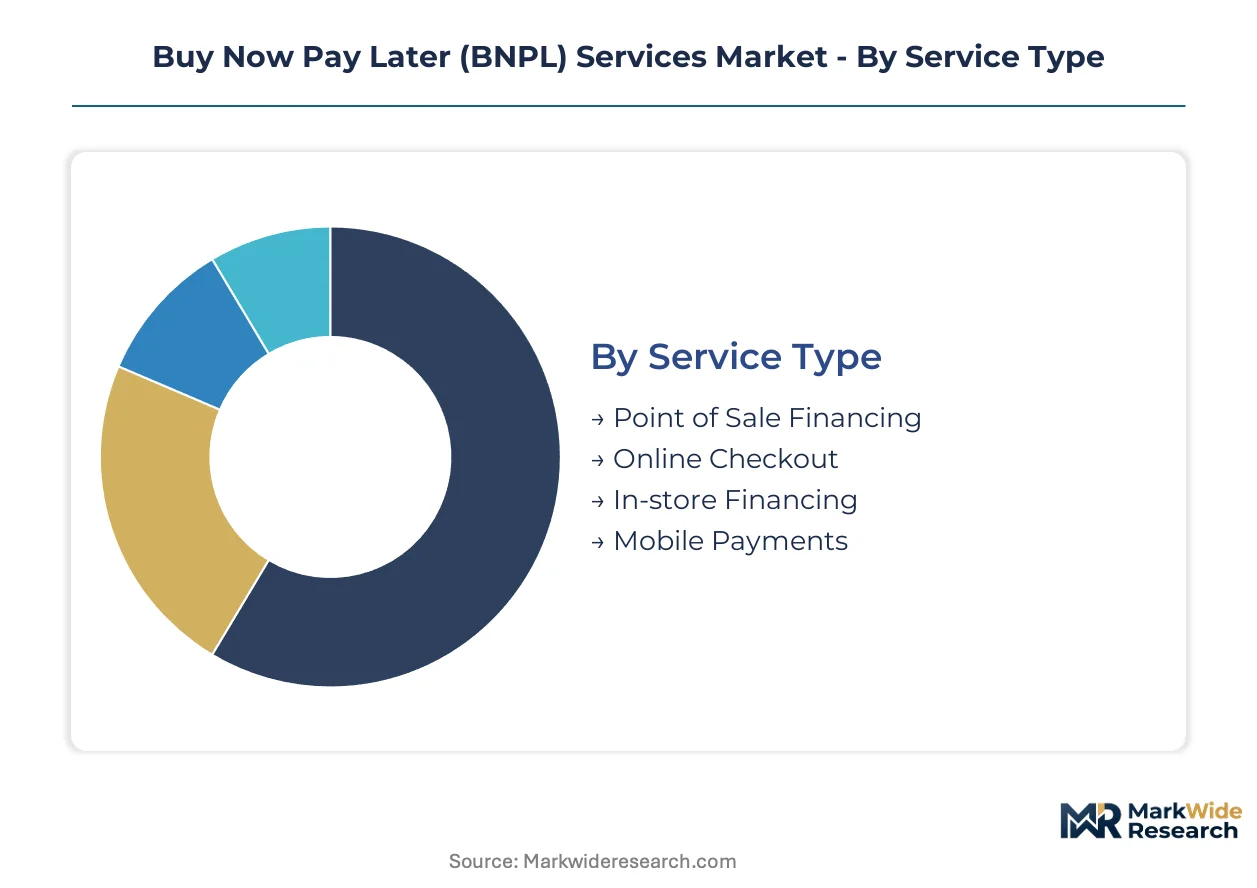
BNPL market structure reflects divergent deployment economics across transaction environments and customer risk profiles. Segmentation reveals where underwriting automation delivers margin compression versus where manual intervention preserves yield.
Service Type:
Use-case spectrum spans impulse-driven micro-purchases through considered large-ticket acquisitions, each demanding distinct authorization latency and fraud architecture.
- Point of Sale Financing:Embedded checkout tools split transaction amounts into predetermined installments at merchant terminals. Demand concentrates in United States furniture and electronics retail where average order values exceed $500 and merchant conversion lift justifies integration costs.
- Online Checkout:Browser-based installment selection surfaces pre-purchase on e-commerce product pages. Australian apparel and beauty verticals drive adoption where cart abandonment reduction metrics validate merchant fees.
- In-store Financing:QR code or SMS-triggered approval workflows bridge physical retail to digital underwriting rails. Nordic markets leverage high smartphone penetration for seamless in-aisle activation.
- Mobile Payments:Native app-based installment selection within wallet interfaces. India Stack UPI autopay mandates enable real-time bank account linking for deferred settlement.
Established volume favors Point of Sale Financing; emerging adoption favors Mobile Payments.
Customer Type:
Credit risk stratification separates thin-file millennials from collateralized B2B procurement officers.
- Retail Consumers:Individual borrowers seeking cash-flow smoothing for discretionary purchases. United States subprime segments bypass FICO gating through alternative data scoring.
- E-commerce Shoppers:Digital-native buyers completing transactions on marketplace platforms. Sweden's Klarna merchant network captures this cohort through one-tap repeat purchasing.
- Small Businesses:Net-30 trade credit digitization for procurement workflows. Working capital float previously locked in supplier relationships now migrates to third-party underwriting.
- Large Enterprises:Treasury-integrated payment timing optimization for capital expenditure. Procurement system ERP connectivity demands ISO 20022 message compatibility.
Transaction velocity peaks with E-commerce Shoppers; margin expansion concentrates with Small Businesses.
Payment Frequency:
Repayment architecture determines funding cost exposure and collections infrastructure requirements.
- Installments:Fixed-schedule debits across 4-6 payment intervals. Pay-in-4 models dominate United States mass-market positioning with automated ACH withdrawal.
- Single Payment:Lump-sum settlement after defined deferral period. Australian regulatory scrutiny intensifies where products resemble payday advance structures.
- Deferred Payment:Interest-free windows with balloon settlement requirements. United Kingdom Financial Conduct Authority affordability assessments reshape product design.
- Subscription Model:Recurring membership fees bundling multiple purchase authorizations. Platform stickiness metrics justify customer acquisition spend.
Regulatory clarity favors Installments; customer acquisition efficiency favors Subscription Model.
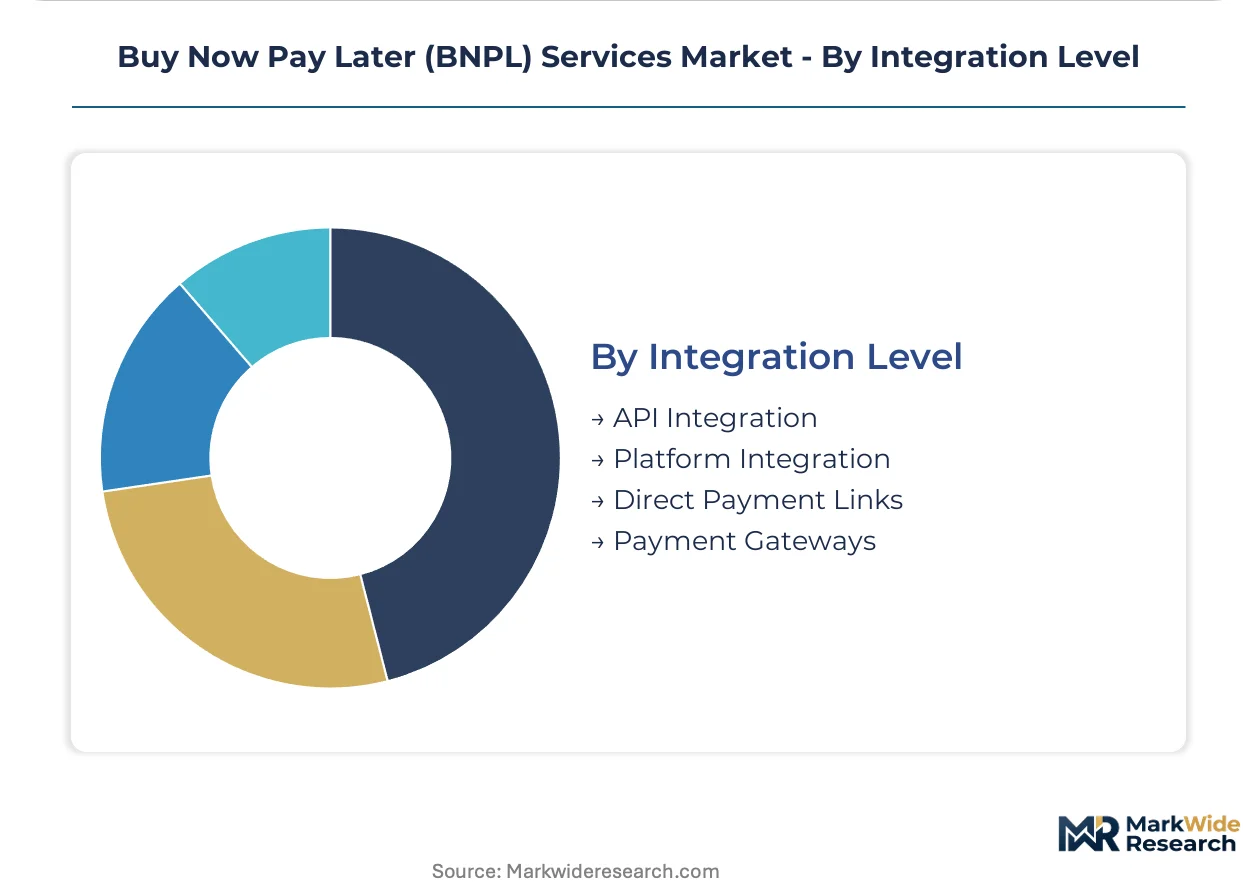
Integration Level:
Technical deployment mode dictates implementation timeline and merchant self-service capability.
- API Integration:Modular REST endpoints enabling low-latency eligibility checks. European PSD2 data-sharing mandates feed real-time transaction history into scoring models.
- Platform Integration:Native embedding within vertical SaaS commerce stacks. Inventory and payroll systems become distribution channels for white-labeled products.
- Direct Payment Links:Standalone URL generation for invoice financing or B2B trade credit. Email and messaging distribution bypasses merchant technical integration.
- Payment Gateways:Incumbent processor partnerships leveraging existing merchant relationships. Stripe and Adyen rails extend reach without direct sales force expansion.
Speed-to-market favors Direct Payment Links; scale economics favor API Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Fedwire Real-Time Gross Settlement system underwrites United States dollar liquidity for cross-border BNPL settlement. SEPA Instant Credit Transfer rails across the eurozone compress merchant payout timelines to ten seconds. India's UPI-AutoPay infrastructure enables real-time debit authorization for installment collections.
United States
Merchant adoption concentrates in furniture and electronics retail where average order values exceed $500. The Consumer Financial Protection Bureau mandates Truth-in-Lending disclosures for installment products, reshaping checkout flow design. Silicon Valley fintech clusters and New York financial services corridors host competing underwriting technology development centers.
United Kingdom
E-commerce penetration in apparel and beauty verticals drives merchant integration demand. The Financial Conduct Authority's impending authorization regime requires affordability assessments and hardship protocols. London's fintech density supports regulatory technology development for compliance automation.
Germany
PSD2 open banking mandates force transaction data sharing that feeds alternative credit scoring models. The Federal Financial Supervisory Authority (BaFin) monitors consumer credit classification boundaries. Berlin and Munich host competing BNPL technology development operations serving DACH market expansion.
Sweden
High smartphone penetration and thin credit card infrastructure accelerate mobile-first adoption. The Swedish Financial Supervisory Authority (Finansinspektionen) supervises payment institution licensing. Stockholm anchors Klarna's merchant network development and risk engine refinement operations.
Australia
Apparel and beauty e-commerce merchants report measurable cart abandonment reduction from checkout integration. The Australian Securities and Investments Commission imposes responsible lending obligations on deferred payment providers. Sydney and Melbourne fintech clusters concentrate competing platform development activity.
Buy Now Pay Later (BNPL) Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in risk scoring and payment orchestration. The vendor base organizes around three strategic archetypes: merchant-facing checkout platforms, bank partnership enablers, and infrastructure-as-a-service providers. Consolidation pressure intensifies as scale economics favor multi-merchant network density. Dominant competitive moves include strategic partnerships with large-ticket retailers and API-first deployment for vertical SaaS integration.
Within the platform tier, Klarna Bank AB and Affirm Holdings Inc. exemplify divergent geographic and vertical specialization strategies. PayPal Holdings Inc. occupies a position leveraging existing two-sided network scale for installment product distribution. Among Australia-based operators, Zip Co Limited and Afterpay Ltd represent early-mover advantages in merchant acquisition density.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Sezzle Inc. |
| Affirm Holdings Inc. |
| Bread Financial Holdings Inc. |
| Zilch Technology Limited |
| Klarna Bank AB |
| Zip Co Limited |
| Amazon.com Inc. |
| Afterpay Ltd |
| Others |
Value Chain & Pricing Dynamics
Stockholm's fintech corridor anchors algorithmic underwriting capacity that feeds downstream pricing power across European BNPL markets. Merchant fee compression in high-volume corridors tightens margin pools, forcing providers to optimize automated debit collection infrastructure.
Pricing Analysis
Volume-discount tiering structures separate enterprise merchant rates from mid-market SaaS-embedded pricing and standalone small-business origination fees. Pay-in-4 models dominate United States mass-market positioning with automated ACH withdrawal, while subscription bundling captures platform stickiness in Nordic corridors. Pricing pressure stems from debit-first repayment infrastructure eliminating card network interchange. E-commerce merchants in apparel and beauty verticals show highest price sensitivity; large-ticket furniture retailers command volume-negotiated rates.
Supply Chain Analysis
Export-control regimes on real-time credit scoring algorithms limit technology transfer to certain jurisdictions, constraining underwriting model deployment. Funding supply concentrates in United States securitization markets, United Kingdom warehouse lines, and Australian ABS programs. Capital flows draw from pension fund allocations, specialty finance vehicles, and bank partnership balance sheets. Single-source vulnerability sits with concentrated merchant dependence in discretionary durable goods. Distribution runs through API-first middleware layers connecting merchant checkout to capital markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large-ticket retailers as merchant network density concentrates among a handful of dominant e-commerce platforms. This consolidation fragments pricing leverage for thin-margin originators.
For Market Incumbents: Build data network effect moats by deepening open banking API integration and merchant-exclusive underwriting partnerships. Incumbents must defend against embedded finance convergence from vertical SaaS platforms by securing ISO 20022-compatible ERP connectivity. Capacity addition in India Stack corridors offers geographic diversification against United States regulatory tightening. Channel control through direct merchant sales forces preserves pricing power against payment gateway intermediation. For New Entrants and Emerging Players: Build out B2B trade credit digitization capabilities targeting net-30 replacement workflows in procurement-intensive industries. Small business segments present the most penetrable white space, with working capital float migrating from supplier relationships to third-party underwriting. A white-labeled API deployment angle through vertical SaaS platforms minimizes customer acquisition costs against established checkout brands. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-layer play because underwriting automation and real-time data pipelines reshape competitive moats around algorithmic scoring rather than balance sheet depth. Acquisition targets should emphasize API-first deployment capabilities and PSD2-compliant data architectures. The signal to watch is regulatory classification divergence between payment and credit product definitions across major jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Modular REST endpoints enable low-latency eligibility checks for merchant networks. |
| Open Banking Data Partnership | PSD2 transaction feeds refine default prediction models without hard credit checks. |
| B2B Trade Credit Expansion | Net-30 digitization captures working capital float from paper-intensive procurement workflows. |
| Regulatory Technology Investment | Affordability assessment automation satisfies UK Financial Conduct Authority authorization requirements. |
| Embedded Finance Convergence | Vertical SaaS integration transforms payroll and inventory systems into distribution channels. |
Study Parameters
Operator-level perspectives from BNPL platform risk officers, merchant acquisition leads, open banking infrastructure providers, and securitization structurers anchored the qualitative base. Secondary validation drew from Consumer Financial Protection Bureau rulemaking dockets, UK Financial Conduct Authority consultation papers, Australian Securities and Investments Commission enforcement releases, and European Banking Authority technical standards. Bottom-up transaction volume estimates triangulated against top-down addressable credit market sizing.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled include service type deployment mode, customer risk stratification, payment frequency architecture, and integration technical level. CAGRs derived from logistic diffusion curves fitted to merchant adoption rates and consumer penetration benchmarks. Forecast inputs incorporated open banking API rollout timelines and regulatory classification ruling probabilities.
Stress conditions across funding cost volatility, merchant concentration thresholds, and regulatory reclassification scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on securitization market depth and interchange compression trajectories. Material shifts in central bank rate cycles or BNPL credit product classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Crypto Payment Gateway Market
Payments
Transit Cards Market
Payments
Japan Real Time Payment Market
Payments
North America Payment Analytics Software Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Mobile Payment Data Protection Market
Payments
Germany Real Time Payments Market
Payments
India Mobile Payments Market
Payments
Global Payments Market
Payments
Japan Retail Cash Management Market
Payments
Payment Analytics Software Market
Payments
Retail POS Terminals Market
Payments
Canada Mobile Payments Market
Payments
Estonia POS Terminal Market
Payments
India Gift Card and Incentive Card Market
Payments
Contactless Payment Market