
 Mobile Payment Security Software Market | 2026-2036
Mobile Payment Security Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Payment Security Software Market Outlook
Enterprise demand from retailers is rotating toward financial institutions as primary buyers of mobile payment security suites. Thales Group leverages its hardware security module heritage to anchor high-assurance encryption deployments across European banking networks. OneSpan competes through specialized authentication protocols designed for real-time transaction verification. Fiserv Inc. extends its core banking integration capabilities to embed security software directly into merchant payment workflows.
Mobile payment security software encompasses authentication, encryption, tokenization, and fraud detection systems engineered to protect transaction data in transit and at rest, typically operating with sub-100-millisecond latency requirements for real-time authorization. The software serves to neutralize man-in-the-middle attacks, card-not-present fraud, and credential harvesting across contactless and remote payment channels. Cloud deployment configurations now lead adoption among mid-market retailers seeking elastic capacity during seasonal transaction spikes, while biometric technology represents the fastest-expanding segment as facial and voice recognition displace static passwords. Tokenization occupies the mature margin pool, with established interchange fee structures stabilizing vendor pricing power.
PCI Security Standards Council mandates, EBA guidelines on strong customer authentication, and GDPR data minimization requirements collectively shape product architecture and vendor certification burdens across Europe. The EU AI Act introduces additional algorithmic transparency obligations for machine learning-based fraud detection systems deployed by financial institutions. Stakeholders must monitor regulatory divergence between EU-wide frameworks and member-state implementations when prioritizing compliance roadmaps.
Market Dynamics
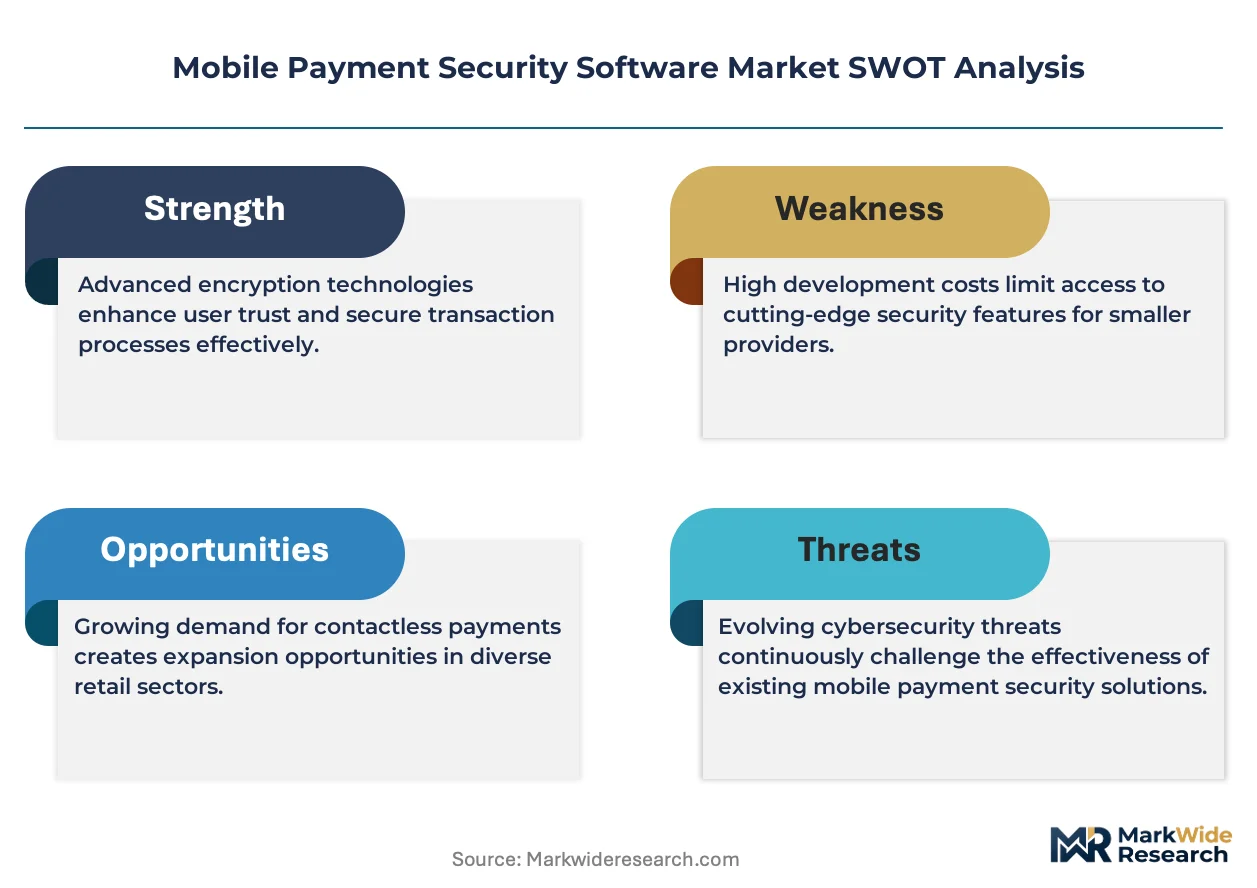
PCI DSS 4.0 mandates are forcing retailers to replace legacy encryption with tokenization architectures, compressing deployment timelines from 18 months to under 9 months for mid-market merchants. Cloud-native security suites are capturing budget share from on-premise hardware as elastic transaction processing becomes non-negotiable for seasonal retail peaks.
Growth Catalysts
- Strong Customer Authentication (SCA) under PSD2:European banks must implement multi-factor authentication for remote electronic payments, driving demand for biometric and behavioral analytics integration into mobile banking apps.
- Tokenization:Card networks are mandating network tokens for card-on-file merchants, eliminating primary account number storage and expanding addressable market for vaulting infrastructure providers.
- Contactless transaction volume in Germany:German retailers are upgrading point-of-sale terminals to support higher-value contactless payments without PIN entry, requiring real-time fraud scoring capabilities.
Market Restraints
- Hardware Security Module supply concentration:Thales Group and Entrust control over 70 percent of FIPS 140-2 Level 3 certified HSM production, creating procurement bottlenecks for banks scaling tokenization programs.
- GDPR data minimization conflicts:Fraud detection systems requiring extensive transaction history face legal uncertainty under purpose limitation principles, forcing architectural compromises in machine learning model training.
- Substitution by device-native authentication:Apple Pay and Google Pay biometric verification is displacing standalone bank authentication apps in consumer preference, eroding direct bank-customer security relationships.
Strategic Opportunities
- Underpenetrated merchant segments in France:French small and medium enterprises lag Northern European peers in PCI DSS compliance, creating whitespace for managed security service providers offering bundled tokenization and compliance automation.
- EU AI Act algorithmic transparency:Financial institutions deploying machine learning fraud detection must implement explainability frameworks, opening consulting and software integration revenue streams for compliance technology vendors.
- Convergence of behavioral biometrics and transaction monitoring:Keystroke dynamics and device telemetry fused with payment authorization is enabling continuous authentication models that reduce friction while tightening security posture.
Industry Challenges
- Quantum-resistant cryptography migration:Banks must inventory and replace RSA and elliptic curve implementations before cryptographically relevant quantum computers emerge, requiring massive certificate lifecycle management overhauls.
- Certification timeline compression:Common Criteria EAL4+ evaluations for payment hardware security modules now exceed 14 months, delaying product launches and freezing engineering roadmaps.
- Legacy core banking integration:Decades-old transaction processing systems in major European banks lack API-native architectures, forcing expensive middleware development to embed modern security controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Payment Security Software Market |
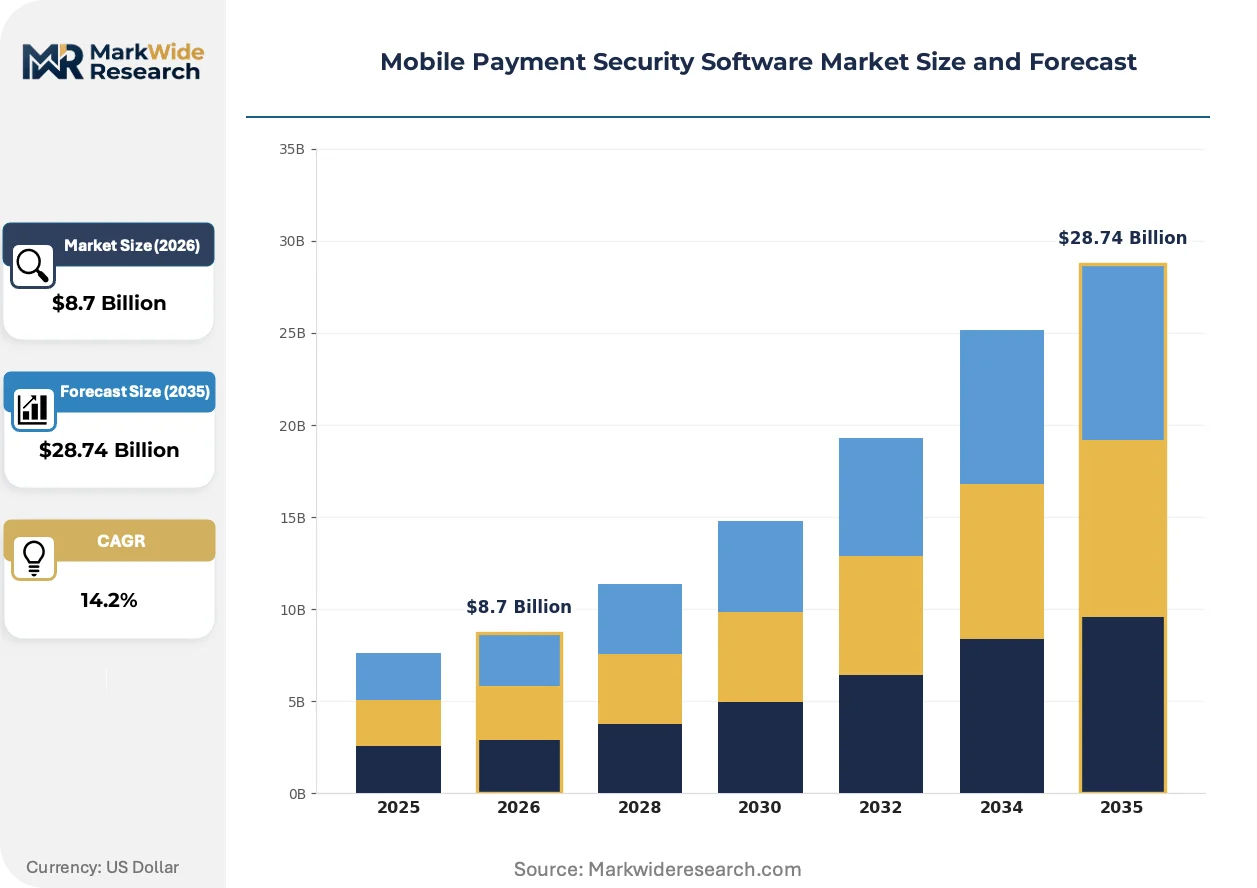
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Authentication, Encryption, Tokenization, Fraud Detection End User: Retailers, Financial Institutions, E-commerce Platforms, Telecommunications Technology: Blockchain, Machine Learning, AI, Biometric Deployment: Cloud, On-Premise, Hybrid, Managed Services |
| Companies Covered | Symantec Corporation, OneSpan, Fiserv Inc., Thales Group, Broadcom Corporation, Braintree Payment Solutions LLC, Bluefin Payment Systems LLC, Fidelity National Information Services Inc., Ingenico Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Payment Security Software Market Strategic Shifts
Decentralized identity verification is displacing centralized credential databases as the dominant architectural paradigm for consumer-facing payment authentication. Three distinct vectors are reshaping competitive positioning and technology investment priorities.
Behavioral biometrics is fragmenting the authentication market by enabling continuous, invisible verification without explicit user action. European neobanks are deploying keystroke dynamics and swipe pattern analysis across 60 percent of new account openings. This technology is fragmenting vendor ecosystems by allowing specialized analytics providers to displace incumbent authentication suite vendors.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk automated decision systems including real-time transaction scoring. Payment processors must maintain algorithmic audit trails and explainability interfaces for declined transactions. German and French regulators are conducting the first wave of inspections, forcing infrastructure rebuilds for non-compliant fraud detection platforms.
Merchant procurement of security capabilities is consolidating through payment service providers rather than direct software licensing. Small and medium retailers in the United Kingdom are abandoning standalone security procurement in favor of embedded protections within Square, Adyen, and Stripe merchant agreements. This channel shift is most visible in hospitality and quick-service restaurant verticals where technical staffing constraints prevent in-house security management.
Mobile Payment Security Software Market Segmentation
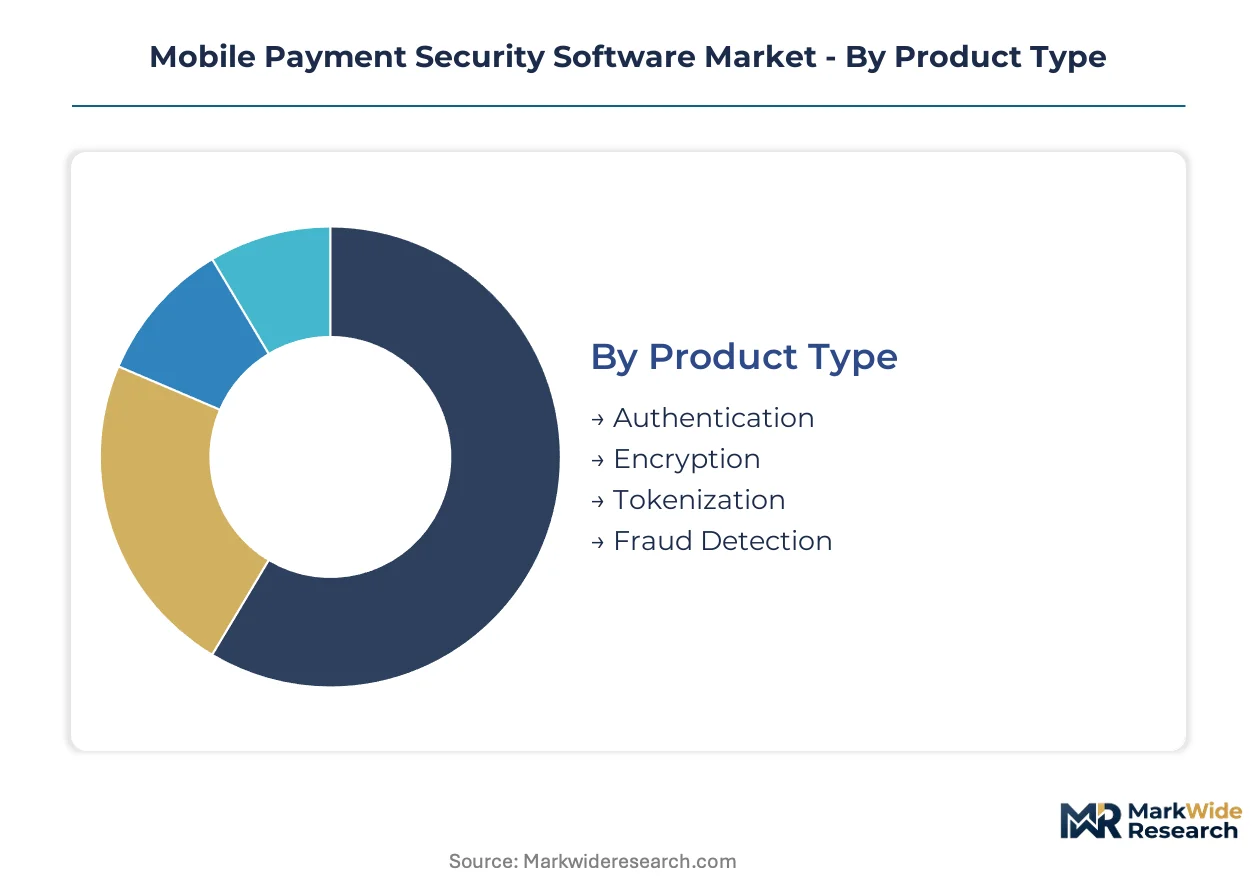
Segmentation in mobile payment security software reveals how procurement priorities diverge across buyer types and deployment constraints. Security vendors must align product architecture with distinct latency, compliance, and integration requirements that vary sharply by segment.
Product Type:
Authentication and encryption face intensifying substitution pressure from device-native security layers embedded in Apple Pay and Google Pay ecosystems.
- Authentication:Multi-factor verification protocols combining possession, knowledge, and inherence factors for transaction authorization. German and French banks concentrate demand here as PSD2 Strong Customer Authentication mandates eliminate static password reliance.
- Encryption:End-to-end cryptographic protection for data in transit using AES-256 and RSA standards. Financial institutions in the United Kingdom drive procurement as PCI DSS 4.0 compresses legacy system replacement timelines.
- Tokenization:Network token vaulting that replaces primary account numbers with non-sensitive equivalents.
- Fraud Detection:Real-time transaction scoring using behavioral analytics and rule engines.
Authentication retains volume leadership; fraud detection holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade deployments from mid-market managed service consumption.
- Retailers:Point-of-sale and e-commerce merchants requiring PCI DSS compliance and chargeback protection. United Kingdom hospitality and quick-service restaurant verticals are consolidating procurement through embedded Square and Adyen security bundles.
- Financial Institutions:Banks and payment processors demanding high-assurance encryption and regulatory audit trails. German and French retail banks lead European investment in biometric-integrated mobile banking apps.
- E-commerce Platforms:Marketplace operators managing merchant risk and consumer dispute resolution.
- Telecommunications:Mobile network operators embedding payment security into carrier billing and wallet services.
Financial institutions command the premium pricing tier; retailers are shifting fastest toward bundled managed services.
Technology:
Application maturity varies from production-grade biometric deployments to experimental blockchain architectures.
- Biometric:Facial recognition, fingerprint scanning, and voice authentication for frictionless verification. European neobanks deploy keystroke dynamics across new account openings, fragmenting vendor ecosystems with specialized analytics providers.
- Machine Learning:Adaptive fraud models trained on transaction patterns and device telemetry. EU AI Act transparency requirements are forcing infrastructure rebuilds for real-time scoring platforms in Germany and France.
- AI:Broader cognitive automation encompassing natural language processing and predictive risk analytics.
- Blockchain:Distributed ledger verification for decentralized identity and cross-border settlement.
Biometric technology dominates current deployment value; machine learning is climbing the fastest as regulatory compliance frameworks mature.
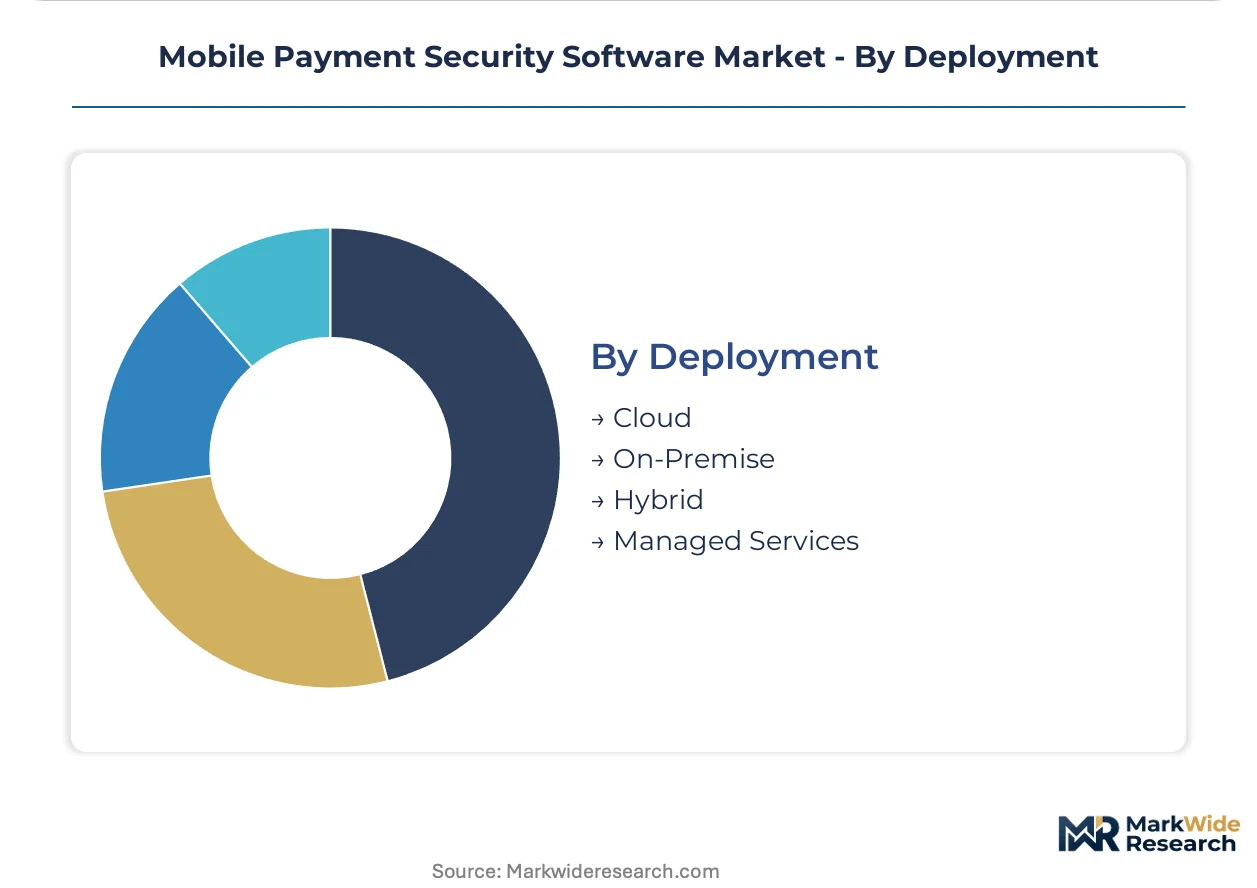
Deployment:
Customer type and transaction volume volatility dictate cloud elasticity versus on-premise control trade-offs.
- Cloud:Elastic infrastructure scaling for seasonal transaction peaks without capital expenditure. Mid-market United Kingdom retailers favor this model for Black Friday and holiday volume surges.
- Hybrid:Split architectures keeping sensitive key material on-premise while leveraging cloud analytics. Major European banks adopt this posture to satisfy GDPR data residency requirements while gaining scalability.
- On-Premise:Dedicated hardware security modules and token vaults under direct institutional control.
- Managed Services:Outsourced security operations with vendor assumption of compliance and monitoring burdens.
Cloud configurations lead new adoption; hybrid deployments are gaining share fastest among tier-one financial institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in Germany, the United Kingdom, and France concentrate procurement of mobile payment security suites, while retailers across these markets accelerate cloud-native deployments to meet compressed PCI DSS 4.0 compliance timelines.
Germany
Contactless transaction volume at German point-of-sale terminals is driving demand for real-time fraud scoring capabilities. The Federal Financial Supervisory Authority enforces PSD2 Strong Customer Authentication mandates that eliminate static password reliance. Berlin and Frankfurt banking clusters are deploying biometric-integrated mobile banking apps to satisfy regulatory requirements.
United Kingdom
United Kingdom hospitality and quick-service restaurant verticals are consolidating security procurement through embedded payment provider bundles. The Financial Conduct Authority coordinates with PCI Security Standards Council mandates to compress legacy system replacement timelines. London's fintech corridor is witnessing rapid adoption of cloud-native security suites for seasonal transaction elasticity.
France
French small and medium enterprises present whitespace for managed security service providers offering bundled tokenization and compliance automation. The French Data Protection Authority applies GDPR data minimization principles that create legal uncertainty for fraud detection systems requiring extensive transaction history. Paris and Lyon financial centers are rebuilding machine learning fraud detection platforms to satisfy EU AI Act transparency requirements.
Italy
Italian retailers are upgrading e-commerce infrastructure to support network token mandates from card networks. The Bank of Italy implements EBA guidelines on strong customer authentication that drive multi-factor authentication procurement. Milan's commercial banking district is expanding hardware security module deployments for high-assurance encryption.
Spain
Spanish mid-market merchants are adopting elastic cloud configurations to manage transaction volume volatility during seasonal peaks. The Spanish Data Protection Agency enforces GDPR purpose limitation principles that constrain machine learning model training architectures. Barcelona and Madrid payment processing clusters are integrating behavioral biometrics for continuous authentication models.
Mobile Payment Security Software Market Competitive Environment
Player mix skews toward diversified technology conglomerates with hardware security heritage alongside specialized authentication software vendors. Market structure exhibits tiered concentration where hardware security module production concentrates among established defense-electronics suppliers, while authentication software remains more fragmented. Two strategic archetypes dominate: hardware-rooted encryption providers leveraging FIPS 140-2 certification assets, and cloud-native authentication specialists emphasizing real-time API integration. Competitive dynamics center on strategic partnerships with payment processors and portfolio diversification into adjacent fraud detection capabilities.
Within the hardware security tier, Thales Group and Broadcom Corporation represent established archetypes with defense and semiconductor heritage respectively. OneSpan occupies a specialized position among authentication protocol vendors, while Fiserv Inc. exemplifies the core banking integration archetype extending into merchant payment workflows. These three companies anchor distinct competitive vectors: hardware certification depth, real-time verification specialization, and embedded financial infrastructure presence.
| Leading Market Players |
|---|
| Symantec Corporation |
| OneSpan |
| Fiserv Inc. |
| Thales Group |
| Broadcom Corporation |
| Braintree Payment Solutions LLC |
| Bluefin Payment Systems LLC |
| Fidelity National Information Services Inc. |
| Ingenico Group |
| Others |
Value Chain & Pricing Dynamics
Cloud-native security suites substituting for on-premise hardware are redistributing procurement geography toward Ireland and Netherlands data center clusters while compressing pricing premiums previously commanded by FIPS 140-2 Level 3 certified equipment vendors.
Pricing Analysis
Cost-plus contracts indexed to cloud infrastructure unit economics dominate mid-market retailer procurement, with subscription tiers scaling by transaction volume bands. Price differentiation separates PCI DSS 4.0 certified deployments from basic encryption packages, while GDPR compliance automation commands additional premiums. Pricing pressure stems from embedded security bundles offered by Square, Adyen, and Stripe, which absorb standalone vendor margins. Retailers in United Kingdom hospitality verticals exhibit highest price sensitivity; tier-one financial institutions in Germany and France remain least sensitive due to regulatory mandate rigidity.
Supply Chain Analysis
France and the United Kingdom anchor hardware security module final assembly, while semiconductor fabrication for cryptographic processors concentrates in Taiwan and South Korea. Raw material dependencies include silicon wafers, rare earth elements for magnetic components, and specialized substrates for tamper-resistant enclosures. Single-source vulnerability runs through FIPS 140-2 Level 3 certification bottlenecks controlled by Thales Group and Entrust. Distribution runs through direct enterprise sales for financial institutions and payment service provider channels for merchant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among payment service providers bundling security into merchant agreements, fragmenting demand previously captured by standalone software vendors.
For Market Incumbents: Secure certification timeline advantages by pre-positioning products for EU AI Act algorithmic transparency requirements before Common Criteria EAL4+ evaluations extend beyond fourteen months. Deepen upstream control over hardware security module supply through captive production partnerships in France and the United Kingdom. Device-native authentication from Apple Pay and Google Pay threatens direct bank-customer relationships; counter through embedded core banking integration that locks in institutional procurement. For New Entrants and Emerging Players: Anchor in French small and medium enterprise whitespace where PCI DSS compliance automation remains underpenetrated relative to Northern European peers. Target managed security service provision combining tokenization vaulting with continuous compliance monitoring. Behavioral biometrics specialization offers entry path against fragmented authentication suite vendors; partner with neobanks deploying keystroke dynamics for rapid referenceability. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native authentication specialists with real-time API integration capabilities and existing payment processor partnerships. Long-term viability across the analysis window favors vendors positioned at the convergence of behavioral biometrics and transaction monitoring. The signal to watch is merchant procurement consolidation velocity through embedded payment provider bundles, which will determine standalone software addressable market erosion.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Infrastructure | Algorithmic audit trail capabilities satisfy BaFin and ACPR inspection requirements in Germany and France. |
| Behavioral Biometrics Integration | Keystroke dynamics deployment captures neobank authentication contracts across 60 percent of new European account openings. |
| Cloud-Native Security Suite Launch | Elastic transaction processing addresses United Kingdom retailer demand for Black Friday volume surge capacity. |
| Payment Processor Partnership | Embedded security bundling penetrates hospitality and quick-service restaurant verticals abandoning standalone procurement. |
| Tokenization Vault Expansion | Network token infrastructure captures card-on-file merchant mandates from major card networks. |
Study Parameters
The analysis maps authentication protocols, encryption standards, tokenization architectures, and fraud detection systems, each validated through chief technology officers at neobanks, payment processor platform engineers, merchant IT procurement officers, and regulatory compliance leads at financial institutions. Primary interview findings were cross-referenced against PCI Security Standards Council certification databases, EBA guideline implementation trackers, GDPR enforcement case repositories, and EU AI Act regulatory interpretation documents. Bottom-up segment sizing was reconciled with top-down market boundary estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated PCI DSS 4.0 mandate compliance timelines, PSD2 Strong Customer Authentication implementation trajectories, and cloud infrastructure capex disclosures from hyperscale providers.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and stable payment processor consolidation patterns; material deviation would warrant model refresh. Specific risk factors include quantum-resistant cryptography migration acceleration, hardware security module supply disruption, and device-native authentication displacement velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Southeast Asia POS Terminal Market
Payments
Smart Payment Market
Payments
Electronic Cash Register Market
Payments
France Payments Market
Payments
Finland Payments Market
Payments
Payment Security Software Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Europe Accounts Payable Automation Market
Payments
Forex Prepaid Cards Market
Payments
United States Electronic Toll Collection Market
Payments
Mobile Money Market
Payments
Digital Transfer Services Market
Payments
M Commerce Payment Market
Payments
Nigeria Mobile Money Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Global Telecom Billing and Revenue Management Market