
 Europe Gift Card and Incentive Card Market | 2026-2036
Europe Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gift Card and Incentive Card Market Foresight
European digital payment infrastructure is consolidating as banks and fintechs converge on API-first card provisioning. Edenred leverages its employer network across France and Belgium to sustain prepaid meal and incentive card dominance. Blackhawk Network competes through grocery and retail partnerships in the United Kingdom and Netherlands, while Sodexo anchors corporate welfare segments in Italy and Spain with specialized employee benefit platforms.
Gift and incentive cards are stored-value instruments encoded with magnetic stripes, EMV chips, or tokenized credentials for redemption at designated merchant networks or open-loop payment systems. They function as prepaid monetary instruments for consumer gifting, employee recognition, and promotional loyalty campaigns. Digital cards are displacing physical plastic across the distribution channel spectrum as e-commerce platforms capture younger demographics, while corporate incentives remain the most margin-rich application segment due to bulk procurement contracts and recurring enterprise subscriptions. Retail applications retain volume leadership but face compression from virtual card alternatives.
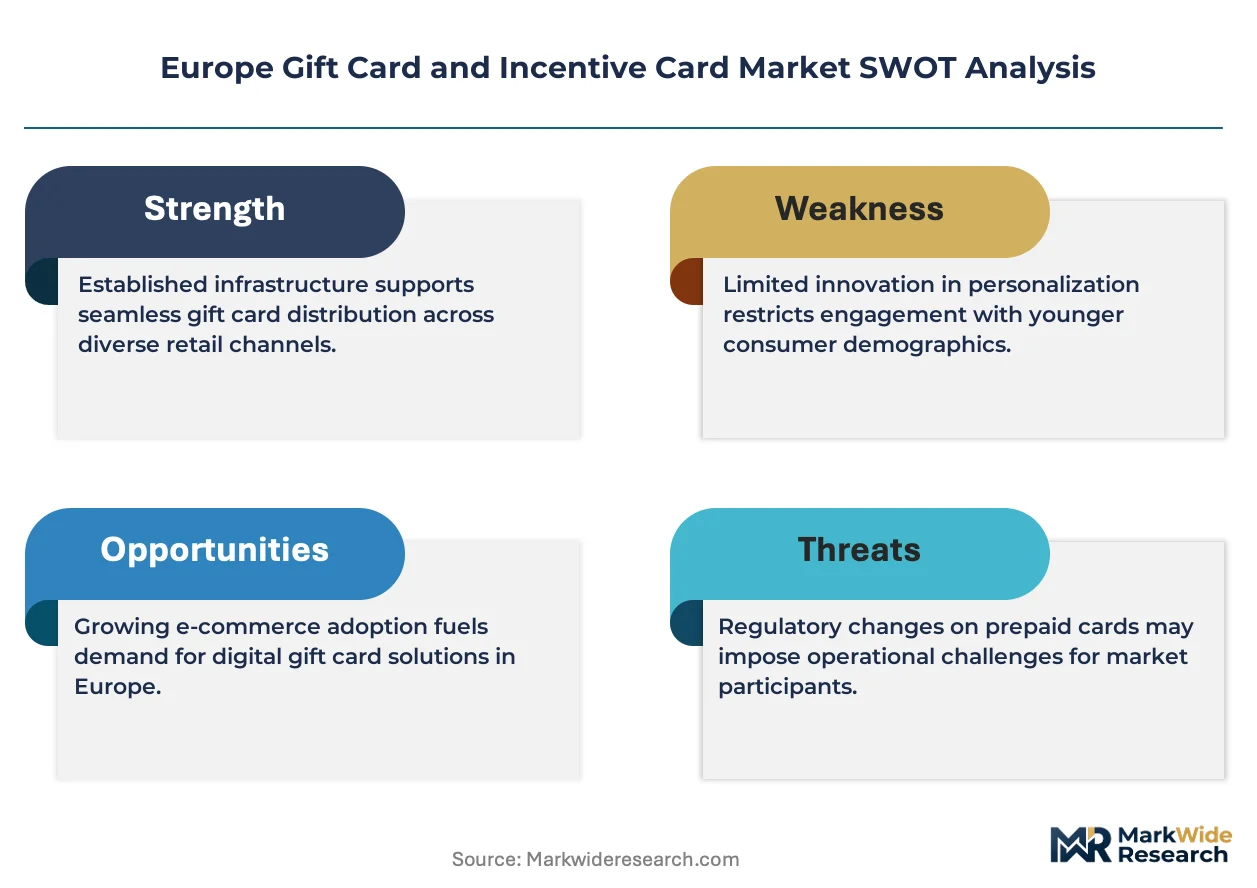
PSD2 and the EU's Digital Operational Resilience Act (DORA) are reshaping issuer compliance burdens around Strong Customer Authentication and third-party risk management. The European Banking Authority (EBA) enforces capital reserve requirements for e-money institutions that underlie prepaid card programs, tightening market access for non-bank entrants. Stakeholders must monitor how the EU's instant payment regulation alters settlement economics for digital card loads and real-time redemption.
Market Dynamics
PSD2-mandated open banking APIs are forcing prepaid card issuers to rebuild their technology stacks around real-time account linking, compressing margins for legacy batch-processing platforms while creating entry points for API-native fintechs.
Growth Catalysts
- Corporate HR digitization:German automotive and pharmaceutical employers are expanding card-based incentive disbursement through integrated payroll platforms.
- PSD2 open banking:The EU's revised Payment Services Directive accelerates instant card issuance through bank API partnerships.
- Tokenized credentials:EMVCo specifications enable smartphone-native redemption, capturing younger demographics across French and UK retail networks.
Market Restraints
- E-money capital reserves:The European Banking Authority enforces stringent liquidity requirements that constrain non-bank program managers.
- Plastic supply concentration:Magnetic stripe and chip card manufacturing clusters in Southeast Asia create procurement vulnerability for European issuers.
- Interchange compression:EU caps on payment scheme fees limit revenue per transaction for open-loop incentive programs.
Strategic Opportunities
- Spanish corporate welfare:Underpenetrated mid-market employers present white space for automated meal and transport benefit platforms.
- Instant payment settlement:The EU's instant payment regulation enables real-time card loads that reduce float revenue dependency.
- AI-powered personalization:Convergence of machine learning with transaction data enables dynamic reward catalog curation for enterprise clients.
Industry Challenges
- SCA implementation:Strong Customer Authentication under PSD2 creates checkout friction that degrades digital gift card redemption rates.
- Legacy core migration:Bank-owned issuers struggle to decouple prepaid operations from decades-old mainframe architectures.
- DORA compliance timelines:The Digital Operational Resilience Act imposes incident reporting burdens that strain mid-tier e-money institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gift Card and Incentive Card Market |
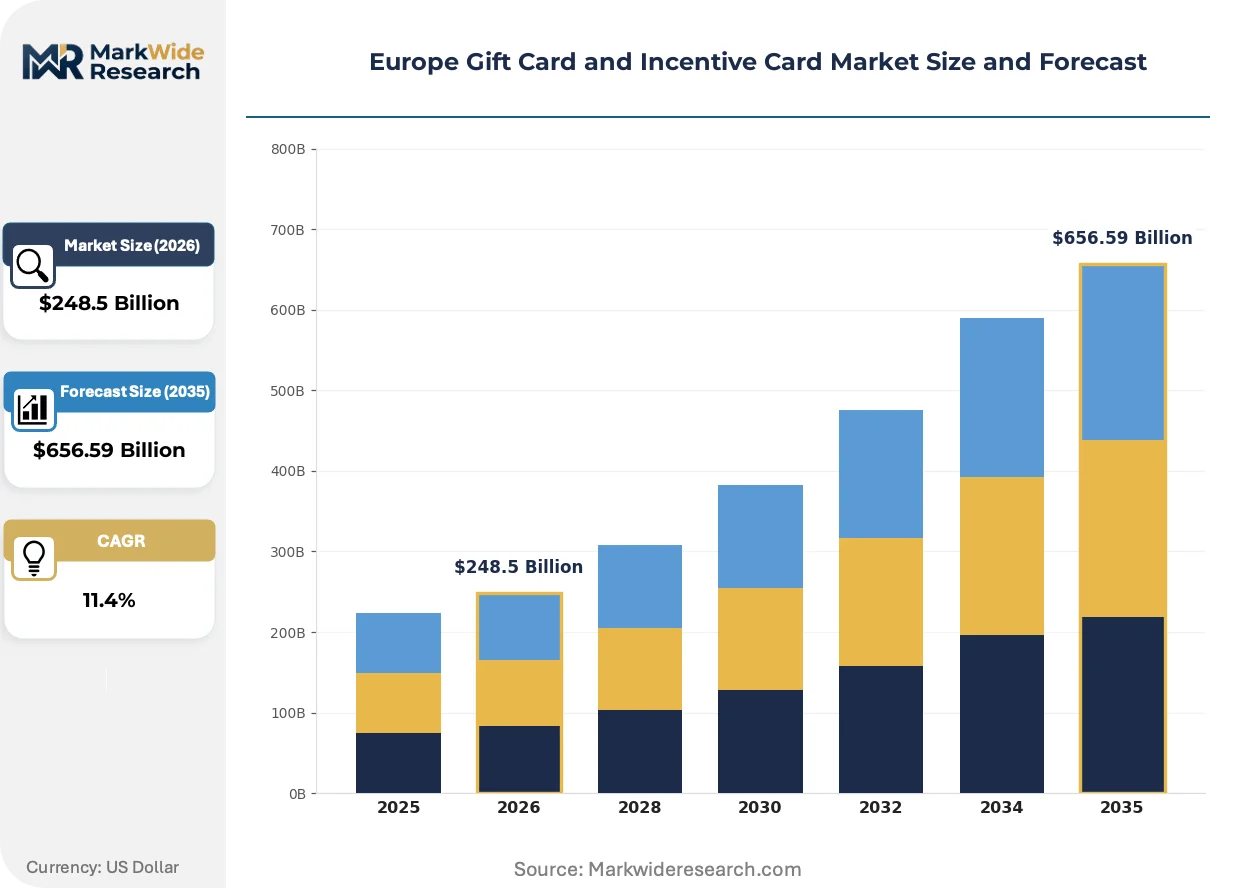
| Market Size in 2026 | $248.5 Billion |
| Market Size in 2035 | $656.59 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Cards, Digital Cards, Prepaid Cards, Virtual Cards Application: Retail, Corporate Incentives, Promotions, Loyalty Programs End User: Consumers, Businesses, Employees, Charities Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, E-commerce Platforms |
| Companies Covered | Edenred, Blackhawk Network, Amazon, WeGift, InComm Payments, Carrefour, Sodexo, Tesco, Zalando, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gift Card and Incentive Card Market Shifts & Advancements
Tokenized virtual cards are overtaking physical plastic as the dominant issuance format, driven by e-commerce platform integration and corporate demand for instant, trackable disbursement.
Virtual card provisioning through Apple Wallet and Google Pay is overtaking physical plastic distribution in the UK and Netherlands. Retailers in these markets report that contactless redemption rates now exceed 70 percent for digital-first gift products. This shift compresses manufacturing and logistics costs while enabling real-time balance tracking.
The EU's Digital Operational Resilience Act imposes mandatory third-party risk management frameworks on card issuers. E-money institutions must now map critical service dependencies and conduct annual resilience testing. French and Belgian program managers are consolidating vendor relationships to reduce compliance documentation burden.
Enterprise procurement teams are consolidating incentive spend with single-platform contracts that bundle gift cards, experiences, and charitable donations. This behavior displaces fragmented departmental purchasing across German automotive suppliers. Procurement departments now prioritize API-first platforms that integrate with Workday and SAP SuccessFactors.
Europe Gift Card and Incentive Card Market Segmentation
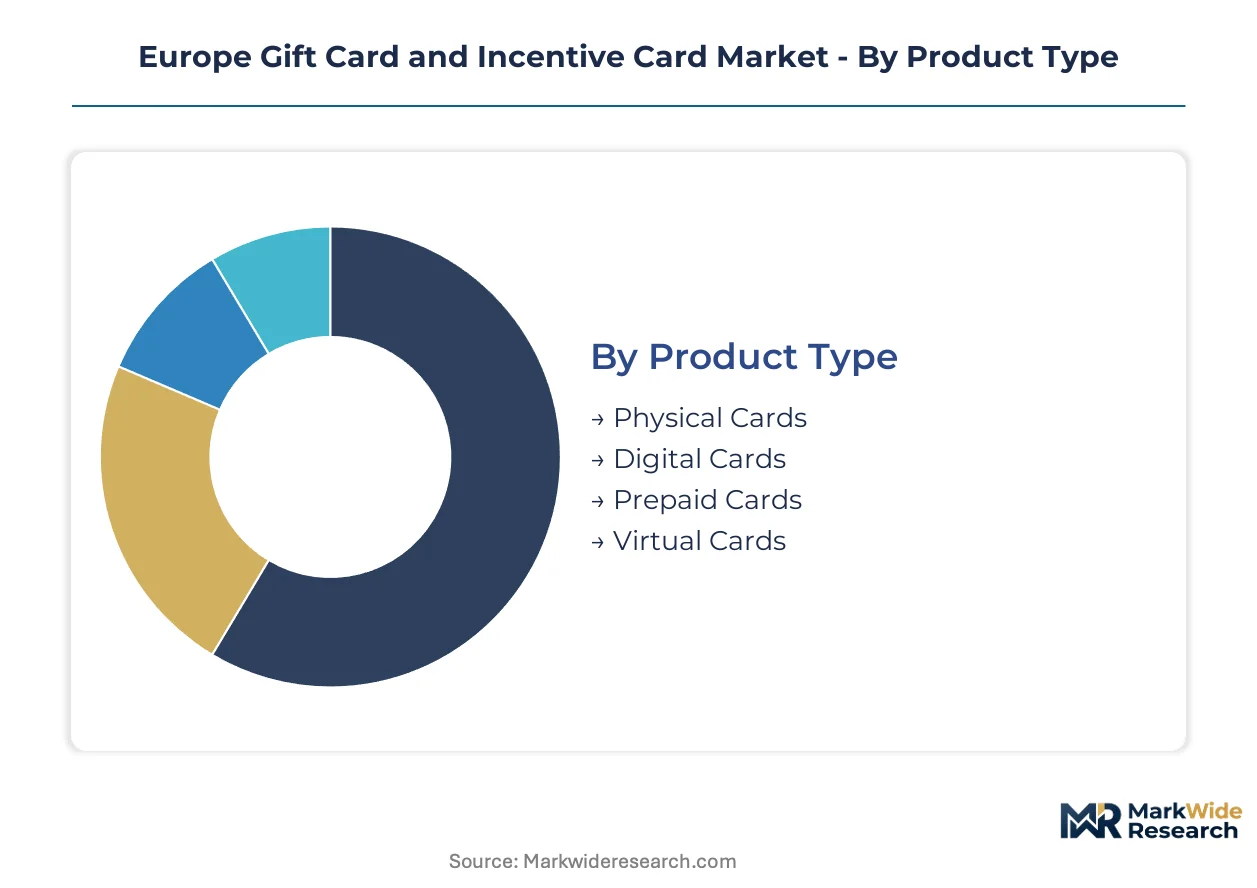
European gift and incentive card procurement patterns diverge sharply across product formats and disbursement contexts. Issuers must align their technology stacks and partnership networks with the specific authentication, settlement, and compliance requirements of each segment cluster.
Product Type:
Manufacturing concentration for physical card substrates in Southeast Asia shapes procurement risk profiles across European issuers.
- Physical Cards:Magnetic stripe and EMV chip cards remain dominant in German retail networks where older POS infrastructure persists. Procurement teams face vulnerability from concentrated Southeast Asian substrate suppliers.
- Digital Cards:Tokenized credentials delivered via email or SMS are climbing the fastest in UK and Netherlands markets where smartphone penetration exceeds 90 percent. Real-time balance tracking and instant issuance reduce float management complexity for corporate clients.
- Prepaid Cards:Open-loop instruments regulated under EU e-money directives require capital reserves that constrain non-bank program managers.
- Virtual Cards:API-generated single-use credentials integrate directly into enterprise payroll platforms for automated incentive disbursement.
Today's leader: Physical Cards. Tomorrow's challenger: Digital Cards.
Application:
Margin structures vary dramatically across use cases, with bulk enterprise contracts commanding pricing premiums over individual retail purchases.
- Corporate Incentives:German automotive and pharmaceutical employers deploy card-based rewards through integrated Workday and SAP SuccessFactors platforms. Recurring subscription contracts and volume guarantees produce the highest per-account margins.
- Retail:Consumer gifting through French and UK supermarket chains retains volume leadership but faces compression from virtual alternatives. Seasonal demand spikes around December strain issuer processing capacity.
- Promotions:Marketing campaign disbursements require rapid bulk issuance with custom branding and expiration management.
- Loyalty Programs:Coalition schemes across Belgian and Dutch retail networks consolidate points-to-card redemption pathways.
Corporate Incentives capture margin concentration. Retail commands transaction volume leadership.
End User:
Authentication requirements under PSD2 Strong Customer Authentication reshape redemption friction across user categories.
- Businesses:Procurement departments consolidate incentive spend with API-first platforms bundling cards, experiences, and charitable donations. French and Belgian program managers prioritize vendor consolidation to reduce DORA compliance documentation burden.
- Employees:Spanish mid-market employers present white space for automated meal and transport benefit platforms with underpenetrated digital disbursement.
- Consumers:Individual purchasers favor contactless redemption through Apple Wallet and Google Pay integration.
- Charities:Donation-directed cards require specialized regulatory treatment across EU member state fundraising laws.
Businesses drive platform consolidation. Employees represent the steepest expansion trajectory for automated welfare disbursement.
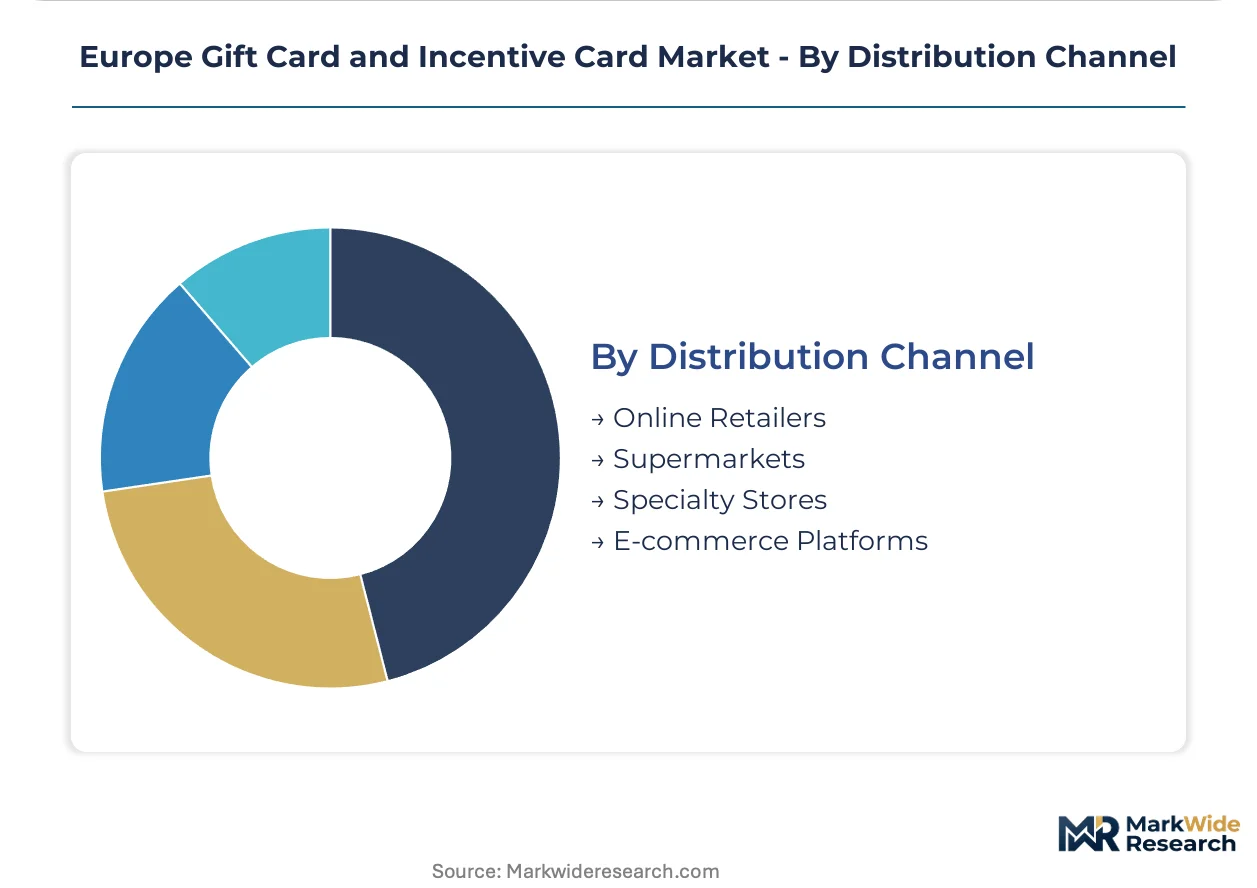
Distribution Channel:
Channel economics shift as instant payment settlement reduces float revenue dependency for digital-first provisioning.
- E-commerce Platforms:Native digital issuance captures younger demographics across French retail networks with seamless mobile wallet integration. Real-time balance tracking and instant delivery eliminate physical logistics costs entirely.
- Supermarkets:UK and Netherlands grocery partnerships anchor physical card placement with high-visibility checkout displays. Blackhawk Network competes aggressively for shelf space in these channels.
- Online Retailers:Third-party marketplaces aggregate demand across fragmented merchant networks with standardized fulfillment.
- Specialty Stores:Niche electronics and luxury retailers maintain curated card assortments targeting premium gifting occasions.
E-commerce Platforms expand most quickly. Supermarkets defend physical volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest corporate incentive penetration while Spain presents the steepest expansion runway for automated employee benefit platforms.
Germany
BMW and Siemens anchor card-based reward disbursement through integrated SAP SuccessFactors payroll systems. The Federal Financial Supervisory Authority (BaFin) enforces e-money capital reserves that constrain non-bank program managers. Stuttgart's automotive supplier cluster drives bulk procurement contracts with recurring volume guarantees.
United Kingdom
Smartphone-native redemption through Apple Wallet and Google Pay exceeds 70 percent contactless usage for digital-first gift products. The Financial Conduct Authority (FCA) mandates Strong Customer Authentication protocols under PSD2 implementation. London's fintech corridor hosts API-native issuers displacing legacy batch-processing platforms.
France
Edenred sustains prepaid meal and incentive card dominance across employer networks concentrated in Paris and Lyon. The Autorité de Contrôle Prudentiel et de Résolution (ACPR) supervises e-money institution licensing with tightened third-party risk frameworks. Île-de-France program managers consolidate vendor relationships to reduce DORA compliance documentation burden.
Netherlands
Blackhawk Network competes aggressively for grocery partnership shelf space with high-visibility checkout displays. The Dutch Central Bank (DNB) enforces Digital Operational Resilience Act incident reporting requirements on card issuers. Amsterdam's retail networks report virtual card provisioning overtaking physical plastic distribution.
Spain
Mid-market employers present white space for automated meal and transport benefit platforms with underpenetrated digital disbursement. The National Securities Market Commission (CNMV) coordinates with EU regulators on instant payment settlement frameworks. Barcelona's corporate welfare technology cluster attracts platform providers targeting southern European expansion.
Europe Gift Card and Incentive Card Market Competitive Landscape
French and Belgian specialists anchor the employer benefit tier; UK and Netherlands grocery-focused operators hold retail distribution density. The vendor base organizes around three strategic archetypes: integrated corporate welfare platforms, retail partnership aggregators, and API-native digital issuance specialists. Competitive dynamics center on M&A consolidation of fragmented mid-market program managers and strategic partnerships with enterprise HR software providers.
Within the integrated corporate welfare tier, Edenred and Sodexo exemplify platform-centric positioning anchored to employer network density. Blackhawk Network occupies the retail partnership aggregator archetype through grocery and supermarket shelf-space dominance. WeGift represents the API-native specialist segment with technology-first provisioning for e-commerce platform integration.
| Leading Market Players |
|---|
| Edenred |
| Blackhawk Network |
| Amazon |
| WeGift |
| InComm Payments |
| Carrefour |
| Sodexo |
| Tesco |
| Zalando |
| Others |
Supply & Pricing Matrix
Horizontal integration into e-money institution licensing anchors both supply position and pricing power across European prepaid card programs. Issuers that control captive e-money licenses under PSD2 avoid third-party program manager fees while commanding premium contract terms from corporate clients seeking integrated disbursement platforms.
Pricing Analysis
Capacity additions in UK and Netherlands fintech corridors are reshaping price floors for digital card issuance infrastructure. Subscription-based platform pricing dominates enterprise contracts, with differentiation driven by API integration depth and DORA compliance bundling. Cost compression in mid-tier e-money licensing is intensifying because BaFin and ACPR have tightened capital reserve requirements. Procurement departments at German automotive suppliers exhibit highest price sensitivity, while French employer networks anchored to Edenred show lowest sensitivity due to switching costs.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian EMV chip and magnetic stripe substrate manufacturers clustered in Thailand and Vietnam. Card substrate production draws from concentrated petrochemical feedstock suppliers in South Korea and Japan, with logistics chokepoints at Rotterdam and Hamburg ports creating downstream distribution risk. Distribution runs through grocery retail partnerships in UK and Netherlands for physical cards, while API-native provisioning bypasses substrate dependencies entirely for digital-first segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Spanish regulatory forbearance and German capital reserve stringency creates cost-efficient expansion pathways for platform providers. The CNMV's lighter-touch e-money supervision versus BaFin's liquidity requirements enables margin-preserving market entry.
For Market Incumbents: To counter API-native fintechs displacing legacy batch-processing platforms, Edenred and Sodexo should deepen employer network density through SAP SuccessFactors integration while consolidating vendor relationships to reduce DORA compliance documentation burden. Captive control over e-money licenses in France and Belgium preserves pricing power against non-bank entrants constrained by EBA capital requirements. For New Entrants and Emerging Players: Spanish mid-market employers represent the most penetrable buyer archetype for automated meal and transport benefit platforms, with digital disbursement penetration lagging northern European benchmarks by several years. A Workday-integrated API-first positioning bypasses incumbent switching costs while capturing procurement consolidation momentum across fragmented southern European HR departments. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier e-money institutions because DORA compliance timelines are forcing sub-scale program managers toward acquisition or exit. Long-term viability hinges on platform density rather than geographic coverage breadth. The signal to watch is M&A velocity among French and Belgian specialists as DORA incident reporting burdens crystallize.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Workday and SAP SuccessFactors connectivity captures procurement consolidation across German automotive employers. |
| E-Money License Acquisition | Captive PSD2 authorization eliminates third-party program manager fees and accelerates instant issuance capabilities. |
| DORA Compliance Bundling | Integrated resilience testing and vendor consolidation reduce documentation burden for French and Belgian program managers. |
| Spanish Market Expansion | Underpenetrated mid-market employer segment offers white space for automated welfare disbursement platforms. |
| Virtual Card Provisioning | Apple Wallet and Google Pay integration eliminates Southeast Asian substrate dependency while capturing 90-percent smartphone penetration markets. |
Research Methodology
Coverage spans Germany, United Kingdom, France, Netherlands, and Spain, with primary inputs from each national regulatory cluster. The analysis combines structured interviews with e-money institution compliance officers, enterprise HR platform directors, and grocery retail category buyers with secondary validation against EBA regulatory filings, national central bank licensing databases, and EU payment scheme interchange data. Bottom-up triangulation across issuer transaction volumes and top-down reconciliation against employer benefit expenditure surveys anchor the market sizing framework.
Rate-of-change decomposition separates volume expansion from value-per-transaction evolution across the projection horizon. Segmentation dimensions modeled include product format, application context, end-user archetype, and distribution channel, with additional granularity on PSD2 compliance tier and DORA readiness status. CAGRs derive from regression analysis of historical issuance velocity against corporate HR digitization indices and open banking API penetration curves. Industry-specific forecast inputs incorporate EBA capital reserve requirement trajectories and EU instant payment settlement adoption timelines.
Underlying measurement precision varies by segment; digital card and virtual card categories carry tighter precision than physical card substrates given data availability from API-native issuers. Forecasts reflect assumptions around regulatory implementation timelines and corporate procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Online Payment Gateway Market
Payments
Forex Cards Market
Payments
Global Payment Monitoring Market
Payments
United States Payment Gateways Market
Payments
Direct Carrier Billing Platform Market
Payments
Romania POS Terminals Market
Payments
Spain POS Terminals Market
Payments
Japan Virtual Cards Market
Payments
United Kingdom Payment Market
Payments
Italy Payments Market
Payments
Slovakia POS Terminal Market
Payments
Africa Mobile Money Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Netherland Payments Market
Payments
Clearing Houses and Settlements Market
Payments
B2B Payments Platform Market