
 Credit Card Issuance Services Market | 2026-2036
Credit Card Issuance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Card Issuance Services Market Outlook
Software-defined rewards personalization is shifting the core value proposition away from static APR tiers toward dynamic, transaction-triggered benefits. Chase leverages its travel and dining partnerships to sustain premium cardholder engagement across geographies. Marqeta differentiates through API-first card program management that lets fintechs launch branded products without legacy processor dependencies. Capital One anchors mass-market acquisition through data-science-driven prequalification and digital-first onboarding.
Credit card issuance services encompass the end-to-end infrastructure enabling financial institutions to underwrite, produce, activate, and manage payment card programs, encompassing BIN sponsorship, card personalization with EMV chip encoding, authorization systems, and real-time fraud scoring engines. The primary commercial purpose centers on converting consumer and commercial credit risk into recurring interchange and interest income streams while minimizing operational loss rates. Reward Cards command disproportionate attention from issuers because annual fee structures and merchant-funded redemption pools generate superior yield per active account. Contactless Payments and Mobile Wallets represent the fastest-growing technology dimension, displacing magnetic-stripe and chip-and-PIN transaction volumes at physical terminals. Co-Branded Cards remain structurally attractive for airlines and retailers seeking direct consumer payment relationships, though margin pools increasingly shift toward program management fees rather than pure interchange splits.
The US Consumer Financial Protection Bureau supervises fair lending disclosures and late-fee structures, while the Federal Reserve governs capital reserve requirements affecting issuer underwriting capacity. The EU's PSD2 and forthcoming PSD3 frameworks mandate strong customer authentication and open API access, compelling European issuers to modernize core authorization platforms. Stakeholders must monitor how central bank digital currency pilots and real-time payment network expansion reshape the competitive necessity of physical card issuance infrastructure.
Market Dynamics
Real-time payment network expansion and open banking mandates are compressing the traditional card issuance value chain, forcing processors to modernize core authorization infrastructure or cede volume to account-to-account alternatives.
Growth Catalysts
- Embedded Finance Proliferation:Non-bank platforms in ride-sharing and e-commerce are launching branded card programs through BIN sponsorship, expanding addressable issuance volume beyond traditional banking channels.
- PSD2 and Open Banking APIs:European regulators have mandated standardized data sharing, compelling issuers to build consent-management layers that unlock personalized underwriting and dynamic reward engines.
- Small Business Expense Management:Digital-native challenger banks are targeting freelancers and micro-merchants with integrated corporate cards, creating new issuance demand from previously unserved segments.
Market Restraints
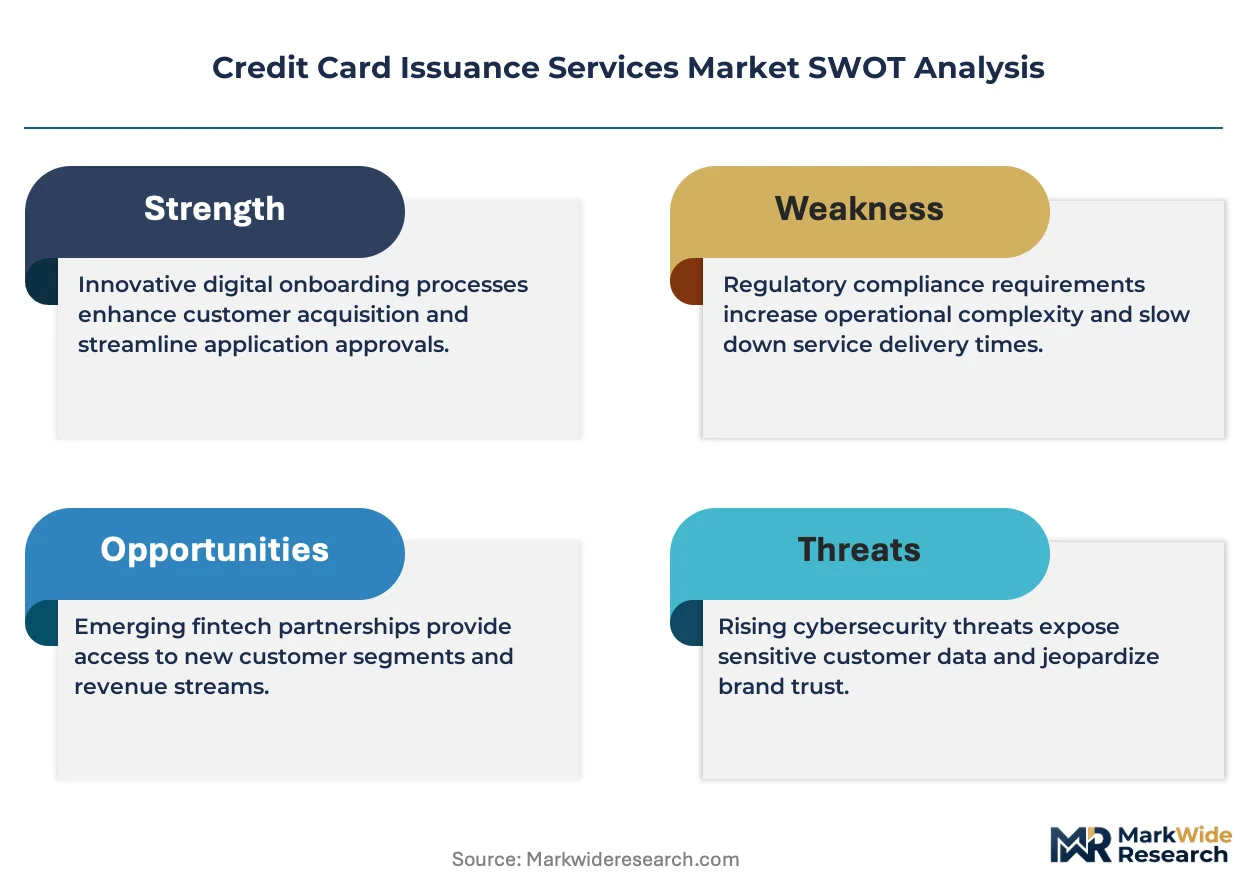
- Interchange Rate Compression:Regulatory caps on merchant fees in Australia and the European Union directly constrain issuer revenue pools, pressuring program economics.
- Core Processor Concentration:Three legacy platforms dominate BIN sponsorship and authorization switching, creating single-point-of-failure risk and limiting pricing leverage for emerging issuers.
- Fraud Liability Migration:EMV liability shifts and strong customer authentication requirements under PSD2 have transferred operational risk to issuers without proportional fee adjustments.
Strategic Opportunities
- Central Bank Digital Currency Integration:Pilot programs in Brazil and India are creating hybrid infrastructure where card networks bridge fiat and CBDC rails, positioning early issuers as interoperability providers.
- Biometric Authentication Convergence:Fingerprint and facial recognition technologies are merging with tokenization standards, enabling passwordless transaction approval that reduces abandonment at checkout.
- Cross-Border SME Banking:Underpenetrated corridors between Southeast Asian manufacturing hubs and European importers present white space for multi-currency card programs with embedded FX hedging.
Industry Challenges
- Legacy Core Modernization:Decades-old authorization platforms require multi-year migration timelines to cloud-native architectures, delaying API-first product launches.
- Certification Backlogs:EMVCo and PCI DSS compliance queues stretch 12-18 months, throttling speed-to-market for new card programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Card Issuance Services Market |
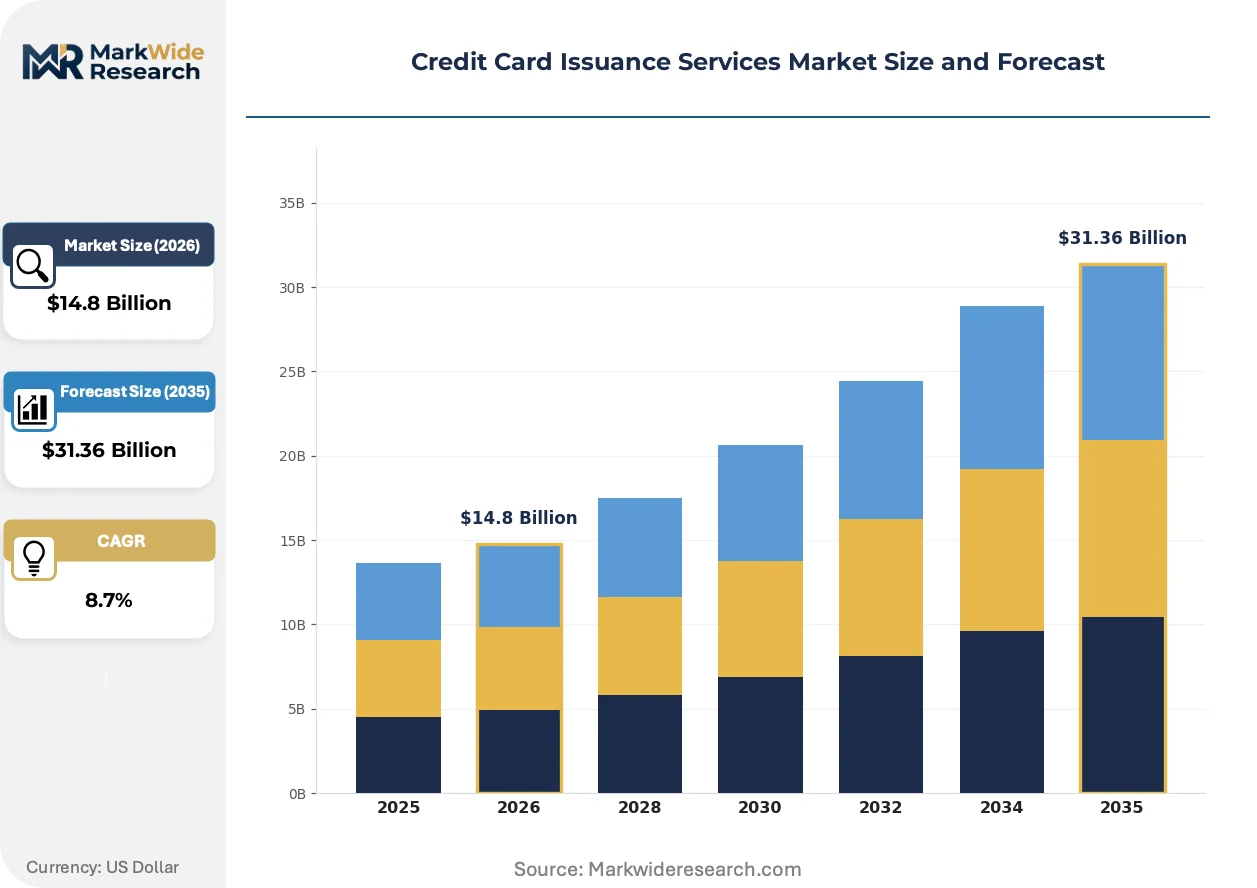
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cards, Reward Cards, Business Cards, Co-Branded Cards Service Type: Issuance, Processing, Customer Support, Fraud Prevention Client Type: Individuals, Small Businesses, Corporations, Government Agencies Technology: Chip Technology, Contactless Payments, Mobile Wallets, Blockchain |
| Companies Covered | Capital One, Marqeta, Chase, Galileo, Fiserv, American Express, Bank of America, Paymentology, Citi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Card Issuance Services Market Strategic Shifts
Software-defined card programs are displacing hardware-centric personalization, enabling issuers to reconfigure reward structures and spending controls without physical reissuance. This shift compresses product development cycles and expands test-and-learn capabilities.
Tokenization infrastructure is integrating directly into mobile wallet provisioning, replacing static primary account numbers with device-bound credentials. Challenger banks and fintechs are adopting this architecture fastest, embedding cards into merchant apps before physical plastic ships. The structural consequence is decoupling card issuance from physical manufacturing, collapsing time-to-activation from weeks to minutes.
The US Consumer Financial Protection Bureau's open banking rulemaking and the EU's PSD3 draft are mandating standardized API access and consent frameworks. These regulations compel issuers to expose transaction data to third-party providers under customer direction, transforming data monetization from proprietary advantage to regulated utility. European issuers face the steepest compliance curves, with authentication requirements expanding to cover all remote transactions.
Merchant-funded rewards are displacing issuer-funded points programs as the dominant engagement mechanism. Retailers and airlines are directly purchasing transaction data and funding statement credits, shifting program economics toward data brokerage. This pattern concentrates in the United States where co-brand partnerships sustain higher interchange yields, though European issuers are piloting similar structures within PSD2 consent boundaries.
Credit Card Issuance Services Market Segmentation
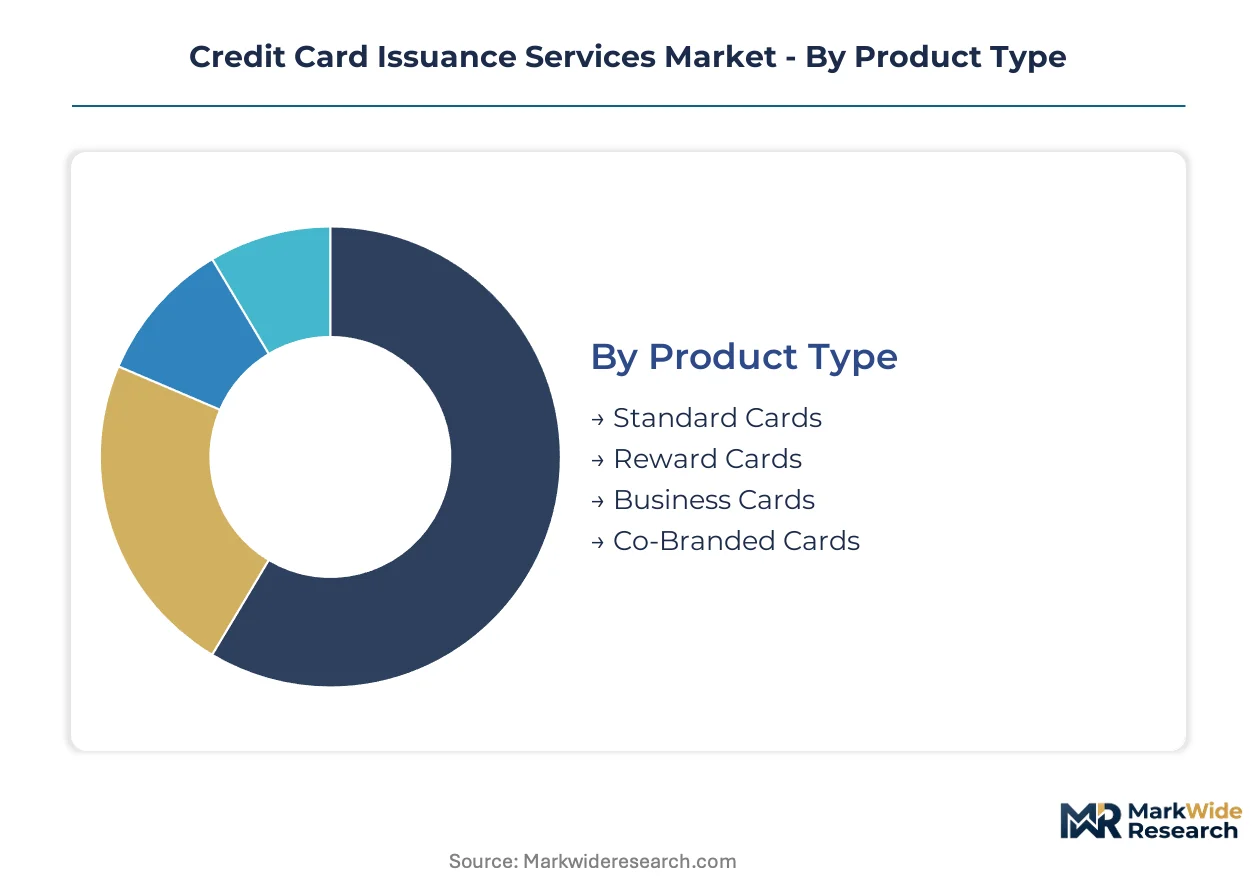
Credit card issuance services fragment across product design, operational delivery, and client engagement models. Each dimension carries distinct margin profiles and infrastructure requirements that reshape competitive positioning.
Product Type:
Integration depth varies sharply—some products operate as standalone financial instruments while others embed deeply into merchant ecosystems and travel platforms.
- Reward Cards:Annual fee structures and merchant-funded redemption pools generate superior yield per active account. Demand concentrates in the United States where Chase and American Express sustain premium cardholder engagement through travel and dining partnerships.
- Co-Branded Cards:Airlines and retailers purchase direct consumer payment relationships, though economics now tilt toward program management fees rather than pure interchange splits. Delta and United maintain flagship partnerships that anchor issuer portfolios.
- Standard Cards:Mass-market acquisition tools with thin margins requiring scale efficiency.
- Business Cards:Integrated expense management features target freelancers and micro-merchants previously underserved by commercial banking.
Volume placements concentrate in Reward Cards; the faster expansion belongs to Co-Branded Cards.
Service Type:
Cost tier stratification separates high-touch advisory functions from automated infrastructure layers.
- Processing:Real-time authorization systems and BIN sponsorship form the technical backbone of issuance. Demand clusters among fintechs seeking API-first program management without legacy processor dependencies.
- Fraud Prevention:EMV chip encoding and real-time scoring engines minimize operational loss rates. European issuers face steepest compliance curves under PSD2 strong customer authentication mandates.
- Issuance:End-to-end underwriting and card production workflows.
- Customer Support:Digital-first onboarding and account servicing functions.
Processing commands the largest share of service expenditure; Fraud Prevention is climbing the fastest as liability shifts intensify.
Client Type:
Application context determines risk calibration and product configuration complexity.
- Small Businesses:Digital-native challenger banks target this segment with integrated corporate cards and embedded expense management. Brex and Ramp have captured significant share from traditional commercial banking.
- Corporations:Treasury integration and multi-entity spend controls drive procurement decisions.
- Individuals:Mass-market consumers reached through data-science-driven prequalification.
- Government Agencies:Procurement card programs with strict compliance and audit trail requirements.
Small Businesses show the steepest expansion trajectory; Corporations anchor current volume.
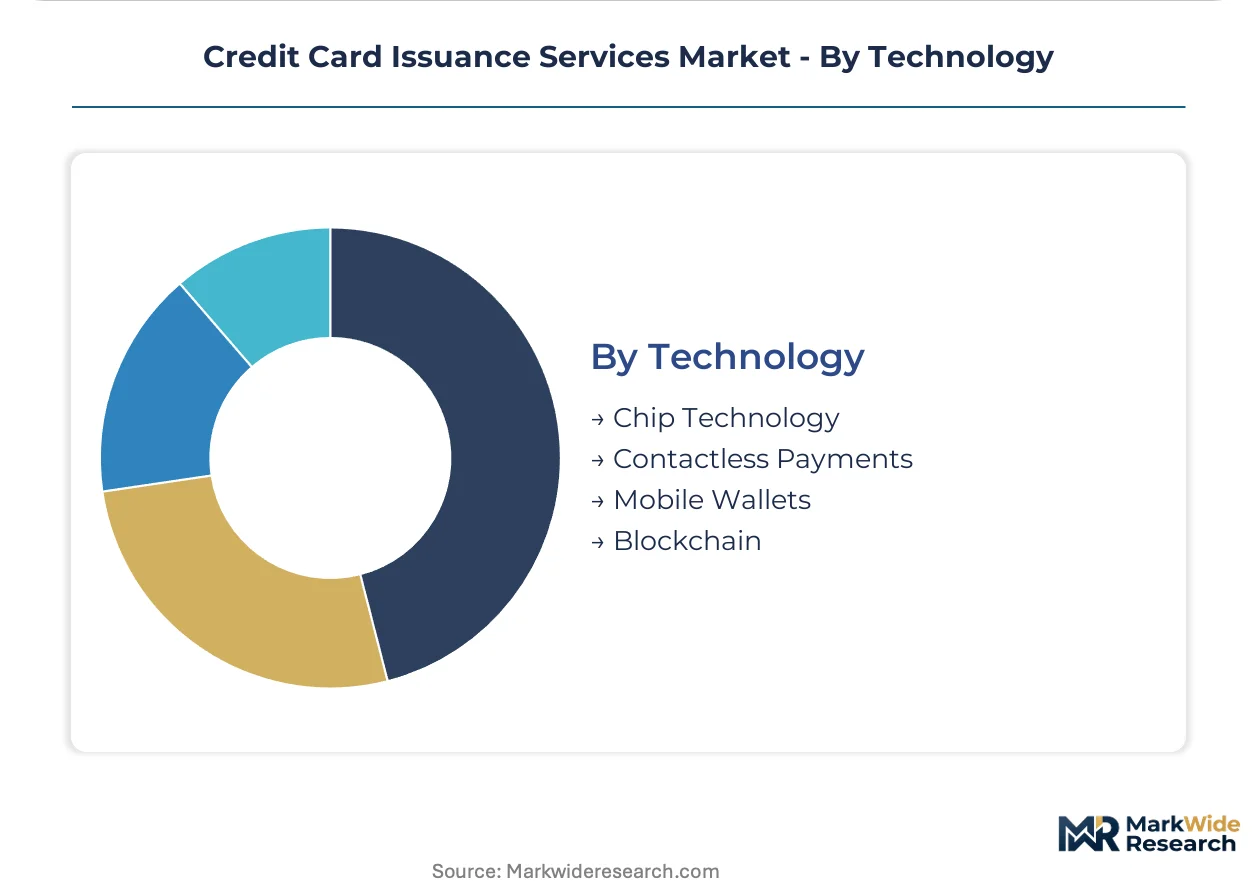
Technology:
Maturity curves separate established authentication methods from emerging infrastructure.
- Contactless Payments:Displacing magnetic-stripe and chip-and-PIN volumes at physical terminals through tap-to-pay convenience. Transit authorities in London and New York have accelerated adoption by accepting open-loop payments.
- Mobile Wallets:Tokenization infrastructure enables device-bound credentials that collapse activation timelines from weeks to minutes. Apple Pay and Google Pay provisioning dominate smartphone-based issuance.
- Chip Technology:EMV standards remain baseline for fraud liability compliance.
- Blockchain:Pilot programs explore settlement efficiency and programmable money integration.
Chip Technology retains volume dominance; Mobile Wallets are gaining share fastest among challenger bank deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Credit card issuance infrastructure concentrates where interchange economics and regulatory frameworks sustain program profitability. Production of processing technology clusters in financial centers, while cardholder acquisition concentrates in markets with mature reward ecosystems.
United States
Co-brand partnerships with airlines and retailers anchor issuer profitability through premium annual fee structures. The Consumer Financial Protection Bureau supervises fair lending disclosures and late-fee limitations, constraining revenue model flexibility. New York and San Francisco host the dominant fintech clusters where challenger banks launch API-first card programs.
United Kingdom
Open banking adoption through PSD2-mandated APIs has accelerated personalized underwriting and dynamic reward engines. The Financial Conduct Authority governs strong customer authentication requirements for remote transactions. London's financial district concentrates BIN sponsorship and tokenization infrastructure providers serving European fintech expansion.
Germany
Savings bank cooperatives and regional institutions dominate card issuance, resisting fintech penetration compared to neighboring markets. The Federal Financial Supervisory Authority enforces PSD2 compliance timelines for authentication modernization. Frankfurt's banking quarter houses core processor data centers serving Central European authorization networks.
Brazil
Central bank digital currency pilots are creating hybrid infrastructure where card networks bridge fiat and CBDC rails. The Central Bank of Brazil regulates interchange fee structures and open finance data-sharing mandates. São Paulo's fintech corridor hosts emerging issuers targeting underbanked micro-merchants with integrated corporate card programs.
India
Unified Payments Interface expansion and RuPay network growth are compressing traditional card transaction volumes while expanding digital payment penetration. The Reserve Bank of India governs prepaid instrument licensing and data localization requirements for payment processors. Mumbai's financial district and Bangalore's technology corridor concentrate issuer technology development centers.
Credit Card Issuance Services Market Competitive Environment
Capital-heavy legacy processors compete with asset-light API-first platforms for fintech partnership volumes. The vendor base stratifies across three tiers: global banking conglomerates with captive issuance arms, specialized processor networks handling BIN sponsorship and authorization switching, and modular infrastructure providers enabling rapid program deployment. Dominant competitive moves include strategic API ecosystem partnerships and geographic expansion into underpenetrated SME banking corridors.
Within the legacy processor tier, Fiserv and FIS exemplify scale-driven infrastructure consolidation. Among API-first challengers, Marqeta and Galileo occupy positions enabling fintechs to launch branded products without legacy dependencies. Chase and Capital One anchor the banking conglomerate archetype, sustaining mass-market acquisition through data-science-driven prequalification and digital-first onboarding workflows.
| Leading Market Players |
|---|
| Capital One |
| Marqeta |
| Chase |
| Galileo |
| Fiserv |
| American Express |
| Bank of America |
| Paymentology |
| Citi |
| Others |
Value Chain & Pricing Dynamics
Fintech procurement preferences for API-first program management are compressing legacy processor margins and forcing infrastructure providers toward cloud-native delivery models that sacrifice near-term yield for platform stickiness.
Pricing Analysis
Margin tightening in BIN sponsorship reflects interchange rate compression in Australia and the European Union. Three-tier pricing structure across premium, standard, and economy levels stratifies by authentication sophistication and fraud liability coverage. Cost-down pressure on processing tiers accelerates because fintechs demand per-transaction economics over fixed licensing. Small business card programs show highest price sensitivity; premium reward portfolios retain pricing power through merchant-funded redemption structures.
Supply Chain Analysis
Regional distribution centers in the United States, United Kingdom, and Germany concentrate EMV chip personalization and tokenization infrastructure. Hardware production draws from semiconductor foundries in Taiwan, card substrate manufacturers in China, and secure element fabricators in South Korea. Single-source vulnerability sits with legacy core processor concentration affecting authorization switching. Distribution runs through BIN sponsorship networks that bridge issuer programs to card network rails.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from real-time payment network expansion will eliminate processors unable to modernize authorization infrastructure within viable investment windows.
For Market Incumbents: Extend API ecosystem partnerships to defend against Marqeta and Galileo capturing fintech issuance volume. Invest in cloud-native core migration to offset legacy platform technical debt. Pursue certification pre- clearance with EMVCo and PCI DSS to compress 12-18 month compliance queues throttling competitor speed-to-market. For New Entrants and Emerging Players: PSD2 in the European Union opens a window for consent-management layer specialization targeting personalized underwriting engines. Target underpenetrated Southeast Asian SME banking corridors with multi-currency card programs. Deploy merchant app embedding before physical card fulfillment to collapse activation timelines. For Investors and Strategic Acquirers: Re-rating potential sits with modular infrastructure providers given central bank digital currency pilot integration demands. Long-term viability favors API-first platforms with demonstrated fintech partnership scalability. Watch CBDC interoperability announcements in Brazil and India as inflection signals for hybrid infrastructure positioning.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Enables fintechs to launch branded card programs without legacy processor dependencies. |
| Biometric Authentication Integration | Merges fingerprint and facial recognition with tokenization standards for passwordless approval. |
| CBDC Interoperability Development | Positions early issuers as bridge providers between fiat rails and central bank digital currencies. |
| Merchant-Funded Rewards Expansion | Shifts program economics from issuer-funded points toward data brokerage revenue pools. |
| Cross-Border SME Banking Entry | Captures white space in manufacturing hub corridors with embedded FX hedging capabilities. |
Study Parameters
SEC 10-K filings, central bank regulatory disclosures, and EMVCo compliance databases formed the secondary backbone for issuer infrastructure mapping. Primary interviews with payment processor executives, fintech product managers, and BIN sponsorship directors validated technology adoption timelines. Bottom-up triangulation across service type expenditure and top-down reconciliation against interchange revenue pools produced volume estimates.
Historical trendline analysis of authorization system deployments and card program launches informed projection modeling across the analysis window. Segmentation dimensions included product type, service tier, client archetype, and technology maturity curve. CAGRs derived from weighted average of issuer capital expenditure patterns and fintech partnership formation rates. Forecast inputs incorporated PSD2 compliance timelines and CBDC pilot expansion schedules.
Caveats apply where regulatory interchange caps, core processor consolidation, or authentication standard revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding fintech partnership velocity and legacy migration investment cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Japan Virtual Cards Market
Payments
North America Accounts Payable Automation Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Remote Deposit Capture Market
Payments
Outdoor Payment Terminal Market
Payments
Brazil POS Terminal Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Russia Payments Market
Payments
Online Payment Gateway Market
Payments
United States Clearing Houses and Settlements Market
Payments
Digital Debit Market
Payments
United States POS Terminals Market
Payments
Retail Point of Sale (POS) Market
Payments
APAC Mobile Payments Market
Payments
Mexico Real Time Payments Market