
 Commercial Vehicle Rental and Leasing Market | 2026-2036
Commercial Vehicle Rental and Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Rental and Leasing Market Intelligence
Fleet diversification by major rental providers in Europe is broadening the availability of specialized commercial vehicles. Ryder System specializes in full-service leasing and integrated supply chain solutions for North American clients. Penske Truck Leasing leverages its extensive network for logistics support and contract maintenance. In contrast, Sixt SE competes by offering flexible short-term rental options across a wide range of vehicle classes.
Commercial vehicle rental and leasing provides businesses with temporary access to vehicles for operational use without a capital purchase. This model covers assets with specific gross vehicle weight ratings (GVWR) designed for cargo transport or specialized industrial tasks. The full-service lease segment is expanding, particularly for heavy-duty trucks in the logistics vertical, as it includes maintenance and compliance. Short-term rentals remain vital for corporates and SMEs to manage seasonal demand spikes in construction and transportation.
Regulations like the EPA's emission standards in the United States and the EU's F-Gas Regulation for refrigerated transport directly shape fleet investment. In China, MIIT mandates on vehicle telematics and safety influence technology adoption. These rules compel rental companies to continuously update their fleets with compliant, modern vehicles. Future profitability depends on balancing the high capital cost of electric vehicle adoption against long-term operational savings and regulatory mandates.
Market Dynamics
The central dynamic in the commercial vehicle rental market is the tension between immense capital requirements for fleet modernization and the operational imperative to serve escalating logistics demand. This pressure forces firms to balance investment in compliant, high-cost assets against customer needs for cost-effective capacity.
Growth Catalysts
- E-commerce Expansion:The sustained growth of online retail directly fuels requirements for light and medium-duty commercial vehicles for last-mile delivery and urban logistics networks, creating a constant replacement and expansion cycle for rental fleets.
- Regulatory Mandates:Emission reduction targets under frameworks like the EU Green Deal compel fleet operators to adopt newer, cleaner vehicles, making leasing an attractive option to avoid the full capital cost of compliance and fleet turnover.
- Asset-Light Business Models:Corporations and SMEs increasingly favor leasing and rental to preserve capital, reduce balance sheet liabilities, and convert a large capital expenditure into a predictable operational expense, improving financial flexibility.
Market Restraints
- High Capital Expenditure:The significant upfront investment needed to acquire and maintain a modern fleet, especially with the higher purchase price of electric and alternative fuel trucks, acts as a major barrier to entry and a constraint on expansion.
- Regulatory Fragmentation:Disparate standards for vehicle safety, emissions, and telematics, such as conflicting requirements between China's MIIT and regulations in Europe, create operational complexity and increase compliance costs for multinational lessors.
- Infrastructure Deficiencies:A lack of robust public charging and alternative fueling infrastructure for heavy-duty commercial vehicles limits the operational viability and geographic range of electric and hydrogen-powered trucks, slowing their adoption in lease portfolios.
Strategic Opportunities
- Value-Added Services:Integrating advanced telematics, predictive maintenance analytics, and fleet management software into leasing packages creates new revenue streams and enhances customer retention by offering operational efficiency gains beyond the physical asset.
- Specialized Vehicle Segments:There is a clear opportunity in offering specialized vehicles for cold chain logistics, driven by pharmaceutical and food industry needs, which are governed by strict standards like the EU's F-Gas Regulation.
- Emerging Market Penetration:Expanding rental and leasing services into developing logistics hubs in Southeast Asia and Latin America offers access to new customer bases where capital constraints make direct vehicle ownership challenging for local businesses.
Industry Challenges
- Technical Skill Shortages:A persistent shortage of technicians qualified to service and repair advanced vehicle technologies, including electric powertrains and complex electronic systems, creates maintenance bottlenecks and increases operational costs for leasing companies.
- Residual Value Uncertainty:The unpredictable long-term resale value of current-generation electric vehicles and, conversely, aging diesel trucks creates significant financial risk and complicates the setting of long-term lease rates and depreciation schedules.
- Cybersecurity Threats:Protecting the vast amounts of data generated by connected vehicle fleets from cyberattacks is a critical operational challenge, requiring continuous investment in security protocols to prevent data breaches and vehicle system compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Rental and Leasing Market |
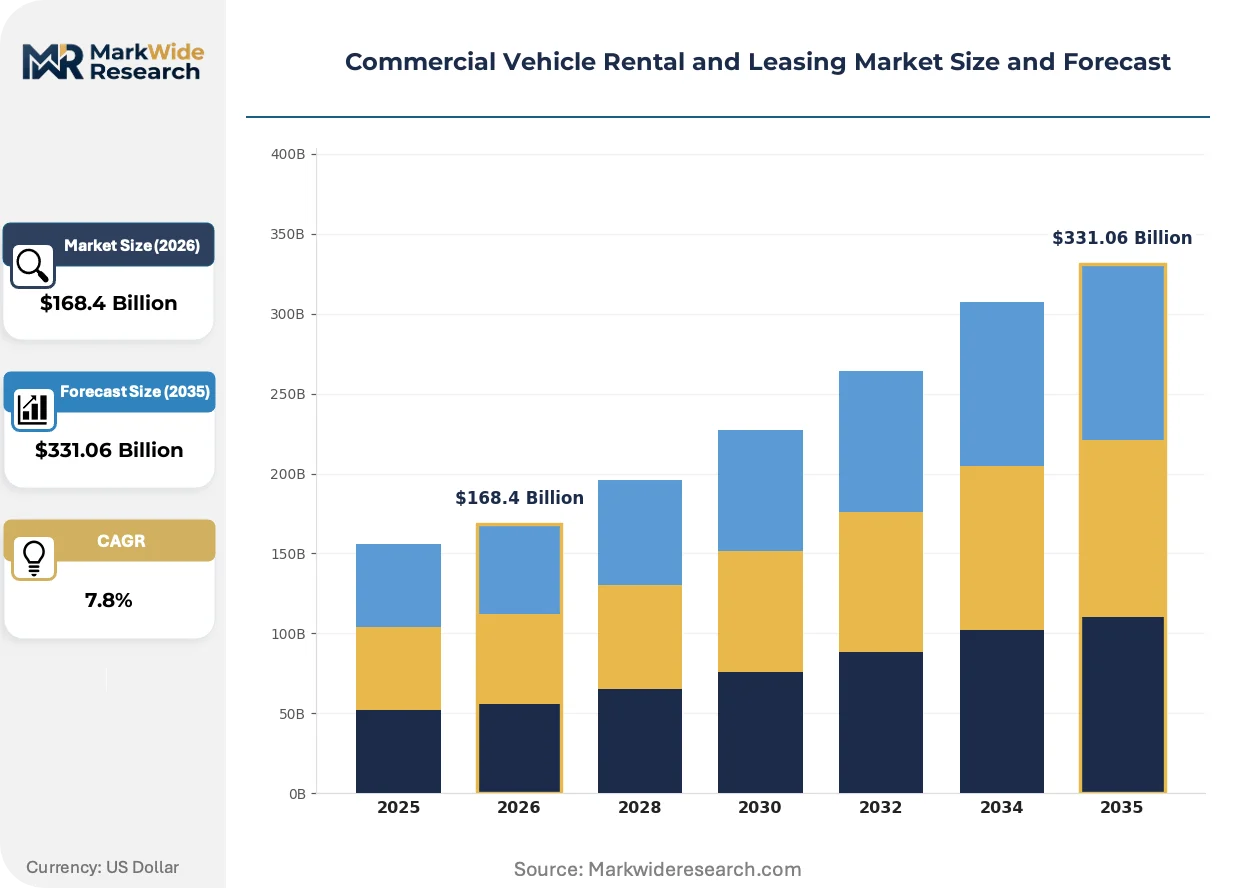
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $331.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Vans, Buses Service Type: Short-term Rental, Long-term Lease, Full-service Lease, Maintenance Lease Customer Segment: Corporates, SMEs, Government, Individual Industry Vertical: Transportation, Construction, Logistics, Hospitality |
| Companies Covered | Sixt SE, Europcar, Enterprise Holdings, Hertz Global Holdings, ALD Automotive, Ryder System, LeasePlan Corporation, Avis Budget Group, Penske Truck Leasing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Rental and Leasing Market Strategic Shifts & Innovations
The convergence of sustainability mandates and data analytics is fundamentally altering the commercial vehicle leasing model. Service offerings are evolving from simple asset provision to integrated, data-driven solutions that prioritize uptime, compliance, and total cost of ownership for the end-user.
Telematics platforms integrate GPS, engine diagnostics, and driver behavior monitoring. Logistics and construction sectors adopt these systems to optimize fuel use and asset utilization. This integration of hardware and software is modularizing fleet management, allowing customers to select specific data services like compliance reporting or predictive maintenance.
The United States Environmental Protection Agency (EPA) implements stricter emission standards for heavy-duty vehicles. This forces rental companies to invest in cleaner engines or alternative fuels for a compliant fleet. The heavy-duty truck leasing segment is most affected, accelerating asset retirement and influencing lease pricing to cover new technology costs.
A notable behavioral shift involves customers demanding flexible contracts over rigid multi-year leases. This disrupts the traditional full-service leasing model, with on-demand and pay-per-mile options gaining traction. This trend is prominent among SMEs in last-mile delivery across North America and Europe, who need to scale fleets dynamically.
Commercial Vehicle Rental and Leasing Market Segmentation
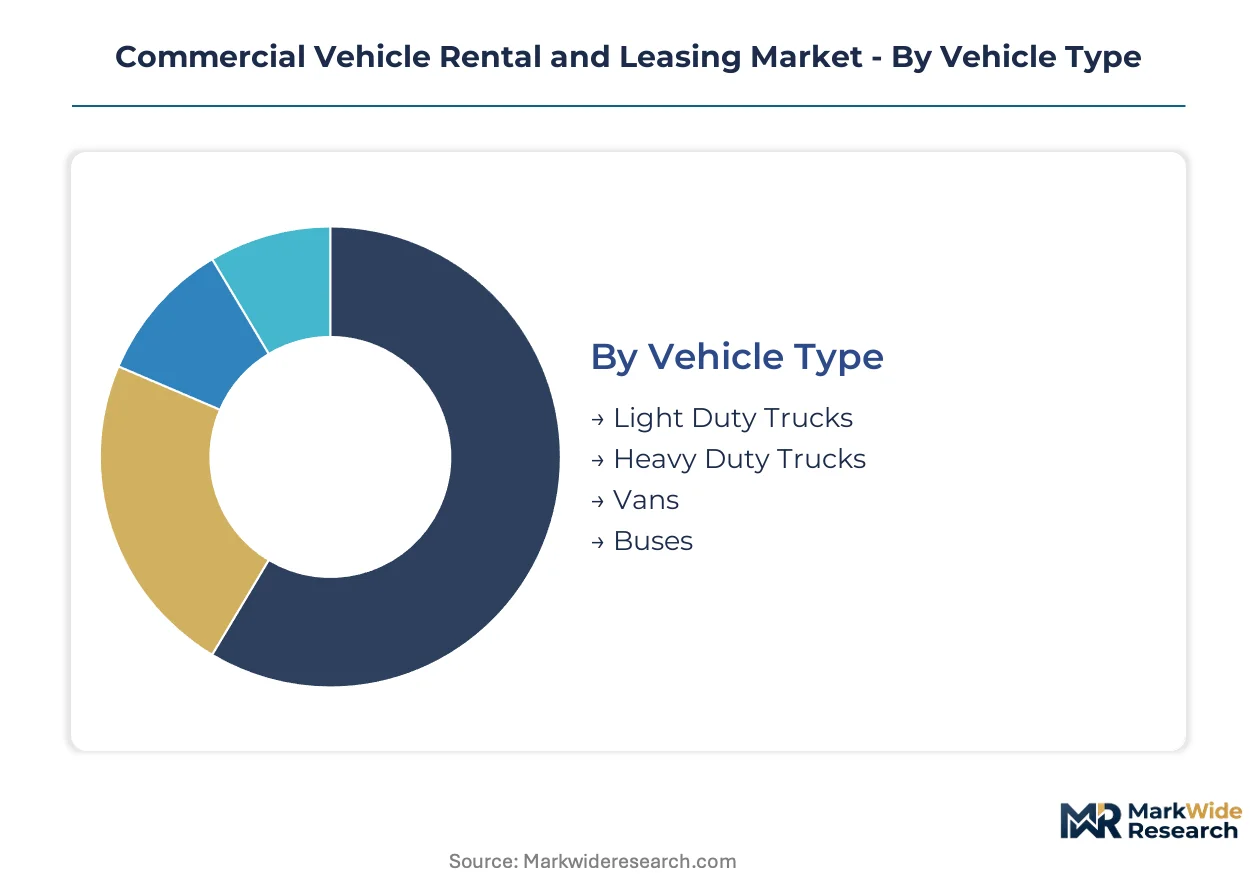
The commercial vehicle rental and leasing market exhibits diverse segmentation, reflecting varied operational needs and regulatory landscapes across industries. Understanding these distinct segments allows providers to tailor offerings, from specialized vehicle types to flexible service models, optimizing asset utilization and client satisfaction. This granular view highlights where capital investment and service innovation are most impactful.
Vehicle Type:
The vehicle type segmentation is particularly sensitive to certification burdens, with heavy-duty vehicles facing stringent emission and safety approvals from bodies like the EPA in the United States and the EU Green Deal in Europe.
- Heavy Duty Trucks:These vehicles possess a gross vehicle weight rating (GVWR) exceeding 26,000 pounds, designed for long-haul freight and heavy cargo transport. Demand concentrates in the logistics sector across North America, driven by e-commerce fulfillment and the need for compliant, high-capacity assets.
- Light Duty Trucks:Characterized by a GVWR typically below 10,000 pounds, these trucks serve last-mile delivery, utility work, and urban logistics. Expansion is prominent in European cities, where e-commerce growth mandates flexible fleets for efficient urban distribution.
- Vans:This segment includes cargo vans and passenger vans, frequently used for courier services, small-scale deliveries, and shuttle operations.
- Buses:Buses cater to public transportation, corporate shuttles, and school transport, requiring specific passenger safety certifications.
Heavy Duty Trucks sits at the top of the volume ranking, with Light Duty Trucks climbing the fastest.
Service Type:
The service type segmentation reflects a clear differentiation in cost tiers, with full-service models commanding higher premiums due to their comprehensive inclusions, while short-term options offer lower entry points for episodic needs.
- Full-service Lease:This comprehensive model includes the vehicle, maintenance, repairs, and often compliance management, converting capital expenditure into a predictable operational expense. Businesses in the logistics vertical in the United States increasingly favor this for heavy-duty trucks to ensure uptime and regulatory adherence.
- Short-term Rental:Providing temporary access to commercial vehicles for periods ranging from a day to several months, this service type addresses seasonal demand spikes or project-specific requirements. Small and medium-sized enterprises (SMEs) in construction across Europe rely on these flexible options.
- Long-term Lease:Customers secure vehicles for extended periods, typically one to five years, without the full maintenance package of a full-service lease.
- Maintenance Lease:This option bundles the vehicle with a predefined maintenance schedule and repair services, reducing unexpected operational costs.
The market shows Full-service Lease models gaining significant traction, particularly among large corporate clients seeking operational efficiency.
Customer Segment:
The customer segment segmentation highlights distinct purchasing behaviors, with corporates prioritizing integrated solutions and SMEs valuing financial flexibility, each driving demand for tailored rental and leasing products.
- Corporates:Large enterprises with extensive logistics operations or significant fleet requirements, often seeking integrated solutions and full-service leasing arrangements. These clients prioritize fleet uptime and compliance with regulations like the EU's F-Gas Regulation for refrigerated transport.
- SMEs:Small and medium-sized enterprises that leverage rental and leasing to manage capital, access modern vehicles, and scale operations without large upfront investments. Last-mile delivery firms in North America represent a substantial portion of this demand for light and medium-duty vehicles.
- Government:Public sector entities and municipalities requiring vehicles for various services, often procured through competitive bidding processes.
- Individual:Sole proprietors or independent contractors who rent commercial vehicles for specific tasks or short-term operational needs.
Corporates demonstrate a sustained demand for comprehensive leasing packages, while SMEs are expanding most quickly in the short-term rental category.
Industry Vertical:
This industry vertical segmentation underscores the diverse application of commercial vehicles, with logistics and construction standing out due to their intensive and often specialized equipment needs.
- Logistics:This vertical encompasses freight transport, warehousing, and parcel delivery, heavily relying on commercial vehicles for supply chain operations. The e-commerce expansion in the United States fuels constant demand for light and heavy-duty trucks to support last-mile and regional distribution.
- Construction:The construction sector utilizes commercial vehicles for material transport, equipment delivery, and site support, often requiring specialized trucks and vans. Project-based demand in European infrastructure development drives significant short-term rental activity.
- Transportation:This segment includes general passenger and goods transport services, excluding dedicated logistics operations.
- Hospitality:Hotels, resorts, and tourism operators use commercial vehicles for guest transport, luggage handling, and supply deliveries.
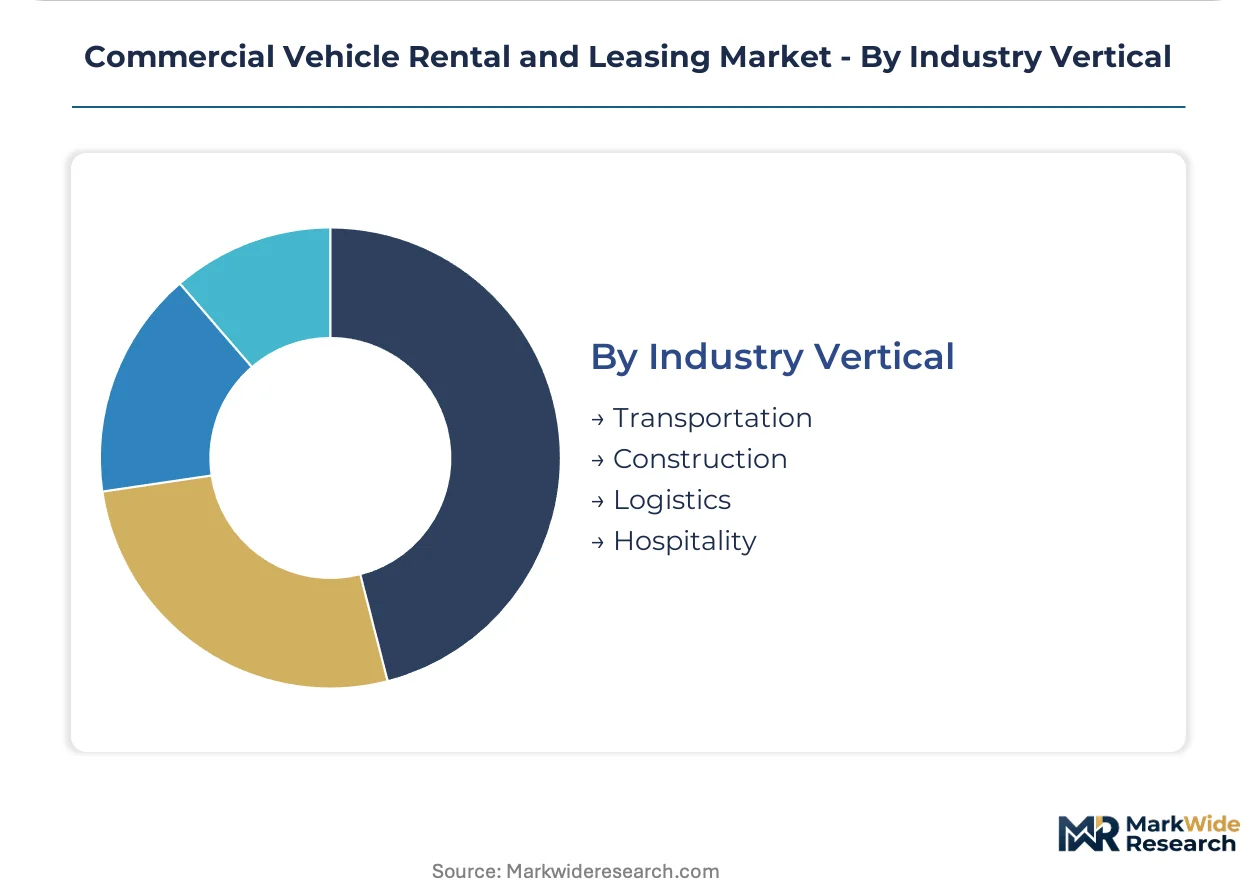
The Logistics sector commands the largest share of commercial vehicle rental and leasing activity, with Construction showing a strong, cyclical expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for last-mile delivery services contrasts with European cities' e-commerce growth, both significantly influencing commercial vehicle rental needs. Regulatory frameworks in each region further shape fleet investment and operational strategies. This dynamic environment creates distinct regional market characteristics across the globe.
United States
E-commerce fulfillment and extensive logistics operations drive demand for heavy-duty trucks and light-duty vehicles in the United States. EPA emission standards compel rental companies to continuously update their fleets with compliant, modern vehicles. Major logistics hubs in states like California and Texas experience concentrated activity for both short-term and full-service leases.
Germany
The logistics sector and the EU Green Deal's emission targets accelerate fleet modernization and demand for cleaner vehicles in Germany. The country's robust manufacturing base supports a strong market for specialized commercial vehicles. Cities like Munich and Hamburg see significant activity from corporates seeking full-service leasing to manage compliance and operational efficiency.
China
E-commerce expansion and urban logistics growth fuel requirements for commercial vehicles across China. MIIT mandates on vehicle telematics and safety directly influence technology adoption within rental fleets. Developing logistics hubs in the Yangtze River Delta and Pearl River Delta regions show increasing demand for modern, compliant assets.
United Kingdom
Urban logistics and seasonal demand spikes, particularly from SMEs in construction, drive short-term rental activity in the United Kingdom. Regulations like the EU's F-Gas Regulation for refrigerated transport influence specialized vehicle availability. Major metropolitan areas like London and Birmingham exhibit consistent demand for flexible fleet solutions.
India
Developing logistics hubs and capital constraints for local businesses create a strong opportunity for commercial vehicle rental and leasing in India. Government initiatives supporting infrastructure development indirectly boost demand for construction and transport vehicles. Major cities such as Mumbai and Delhi are experiencing significant growth in commercial vehicle utilization.
Commercial Vehicle Rental and Leasing Market Key Industry Players
United States producers anchor one tier; European specialists hold another, creating a tiered market structure for commercial vehicle rental and leasing. This landscape features large, full-service providers alongside agile, short-term rental specialists. Strategic archetypes include integrated solution providers, flexible capacity facilitators, and regional niche players. Geographic expansion and portfolio diversification represent common competitive moves.
Within the full-service leasing segment, Ryder System and Penske Truck Leasing exemplify providers offering extensive integrated supply chain solutions and comprehensive maintenance packages for North American clients. Sixt SE, conversely, represents a European-based specialist known for flexible short-term rental options across a wide range of vehicle classes. These companies occupy distinct positions, catering to varied customer needs from long-term operational efficiency to dynamic, on-demand fleet access.
| Leading Market Players |
|---|
| Sixt SE |
| Europcar |
| Enterprise Holdings |
| Hertz Global Holdings |
| ALD Automotive |
| Ryder System |
| LeasePlan Corporation |
| Avis Budget Group |
| Penske Truck Leasing |
| Others |
Cost & Logistics Intelligence
Electric vehicle adoption is reshaping fleet cost economics and concentrating supply chain dependencies for commercial vehicle rental and leasing. This transition necessitates higher capital investment and specialized maintenance capabilities.
Pricing Analysis
Capacity additions in North America are reshaping price floors for commercial vehicle leasing. Contract-based full-service leases dominate, with pricing differentiated by comprehensive maintenance packages and regulatory compliance support. Pricing pressure stems from the high capital cost of fleet modernization, particularly for electric vehicles. SMEs demonstrate higher price sensitivity compared to corporates, who prioritize uptime and integrated solutions.
Supply Chain Analysis
Certification requirements for advanced vehicle technologies gate the commercial vehicle supply chain. Vehicle manufacturing concentrates in Germany, the United States, and China, drawing from global semiconductor and battery cell dependencies. Single-source vulnerability for critical components poses a structural risk. Distribution centers on direct fleets operated by major leasing companies and specialized dealership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
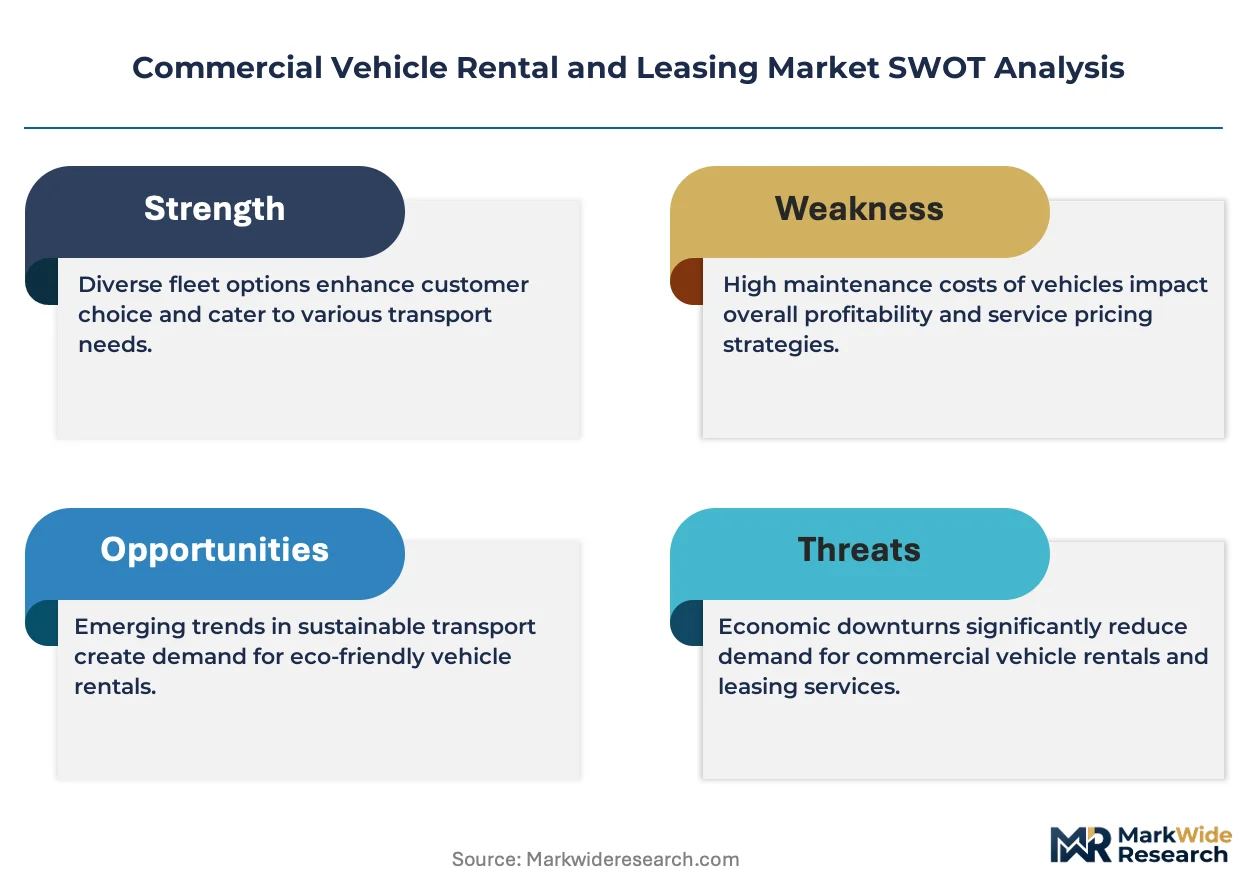
The commercial vehicle rental and leasing market presents a compelling margin-expansion story. Integration of telematics and predictive maintenance services creates new premium tiers, enhancing operational efficiency for clients.
For Market Incumbents: Cement market leadership by diversifying fleets with specialized vehicles and investing in advanced telematics platforms. This mitigates the threat of residual value uncertainty for electric vehicles. Prioritize R&D in predictive maintenance analytics to enhance service offerings. Channel control through integrated supply chain solutions ensures client retention.
For New Entrants and Emerging Players: Capture market share by targeting specialized vehicle segments, such as cold chain logistics, in underpenetrated geographies like Southeast Asia. SMEs requiring last-mile delivery solutions represent a highly penetrable segment. Offer flexible, pay-per-mile contract models to appeal to businesses seeking dynamic scaling options. Develop localized service networks to support rapid expansion.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists because of fragmented operational footprints and varied local regulatory landscapes. The market demonstrates long-term viability fueled by sustained logistics demand and regulatory tailwinds for fleet modernization. Target agile, technology-driven rental providers with strong customer loyalty in specific vehicle segments. The signal to watch is the acceleration of heavy-duty EV charging infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Investment | Rental providers must update fleets to meet EU Green Deal emission targets and reduce long-term operational costs. |
| Telematics Integration | Integrating advanced telematics platforms enhances fleet efficiency and offers new revenue streams through data services. |
| Specialized Vehicle Expansion | Offering cold chain vehicles addresses critical demand from pharmaceutical and food logistics sectors. |
| Flexible Contract Development | Developing pay-per-mile and on-demand options attracts SMEs needing dynamic fleet scaling for last-mile delivery. |
| Emerging Market Entry | Penetrating developing logistics hubs in India provides access to new customer bases with capital constraints. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Interviews engaged fleet managers, logistics directors, rental company executives, and regulatory compliance officers. Secondary data sources included EPA reports, EU F-Gas Regulation documents, MIIT mandates, and industry association publications. This approach ensured robust bottom-up and top-down triangulation for market sizing.
Segment-weighting informed the analytical framework, modeling market dynamics across the forecast period. Segmentation dimensions included vehicle type, service type, customer segment, industry vertical, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data trends and projected future demand. Key forecast inputs included e-commerce growth rates and global emission reduction compliance deadlines.
Underlying measurement precision varies by segment; heavy-duty trucks and full-service leases carry tighter precision than others. Forecasts reflect assumptions regarding regulatory stability and economic conditions. Geopolitical instability or significant raw material price volatility could impact projections. A model refresh is warranted upon material change in fleet electrification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
France Auto Loan Market