
 3D Secure Payment Authentication Market | 2026-2036
3D Secure Payment Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
3D Secure Payment Authentication Market Intelligence
Modular authentication bundling is broadening buyer choice as payment service providers unbundle 3D Secure components from full-stack acquiring packages. Visa Inc. leverages its network tokenization infrastructure to anchor 3D Secure 2.0 deployment across major card-issuing banks. Mastercard Incorporated differentiates through its Identity Check platform, which competes on biometric integration and risk-based authentication pathways. Netcetera specializes in white-label 3D Secure server software, sustaining its position through deep European bank relationships.
3D Secure Payment Authentication denotes a protocol layer that verifies card-not-present transactions through multi-factor challenge-response mechanisms, typically embedding risk scoring engines that analyze device fingerprinting, behavioral biometrics, and transaction velocity before prompting cardholder verification. The protocol's primary commercial purpose is liability shift protection for merchants and issuers while reducing fraudulent authorization rates in remote payment channels. Credit card authentication occupies the largest transaction volume pool, though digital wallet integration represents the fastest-growing payment method as wallet providers embed native 3D Secure flows. Mobile app authentication leads the authentication type hierarchy, displacing SMS OTP in markets where smartphone penetration supports push-notification verification.
The European Banking Authority enforces PSD2 Strong Customer Authentication requirements that mandate two-factor verification for electronic payments, directly expanding 3D Secure deployment scope across EU card issuers. India's Reserve Bank India guidelines on card-not-present security and the US Federal Reserve's oversight of payment system risk collectively shape product standards and market access thresholds for authentication vendors. Stakeholders must monitor how central bank digital currency pilots and real-time payment network expansions alter the authentication stack architecture.
Market Dynamics
Frictionless authentication flows are compressing checkout abandonment rates as merchants prioritize sub-2-second challenge completion over traditional step-up verification intensity. This pressure is fragmenting legacy bundled authentication stacks into discrete, API-callable components.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European Banking Authority mandate requires two-factor verification for electronic payments, compelling EU card issuers to deploy 3D Secure 2.0 infrastructure across their authorization stacks.
- Behavioral biometrics:Keystroke dynamics and touchscreen gesture analysis reduce false-positive challenge rates, cutting merchant friction costs while maintaining liability shift protections.
- Germany:The country's dense network of savings banks and cooperative issuers drives concentrated demand for white-label 3D Secure server deployments with localized risk-scoring configurations.
Market Restraints
- Issuer-side concentration:Authentication vendor revenue depends on a narrow base of tier-1 card-issuing banks in the United States, the United Kingdom, and Germany, creating account concentration risk.
- SMS OTP cost volatility:Messaging termination fees in emerging markets fluctuate with carrier consolidation, squeezing margins for authentication providers relying on SMS fallback channels.
- Native app authentication:Digital wallets embedding proprietary verification flows bypass traditional 3D Secure rails, threatening protocol relevance in mobile-first transaction volumes.
Strategic Opportunities
- India:Reserve Bank of India guidelines on card-not-present security create regulatory pull for 3D Secure deployment among domestic issuers still migrating from static password verification.
- Real-time payment convergence:Integration of 3D Secure risk engines into instant payment schemes like FedNow and SEPA Instant Credit Transfer opens authentication-as-a-service revenue streams.
- Device binding with FIDO2:Cryptographic device attestation standards enable passwordless checkout flows that satisfy PSD2 SCA requirements while eliminating SMS dependency.
Industry Challenges
- Legacy core banking integration:Mainframe-based authorization systems at established issuers require expensive middleware development to support 3D Secure 2.0's JSON messaging protocols.
- Certification timeline compression:EMVCo and scheme-specific testing cycles for new authentication server deployments extend 9-14 months, delaying revenue recognition for vendor implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Secure Payment Authentication Market |
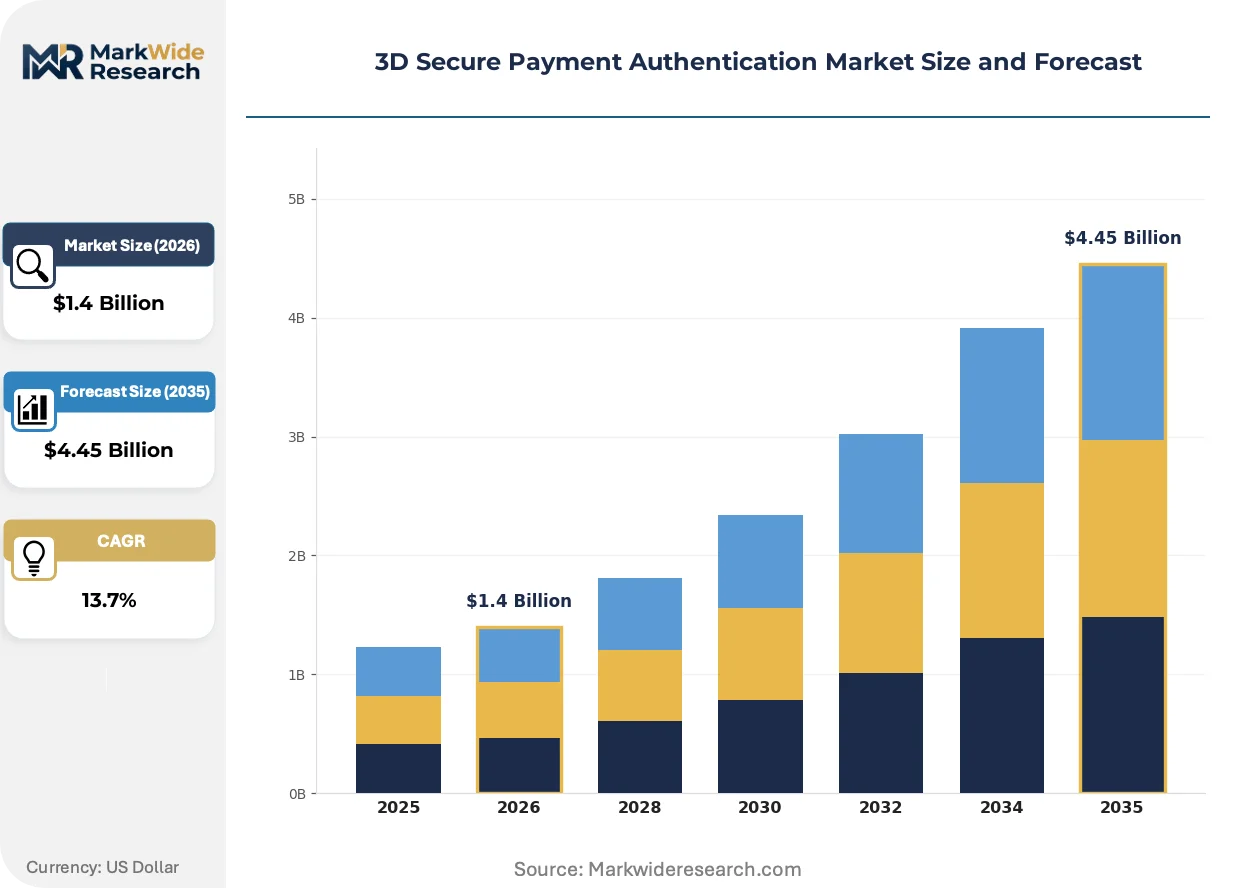
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer End User: Online Retailers, Payment Service Providers, Banks, E-commerce Platforms Authentication Type: SMS OTP, Mobile App Authentication, Biometric Verification, Email Verification Application: E-commerce Transactions, Subscription Services, Online Banking, Retail Checkout |
| Companies Covered | GPayments Pty Ltd., Modirum, Visa Inc., Bluefin Payment Systems LLC, Netcetera, Mastercard Incorporated, Broadcom Inc., DECTA Limited, American Express Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Secure Payment Authentication Market Strategic Shifts & Innovations
Authentication infrastructure is unbundling from monolithic payment platforms into discrete, composable services. This decomposition enables merchants to swap risk-scoring engines, challenge methods, and data sources without replacing entire technology stacks.
3D Secure server software is modularizing into separate access control, authentication, and challenge-handling components. Payment service providers unbundle these elements from full-stack acquiring packages, allowing merchants to select best-of-breed risk engines from specialized vendors. This decomposition compresses vendor lock-in and accelerates procurement cycles for authentication upgrades.
The European Banking Authority's PSD2 Strong Customer Authentication mandate reshapes issuer technology roadmaps across EU member states. The regulation's two-factor requirement forces banks to retire static password verification in favor of dynamic authentication methods. Card issuers in France and Spain accelerate 3D Secure 2.0 migration to meet compliance deadlines while minimizing checkout friction.
Merchant procurement of authentication services fragments from bundled acquiring relationships toward direct vendor contracts. Large e-commerce platforms negotiate standalone 3D Secure server agreements to retain control over risk-scoring data and challenge user experience. This pattern concentrates in the United States and the United Kingdom where merchant technical sophistication supports direct API integration.
3D Secure Payment Authentication Market Segmentation
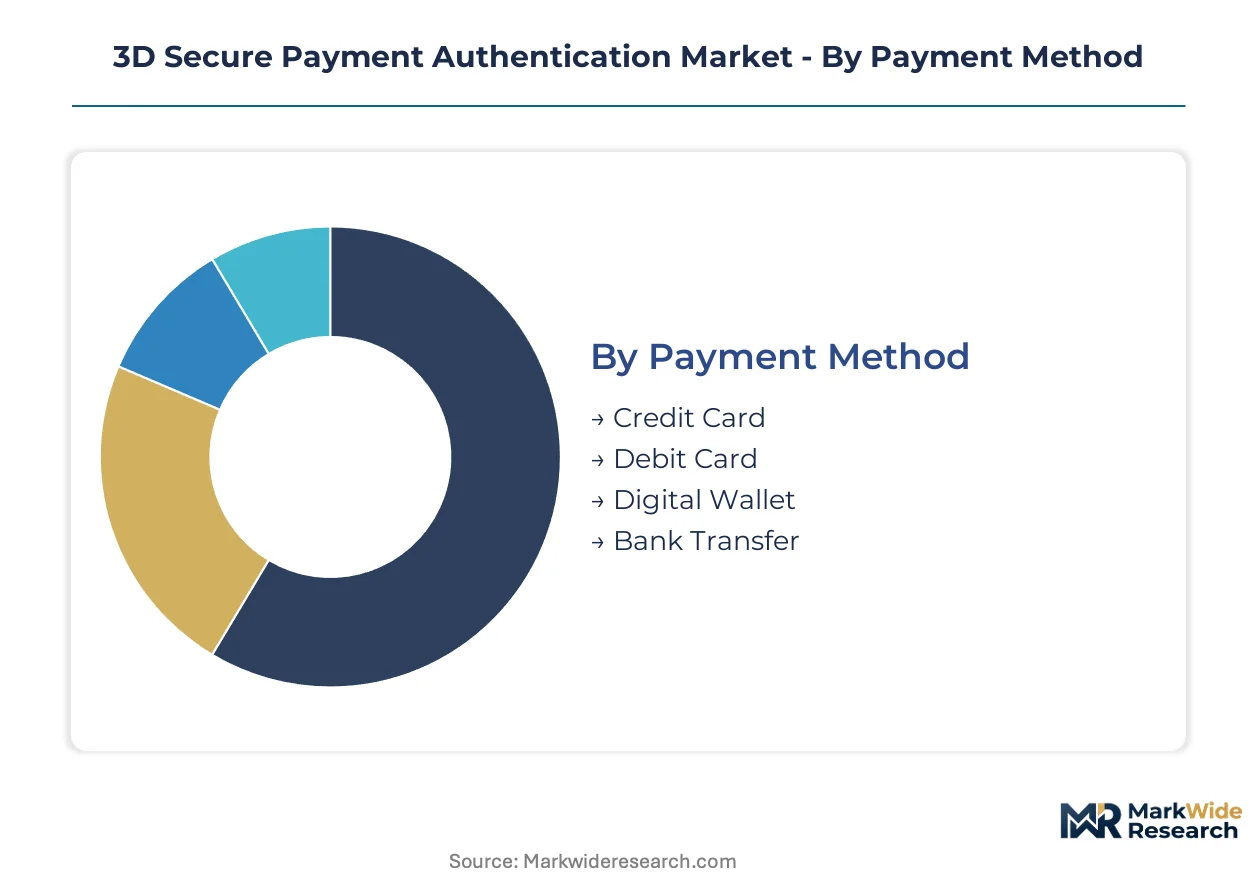
3D Secure Payment Authentication Market segmentation reveals how capital deployment and technical complexity vary across protocol implementations. Issuers and merchants allocate infrastructure spending differently depending on transaction velocity, regulatory exposure, and fraud liability profiles.
Payment Method:
Credit card networks demand the heaviest upfront investment in issuer authentication servers and scheme certification cycles.
- Credit Card:Dominates transaction volume through Visa and Mastercard rails, requiring issuers to maintain dedicated 3D Secure Access Control Servers with EMVCo-certified risk engines. United States card-issuing banks concentrate procurement here due to chargeback liability exposure.
- Digital Wallet:Expanding most quickly as Apple Pay and Google Pay embed native 3D Secure flows, reducing merchant friction while preserving liability shift. Germany's savings bank sector drives white-label server demand for wallet-integrated authentication.
- Debit Card:Lower average transaction values constrain per-transaction authentication economics, pushing issuers toward shared utility models.
- Bank Transfer:SEPA Instant Credit Transfer convergence creates authentication-as-a-service opportunities with lighter scheme certification burdens.
Most installed capacity flows through Credit Card. Expansion is steepest in Digital Wallet.
End User:
Merchant technical sophistication determines whether authentication is procured standalone or bundled within acquiring relationships.
- E-commerce Platforms:Amazon-scale operators negotiate direct 3D Secure server contracts to control risk-scoring data and challenge UX, absorbing higher integration costs for conversion optimization. United Kingdom marketplaces lead this procurement pattern.
- Banks:Tier-1 issuers in the United States deploy in-house authentication stacks with behavioral biometric layers, while smaller institutions rely on hosted 3D Secure services to avoid core banking middleware expenses.
- Payment Service Providers:Stripe and Adyen-type platforms unbundle authentication from acquiring to offer modular risk-engine selection.
- Online Retailers:Mid-market merchants typically accept bundled authentication through their payment gateway, sacrificing customization for faster deployment.
E-commerce Platforms command the deepest technical integration budgets. Banks represent the largest absolute spending pool.
Authentication Type:
Channel costs and device penetration shape how issuers allocate between synchronous and asynchronous verification methods.
- Mobile App Authentication:Push-notification verification displaces SMS in markets with high smartphone penetration, eliminating carrier termination fee volatility. United States issuers prioritize this channel for sub-2-second challenge completion.
- Biometric Verification:Fingerprint and facial recognition satisfy PSD2 SCA requirements while removing password friction, driving German bank adoption for mobile-first transaction volumes.
- SMS OTP:Remains prevalent in emerging markets where smartphone penetration lags, though messaging cost fluctuations squeeze provider margins.
- Email Verification:Limited to low-value transactions and account recovery flows due to latency and deliverability risks.
Mobile App Authentication captures the steepest share gains. SMS OTP retains the widest geographic footprint.
Application:
Transaction pattern predictability determines whether risk engines apply behavioral models or default to step-up verification.
- E-commerce Transactions:One-off purchases with variable merchant profiles generate the highest false-positive challenge rates, demanding sophisticated device fingerprinting and velocity checks. United Kingdom fashion and electronics merchants invest heavily here.
- Subscription Services:Recurring billing with stored credentials enables frictionless authentication pathways, reducing churn for SaaS and streaming providers. United States subscription economy drives merchant-specific 3D Secure optimization.
- Online Banking:Account access authentication sits outside card scheme rails, though 3D Secure risk engines increasingly cross-pollinate into banking login flows.
- Retail Checkout:Buy-online-pickup-in-store and curbside models blend card-not-present authentication with physical fulfillment verification.
E-commerce Transactions absorb the most authentication R&D spending. Subscription Services deliver the highest approval rate optimization returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
3D Secure authentication infrastructure first achieved commercial scale across European card-issuing banks responding to early liability shift mandates from Visa and Mastercard in the late 1990s. This foundational deployment pattern established technical standards and certification protocols that subsequently diffused to North American and Asia-Pacific markets. Today, regulatory enforcement intensity and digital payment volume concentration determine regional investment priorities.
United States
Chargeback liability exposure drives tier-1 card-issuing banks to maintain dedicated Access Control Servers with EMVCo-certified risk engines. The Federal Reserve's oversight of payment system risk shapes vendor qualification standards. New York and San Francisco host the densest clusters of merchant technical teams negotiating direct 3D Secure server contracts for conversion optimization.
Germany
Savings banks and cooperative issuers generate concentrated demand for white-label server deployments with localized risk-scoring configurations. BaFin enforcement of PSD2 Strong Customer Authentication compels migration from static password verification. Frankfurt and Munich anchor the vendor relationship networks serving this fragmented banking structure.
United Kingdom
E-commerce platforms at scale prioritize standalone authentication procurement to retain control over risk-scoring data and challenge user experience. The Financial Conduct Authority's PSD2 implementation timeline accelerated issuer infrastructure replacement cycles. London's fintech concentration supports merchant-direct API integration capabilities unmatched elsewhere in Europe.
India
Domestic issuers migrate from static password verification toward dynamic authentication methods under Reserve Bank of India card-not-present security guidelines. Mumbai and Bangalore concentrate vendor implementation teams serving public-sector banks with legacy core banking constraints. Smartphone penetration growth enables push-notification verification displacement of SMS OTP cost structures.
France
Card issuers accelerate 3D Secure 2.0 migration to meet PSD2 compliance deadlines while minimizing checkout friction for merchant acquirers. The Autorité de Contrôle Prudentiel et de Résolution monitors authentication adequacy across retail banking networks. Paris anchors scheme certification relationships and EMVCo testing facility access for domestic vendors.
3D Secure Payment Authentication Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and scheme relationship intensity. Network operators with tokenization infrastructure command pricing power over standalone software vendors. Three archetypes dominate: scheme-affiliated platform providers, white-label server specialists, and payment service providers unbundling authentication from acquiring. Consolidation pressure manifests through strategic partnerships between risk-engine specialists and core banking middleware vendors, plus geographic expansion by European specialists into Asia-Pacific regulatory jurisdictions.
Within the scheme-affiliated tier, Visa Inc. and Mastercard Incorporated anchor competitive positioning through network tokenization integration and Identity Check platform deployment. Netcetera exemplifies the white-label specialist archetype with European bank relationship depth. Modirum occupies a position bridging hosted service delivery and issuer-specific customization for mid-tier financial institutions.
| Leading Market Players |
|---|
| GPayments Pty Ltd. |
| Modirum |
| Visa Inc. |
| Bluefin Payment Systems LLC |
| Netcetera |
| Mastercard Incorporated |
| Broadcom Inc. |
| DECTA Limited |
| American Express Company |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up authentication specialists anchor supply discipline through centralized procurement of EMVCo certification services, compressing vendor margins while sustaining premium pricing for scheme-affiliated platform tiers. This ownership pattern concentrates pricing power among three dominant network operators who leverage tokenization infrastructure to bundle authentication with interchange revenue streams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies authentication vendors by certification depth and scheme relationship intensity. Premium tiers command sustained margins through EMVCo-certified risk engines and direct issuer relationships, while economy tiers face compression from open-source 3D Secure server alternatives. Price differentiation rests on behavioral biometric integration depth and geographic localization capabilities. Mid-market payment service providers exhibit acute price sensitivity, whereas tier-1 issuers prioritize liability shift reliability over per-transaction cost. Cost compression in standard-tier SaaS offerings is intensifying because merchant procurement teams now benchmark authentication costs against bundled gateway fees.
Supply Chain Analysis
Returns and refurbishment flows for authentication server hardware remain minimal given software-dominant delivery models, though white-label specialists maintain legacy middleware upgrade services for mainframe-dependent issuers. Software development concentrates in the United States, Germany, and India, with certification testing anchored in France and the United Kingdom. Component dependencies include cryptographic libraries from open-source repositories, cloud compute capacity from hyperscalers, and carrier messaging termination for SMS fallback channels. Single-source vulnerability concentrates in EMVCo certification facility access, where queue bottlenecks delay vendor revenue recognition. Distribution runs through direct enterprise sales for tier-1 issuers and channel partnerships with payment service providers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate between European regulatory enforcement and Indian implementation lag, where identical authentication technology commands divergent pricing power based on compliance timeline differentials.
For Market Incumbents: Deepen scheme certification moats by accelerating EMVCo 2.0 server accreditation ahead of compliance deadlines, insulating against open-source displacement. Consolidate risk-engine specialists through targeted acquisition of behavioral biometric vendors to capture merchant demand for frictionless flows. Native app authentication bypass by digital wallets represents the most credible substitution threat; vertical integration into push-notification infrastructure neutralizes carrier cost volatility. For New Entrants and Emerging Players: PSD2 Strong Customer Authentication in France and Spain opens a window for hosted 3D Secure services targeting cooperative issuers lacking core banking modernization budgets. White-label server deployment for Germany's savings bank sector offers the most penetrable entry point given fragmented procurement authority. Go-to-market execution should anchor in API-first integration patterns that bypass legacy middleware dependencies. For Investors and Strategic Acquirers: Valuations sit cheapest among white-label server specialists with deep European bank relationships but limited geographic diversification. Long-term viability across the analysis window hinges on authentication-as-a-service revenue from real-time payment scheme convergence. Acquisition targets should exhibit device-binding capabilities with FIDO2 standards. The signal to watch is central bank digital currency pilot announcements, which would recalibrate authentication stack architecture requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo 2.0 Certification Acceleration | Visa and Mastercard scheme relationships determine issuer procurement priority and pricing tier access. |
| Behavioral Biometric Integration | Keystroke dynamics and gesture analysis reduce merchant friction costs while preserving PSD2 SCA compliance. |
| Real-Time Payment Scheme Convergence | FedNow and SEPA Instant Credit Transfer integration opens authentication-as-a-service revenue streams beyond card rails. |
| Device Binding with FIDO2 Standards | Cryptographic attestation enables passwordless checkout flows that eliminate SMS OTP cost dependencies. |
| Geographic Expansion into India | RBI card-not-present security guidelines create regulatory pull for 3D Secure deployment among domestic issuers. |
Research Approach
Multiple input streams — executive interviews with authentication vendor leadership, issuer technology procurement officers, and payment scheme product managers — were reconciled against EMVCo certification databases, SEC filings from publicly traded network operators, and regulatory guidance from the European Banking Authority and Reserve Bank of India. Secondary validation drew from hyperscaler authentication service disclosures, merchant gateway integration documentation, and trade data on SMS termination pricing. Bottom-up transaction volume estimates triangulated with top-down authentication infrastructure spending projections.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions to payment method, authentication type, and end-user dimensions. Modeled variables included digital wallet penetration curves, PSD2 compliance timeline enforcement variance, and smartphone displacement of SMS OTP channels. CAGRs were derived from logistic adoption curves fitted to issuer migration patterns and merchant friction-cost sensitivity thresholds. Industry-specific forecast inputs incorporated EMVCo certification queue duration and carrier messaging cost volatility in emerging markets.
Revisions become necessary when central bank digital currency pilots alter authentication stack requirements or when real-time payment scheme adoption accelerates beyond card-not-present displacement assumptions. Practitioners should monitor FedNow transaction volume growth and SEPA Instant Credit Transfer authentication integration announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mobile Payment Transaction Market
Payments
Ireland POS Terminals Market
Payments
Mexico POS Terminals Market
Payments
Global Wearable Payment Device Market
Payments
Cash Management Software Market
Payments
Canada Gift Card and Incentive Card Market
Payments
Buy Now Pay Later Market
Payments
India RTP Market
Payments
China Mobile Payments Market
Payments
Norway Payments Market
Payments
US Buy Now Pay Later Services Market
Payments
Asia-Pacific Payments Market
Payments
Italy Payments Market
Payments
United States Clearing Houses and Settlements Market
Payments
Japan POS Terminals Market
Payments
Global Real-Time Payments Market