
 Saudi Arabia Payment Gateway Market | 2026-2036
Saudi Arabia Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Payment Gateway Market Insights
Merchant onboarding strategy is shifting from single-source acquirer relationships toward multi-gateway orchestration across the Saudi digital economy. PayTabs leverages localized Arabic-language checkout interfaces to sustain merchant retention in domestic e-commerce. HyperPay anchors enterprise-grade API infrastructure for large retail chains requiring real-time transaction processing. Checkout.com competes through direct acquiring licenses that bypass intermediary routing fees for high-volume merchants.
A payment gateway is a technology layer that encrypts, routes, and authorizes financial transactions between merchants, acquirers, and card networks using tokenization protocols and TLS 1.3 encryption standards. Its primary commercial purpose is to reduce fraud exposure while enabling real-time settlement across omnichannel sales environments. Mobile service type leads transaction volume growth as smartphone penetration drives in-app and QR-code payments ahead of legacy POS terminal flows. E-wallet payment method captures expanding share as STC Pay and similar licensed providers integrate directly with merchant checkout flows, displacing traditional card-not-present dominance. API integration level attracts mid-market SaaS platforms seeking embedded finance capabilities without hosted-page redirects.
SAMA's Payment Services Provider Regulations and the Saudi Central Bank's open banking framework mandate licensed operational resilience standards that shape gateway infrastructure investment requirements. Anti-money laundering protocols enforced through SAMA's Financial Intelligence Unit impose real-time transaction monitoring obligations that filter market access for unlicensed foreign operators. Stakeholders must monitor SAMA's evolving stablecoin and central bank digital currency roadmap, as settlement-layer changes would recalibrate gateway economics and technical interoperability requirements across the kingdom's payment ecosystem.
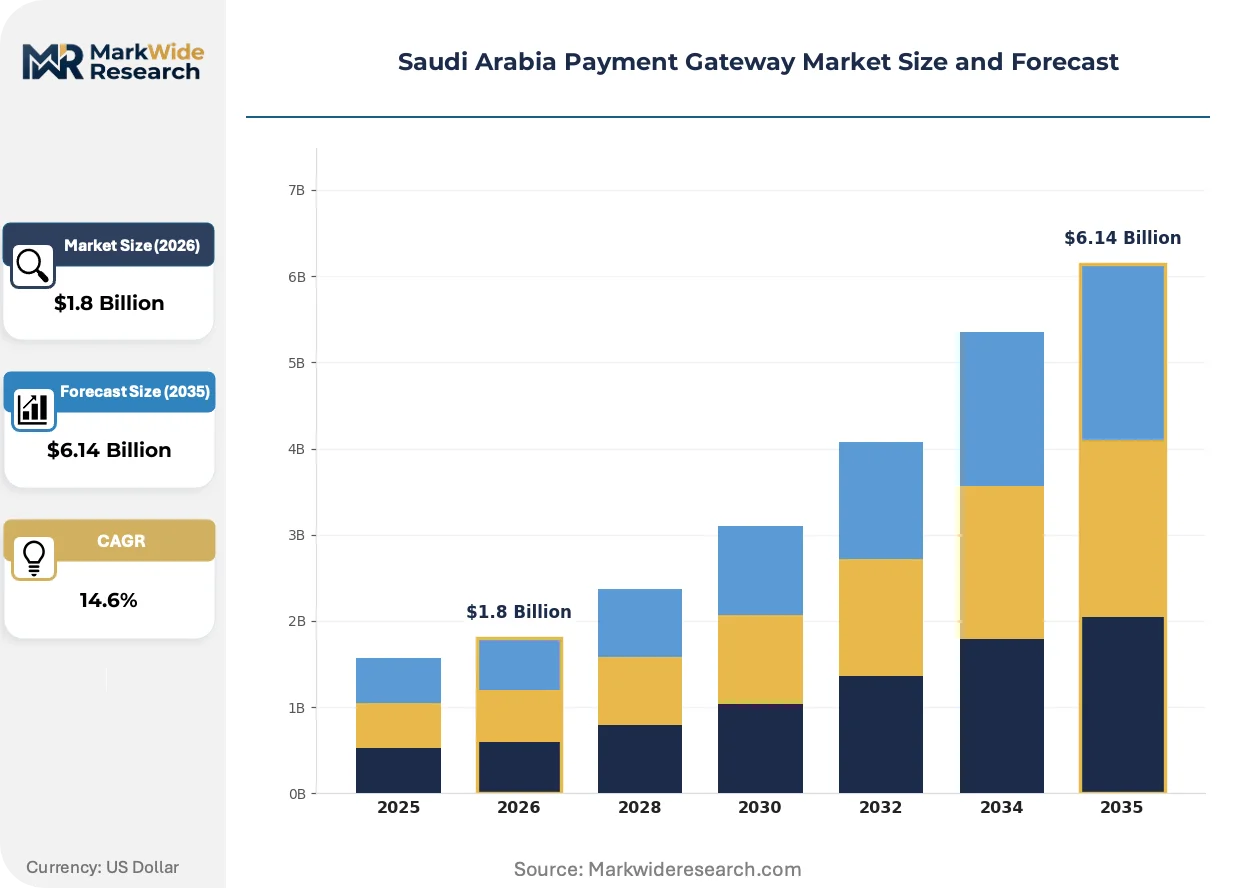
Market Dynamics
SAMA's Payment Services Provider Regulations are compressing market access timelines while mandating operational resilience investments that reshape gateway infrastructure economics across the kingdom.
Growth Catalysts
- SAMA Licensing Framework:The Saudi Central Bank's tiered authorization structure accelerates fintech entry while enforcing capital adequacy standards that build merchant trust in licensed operators.
- E-commerce Merchant Surge:Domestic online retail transaction volumes are pulling multi-gateway orchestration demand as merchants abandon single-acquirer dependencies for redundancy.
- STC Pay Integration:E-wallet infrastructure is embedding directly into checkout flows, displacing card-not-present dominance and creating new routing revenue pools for gateway intermediaries.
Market Restraints
- Capital Reserves Mandate:SAMA's minimum paid-up capital requirements for Payment Service Providers create a structural barrier for unlicensed foreign entrants seeking direct market access.
- Technical Debt Burden:Legacy POS terminal estates at major retail chains constrain API-first gateway migration timelines and inflate parallel-system maintenance costs.
- Concentrated Acquirer Control:The domestic banking oligopoly's grip on settlement infrastructure limits gateway pricing autonomy and compresses margin pools for independent operators.
Strategic Opportunities
- Eastern Province Expansion:Dammam's logistics corridor and industrial zones remain underpenetrated by localized Arabic-language checkout solutions relative to Riyadh saturation.
- Open Banking Convergence:SAMA's account information service framework enables gateway operators to unify card and account-to-account rails within single API architectures.
- Embedded Finance SaaS:Mid-market software platforms in the kingdom are seeking white-label payment infrastructure without hosted-page redirects, creating vertical-specific gateway demand.
Industry Challenges
- Certification Bottlenecks:PCI-DSS Level 1 compliance timelines for new entrants stretch operational launch windows while SAMA parallel licensing runs.
- Legacy System Integration:Enterprise ERP suites at major retail chains require custom middleware development that inflates gateway deployment costs and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Payment Gateway Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online, Mobile, POS, Subscription Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer End User: E-Commerce, Retail, Hospitality, Healthcare Integration Level: API, SDK, Hosted, White Label |
| Companies Covered | PayTabs, HyperPay, Moyasar, Tap, Amazon Payment Services, Checkout.com, Network International, BayanPay, STC Pay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Payment Gateway Market Trends and Innovations
Tokenization protocols and real-time settlement architectures are compressing fraud exposure windows while enabling merchant preference shifts toward embedded payment experiences.
Unified commerce platforms are unifying in-app, QR-code, and web checkout flows into single token vault architectures. Mid-market Saudi merchants are adopting these consolidated stacks to reduce PCI scope and simplify reconciliation. This convergence is unifying previously siloed payment data streams into merchant analytics dashboards that drive retention pricing for gateway providers.
SAMA's Financial Intelligence Unit mandates are tightening real-time transaction monitoring obligations across all licensed operators. Gateway infrastructure investments now prioritize behavioral analytics engines that flag anomalous patterns before authorization. Domestic e-commerce merchants bear the heaviest compliance burden as transaction volumes concentrate in high-velocity retail verticals.
Merchant procurement of payment infrastructure is fragmenting across orchestration layers rather than consolidating with single acquirers. SaaS platforms and independent software vendors are inserting themselves as distribution intermediaries, displacing direct bank sales relationships. This channel shift is most visible in Riyadh's technology corridor where fintech clusters aggregate mid-market demand.
Saudi Arabia Payment Gateway Market Segmentation
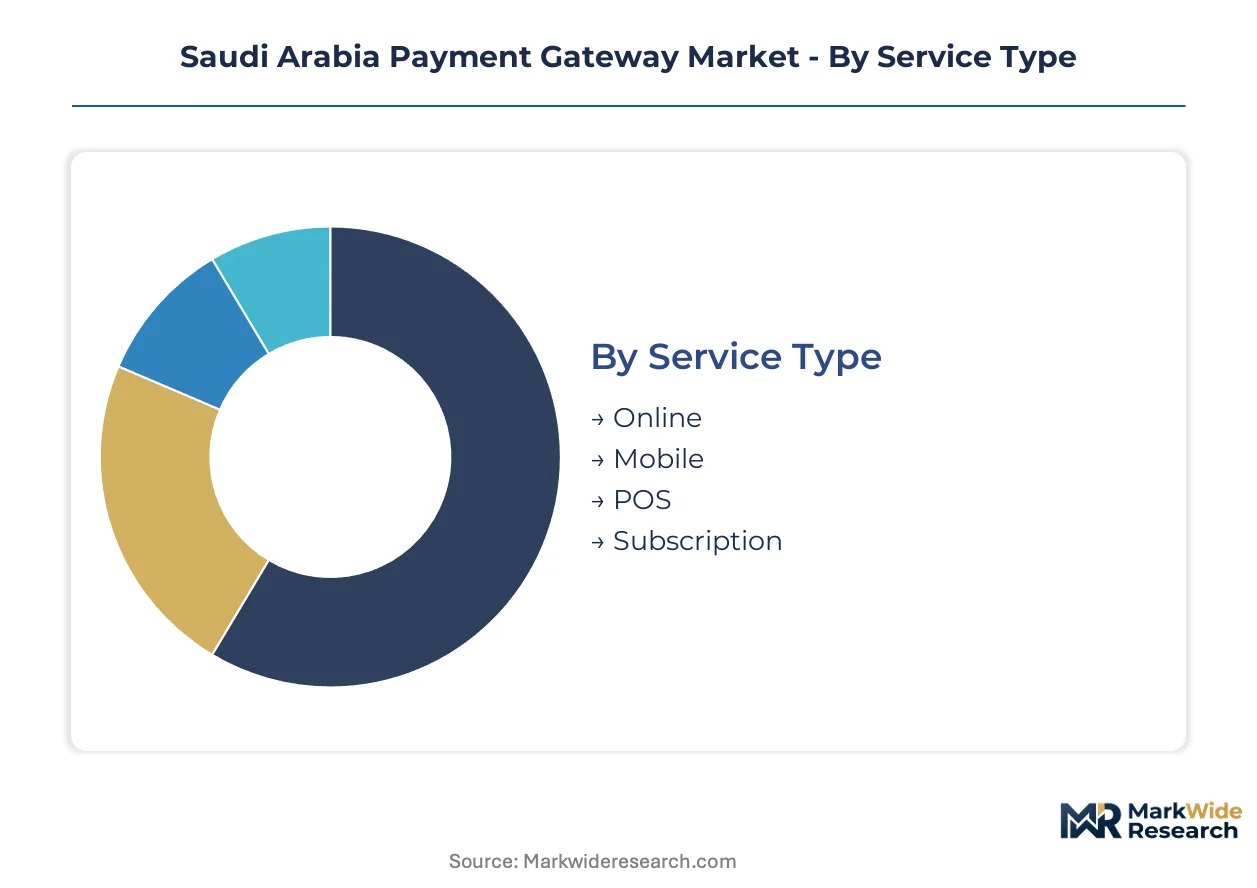
Gateway configuration choices in Saudi Arabia determine settlement speed, fraud exposure, and merchant onboarding friction. SAMA's licensing tiers create divergent infrastructure investment requirements across service categories. Each segmentation axis reveals distinct procurement patterns between enterprise retail chains and emerging SaaS platforms.
Service Type:
Standardization dominates high-volume transaction processing, while customization concentrates in recurring billing and omnichannel orchestration layers.
- Mobile:Smartphone penetration drives in-app and QR-code transaction volumes through tokenized authentication protocols. Riyadh's fintech corridor anchors platform development as STC Pay integration creates new routing revenue pools for gateway intermediaries.
- Online:Browser-based checkout flows leverage TLS 1.3 encryption and 3D Secure 2.0 protocols to reduce card-not-present fraud exposure. Domestic e-commerce merchants in the technology corridor prioritize Arabic-language interfaces that sustain retention against foreign competitors.
- POS:Legacy terminal estates at major retail chains constrain API-first migration timelines and inflate parallel-system maintenance costs.
- Subscription:Recurring payment vaults with credential-on-file tokenization support SaaS and media streaming business models.
Most installed capacity flows through Mobile. Expansion is steepest in Subscription.
Payment Method:
Cost tier stratification separates premium card routing from lower-fee account-to-account alternatives, with wallet infrastructure occupying a mid-tier position.
- E-Wallet:Licensed providers embed directly into merchant checkout flows through SAMA-regulated tokenization protocols. STC Pay and similar operators displace traditional card dominance in Riyadh's enterprise retail segment.
- Credit Card:Visa and Mastercard networks maintain premium interchange economics for high-value transactions despite wallet encroachment. Concentrated acquirer control limits gateway pricing autonomy for independent operators serving hospitality chains.
- Debit Card:Domestic bank-issued instruments carry lower interchange rates that compress margin pools for gateway intermediaries.
- Bank Transfer:Account-to-account rails gain traction in B2B procurement and invoice settlement use cases.
Transaction volume concentrates in Credit Card. E-Wallet gains share fastest.
End User:
Application maturity separates high-velocity retail verticals from compliance-heavy sectors with extended sales cycles and custom middleware requirements.
- E-Commerce:Domestic online retail platforms demand multi-gateway orchestration for redundancy against single-acquirer dependencies. SAMA's Financial Intelligence Unit mandates impose heaviest real-time monitoring burdens as transaction volumes concentrate in high-velocity environments.
- Retail:Enterprise chains require unified commerce stacks that consolidate in-app, QR-code, and web flows into single token vault architectures. Legacy ERP suites at major operators inflate deployment costs through custom middleware development.
- Hospitality:Hotels and restaurants prioritize pre-authorization capabilities and multi-currency settlement for international guest segments.
- Healthcare:HIPAA-aligned data handling and insurance reconciliation workflows create specialized integration requirements.
Merchant procurement concentrates in E-Commerce. Healthcare presents the steepest expansion trajectory.
Integration Level:
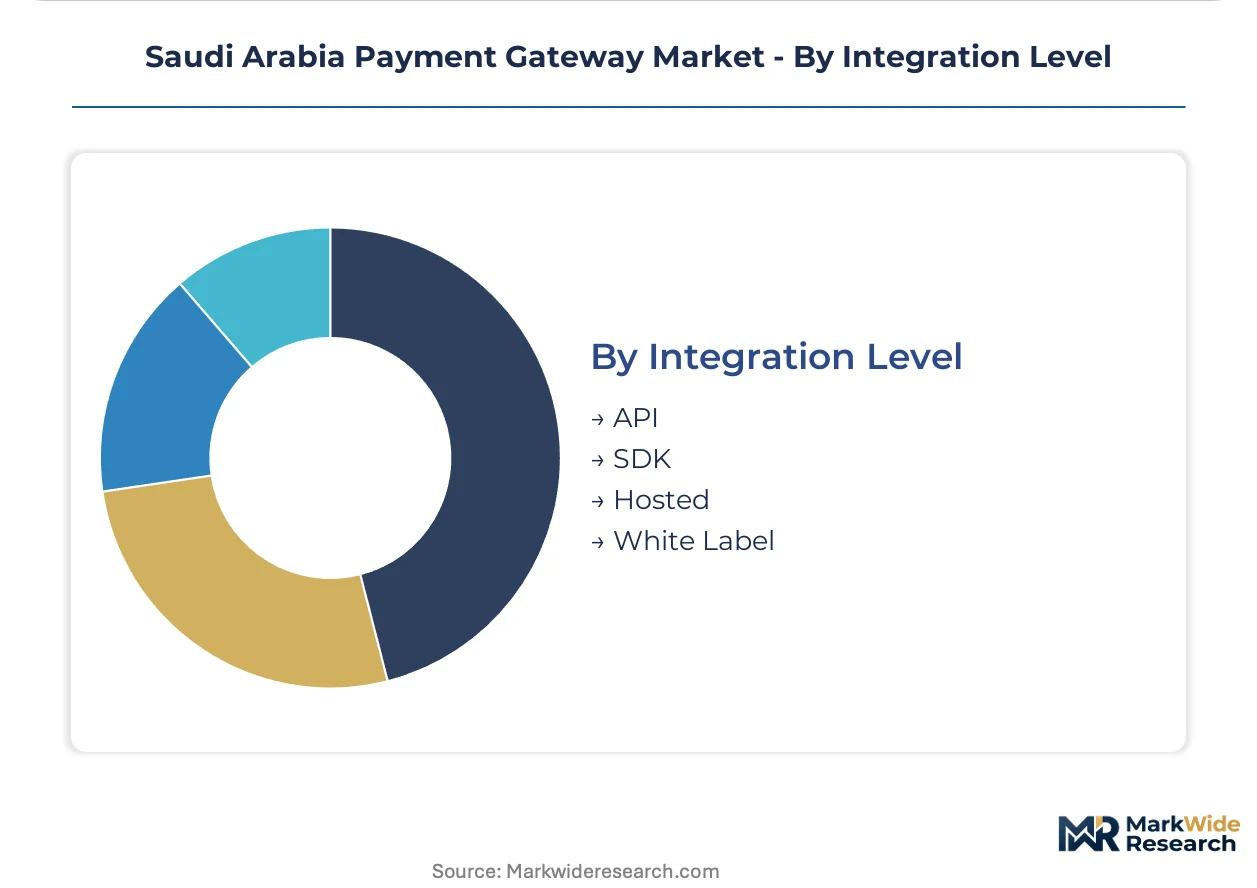
Customer type stratification separates developer-centric embedded finance platforms from merchant-procured turnkey solutions with minimal technical overhead.
- API:Direct server-to-server integration enables real-time transaction processing without hosted-page redirects. Mid-market SaaS platforms in the kingdom seek embedded finance capabilities that unify card and account-to-account rails within single architectures.
- White Label:Branded payment infrastructure allows software vendors to monetize transaction flows without building licensed payment service provider capabilities. Independent software vendors insert themselves as distribution intermediaries, displacing direct bank sales relationships.
- SDK:Pre-built mobile libraries accelerate in-app checkout deployment for merchants without dedicated development resources.
- Hosted:Redirect-based solutions minimize PCI scope for smaller merchants with limited technical capacity.
Developer preference concentrates in API. White Label climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's technology corridor anchors payment gateway deployment density as fintech clusters concentrate enterprise headquarters and mid-market SaaS platforms. SAMA's licensing framework has established the capital as the primary hub for regulated payment service provider operations. Infrastructure investment patterns reveal stark sub-regional disparities across the kingdom's economic geography.
Riyadh
Domestic e-commerce merchants and enterprise retail chains drive multi-gateway orchestration demand in the capital's fintech corridor. SAMA's Financial Intelligence Unit mandates impose concentrated compliance burdens on high-velocity transaction environments. The King Abdullah Financial District hosts the densest cluster of licensed payment service providers competing for merchant acquisition.
Eastern Province
Dammam's logistics corridor and industrial zones generate underpenetrated demand for localized Arabic-language checkout solutions. The Saudi Central Bank's open banking framework enables account-to-account rail integration for B2B procurement use cases. Gateway operators face extended sales cycles addressing legacy ERP suites at petrochemical and manufacturing enterprises.
Western Region
Jeddah's hospitality and pilgrimage economy prioritizes pre-authorization capabilities and multi-currency settlement for international guest segments. SAMA's Payment Services Provider Regulations mandate operational resilience investments that reshape infrastructure economics for Red Sea coastal operators. The city's commercial districts show accelerating STC Pay integration displacing traditional card-not-present dominance.
NEOM Northwest
The giga-project's cashless infrastructure mandates create greenfield deployment opportunities without legacy POS terminal debt burdens. SAMA's evolving central bank digital currency roadmap positions the zone as a testbed for settlement-layer interoperability. Technology partnerships between global gateway providers and project developers are establishing API-first architectures absent elsewhere in the kingdom.
Saudi Arabia Payment Gateway Market Competitive Landscape
Global majors compete with regional champions across licensing velocity and merchant trust dimensions in a structurally tiered market. SAMA's tiered authorization framework has compressed market access timelines while elevating capital requirements that favor scaled operators. Three archetypes dominate: domestic fintechs leveraging Arabic-language localization, global platforms with direct acquiring licenses, and bank-affiliated processors controlling settlement infrastructure. Competitive moves concentrate on strategic partnerships with SaaS distribution intermediaries and vertical-specific API customization.
Among Riyadh-based specialists, PayTabs and HyperPay exemplify the localization-first archetype that sustains merchant retention through culturally adapted checkout experiences. Moyasar occupies a position within the developer-centric tier serving mid-market software platforms seeking embedded finance capabilities. These domestic champions anchor competitive dynamics against global entrants like Checkout.com that compete through direct acquiring licenses bypassing intermediary routing fees.
| Leading Market Players |
|---|
| PayTabs |
| HyperPay |
| Moyasar |
| Tap |
| Amazon Payment Services |
| Checkout.com |
| Network International |
| BayanPay |
| STC Pay |
| Others |
Pricing and Supply Chain Analysis
Multi-gateway orchestration procurement by Saudi e-commerce merchants is compressing single-acquirer pricing premiums and forcing gateway providers to absorb certification and compliance costs without full pass-through capacity.
Pricing Analysis
Input-cost pass-through from PCI-DSS Level 1 certification timelines and SAMA licensing fees sustains a transaction-fee-plus-monthly-SaaS pricing model across the kingdom. Price differentiation separates enterprise-grade API infrastructure with real-time settlement from hosted-page solutions serving smaller merchants. Pricing pressure intensifies as Checkout.com and other direct acquiring license holders bypass intermediary routing fees, compressing margin pools for independent operators. Mid-market SaaS platforms exhibit highest price sensitivity due to embedded finance margin constraints, while enterprise retail chains prioritize uptime guarantees over fee minimization.
Supply Chain Analysis
Gateway infrastructure supply rests on specialized software development concentrated in India, UAE-based data center operations, and European tokenization technology providers. Critical dependencies include TLS 1.3 encryption modules, behavioral analytics engines for fraud detection, and cloud-native API architectures. Single-source vulnerability concentrates in acquirer settlement rails controlled by Saudi Arabia's domestic banking oligopoly. Distribution runs through direct enterprise sales teams in Riyadh's fintech corridor and SaaS platform partnerships displacing traditional bank channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
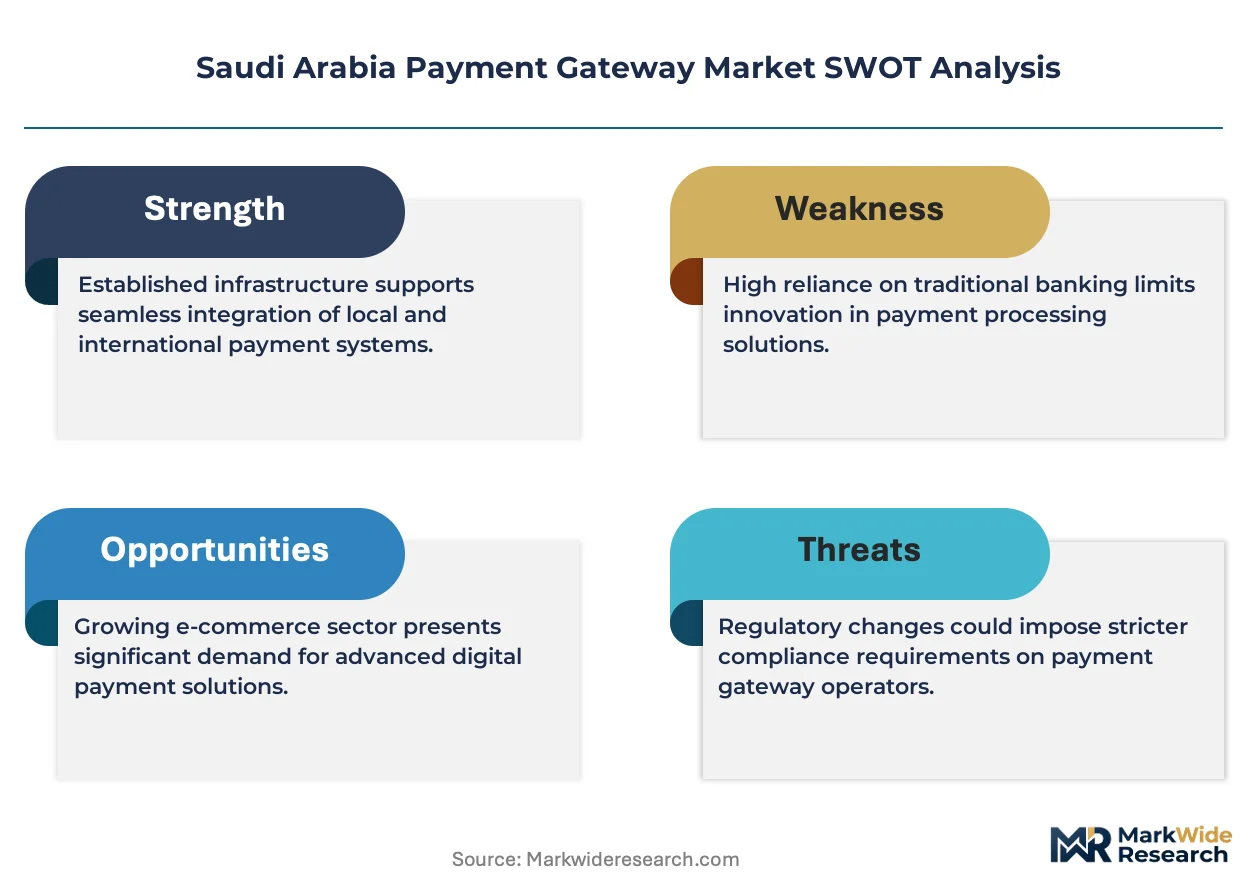
SAMA's open banking framework is expanding premium-tier revenue pools for gateway operators that unify card and account-to-account rails, while API-first architectures reduce per-merchant onboarding costs.
For Market Incumbents: Hedge against direct acquiring license proliferation by deepening Arabic-language localization moats and embedding into vertical-specific SaaS workflows. SAMA's evolving central bank digital currency roadmap threatens settlement-layer displacement. Prioritize certification investments that accelerate PCI-DSS Level 1 compliance velocity relative to new entrants. For New Entrants and Emerging Players: SAMA's Payment Services Provider Regulations in Saudi Arabia open a window for Eastern Province penetration where Dammam's logistics corridor remains underpenetrated by localized checkout solutions. Target petrochemical and manufacturing enterprises with B2B procurement use cases. Pursue white-label partnerships with independent software vendors rather than direct merchant acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with API-first domestic champions possessing SAMA licenses and established STC Pay integration pathways. Five-to-ten-year viability hinges on settlement-layer interoperability as central bank digital currencies mature. Watch SAMA's stablecoin roadmap as the critical inflection signal for gateway economics recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Enables real-time transaction processing without hosted-page redirects for mid-market SaaS platforms. |
| STC Pay Integration Partnership | Captures routing revenue pools as e-wallet infrastructure displaces card-not-present dominance. |
| Eastern Province Geographic Expansion | Addresses underpenetrated demand in Dammam's logistics corridor for Arabic-language checkout solutions. |
| Open Banking Convergence Investment | Unifies card and account-to-account rails within single architectures per SAMA's framework. |
| Behavioral Analytics Engine Deployment | Satisfies SAMA Financial Intelligence Unit mandates for real-time transaction monitoring obligations. |
Research Methodology
Multiple input streams — primary interviews with payment gateway executives, SAMA regulatory affairs specialists, and e-commerce merchant technology officers — were reconciled against secondary sources including SAMA licensing disclosures, Saudi Central Bank open banking framework documents, and PCI Security Standards Council certification records. Bottom-up merchant procurement pattern analysis was cross-validated with top-down infrastructure investment tracking across Riyadh's fintech corridor.
Historical transaction volume trajectories were cross-referenced against panel input from licensed payment service providers to construct segment-specific growth curves across the analysis window. Segmentation dimensions modeled include service type, payment method, end-user vertical, and integration complexity tier. CAGRs were derived from slope analysis of normalized adoption curves, with specific adjustment for SAMA regulatory timeline acceleration and STC Pay integration velocity.
Revisions become necessary when SAMA's central bank digital currency roadmap materializes with concrete settlement-layer specifications, or when open banking framework implementation timelines shift materially. Forecasts reflect assumptions about licensing velocity and merchant onboarding friction coefficients. SAMA stablecoin policy, PCI-DSS certification bottleneck resolution, and domestic banking oligopoly settlement pricing constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
UAE Card Payments Market
Payments
Cyprus POS Terminals Market
Payments
Canada Gift Card and Incentive Card Market
Payments
Europe Accounts Payable Automation Market
Payments
China Prepaid Cards Market
Payments
New Zealand Payments Market
Payments
Germany POS Terminal Market
Payments
Asia Pacific Mobile Wallet Market
Payments
United Kingdom Payment Market
Payments
Europe Payment Analytics Software Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Gift Card and Incentive Card Market
Payments
Finland POS Terminals Market
Payments
Norway Payments Market