
 Global Master Card Market | 2026-2036
Global Master Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global Master Card Market Foresight
Platform licensing revenue is reconfiguring how payment networks capture value beyond transaction interchange. Visa leverages its tokenization infrastructure to anchor premium positioning in cross-border e-commerce. American Express differentiates through closed-loop merchant relationships and travel-centric rewards ecosystems. UnionPay dominates Asia-Pacific corridor volume through its clearing network and government-backed expansion.
A master card functions as a branded payment credential issued by financial institutions, embedding EMV chip technology, magnetic stripe encoding, and near-field communication antennas to authenticate and authorize electronic fund transfers across merchant networks. Its primary commercial purpose is to enable deferred-payment consumer spending and commercial procurement while generating interchange and interest income for issuing banks. Platinum and World Elite card types command the highest margin pools through annual fees and affluent customer segments, while standard cards represent mature, high-volume, low-yield products. Digital wallets as a distribution channel are capturing the fastest growth by decoupling physical card issuance from account funding.
The US Federal Reserve governs interchange fee caps under the Durbin Amendment, while the EU's Interchange Fee Regulation limits cross-border transaction costs for merchants. India's RBI mandates tokenization protocols and data localization for domestic payment processing. Stakeholders must monitor how central bank digital currency pilots in China and India reshape card-linked payment rails and issuer business models.
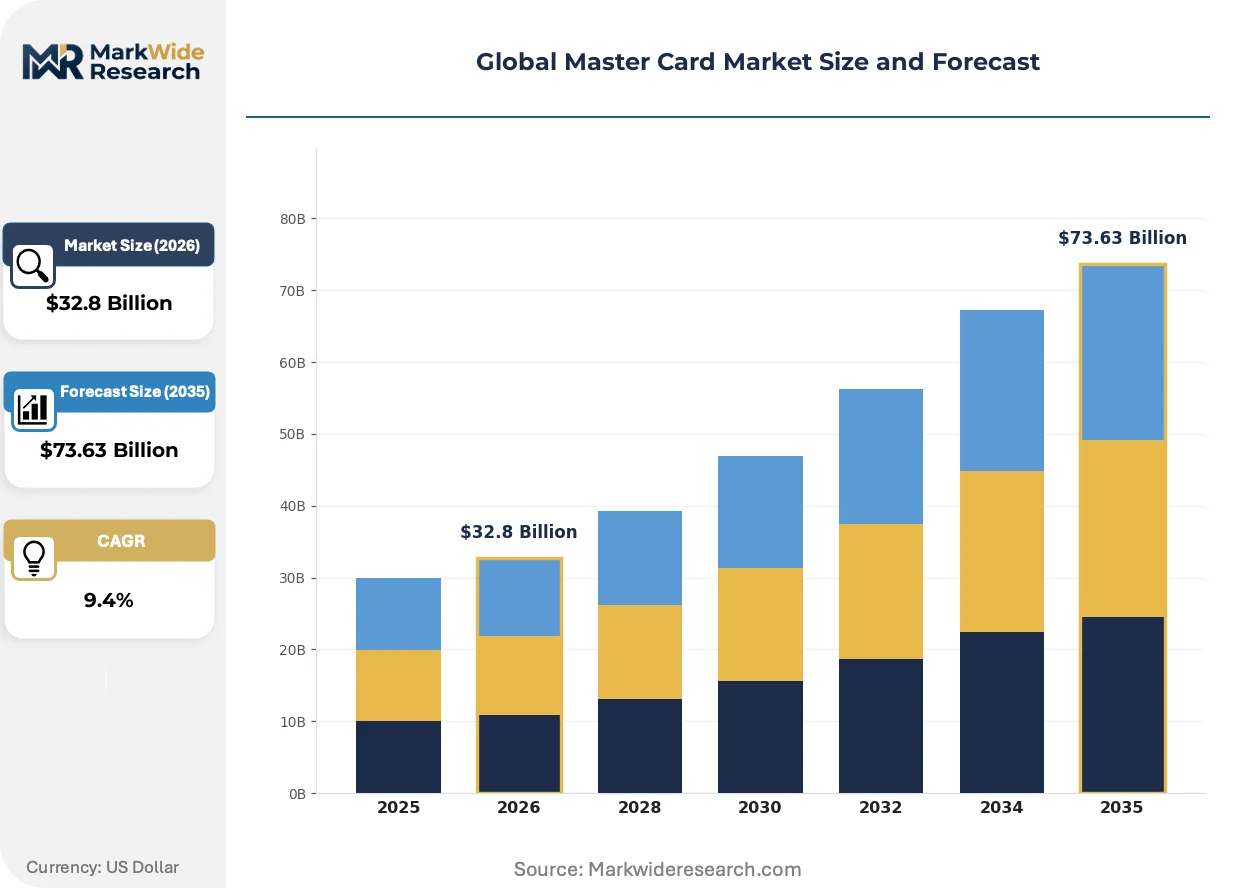
Market Dynamics
Tokenization infrastructure is compressing issuer margins while network operators capture value through platform licensing rather than pure transaction volume. This shift forces banks to rebuild revenue models around data services and embedded finance partnerships.
Growth Catalysts
- India's RuPay Interoperability Mandates:Domestic payment networks must integrate with international schemes, expanding addressable merchant acceptance for dual-branded credentials.
- Contactless EMV Standards:Tap-to-pay hardware upgrades across Brazil and Southeast Asian transit systems are accelerating card reissuance cycles.
- Tier-2 Urban Financial Inclusion:Government-backed basic savings account programs in Indian secondary cities are creating first-time cardholder populations previously excluded from formal banking.
Market Restraints
- Durbin Amendment Interchange Caps:US Federal Reserve limits on debit transaction fees constrain issuer profitability in the world's largest payment volume market.
- Semiconductor Supply Concentration:EMV chip fabrication depends on concentrated East Asian foundry capacity, creating procurement vulnerability for card personalization bureaus.
- Central Bank Digital Currency Substitution:Pilot programs in China and India threaten to displace card-linked payment rails for domestic transactions.
Strategic Opportunities
- Brazil's Urban Center Expansion:Pix instant payment infrastructure creates hybrid wallet-card propositions for underbanked metropolitan populations.
- EU Interchange Fee Regulation Arbitrage:Cross-border transaction cost limits for merchants enable network operators to structure premium corridor pricing.
- Biometric-Token Convergence:Fingerprint-activated credentials combined with device-bound tokens eliminate physical card dependency for high-value transactions.
Industry Challenges
- Data Localization Compliance:India's RBI mandates domestic storage of transaction records, forcing infrastructure rebuilds for multinational payment processors.
- Legacy Core Banking Integration:Real-time token provisioning requires API overhauls at issuing institutions with decades-old host systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Master Card Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Standard, Gold, Platinum, World, World Elite Industry Vertical: Telecommunications, Travel & Hospitality, E-Commerce, Education, Real Estate Distribution Channel: Direct Bank Issuance, Digital Wallets, Retail Partners, Corporate Sales, Affinity Programs End User: Individual Consumers, Small Enterprises, Online Merchants, Educational Institutions, Non-Profit Organizations |
| Companies Covered | Visa, American Express, Discover Financial Services, UnionPay, PayPal, Stripe, Global Payments, Fiserv, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Master Card Market Shifts & Advancements
Payment credential technology is fragmenting across physical, device-bound, and cloud-resident forms. This diversification demands new security architectures and challenges traditional network-operator business models.
EMV contactless chips are migrating from plastic substrates to smartphone secure elements and wearable devices. Transit authorities in London and Singapore are adopting open-loop fare acceptance, forcing card issuers to compete with phone-native credentials. The technology is migrating from merchant-presented terminals to consumer-controlled authentication environments.
REACH chemical substance restrictions in Europe are pressuring card manufacturers to eliminate brominated flame retardants from PVC substrates. The EU's Interchange Fee Regulation continues to compress cross-border revenue pools for network operators. Premium card products with metal substrates face supply chain requalification to maintain CE marking compliance.
Digital wallet unbundling is separating account funding from physical credential issuance. Younger demographics in South Korea and Sweden now treat cards as backend infrastructure rather than primary payment interfaces. Merchant acquirers in these markets report declining terminal-presented card volume alongside surging tokenized e-commerce authorization rates.
Global Master Card Market Segmentation
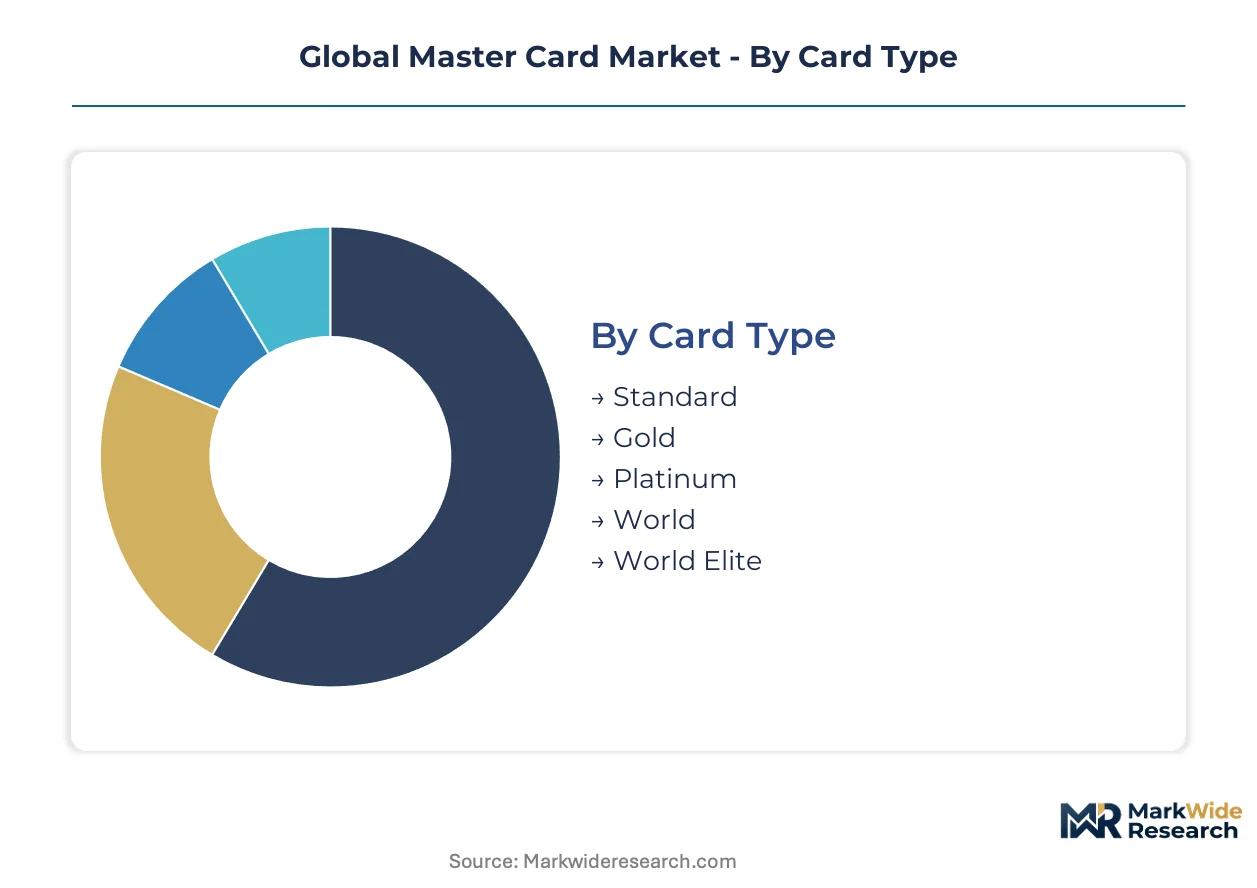
Master card segmentation reveals how payment networks capture value across divergent customer economics and distribution economics. Each dimension—card type, vertical, channel, and end user—exposes different margin pools and infrastructure requirements for issuers.
Card Type:
Mature premium products anchor issuer profitability while entry-level credentials expand addressable populations.
- Standard:PVC substrate cards with magnetic stripe and basic EMV chip authentication serve mass-market debit and credit portfolios. Demand concentrates in India's tier-2 cities under financial inclusion mandates, constrained by interchange fee compression.
- Platinum:Metal or composite substrate credentials with enhanced travel insurance and concierge services target affluent segments. Demand clusters in Brazil's urban centers and Southeast Asian business corridors, driven by cross-border e-commerce volume.
- Gold:Mid-tier rewards products with moderate annual fees and accelerated points earning on everyday spend.
- World:Premium positioning with lifestyle benefits and merchant discount access for upper-middle income households.
- World Elite:Invitation-only tier with dedicated relationship management and luxury travel privileges for ultra-high-net-worth segments.
Standard cards handle the majority of throughput; Platinum is expanding most quickly on share.
Industry Vertical:
Application concentration shifts with digital wallet penetration and regulatory treatment of sector-specific transactions.
- E-Commerce:Tokenized credentials for online checkout dominate authorization volumes, with device-bound tokens replacing physical card entry. Demand concentrates among online merchants across India and Southeast Asia, propelled by contactless EMV standard adoption.
- Travel & Hospitality:Multi-currency cards with dynamic currency conversion and lounge access serve international travelers. Demand clusters in Singapore and London transit corridors, shaped by open-loop fare acceptance mandates.
- Telecommunications:Co-branded products with carrier billing integration for device financing and subscription management.
- Education:Student-oriented credentials with low credit thresholds and financial literacy program tie-ins.
- Real Estate:Commercial cards for property management procurement and tenant payment processing.
E-Commerce captures the dominant authorization share; Travel & Hospitality is climbing the fastest.
Distribution Channel:
Channel economics are restructuring as platform licensing displaces pure transaction-based revenue capture.
- Digital Wallets:Device-bound tokens and cloud-resident credentials decouple account funding from physical issuance. Demand concentrates in South Korea and Sweden among younger demographics, driven by smartphone secure element migration.
- Direct Bank Issuance:Traditional branch and online application channels with integrated core banking systems. Demand clusters in Brazil's metropolitan areas, constrained by legacy host system API overhaul requirements.
- Retail Partners:Co-branded programs with supermarket and fuel station networks for mass-market acquisition.
- Corporate Sales:Commercial card programs with centralized expense management and procurement controls.
- Affinity Programs:Member association and professional society partnerships for niche segment targeting.
Direct Bank Issuance maintains volume leadership; Digital Wallets are gaining share fastest.
End User:
User type segmentation exposes diverging authentication requirements and fraud exposure profiles.
- Individual Consumers:Personal credit and debit products with consumer protection regulations and dispute resolution frameworks. Demand concentrates in Indian secondary cities, propelled by basic savings account program expansion.
- Online Merchants:Seller accounts with settlement timing advantages and chargeback protection for marketplace vendors. Demand clusters in Southeast Asian digital commerce corridors, shaped by RuPay interoperability mandates.
- Small Enterprises:Business cards with expense tracking and employee spending controls for owner-operated firms.
- Educational Institutions:Procurement cards with purchase order matching for administrative and research spend.
- Non-Profit Organizations:Donor-advised funding vehicles with restricted use compliance and grant tracking.
Individual Consumers account for the dominant transaction volume; Online Merchants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across payment corridors. Indian tier-2 cities and Brazilian urban centers exhibit high price sensitivity to interchange fees, while Singapore and London transit corridors absorb premium pricing for multi-currency credentials without volume contraction.
United States
Durbin Amendment interchange caps constrain debit issuer profitability while accelerating tokenization infrastructure investment. The Federal Reserve governs fee structures under Regulation II. Demand clusters in digital-native corridors spanning Austin and Seattle, where device-bound credentials displace physical card-present volume.
India
RuPay interoperability mandates force domestic network integration with international schemes, expanding dual-branded credential acceptance. RBI tokenization protocols and data localization requirements reshape processor infrastructure. Financial inclusion programs in Pune and Lucknow generate first-time cardholder populations from basic savings account expansion.
Brazil
Pix instant payment infrastructure creates hybrid wallet-card propositions for underbanked metropolitan populations. Central Bank of Brazil regulations govern open banking data sharing for payment initiation. São Paulo and Rio de Janeiro anchor credential reissuance cycles driven by contactless EMV transit system upgrades.
China
Central bank digital currency pilots threaten displacement of card-linked rails for domestic transactions. People's Bank of China governs payment clearing and foreign network market access restrictions. Shenzhen and Shanghai transit authorities adopt open-loop fare acceptance, forcing credential competition with phone-native wallets.
United Kingdom
Open-loop transit fare mandates accelerate contactless credential penetration across Transport for London corridors. Financial Conduct Authority rules govern payment service provider authorization and consumer protection frameworks. London fintech clusters drive tokenized e-commerce authorization volume through merchant acquirer partnerships.
Global Master Card Market Competitive Landscape
Capability concentration sits with network operators commanding tokenization infrastructure; scale advantage sits with processors managing transaction throughput across merchant categories. The market structures around three tiers: closed-loop issuers with captive merchant relationships, open-loop networks licensing platform access, and merchant acquirers consolidating authorization volume. Dominant competitive moves include strategic partnerships embedding credentials into digital wallets and geographic expansion through local scheme interoperability mandates.
Within the closed-loop issuer tier, American Express exemplifies relationship-driven positioning through travel-centric rewards ecosystems. Visa and UnionPay occupy complementary positions across corridor types, with the former anchoring cross-border e-commerce tokenization and the latter dominating Asia-Pacific clearing volume through government-backed network expansion. These three entities represent divergent archetypes for value capture beyond pure transaction interchange.
| Leading Market Players |
|---|
| Visa |
| American Express |
| Discover Financial Services |
| UnionPay |
| PayPal |
| Stripe |
| Global Payments |
| Fiserv |
| Adyen |
| Others |
Supply & Pricing Matrix
Overcapacity in East Asian EMV chip foundries is compressing unit economics for card personalization bureaus while simultaneously eroding pricing power across standard PVC substrate tiers. This utilization imbalance forces manufacturers to absorb REACH compliance costs and accept extended payment terms from network operators seeking to lock in volume commitments.
Pricing Analysis
Platform licensing revenue from tokenization infrastructure anchors lifetime value beyond physical card issuance. Three-tier pricing structure across premium metal-composite credentials, standard EMV PVC products, and entry-level magnetic-stripe portfolios reflects authentication complexity and annual fee bundling. Cost compression in standard tiers intensifies because India's RuPay interoperability mandates expand dual-branding requirements without corresponding interchange relief. Online merchants across Southeast Asia exhibit acute price sensitivity to transaction fees, while ultra-high-net-worth segments absorb World Elite premiums without volume contraction.
Supply Chain Analysis
Supply-chain finance facilities extended by network operators to card personalization bureaus are masking underlying fabrication concentration risks. EMV chip sourcing draws from Taiwan, South Korea, and mainland China foundries, while PVC substrate and metal composite card bodies originate from German and Japanese specialty chemical processors. Single-source vulnerability in semiconductor lithography equipment creates procurement fragility for issuers facing reissuance deadlines. Distribution runs through regional personalization hubs in São Paulo, Singapore, and Frankfurt that embed localized compliance and fulfillment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The master card market is entering a cyclical recovery phase as contactless EMV reissuance cycles and financial inclusion program expansions in India and Brazil drive replacement demand. Card reissuance velocity serves as the primary cyclical inflection driver.
For Market Incumbents: Pre-empt central bank digital currency displacement by accelerating biometric-token convergence investments that eliminate physical card dependency. Defend interchange revenue pools through embedded finance partnerships that reconstitute issuer economics around data services rather than pure transaction volume. Vertical integration into tokenization infrastructure represents the critical capability lever for sustaining platform licensing margins.
For New Entrants and Emerging Players: Brazil's underbanked metropolitan populations using Pix instant payment infrastructure represent the most penetrable entry point for hybrid wallet-card propositions. India's tier-2 city financial inclusion corridors offer second-mover acquisition opportunities as basic savings account programs mature into credit product eligibility. A direct-to-merchant acquisition model bypassing legacy bank distribution channels enables faster credential embedding into digital commerce checkout flows.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across tokenization infrastructure providers as platform licensing scales beyond physical issuance economics. The five-to-ten-year viability window favors network operators with closed-loop merchant relationship depth over pure transaction processors. Acquisition targets should demonstrate proven API integration capabilities with legacy core banking systems. The signal to watch is central bank digital currency pilot expansion velocity in China and India as a leading indicator of card-linked rail displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Tokenization Infrastructure Licensing | Visa's platform licensing model captures value beyond interchange through device-bound credential provisioning. |
| RuPay Interoperability Integration | Domestic network mandates in India expand addressable merchant acceptance for dual-branded credentials. |
| Biometric-Token Convergence | Fingerprint-activated credentials eliminate physical card dependency for high-value transaction authentication. |
| Contactless EMV Transit Upgrades | Brazil's São Paulo and Rio de Janeiro transit systems accelerate card reissuance cycles through tap-to-pay mandates. |
| Data Localization Infrastructure | RBI-mandated domestic transaction storage forces multinational processors to rebuild regional processing architectures. |
Research Methodology
A standing panel of payment network strategy executives, issuing bank product managers, merchant acquirer operations leads, and central bank regulatory specialists provided ongoing calibration across the research period. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Visa and American Express, RBI circulars on tokenization protocols, EU Interchange Fee Regulation implementation reports, and Brazil Central Bank Pix system disclosures. Bottom-up credential issuance volume estimates triangulated against top-down network operator revenue disclosures.
Scenario-bracketing framed the analytical approach, with baseline, accelerated digitization, and central bank digital currency displacement cases tested across the projection horizon. Segmentation dimensions modeled include card type tier, industry vertical application, distribution channel architecture, and end-user authentication profile. CAGRs derived from regression analysis against EMV reissuance cycle timing, financial inclusion program enrollment trajectories, and digital wallet penetration rates in South Korea and Sweden.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, emerging market currency volatility, or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timing and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Buy Now Pay Later Market
Payments
Southeast Asia POS Terminal Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
India Gift Card and Incentive Card Market
Payments
Saudi Arabia POS Terminal Market
Payments
Vietnam E-Wallet Market
Payments
Mobile Wallet Market
Payments
India Buy Now Pay Later Services Market
Payments
Social Media Payment Solution Market
Payments
Asia Pacific Mobile Wallet Market
Payments
France POS Terminal Market
Payments
China Payments Market
Payments
Denmark POS Terminals Market
Payments
India Payment Gateway Market
Payments
Global Financial Cards and Payments Market
Payments
Smart Bands Payments Market