
 Australia Payments Market | 2026-2036
Australia Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Payments Market Outlook
Platform licensing revenue is reshaping competitive economics across the Australia Payments Market. Commonwealth Bank of Australia leverages its extensive merchant network to sustain transaction volume leadership. Afterpay differentiates through its embedded checkout experience, while Stripe anchors developer-centric API infrastructure that powers thousands of Australian SaaS and marketplace businesses.
Australia Payments encompass electronic fund transfers, card networks, digital wallets, and real-time clearing systems that facilitate commercial and consumer value exchange. The technical stack relies on ISO 20022 messaging standards, tokenization protocols, and API-driven orchestration layers that settle transactions across the Reserve Bank of Australia's New Payments Platform within seconds. Mobile Wallet and Bank Transfer methods are capturing incremental share as contactless limits rise and real-time account-to-account settlement matures. Peer-to-Peer Transfers within the Transaction Type dimension are growing fastest, fueled by social payment habits and split-bill functionality embedded in banking apps.
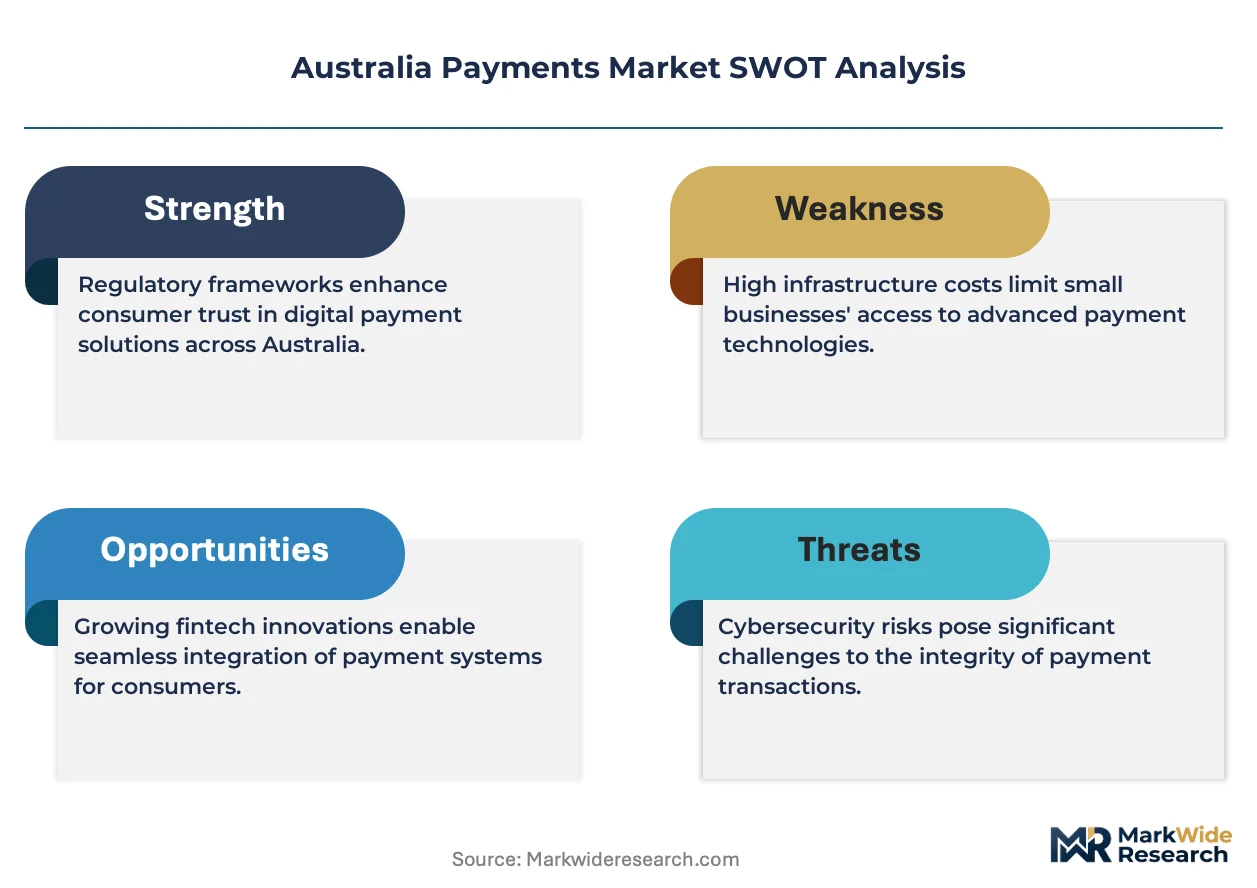
The Reserve Bank of Australia governs systemic payment stability and interchange regulation, while the Australian Securities and Investments Commission enforces licensing under the Payment Services Act and Anti-Money Laundering frameworks. Data Protection Regulations administered by the Office of the Australian Information Commissioner impose breach-notification mandates that elevate compliance costs for fintech entrants. Stakeholders must monitor how open banking data-sharing obligations under the Consumer Data Right will redistribute customer acquisition economics between incumbent banks and emerging payment orchestrators.
Market Dynamics
Platform licensing revenue is restructuring competitive economics across the Australia Payments Market, as real-time settlement infrastructure and open banking data-sharing obligations redistribute customer acquisition economics between incumbent banks and emerging payment orchestrators.
Growth Catalysts
- NPP Infrastructure Expansion:The Reserve Bank of Australia's New Payments Platform enables sub-second settlement that accelerates merchant digitization across retail corridors in Sydney and Melbourne.
- Consumer Data Right Mandates:Open banking frameworks force incumbent banks to share transaction data, lowering barriers for fintech entrants building embedded finance products.
- Contactless Terminal Rollout:Small business adoption of tap-to-pay hardware concentrates in New South Wales, where merchant digitization rates outpace other Australian states.
Market Restraints
- Compliance Cost Escalation:Data Protection Regulations administered by the Office of the Australian Information Commissioner impose breach-notification mandates that elevate operational overhead for emerging payment providers.
- Interchange Rate Compression:Reserve Bank of Australia regulation of merchant service fees constrains revenue per transaction for card network participants.
- Core Banking Legacy Debt:Tier-one banks maintain decades-old mainframe architectures that slow API integration with modern payment orchestration layers.
Strategic Opportunities
- Queensland and Western Australia Penetration:Merchant digitization lags behind New South Wales and Victoria, creating whitespace for terminal deployment and SaaS-embedded checkout solutions.
- Account-to-Account Convergence:Real-time bank transfer functionality is merging with digital wallet interfaces, enabling direct debit alternatives to card networks at lower cost.
- Superannuation Payment Integration:Regulatory pressure on employer compliance creates demand for payroll-integrated payment rails that automate contribution timing.
Industry Challenges
- ISO 20022 Migration Complexity:Financial institutions must retool messaging infrastructure to meet messaging standards deadlines while maintaining backward compatibility.
- Tokenization Architecture Fragmentation:Competing token vault implementations across card networks and wallets complicate merchant integration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Payments Market |
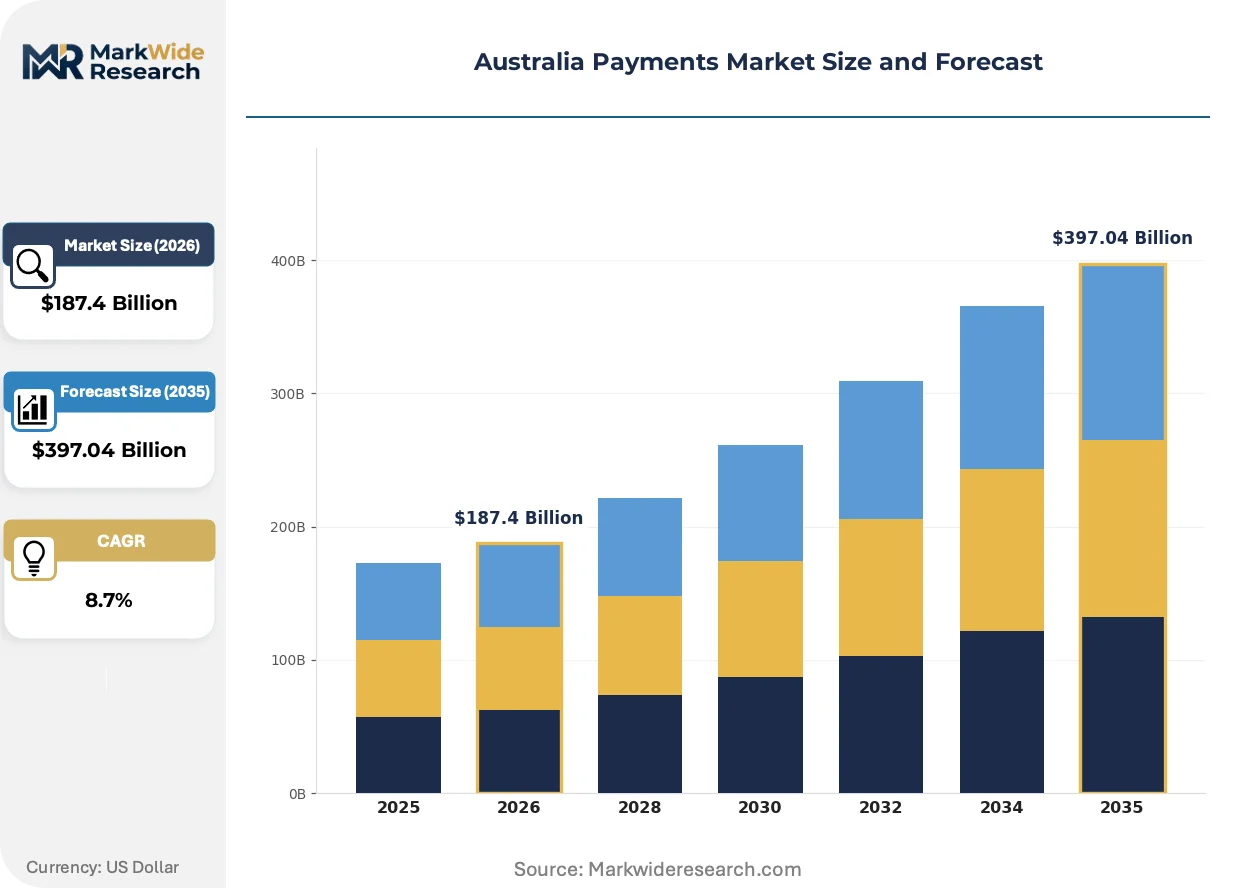
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Transaction Type: Online Payments, In-Store Purchases, Recurring Payments, Peer-to-Peer Transfers Customer Segment: Millennials, Gen Z, Small Businesses, Corporates Regulatory Framework: Payment Services Act, Anti-Money Laundering, Data Protection Regulations, Consumer Protection Laws |
| Companies Covered | Australia and New Zealand Banking Group, Afterpay, Commonwealth Bank of Australia, Tyro Payments, Zip Co, Westpac Banking Corporation, PayPal, Stripe, National Australia Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Payments Market Strategic Shifts
Payment infrastructure is virtualizing around software-defined orchestration layers that abstract underlying settlement rails, compressing the distinction between traditional banking and fintech service delivery.
API-first payment orchestration is virtualizing merchant acquiring by embedding checkout functionality directly into e-commerce platforms and SaaS marketplaces. Mid-market retailers in Brisbane and Perth are adopting these pre-integrated stacks faster than standalone terminal deployments. This compression of the merchant services value chain is forcing traditional acquirers to reprice gateway services or cede volume to platform-native providers.
The Australian Securities and Investments Commission is tightening enforcement of the Payment Services Act licensing regime, requiring non-bank payment providers to hold restricted ADI status for certain activities. This regulatory tightening is raising capital requirements and compliance overhead for fintech scale-ups. Neobanks and buy-now-pay-later operators are responding by pursuing banking licenses or partnering with incumbent ADIs to access regulatory cover.
Split-bill functionality embedded in banking apps is displacing standalone peer-to-peer transfer tools as the default social payment method among Australian consumers. Major bank mobile applications now capture restaurant and travel expense sharing that previously flowed through dedicated fintech wallets. This behavioral shift is most visible among under-35 demographics in metropolitan Sydney and Melbourne, where social payment frequency exceeds traditional bill payment volume.
Australia Payments Market Segmentation
Payment infrastructure in Australia fragments across settlement rails, customer demographics, and compliance obligations. Understanding these divisions reveals where transaction volume concentrates and where emerging providers can displace incumbent economics.
Payment Method:
Settlement velocity varies dramatically across these rails, with real-time infrastructure compressing cycle times while legacy card networks maintain slower clearing schedules.
- Credit Card:Revolving credit facilities tied to international card scheme networks dominate high-value discretionary spending. Australian consumers concentrate usage in travel and hospitality verticals, though interchange rate compression by the Reserve Bank of Australia constrains issuer margins.
- Debit Card:Direct linkage to deposit accounts eliminates credit risk for merchants and reduces transaction costs. Demand concentrates in everyday retail across New South Wales supermarkets and fuel stations, driven by contactless limit increases that displaced cash handling.
- Mobile Wallet:Tokenized credentials stored on NFC-enabled smartphones enable tap-to-pay without physical plastic. Uptake accelerates among under-35 demographics in metropolitan Sydney and Melbourne where device penetration nears saturation.
- Bank Transfer:Real-time account-to-account settlement via the New Payments Platform bypasses card network fees entirely. Small business adoption concentrates in B2B invoicing and payroll disbursements where cost sensitivity overrides convenience preferences.
Credit and debit cards dominate installed base. Bank transfer is where expansion concentrates.
Transaction Type:
Frequency and ticket size diverge sharply across these use cases, with recurring and peer-to-peer formats exhibiting fundamentally different churn characteristics than one-time purchases.
- Online Payments:Card-not-present transactions across e-commerce platforms require 3D Secure authentication and fraud screening layers. Merchant demand concentrates in marketplace checkout flows where cart abandonment rates drive conversion optimization investments.
- In-Store Purchases:Physical point-of-sale interactions rely on EMV chip or contactless tap authentication. Small business terminal deployment across Melbourne retail corridors accelerates as cash handling costs exceed digital acceptance fees.
- Recurring Payments:Pre-authorized debits for subscriptions and utilities minimize collection friction. Corporate adoption concentrates in SaaS billing and membership services where churn reduction justifies integration complexity.
- Peer-to-Peer Transfers:Social payment splitting and informal lending flow through banking apps or dedicated wallets. Frequency among Gen Z consumers in Sydney exceeds traditional bill payment volume, driven by restaurant and travel expense sharing habits.
In-store purchases anchor transaction volume. Peer-to-peer transfers are climbing the fastest.
Customer Segment:
Technology adoption curves and payment behavior maturity separate these groups, with generational divides more pronounced than business-scale differences.
- Millennials:Prime earning years coincide with mortgage and family formation expenses that sustain high transaction frequency. Banking app engagement concentrates in New South Wales and Victoria where digital-first institutions captured early cohort loyalty.
- Gen Z:Native mobile interaction patterns favor in-app checkout and biometric authentication over traditional card interfaces. Social payment embedding in messaging platforms drives platform choice more than interest rates or rewards programs.
- Small Businesses:Sole traders and micro-enterprises prioritize low-cost acceptance over feature depth. Terminal adoption lags in Queensland and Western Australia compared to eastern states, creating whitespace for deployment expansion.
- Corporates:Treasury departments demand API-accessible reconciliation and multi-entity reporting. Integration with ERP systems and superannuation compliance workflows determines vendor selection more than per-transaction pricing.
Millennials and corporates dominate revenue contribution. Gen Z is where acquisition economics are steepest.
Regulatory Framework:
Compliance burden intensity and enforcement velocity create tiered barriers to entry that favor well-capitalized incumbents over emerging fintech challengers.
- Payment Services Act:Australian Securities and Investments Commission licensing mandates separate regulated payment providers from unregulated technology vendors. Capital requirements and operational risk frameworks elevate entry costs for neobank and buy-now-pay-later scale-ups.
- Anti-Money Laundering:Customer due diligence and transaction monitoring obligations apply to all payment service providers. Reporting thresholds and suspicious activity detection systems impose fixed compliance overhead regardless of transaction volume.
- Data Protection Regulations:Office of the Australian Information Commissioner breach-notification mandates elevate operational risk for fintech entrants. Privacy impact assessments and cross-border data transfer restrictions complicate cloud infrastructure choices.
- Consumer Protection Laws:Dispute resolution and refund obligation frameworks govern payment service quality standards. Chargeback liability allocation between merchants and acquirers shapes risk pricing across e-commerce verticals.
Anti-Money Laundering and Payment Services Act dominate compliance spend. Data Protection Regulations are gaining enforcement priority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant digitization rates vary sharply across Australian states, with New South Wales and Victoria exhibiting the lowest price elasticity for payment infrastructure while Queensland and Western Australia remain highly cost-sensitive in terminal adoption decisions.
New South Wales
Contactless terminal penetration reaches saturation in Sydney's retail corridors, driven by small business migration from cash handling. The Australian Securities and Investments Commission enforces Payment Services Act licensing mandates that elevate compliance costs for fintech entrants. Merchant digitization concentrates in Parramatta and North Sydney commercial districts, where real-time NPP settlement has displaced traditional card clearing for B2B invoicing.
Victoria
Melbourne's hospitality sector generates dense transaction volume through embedded checkout solutions and banking app split-bill functionality. Consumer Data Right obligations force incumbent banks to share transaction data, lowering barriers for emerging payment orchestrators. Fintech clustering in the Docklands precinct accelerates API-first orchestration layer development for SaaS marketplaces.
Queensland
Terminal deployment lags behind eastern states, creating whitespace for low-cost acquiring solutions among Brisbane sole traders and micro-enterprises. The Office of the Australian Information Commissioner imposes breach-notification mandates that elevate operational risk for cloud-native providers. Merchant digitization accelerates in Fortitude Valley and Surfers Paradise retail strips as contactless limits rise.
Western Australia
Resource sector payroll integration drives demand for real-time bank transfer functionality in Perth corporate treasuries. Anti-Money Laundering customer due diligence obligations apply uniformly across all payment service providers regardless of transaction volume. B2B payment automation concentrates in the Perth CBD, where superannuation compliance workflows determine vendor selection.
South Australia
Adelaide's mid-market retailers adopt pre-integrated payment stacks faster than standalone terminal deployments, compressing the merchant services value chain. ISO 20022 migration deadlines force retooling of messaging infrastructure while maintaining backward compatibility. Terminal rollout concentrates in Rundle Mall and Glenelg retail corridors as cash handling costs exceed digital acceptance fees.
Australia Payments Market Competitive Environment
Domestic banking incumbents and fintech challengers split the market along regulatory-access and technology-velocity axes. The vendor base concentrates around four distinct strategic archetypes: major bank payment divisions, buy-now-pay-later specialists, global platform orchestrators, and neobank payment arms. Consolidation pressure intensifies as scale advantages in compliance infrastructure and API development widen performance gaps between tiers. Dominant competitive moves include restricted ADI license pursuit for regulatory cover and vertical integration into embedded checkout experiences.
Within the domestic banking tier, Commonwealth Bank of Australia and Australia and New Zealand Banking Group exemplify incumbent institutions leveraging extensive merchant networks to sustain transaction volume leadership. Among fintech challengers, Afterpay and Zip Co occupy positions that illustrate the buy-now-pay-later archetype's reliance on embedded checkout differentiation. At the global platform end, Stripe and PayPal anchor developer-centric infrastructure that powers thousands of Australian SaaS and marketplace businesses.
| Leading Market Players |
|---|
| Australia and New Zealand Banking Group |
| Afterpay |
| Commonwealth Bank of Australia |
| Tyro Payments |
| Zip Co |
| Westpac Banking Corporation |
| PayPal |
| Stripe |
| National Australia Bank |
| Others |
Value Chain & Pricing Dynamics
The Port Botany freight corridor's container handling cost dynamics concentrate payment terminal distribution through New South Wales, amplifying price differentiation between eastern seaboard merchants and inland Queensland operators while compressing margins for hardware-dependent acquirers.
Pricing Analysis
Software subscription and transaction-fee revenue tiers now drive lifetime value more than terminal hardware sales. Three-tier pricing structure across premium API-integrated, standard gateway, and economy standalone terminal levels stratifies the market. Pricing pressure stems from Reserve Bank of Australia interchange compression and cloud-native provider entry. Small business sole traders in Western Australia exhibit highest price sensitivity; corporate treasuries in Sydney CBD demonstrate lowest.
Supply Chain Analysis
Australian export-control restrictions on cryptographic security modules limit terminal component flows from designated manufacturing jurisdictions. Hardware assembly concentrates in China, Taiwan, and Malaysia; tokenization security elements draw from United States and United Kingdom suppliers. Single-source vulnerability sits with NPP gateway certification bottlenecks. Distribution runs through authorized dealer networks and direct SaaS platform embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform licensing and recurring orchestration revenue layers expand faster than terminal hardware sales, reframing the Australia Payments Market as a service-attach opportunity where embedded finance integration determines long-term customer lifetime value.
For Market Incumbents: Build regulatory moat through restricted ADI licensing to neutralize neobank and buy-now-pay-later challenger threats. Deepen API development capacity in Melbourne Docklands fintech clusters to maintain orchestration layer control. Pursue backward integration into token vault infrastructure to reduce network dependency. For New Entrants and Emerging Players: Pursue Queensland and Western Australia terminal deployment whitespace where merchant digitization lags eastern states. Target Brisbane sole traders and Perth micro-enterprises with low-cost acquiring solutions. Embed checkout functionality directly into vertical SaaS platforms serving trades and professional services. For Investors and Strategic Acquirers: API-first orchestration specialists with established NPP connectivity represent the highest-conviction acquisition archetype. Five-to-ten year viability hinges on open banking data monetization scale. Watch Consumer Data Right enforcement velocity as inflection indicator for customer acquisition economics redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Restricted ADI License Pursuit | Reserve Bank of Australia prudential cover unlocks payment settlement access and neutralizes regulatory risk. |
| API-First Orchestration Development | ISO 20022 messaging integration enables real-time NPP settlement for SaaS marketplace embedding. |
| Queensland Terminal Deployment | Fortitude Valley and Surfers Paradise retail strips offer underpenetrated merchant digitization expansion. |
| Token Vault Infrastructure Investment | In-house tokenization reduces card network dependency and improves merchant reconciliation latency. |
| Superannuation Payment Rail Integration | ASIC compliance workflow automation captures employer payroll-integrated contribution timing demand. |
Study Parameters
Desk research of Reserve Bank of Australia payment system publications, ASIC licensing registers, and NPP infrastructure disclosure documents preceded structured interviews with payment operations executives at major banks, fintech product managers, merchant acquiring heads, and regulatory compliance officers. Primary fieldwork combined with secondary validation across ABS transaction statistics, industry association submissions, and securities filings. Bottom-up transaction volume modeling and top-down macroeconomic sizing were triangulated for convergence.
Assumptions held NPP real-time settlement penetration and Consumer Data Right adoption schedules fixed across the projection horizon, while varying merchant digitization rates by state and contactless limit policy trajectories. Segmentation dimensions modeled include payment method, transaction type, customer segment, and regulatory framework tier. CAGRs derived from logistic diffusion curves fitted to terminal deployment and digital wallet uptake trajectories. Forecast inputs incorporated interchange regulation schedules and open banking API maturity indicators.
Sensitivities concentrate around Reserve Bank of Australia policy shifts on merchant service fees and ASIC enforcement intensity under the Payment Services Act. Forecasts reflect documented assumptions on infrastructure rollout timelines and competitive response lag structures. Material shifts in NPP real-time settlement adoption or Consumer Data Right data-sharing scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Forex Prepaid Cards Market
Payments
United States Real Time Payments Market
Payments
Vietnam E-Wallet Market
Payments
South Korea Mobile Payment Market
Payments
North America Payment Analytics Software Market
Payments
Electronic Cash Register Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Social Media Payment Solution Market
Payments
US Buy Now Pay Later Services Market
Payments
Hungary POS Terminal Market
Payments
M Commerce Payment Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Europe Mobile Payment Market
Payments
Japan Payments Market
Payments
Global Payments As a Service Market
Payments
Japan Payment Gateway Market