
 Canada Buy Now Pay Later Market | 2026-2036
Canada Buy Now Pay Later Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Buy Now Pay Later Market Insights
Canada's enhanced consumer protection framework for digital lending is consolidating regulatory expectations across provincial and federal jurisdictions. Sezzle Inc leverages its merchant-integrated checkout platform to sustain dominance in Canadian retail partnerships. PayPal Holdings Inc anchors its position through embedded BNPL functionality within its existing e-commerce infrastructure. Klarna differentiates via its AI-powered shopping experience layered with flexible payment options.
Buy Now Pay Later denotes a short-term consumer financing mechanism enabling purchasers to split transaction costs into scheduled installments, typically interest-free, with merchant-funded fees covering operational costs. The model relies on real-time credit assessment algorithms, automated repayment scheduling, and direct merchant API integration to facilitate frictionless checkout conversion. Interest-free service types currently occupy the largest transaction volume as merchants absorb promotional financing costs to reduce cart abandonment. Gen Z customer segments represent the fastest-growing cohort, driven by mobile-native purchasing behavior and preference for debit-linked alternatives to traditional revolving credit. E-commerce merchant types concentrate margin pools through high-frequency, low-ticket transactions in fashion and consumer electronics.
Health Canada and the Financial Consumer Agency of Canada jointly influence market structure through oversight of credit product disclosures and consumer harm mitigation protocols. Provincial regulators in Ontario and British Columbia impose additional licensing requirements on non-bank lenders operating installment plans. The Office of the Superintendent of Financial Institutions monitors systemic risk as bank-affiliated BNPL offerings expand. Stakeholders must track evolving provincial credit legislation and federal open banking implementation to anticipate compliance cost shifts and competitive entry barriers.
Market Dynamics
Real-time credit decisioning engines are compressing underwriting cycles from days to milliseconds, forcing incumbent lenders to rebuild their core infrastructure around API-first architectures or cede merchant relationships to fintech-native platforms.
Growth Catalysts
- FCAC Disclosure Mandates:The Financial Consumer Agency of Canada's standardized fee transparency rules are reducing consumer confusion and accelerating mainstream adoption of installment products among risk-averse demographics previously wary of hidden charges.
- Mobile-First Checkout:Ontario and British Columbia retailers deploying one-tap BNPL integration at point-of-sale are capturing abandoned carts from Gen Z shoppers who reject traditional credit card application friction.
- Open Banking Infrastructure:Canada's phased consumer-directed finance framework enables alternative data scoring that expands credit access to thin-file borrowers previously excluded from prime lending tiers.
Market Restraints
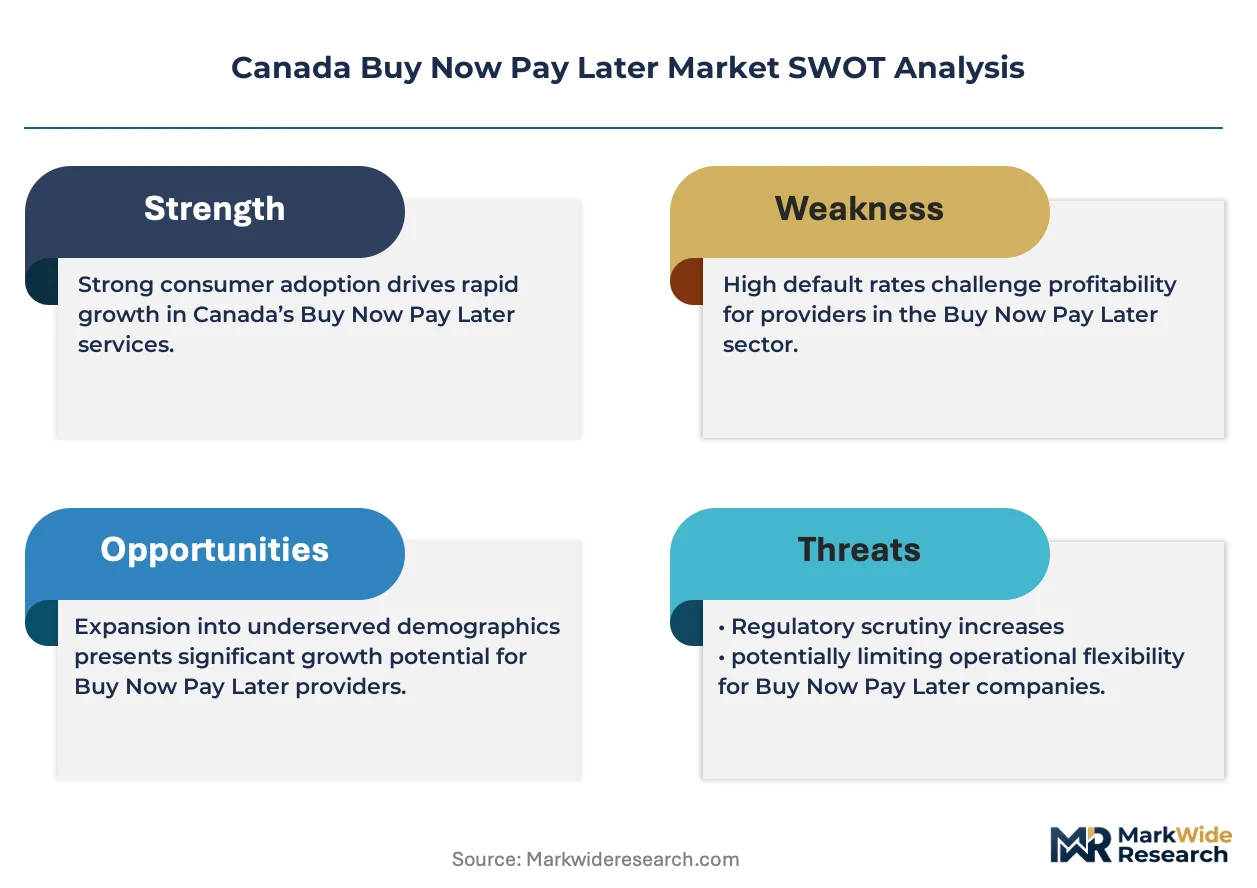
- Provincial Licensing Fragmentation:Non-bank lenders face duplicative compliance costs navigating separate registration requirements across Ontario, British Columbia, Alberta, and Quebec regulatory regimes.
- Merchant Fee Compression:Retailers in saturated electronics and apparel verticals are negotiating down interchange-equivalent rates, squeezing platform unit economics on low-ticket transactions.
- Deposit-Funded Substitution:Traditional banks are retrofitting installment features onto existing credit card infrastructure, presenting zero-switching-cost alternatives to standalone BNPL providers.
Strategic Opportunities
- Healthcare Services:Elective medical and dental providers across Ontario and Quebec represent underpenetrated merchant categories where deferred payment options align with uninsured procedure demand.
- AI-Powered Personalization:Convergence of machine learning recommendation engines with embedded checkout financing is creating differentiated shopping experiences that transcend pure price competition.
- Small Business Lending:B2B trade credit digitization for Canadian SMBs offers white-space expansion beyond saturated consumer retail verticals.
Industry Challenges
- Real-Time Risk Modeling Talent:Platforms struggle to recruit data scientists with expertise in alternative credit scoring and fraud detection calibrated to Canadian consumer behavior patterns.
- Legacy Core Integration:Bank-affiliated BNPL offerings face technical debt from decades-old payment processing architectures that impede agile product iteration against fintech competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Buy Now Pay Later Market |
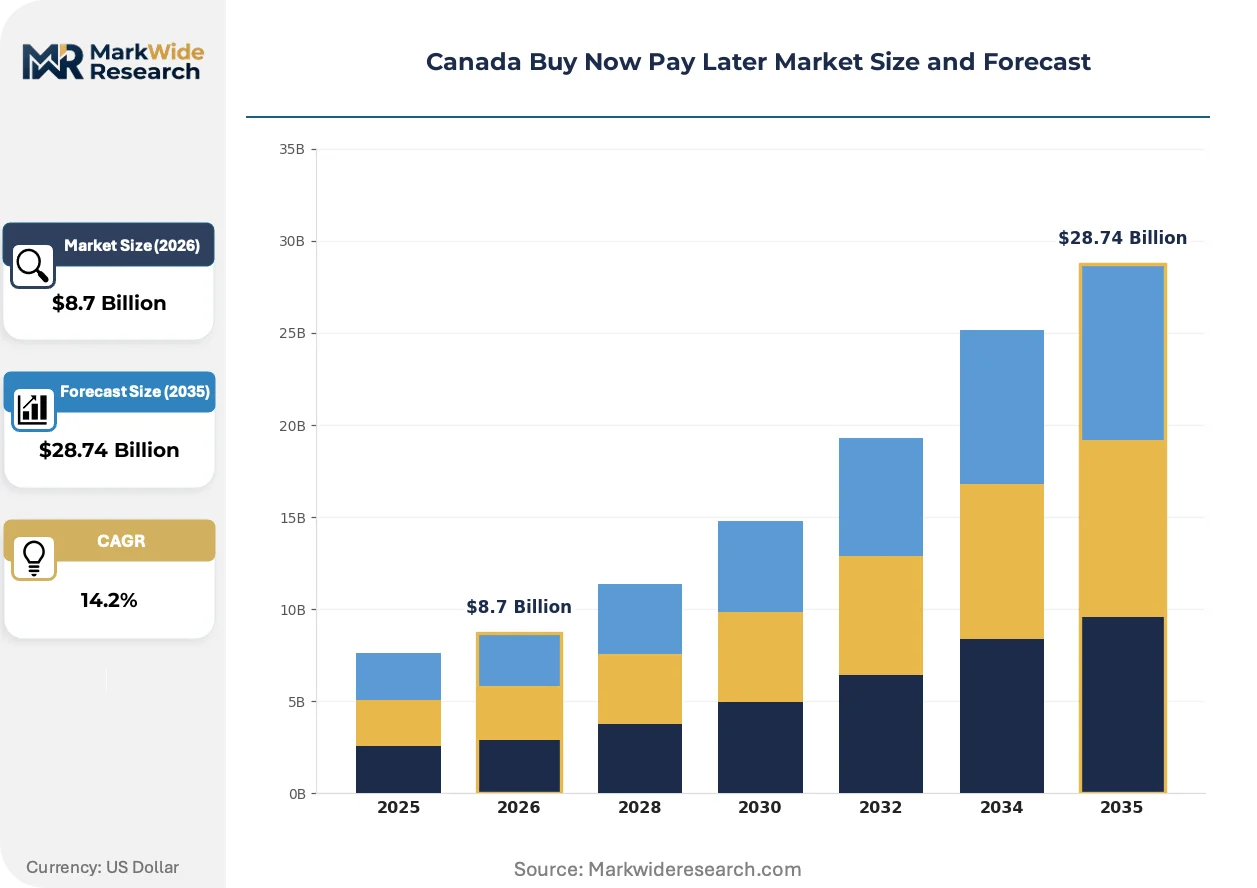
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Bank Transfer, Mobile Payment, E-Wallet Customer Type: Millennials, Gen Z, Working Professionals, Retirees Service Type: Interest-Free, Installment Plans, Subscription Services, Deferred Payments Merchant Type: E-commerce, Retail, Travel, Home Improvement |
| Companies Covered | Sezzle Inc, PayPal Holdings Inc, Afterpay, Block Inc, Splitit Payments Ltd, Klarna, Zip Co Limited, Laybuy Group Holdings Limited, Affirm Holdings Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Buy Now Pay Later Market Trends and Innovations
Artificial intelligence is penetrating every layer of the BNPL value chain, from acquisition targeting through collections optimization, creating structural separation between algorithmically-native platforms and rules-based legacy systems.
Machine learning underwriting is automating credit decisions using cash-flow data from open banking connections rather than traditional FICO scores. Thin-file Gen Z applicants in Vancouver and Toronto gain approval access previously denied by bureau-dependent models. This compression of exclusionary criteria is expanding addressable market reach for platforms with superior data pipelines.
The Financial Consumer Agency of Canada's installment lending guidance is mandating standardized disclosure formats across all provinces. Lenders must present total cost of credit in dollar terms rather than percentage rates. Quebec's consumer protection framework already enforces stricter cooling-off periods that other provinces are evaluating for adoption.
Debit-linked preference is displacing revolving credit dependency among younger Canadian cohorts. Mobile-native shoppers in Ontario prefer fixed-schedule installments drawn directly from chequing accounts over open-ended credit card balances. This behavioral pivot favors platforms offering zero-interest merchant-funded models over traditional interest-bearing products.
Canada Buy Now Pay Later Market Segmentation
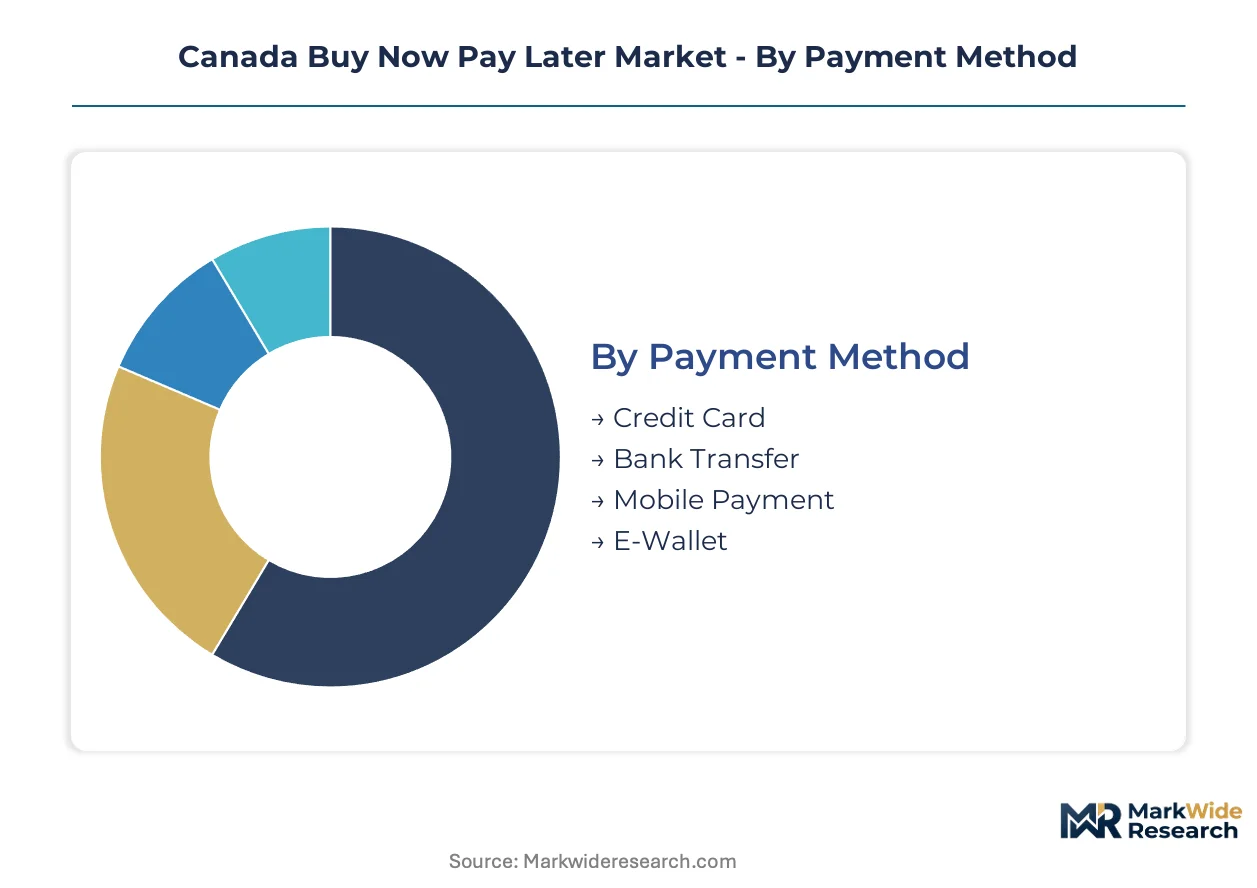
Payment method selection determines platform technical architecture and risk exposure in Canada's BNPL landscape. Customer demographics dictate underwriting model sophistication and merchant partnership priorities.
Payment Method:
Credit card rails dominate transaction volume while debit-linked alternatives capture premium growth segments.
- Credit Card:Traditional revolving credit infrastructure processes the majority of BNPL volume through existing bank networks. Ontario and British Columbia retailers favor this method for higher-ticket electronics purchases where consumer credit limits accommodate deferred payment structures.
- Bank Transfer:Direct debit from chequing accounts eliminates interchange fees and appeals to debt-averse Gen Z shoppers in Vancouver and Toronto. The Financial Consumer Agency of Canada's disclosure mandates accelerate adoption among consumers seeking transparent, fixed-schedule repayment without revolving balance risk.
- Mobile Payment:One-tap checkout integration through smartphone-native wallets.
- E-Wallet:Stored-value digital accounts with embedded installment functionality.
Mature deployment sits with Credit Card. Newer deployment is concentrated in Bank Transfer.
Customer Type:
Generational cohorts exhibit divergent payment preferences that reshape platform acquisition strategies and product design.
- Gen Z:Mobile-native consumers born after 1996 drive the steepest expansion trajectory through debit-first purchasing behavior. Thin-file applicants in Ontario leverage open banking data streams for approval access previously denied by traditional bureau scoring.
- Millennials:Digitally fluent cohort balancing family formation expenses with credit optimization. British Columbia's urban centers concentrate demand for interest-free apparel and electronics financing as this segment prioritizes cash-flow management over revolving credit utilization.
- Working Professionals:Established income earners seeking convenience-driven checkout experiences.
- Retirees:Risk-averse demographic requiring simplified disclosure formats and enhanced customer support.
Platform investment concentrates on Gen Z. Regulatory attention targets Retirees.
Service Type:
Merchant funding models separate zero-interest promotional products from consumer-borne interest structures.
- Interest-Free:Retailer-absorbed financing costs eliminate consumer interest charges in exchange for merchant fees. E-commerce merchants in saturated electronics verticals deploy this structure to reduce cart abandonment among price-sensitive Ontario shoppers.
- Installment Plans:Fixed-schedule repayment with predictable obligation structures. Quebec's consumer protection framework mandates stricter cooling-off periods for these products, influencing national compliance standardization.
- Subscription Services:Recurring payment bundling for membership-based consumption models.
- Deferred Payments:Single-future-date settlement options for seasonal purchasing patterns.
Merchant acquisition prioritizes Interest-Free. Regulatory scrutiny intensifies on Installment Plans.
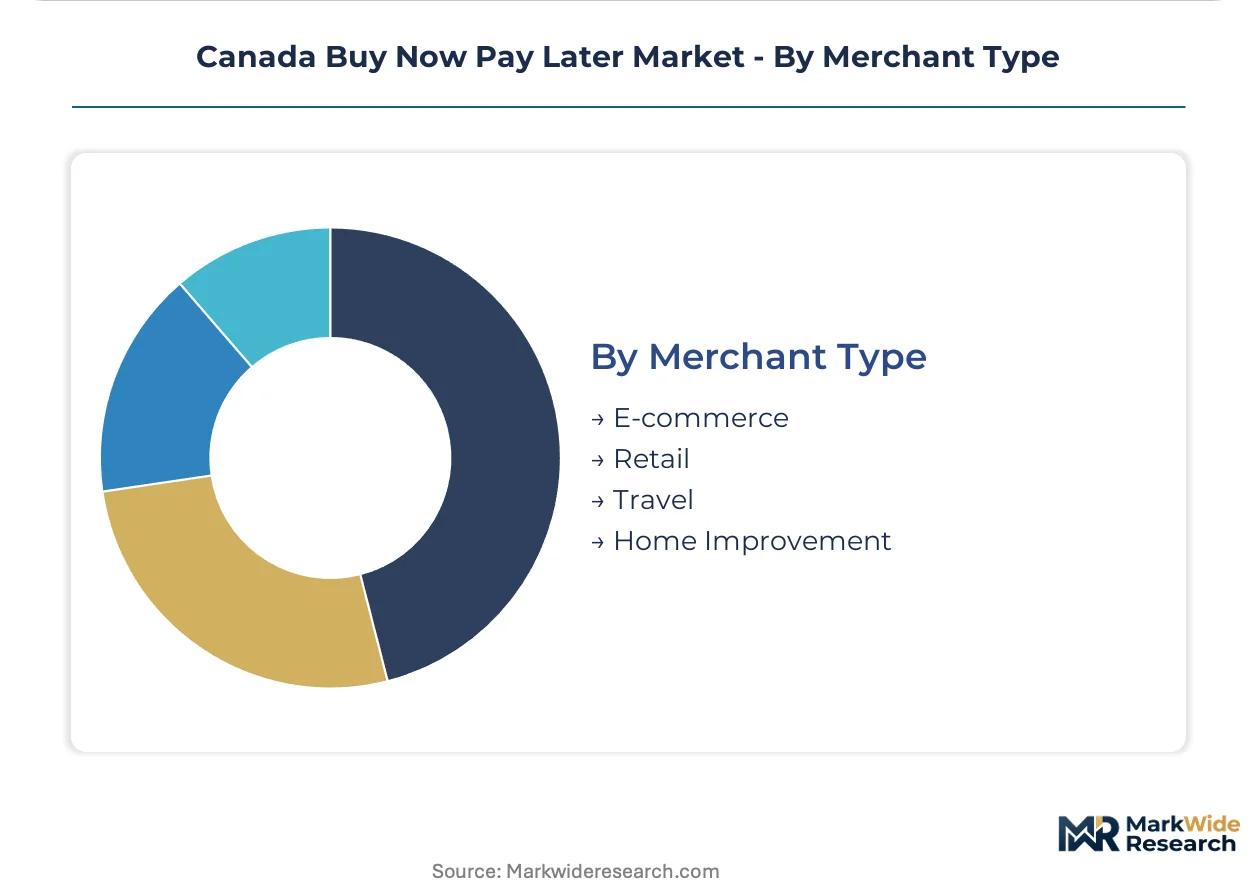
Merchant Type:
Vertical specialization determines platform API integration complexity and underwriting calibration requirements.
- E-commerce:Digital-native checkout environments generate the highest transaction frequency through embedded one-click financing. Fashion and consumer electronics merchants in Toronto and Vancouver leverage real-time credit decisioning to capture mobile-first Gen Z conversion.
- Retail:Brick-and-mortar point-of-sale deployment requires terminal hardware integration and staff training. Ontario's big-box electronics chains anchor physical BNPL adoption through QR-code activated installment applications.
- Travel:High-ticket, low-frequency vertical with seasonal demand concentration.
- Home Improvement:Project-based financing for contractor-mediated purchases.
Technical maturity peaks in E-commerce. Physical infrastructure investment targets Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toronto anchors Canadian BNPL adoption through its concentration of fintech infrastructure and merchant headquarters. The Financial Consumer Agency of Canada operates from Ottawa, shaping disclosure standards that cascade across provincial regulators.
Ontario
Gen Z electronics shoppers in Toronto and Ottawa drive mobile-first checkout adoption through debit-linked installment preferences. The Financial Consumer Agency of Canada's standardized fee transparency rules reduce consumer confusion and accelerate mainstream product acceptance. Waterloo's technology corridor hosts real-time credit decisioning engineering talent pools.
British Columbia
Vancouver's apparel merchants deploy one-tap BNPL integration to capture abandoned carts from mobile-native demographics. Provincial consumer protection licensing requirements impose additional registration obligations on non-bank lenders operating installment plans. Victoria's retail clusters concentrate demand for interest-free promotional financing.
Quebec
Montreal's fashion e-commerce merchants leverage merchant-funded models to reduce cart abandonment among price-sensitive shoppers. The province's consumer protection framework enforces stricter cooling-off periods that influence national compliance standardization. Laval's retail corridors anchor physical point-of-sale deployment through QR-code activated applications.
Alberta
Calgary's energy sector professionals seek convenience-driven checkout experiences for discretionary electronics purchases. Provincial licensing requirements add duplicative compliance costs for non-bank lenders expanding from Ontario and British Columbia. Edmonton's retail clusters concentrate demand for fixed-schedule installment products.
Canada Buy Now Pay Later Market Competitive Landscape
Premium-margin players sit above commodity-margin players across merchant partnership depth and underwriting sophistication. The Canadian BNPL landscape fragments between bank-affiliated platforms with existing payment infrastructure and fintech-native specialists with API-first architectures. Two strategic archetypes dominate: merchant-integrated checkout platforms and embedded finance providers leveraging existing e-commerce relationships. Competitive moves concentrate on strategic partnerships with retail verticals and technology licensing for real-time credit decisioning engines.
Within the merchant-integrated tier, Sezzle Inc and PayPal Holdings Inc exemplify divergent approaches to Canadian market penetration. Sezzle occupies a position representing specialized installment platform architecture built around retail API integration. PayPal anchors the embedded finance archetype through its existing e-commerce payment infrastructure. Klarna sits within the AI-powered shopping experience segment, layering flexible payment options atop machine learning recommendation engines.
| Leading Market Players |
|---|
| Sezzle Inc |
| PayPal Holdings Inc |
| Afterpay |
| Block Inc |
| Splitit Payments Ltd |
| Klarna |
| Zip Co Limited |
| Laybuy Group Holdings Limited |
| Affirm Holdings Inc |
| Others |
Pricing and Supply Chain Analysis
Real-time credit decisioning engines are compressing underwriting infrastructure costs while concentrating platform economics among API-native providers with direct merchant integration. This technology shift simultaneously reduces marginal transaction processing expenses and amplifies pricing power for vertically integrated players controlling both scoring algorithms and checkout endpoints.
Pricing Analysis
Merchant-funded promotional financing anchors value-based pricing in Canada's BNPL landscape, with retailers absorbing service fees to capture abandoned cart conversion. Price differentiation rests on transaction volume tiers and vertical risk profiles, with electronics merchants commanding lower per-transaction rates than discretionary apparel. Cost compression in saturated retail verticals is intensifying because of interchange-equivalent rate negotiations. Gen Z shoppers exhibit highest price sensitivity to visible fees, while established working professionals demonstrate lowest sensitivity to backend merchant pricing.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers hosting real-time scoring engines, particularly AWS and Azure data centers concentrated in Ontario and Quebec. The technology stack draws from US-based payment processors, Indian engineering talent pools for algorithm development, and domestic Canadian regulatory compliance consultants. Supply chain risk centers on data sovereignty requirements under federal privacy legislation. Distribution runs through direct API integration with merchant e-commerce platforms rather than intermediary aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's BNPL market is becoming a vertical-integration race, with platform operators pursuing upstream control over proprietary credit scoring data to escape commodity-margin positioning.
For Market Incumbents: Deploy merchant exclusivity agreements to lock in high-volume retail partnerships before bank-affiliated competitors retrofit installment features. Acquire specialized engineering teams with expertise in Canadian alternative credit scoring to defend against fintech-native entrants exploiting open banking data streams. The threat of deposit-funded substitution from traditional banks demands accelerated product differentiation.
For New Entrants and Emerging Players: Capture elective healthcare and dental verticals across Ontario and Quebec where deferred payment options align with uninsured procedure demand. The most penetrable segment sits with small business trade credit digitization, offering white-space expansion beyond saturated consumer retail. A go-to-market angle anchored in AI-powered shopping personalization can transcend pure price competition against established checkout platforms.
For Investors and Strategic Acquirers: Re-rating potential sits with algorithmically-native platforms given the convergence of machine learning recommendation engines with embedded checkout financing. Long-term viability favors specialists with direct merchant API integration and proprietary underwriting data assets accumulated across provincial regulatory regimes. Watch for federal open banking implementation timelines as the critical inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Merchant API Integration | Direct checkout embedding with Toronto and Vancouver e-commerce platforms reduces acquisition friction for Gen Z conversion. |
| Alternative Credit Scoring Investment | Open banking data pipelines expand approval access for thin-file applicants previously excluded by bureau-dependent models. |
| Provincial Licensing Expansion | Registration across Ontario, British Columbia, Alberta, and Quebec regulatory regimes creates defensive moats against regional competitors. |
| AI-Powered Personalization Layer | Machine learning recommendation engines differentiate shopping experiences beyond commodity installment functionality. |
| Healthcare Vertical Penetration | Elective medical and dental merchant partnerships capture underpenetrated categories with procedure-aligned financing demand. |
Research Methodology
Multi-period observation of transaction volume trajectories, merchant partnership announcements, and regulatory disclosure patterns anchored the trend analysis, supplemented by interviews with platform engineering leads, merchant integration specialists, and provincial compliance officers. Secondary validation drew from Financial Consumer Agency of Canada guidance documents, Office of the Superintendent of Financial Institutions bulletins, provincial consumer protection filings, and e-commerce sector trade data. Bottom-up transaction modeling and top-down market sizing were triangulated to produce consistent volume and value outputs.
Input-output matrix framing structured the analytical approach, with demand-side drivers feeding through payment method adoption curves, customer demographic penetration rates, and merchant vertical expansion patterns across the projection horizon. Segmentation dimensions modeled include payment rail type, generational cohort, service structure, and merchant channel. CAGRs were derived from regression analysis of historical adoption velocities calibrated to regulatory inflection points. Industry-specific forecast inputs incorporated open banking implementation phasing and provincial licensing cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal consumer protection rulemaking and competitive entry by bank-affiliated platforms. Forecasts reflect assumptions about merchant fee sustainability and Gen Z debit-preference persistence without guarantee of realization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Sweden POS Terminals Market
Payments
United States POS Terminals Market
Payments
Online Charging System (OCS) Market
Payments
Electronic Payment Processing Software Market
Payments
Transit Cards Market
Payments
Transaction Monitoring Market
Payments
Italy Gift Cards Market
Payments
Global Telecom Billing Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Payment Processing Solutions Market
Payments
Egypt Mobile Payments Market
Payments
Asia-Pacific Payments Market
Payments
India POS Terminals Market
Payments
Global Virtual Cards Market
Payments
Malaysia Payments Market
Payments
APAC Mobile Payments Market