
 LAMEA Payment Gateway Market | 2026-2036
LAMEA Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Payment Gateway Market Insights
Modular API-first bundling is restructuring how merchants select payment infrastructure across LAMEA markets. Stripe leverages developer-centric toolkits to anchor its position among mid-market SaaS platforms in the region. PayPal Holdings, Inc. sustains brand recognition through consumer trust mechanisms that reduce checkout abandonment. Adyen N.V. competes on unified commerce rails that process online and in-person transactions through single integrations.
A payment gateway is a technology layer that encrypts, routes, and authorizes financial transactions between merchants and acquiring banks using tokenization protocols and PCI-DSS compliance architectures. Its primary commercial purpose is to reduce fraud exposure while enabling real-time settlement across multiple payment instruments. E-wallet integration now leads transaction volume growth as unbanked populations in LAMEA markets bypass traditional card networks. Hosted solutions retain dominance among small retailers lacking internal technical capacity, while API deployments capture enterprise-grade demand from multi-channel e-commerce operators. Bank transfer modalities gain structural traction where real-time settlement networks from central banks reduce intermediary costs.
Brazil's central bank instant payment system and South Africa's Financial Sector Conduct Authority standards shape product certification requirements across the LAMEA corridor. Nigeria's central bank digital currency directives and data localization mandates from national regulators further constrain cross-border architecture choices. Stakeholders must monitor how fragmented national licensing regimes affect platform scalability before committing to regional hub strategies.
Market Dynamics
Brazil's instant payment infrastructure and Nigeria's central bank digital currency directives are compressing settlement timelines and forcing platform architectures toward real-time processing standards across the LAMEA corridor.
Growth Catalysts
- E-wallet penetration:Unbanked populations in Nigeria and Kenya bypass card networks through mobile money rails, expanding addressable transaction volumes for gateway providers.
- Brazil's PIX framework:The central bank's instant payment mandate reduces intermediary friction and drives merchant migration from batch-processed legacy systems.
- SaaS platform bundling:Mid-market software vendors embed payment acceptance as a native feature, expanding gateway distribution without direct merchant acquisition costs.
Market Restraints
- Data localization mandates:Nigeria's central bank and South Africa's Financial Sector Conduct Authority require domestic server deployment, fragmenting cloud infrastructure economics.
- Currency volatility exposure:Argentine peso and Nigerian naira fluctuations force gateways to absorb hedging costs or pass them to merchants, compressing net revenue per transaction.
- Interchange rate compression:Central bank caps on merchant discount rates in Brazil and Mexico limit revenue pools available to platform operators.
Strategic Opportunities
- Cross-border B2B settlements:SME importers in Colombia and Chile seek dollar-denominated invoice financing integrated with payment acceptance.
- Regulatory sandbox access:South Africa's financial conduct authority permits limited-scale testing of crypto-linked settlement rails before full licensing.
- Offline-to-online convergence:Brazilian retail chains demand unified reconciliation across PIX-enabled POS terminals and e-commerce checkouts through single API integrations.
Industry Challenges
- PCI-DSS certification timelines:Annual compliance audits for Level 1 service providers stretch 6-9 months, delaying product launches in competitive windows.
- Legacy core banking integration:Mexican and Argentine commercial banks maintain proprietary messaging protocols that require custom middleware development per institution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Payment Gateway Market |
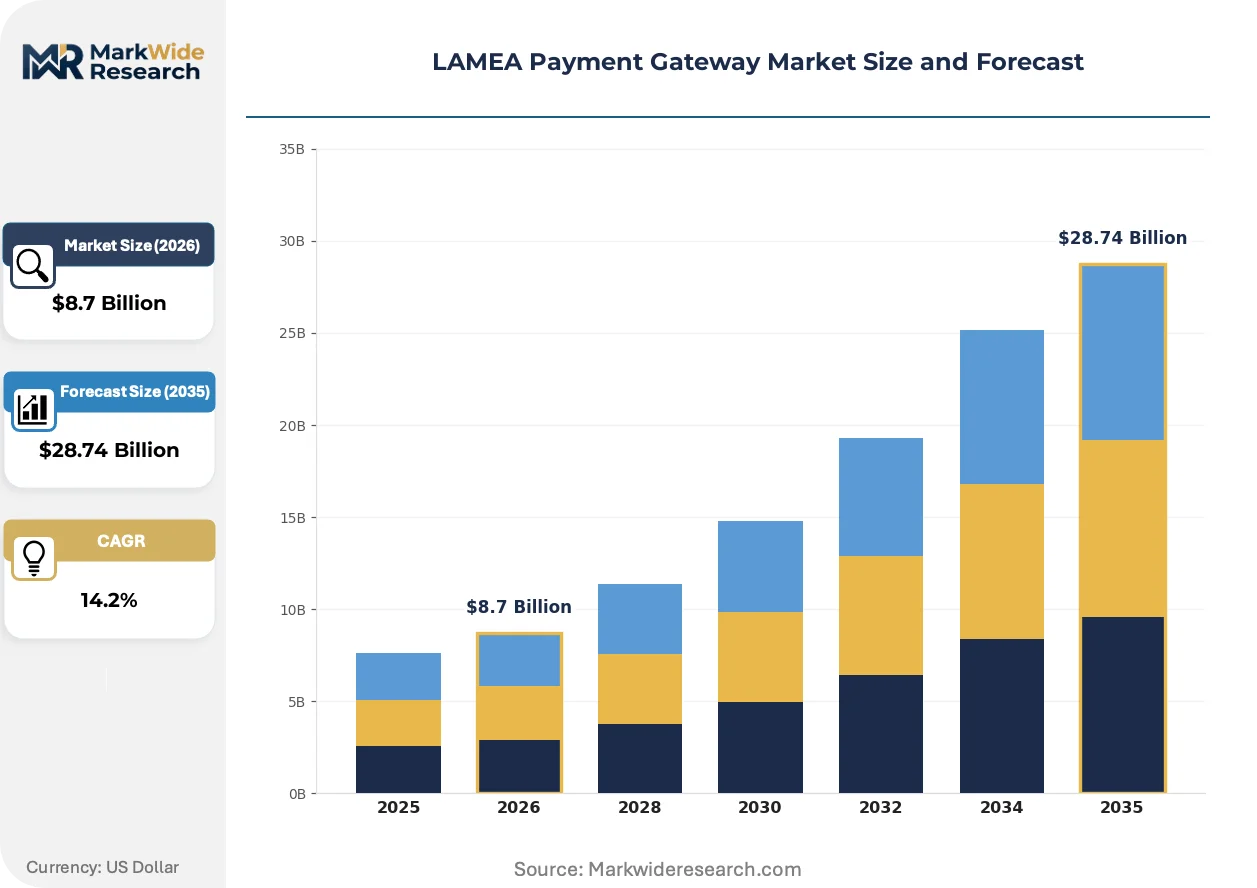
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Integration Type: Hosted, API, On-Premise, Plug-in Transaction Size: Small, Medium, Large, Enterprise End User: Retailers, E-Commerce, Service Providers, Nonprofits |
| Companies Covered | Visa, Inc., PayPal Holdings, Inc., Stripe, Inc., JPMorgan Chase & Co., Amazon.com, Inc., Adyen N.V., Worldline, Naspers Limited, BitPay, Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Payment Gateway Market Trends and Innovations
Payment orchestration layers and embedded finance architectures are dissolving traditional boundaries between acceptance, lending, and treasury functions across Latin American and African merchant bases.
Tokenization vaults with network-agnostic credential storage are unifying fraud management across card, account-to-account, and wallet rails. Large marketplace operators in Brazil and Nigeria deploy these systems to reduce PCI scope while enabling one-click checkout across multiple funding sources. The technology is unifying previously siloed risk engines into single decisioning platforms that cut false-decline rates.
South Africa's Financial Sector Conduct Authority has issued conduct standards for payment service providers that mandate disclosure of total cost of acceptance. The regulation forces platforms to unbundle interchange, scheme fees, and gateway margins in merchant statements. Enterprise retailers are responding by renegotiating contracts and demanding interchange-plus pricing structures.
Merchant procurement of payment infrastructure now favors outcome-based contracts tied to authorization rate guarantees rather than flat per-transaction fees. Mid-market e-commerce operators in Mexico and Colombia select vendors based on guaranteed uptime and fraud loss absorption. This shift concentrates contract awards among platforms with captive risk scoring capabilities and balance sheet capacity to underwrite performance commitments.
LAMEA Payment Gateway Market Segmentation
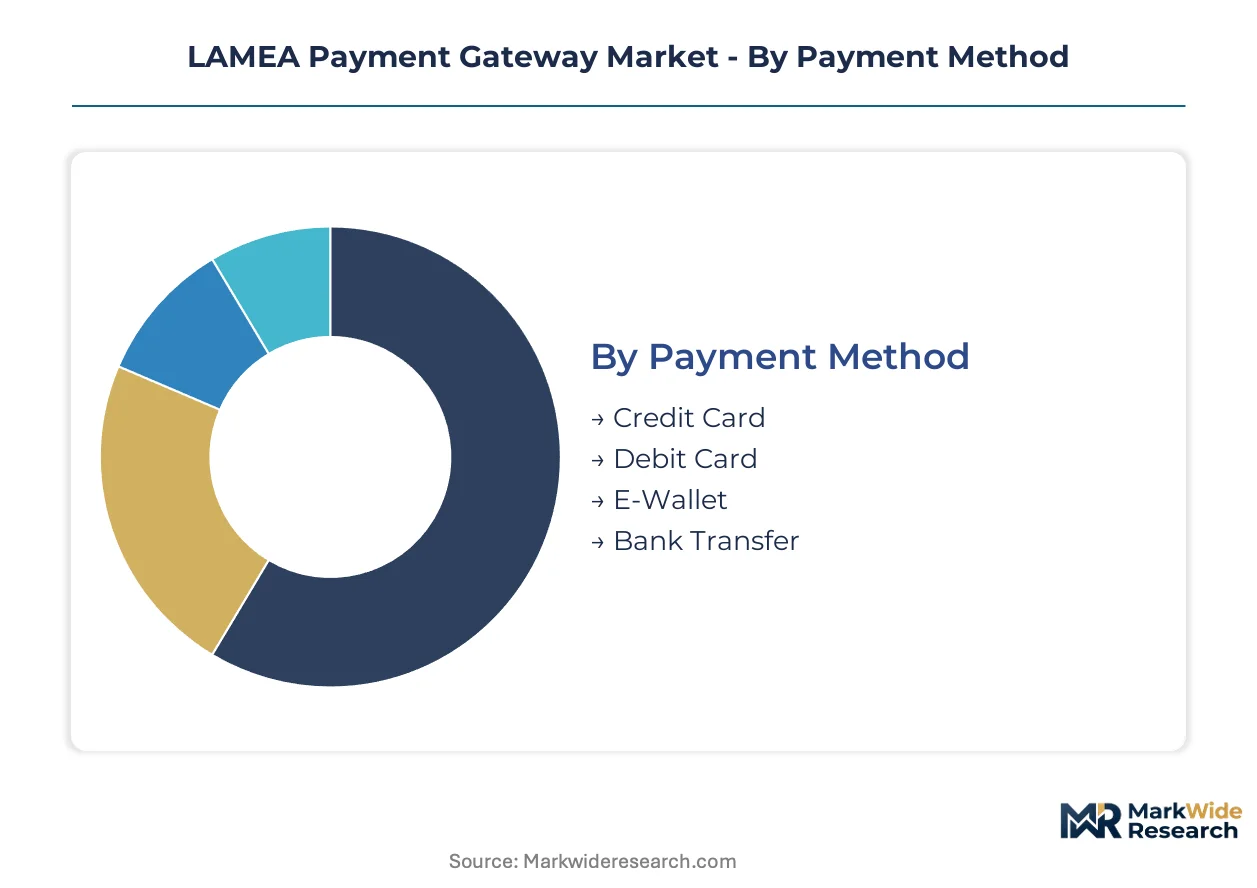
Payment gateway architectures in LAMEA markets fragment across technical integration modes, funding instruments, and merchant scale tiers. Each segmentation axis carries distinct capital requirements and regulatory exposure that reshape vendor economics across Brazil, Nigeria, and South Africa.
Payment Method:
Capital intensity concentrates in card network certification and tokenization infrastructure, with divergent compliance burdens across instrument types.
- Credit Card:PCI-DSS Level 1 certification demands dedicated hardware security modules and annual audit cycles spanning 6-9 months. Brazilian retailers and Nigerian hospitality operators drive volume concentration despite interchange rate caps compressing margins.
- E-Wallet:Mobile money rails require partnerships with telco-owned financial services rather than traditional banking infrastructure. Kenya's M-Pesa ecosystem and Nigeria's OPay network absorb the fastest merchant onboarding velocity as unbanked populations bypass card networks entirely.
- Debit Card:Real-time authorization through domestic switch networks reduces settlement risk exposure. South African retailers favor debit rails for lower merchant discount rates.
- Bank Transfer:PIX in Brazil and Nigeria's NIBSS Instant Payment layer displace card volume where central bank infrastructure enables account-to-account settlement.
Credit card rails absorb the bulk of transaction value; e-wallet penetration is expanding most quickly across frontier markets.
Integration Type:
Technical deployment models segment by internal engineering capacity, with hosted solutions minimizing upfront investment for merchant segments lacking dedicated IT resources.
- API:RESTful and GraphQL interfaces demand sandbox environments and dedicated developer relations teams. Mid-market SaaS platforms in Mexico and Colombia embed these layers to capture recurring revenue streams.
- Hosted:Redirect-based checkout flows eliminate PCI scope for small retailers. Argentine and Chilean merchants with limited technical staffing dominate adoption curves here.
- On-Premise:Dedicated server deployments satisfy Nigeria's central bank data localization mandates and South Africa's FSCA residency requirements.
- Plug-in:Pre-built modules for Shopify, WooCommerce, and Magento reduce time-to-revenue for solo entrepreneurs and micro-merchants.
Hosted solutions carry the widest installed base; API deployments are climbing the fastest as platform-native commerce expands.
Transaction Size:
Merchant scale tiers determine fraud management sophistication and interchange negotiation leverage, with enterprise segments commanding custom pricing architectures.
- Enterprise:Transaction volumes exceeding 6 million annually warrant dedicated relationship management and interchange-plus pricing structures. Brazilian retail chains and South African banking groups anchor this tier.
- Large:1-6 million annual transactions trigger tiered pricing and guaranteed uptime SLAs. Colombian marketplace operators concentrate here.
- Medium:100,000-1 million transactions attract platform attention through self-service onboarding with premium support tiers. Nigerian fintech startups populate this band.
- Small:Sub-100,000 transaction volumes rely on standardized flat-rate pricing with minimal customization. Kenyan agri-cooperatives and Argentine independent retailers dominate.
Enterprise merchants absorb the bulk of platform engineering resources; medium-tier accounts are gaining share fastest as SaaS bundling expands.
End User:
Vertical-specific compliance requirements and checkout complexity fragment procurement patterns, with e-commerce operators demanding the most sophisticated orchestration layers.
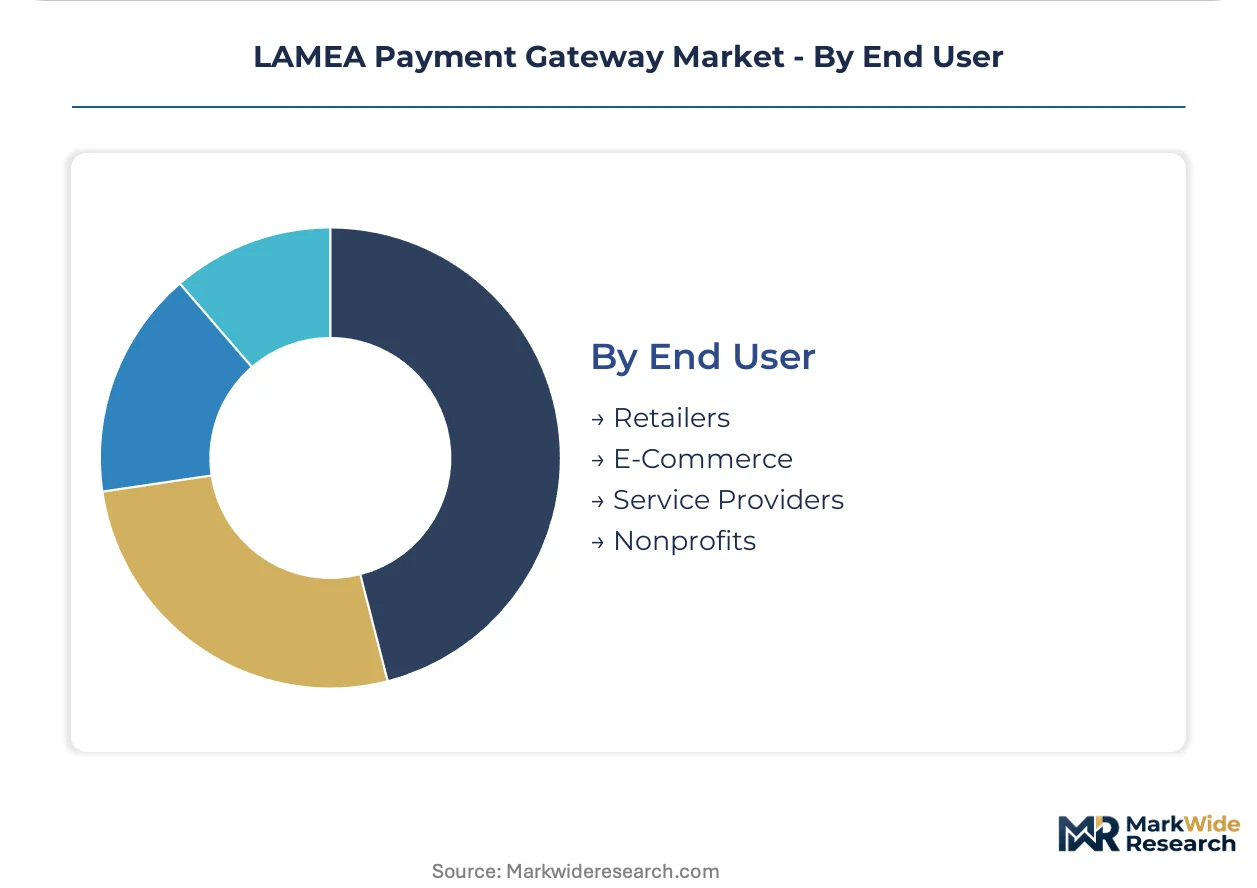
- E-Commerce:Multi-channel inventory synchronization and one-click checkout across mobile and desktop surfaces require tokenization vaults and network-agnostic credential storage. Brazilian marketplaces and Nigerian digital goods platforms anchor demand.
- Retailers:Unified reconciliation across POS terminals and online checkouts drives single-integration requirements. South African grocery chains and Mexican department stores lead unified commerce adoption.
- Service Providers:Recurring billing architectures and subscription management tools differentiate procurement criteria. Colombian SaaS vendors and Chilean professional services firms concentrate here.
- Nonprofits:Donation-specific features including recurring giving and donor management integration shape platform selection. Kenyan NGOs and Argentine charitable foundations populate this segment.
E-commerce operators command the deepest platform customization; service providers are expanding most quickly as subscription billing proliferates across LAMEA economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway infrastructure investment concentrates in payment-processing hubs while merchant demand spreads across secondary cities. Brazil absorbs the largest share of platform engineering resources. Nigeria and South Africa anchor African transaction volume growth.
Brazil
E-commerce marketplaces and retail chains drive PIX integration at scale. The central bank's instant payment mandate forces legacy system migrations and real-time architecture overhauls. São Paulo anchors fintech development clusters where gateway providers co-locate engineering teams near merchant headquarters.
Nigeria
Mobile money penetration among unbanked populations expands addressable transaction volumes for gateway operators. The central bank's digital currency directives and data localization mandates constrain cross-border cloud deployments. Lagos concentrates fintech startup density where OPay and similar platforms drive merchant onboarding velocity.
South Africa
Enterprise retailers and banking groups demand unified commerce rails across online and in-person channels. The Financial Sector Conduct Authority's conduct standards mandate fee unbundling and transparency in merchant statements. Johannesburg anchors corporate procurement decisions where interchange-plus pricing negotiations concentrate.
Mexico
Mid-market SaaS platforms embed payment acceptance as native features, expanding gateway distribution without direct merchant acquisition. The central bank's merchant discount rate caps compress revenue pools available to platform operators. Mexico City concentrates e-commerce operator headquarters where API-first procurement patterns dominate.
Colombia
SME importers seek dollar-denominated invoice financing integrated with payment acceptance. Regulatory sandboxes permit limited-scale testing of alternative settlement rails before full licensing. Bogotá anchors cross-border B2B demand where trade finance and payment orchestration converge.
LAMEA Payment Gateway Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the LAMEA corridor. The vendor base stratifies across three tiers: global payment networks with established brand recognition, regional fintech platforms with localized compliance expertise, and infrastructure-as-a-service providers with developer-centric toolkits. Strategic moves concentrate on regulatory sandbox access, data localization compliance, and API ecosystem expansion.
Among global network operators, Visa, Inc. and PayPal Holdings, Inc. occupy positions anchored by consumer trust mechanisms and established merchant relationships. Stripe, Inc. and Adyen N.V. exemplify the API-first archetype competing on unified commerce rails and developer experience. These four entities represent distinct strategic postures: network incumbents leveraging scale, platform specialists optimizing integration velocity, and orchestration layers unifying fragmented payment instruments.
| Leading Market Players |
|---|
| Visa, Inc. |
| PayPal Holdings, Inc. |
| Stripe, Inc. |
| JPMorgan Chase & Co. |
| Amazon.com, Inc. |
| Adyen N.V. |
| Worldline |
| Naspers Limited |
| BitPay, Inc. |
| Others |
Pricing and Supply Chain Analysis
Enterprise merchants in Brazil and South Africa command interchange-plus pricing negotiations that compress margins for gateway providers lacking scale. This buyer concentration forces platforms to absorb hedging costs on volatile currencies or surrender contract renewals to better-capitalized competitors.
Pricing Analysis
Cost compression in mid-market tiers reflects central bank caps on merchant discount rates across Brazil and Mexico. Pricing stratifies across enterprise, large, and small merchant tiers with volume scale and PCI-DSS certification level as primary differentiation drivers. Margin tightening accelerates because real-time settlement infrastructure reduces intermediary revenue pools. Small retailers exhibit highest price sensitivity while enterprise chains leverage guaranteed uptime SLAs for rate concessions.
Supply Chain Analysis
Engineering talent scarcity in São Paulo and Lagos constrains platform development velocity for API-first deployments. Supply concentration centers on cloud infrastructure providers in Ireland and Singapore, hardware security module manufacturers in Germany and the Netherlands, and fraud-scoring AI labs in Israel and the United States. The supply chain rests on semiconductor availability for encryption processors and fiber connectivity for low-latency authorization. Single-source vulnerability in tokenization vault software creates systemic risk. Distribution runs through direct enterprise sales teams and SaaS platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gateway infrastructure in LAMEA markets is consolidating around platforms with captive compliance expertise and balance sheet capacity to underwrite performance guarantees. Regulatory fragmentation and data localization mandates are forcing weaker players toward exit or acquisition.
For Market Incumbents: Extend PIX certification coverage and tokenization vault deployments to anchor enterprise renewals in Brazil. Deepen API ecosystem partnerships with mid-market SaaS platforms in Mexico and Colombia to capture distribution without direct merchant acquisition costs. Acquire regional fintechs with existing central bank licenses to shortcut Nigeria's data localization compliance timelines. For New Entrants and Emerging Players: Begin with hosted checkout solutions for Argentine and Chilean micro-merchants underserved by developer-centric incumbents. Target agri-cooperatives and independent retailers in Kenya where technical staffing constraints favor redirect-based flows. Pursue white-label partnerships with telco-owned mobile money operators to bypass card network certification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with existing FSCA or central bank licenses in Johannesburg and Lagos. Platforms with proven NIBSS Instant Payment integration and PIX switch connectivity offer strongest long-term viability as real-time settlement becomes mandatory. Watch for merchant discount rate cap announcements as inflection signals for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Access | South Africa's FSCA permits crypto-linked settlement testing before full licensing. |
| API Ecosystem Expansion | GraphQL and RESTful interfaces embed payment acceptance into SaaS platforms natively. |
| Data Localization Compliance | Domestic server deployments satisfy Nigeria's central bank and South Africa's FSCA mandates. |
| Tokenization Vault Deployment | Network-agnostic credential storage reduces PCI scope for Brazilian marketplace operators. |
| Cross-Border B2B Settlement | Dollar-denominated invoice financing integrates with payment acceptance for Colombian importers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with payment platform CTOs, central bank policy officers, merchant acquiring heads, and SaaS integration specialists validated demand-side assumptions. SEC 10-K disclosures, Brazil's Banco Central regulatory circulars, and South Africa's FSCA conduct standard publications provided secondary triangulation. Bottom-up transaction volume estimates and top-down GDP-linked payment penetration rates were reconciled across modeling approaches.
Granularity-level modeling deployed payment method, integration type, transaction size tier, and end-use vertical as core segmentation dimensions. CAGRs were derived from regression analysis against e-commerce penetration curves and real-time payment infrastructure deployment schedules. Authorization rate benchmarks and fraud loss ratios informed revenue-per-transaction assumptions across the projection horizon.
Central bank rate cap announcements, currency volatility spikes, and PCI-DSS certification delays are the dominant revision risks. Forecasts reflect documented assumptions regarding PIX adoption velocity and mobile money merchant onboarding rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China Real Time Payments Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Spain Real Time Payments Market
Payments
Mobile Wallet Market
Payments
Asia-Pacific Payments Market
Payments
United Kingdom Real Time Payments Market
Payments
Spain Mobile Payment Market
Payments
Voice-Based Payments Market
Payments
Malta POS Terminal Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Electronic Payment System for Transportation Market
Payments
Brazil Real Time Payments Market
Payments
GCC Mobile Payment Market
Payments
Singapore Payments Market
Payments
Wearable Payments Market
Payments
Payment Analytics Software Market