
 Mobile Fuel Storage Tank Market | 2026-2036
Mobile Fuel Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Fuel Storage Tank Market Analysis
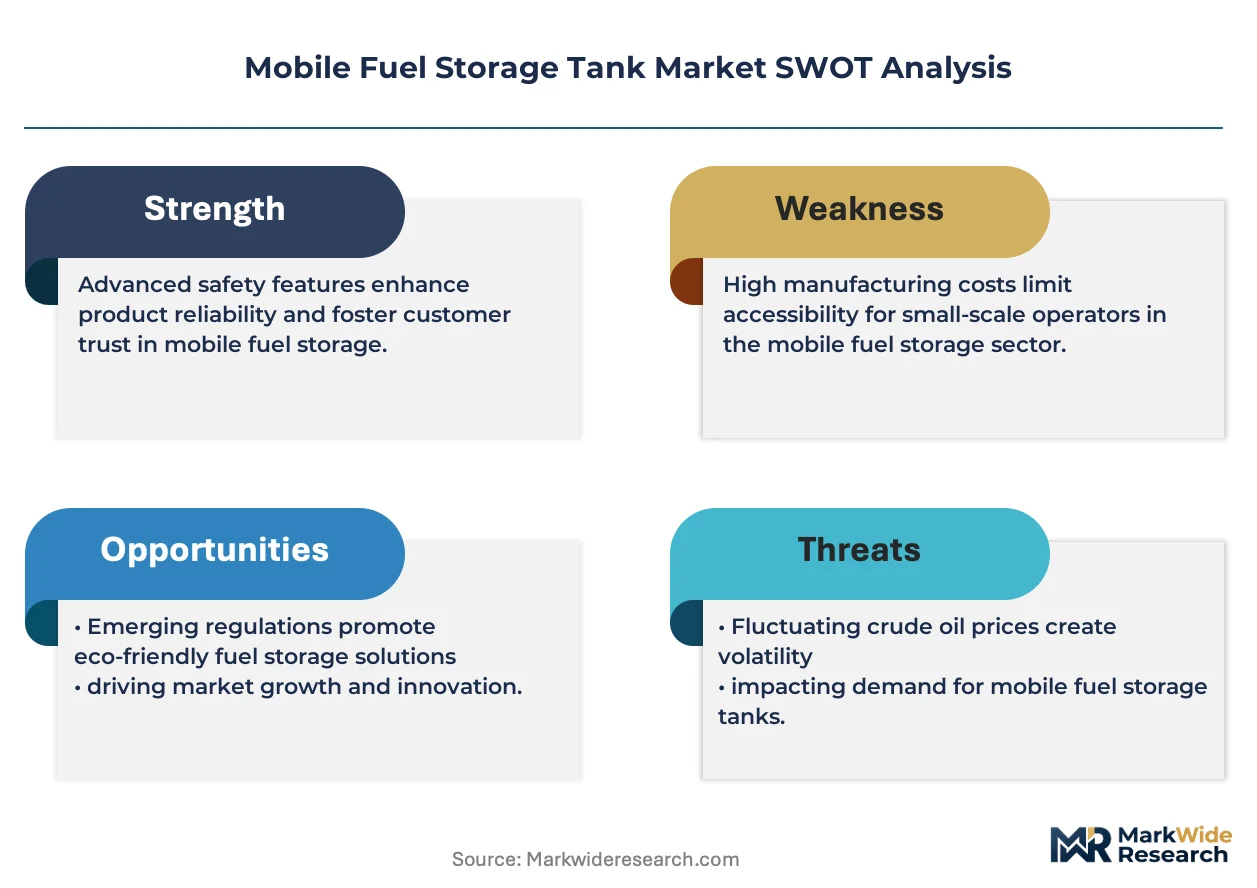
A widening capital-intensity gap between integrated fabricators and regional assemblers is unwinding competitive stability across the mobile fuel storage tank sector. Western Global leverages its transatlantic manufacturing footprint to sustain pricing power in above-ground portable systems. CST Industries anchors its position through captive steel-coating technology that extends tank life cycles in corrosive environments. Guardian Tanks differentiates via specialized rectangular tank geometries purpose-built for constrained construction sites.
Mobile fuel storage tanks are self-contained vessels engineered for temporary or relocatable fuel containment, typically fabricated from carbon steel, stainless steel, or polyethylene with capacities spanning hundreds to tens of thousands of gallons, designed for DOT-compliant highway transport and on-site dispensing without permanent infrastructure. Above ground tanks dominate current fabrication volumes due to lower installation costs and simplified EPA spill prevention compliance, while portable tank configurations are capturing accelerated interest from logistics operators managing distributed fleet refueling. Diesel remains the most demanded fuel type across end-use categories, though biofuel-compatible tank linings are emerging as a margin-rich specialization as blend mandates proliferate.
EPA's Spill Prevention, Control, and Countermeasure rules and DOT's hazardous materials transport codes govern tank design, fabrication certification, and operational deployment across the United States, compelling manufacturers to integrate secondary containment and overfill prevention as standard rather than optional features. OSHA workplace safety standards further constrain field installation protocols, particularly for temporary construction-site deployments. Stakeholders must weigh fabrication compliance investments against the contracting window for legacy single-wall tank replacements.
Market Dynamics
Double-walled fabrication mandates from EPA and DOT are compressing margins for single-wall legacy producers while accelerating replacement cycles across construction and mining fleets.
Growth Catalysts
- Remote Site Fuel Logistics:Mining operators across Western Australia and agricultural contractors in the US Great Plains are procuring portable diesel tanks to eliminate downstream refueling downtime.
- EPA SPCC Rule Stringency:Secondary containment requirements for above-ground storage are compelling fleet managers to retire aging single-wall assets ahead of schedule.
- Biofuel Blend Mandates:State-level renewable fuel standards in California and Oregon are creating demand for specialized tank linings compatible with B20 and higher ethanol blends.
Market Restraints
- Steel Price Volatility:Carbon steel coil costs fluctuate with scrap metal indices, squeezing fabrication margins for mid-tier assemblers without captive rolling capacity.
- Fabrication Concentration Risk:Double-walled tank production clusters in Texas and Louisiana, exposing lead times to Gulf Coast weather disruptions.
- Transport Weight Limits:DOT highway weight restrictions constrain maximum tank capacities for portable configurations, capping per-unit revenue for manufacturers.
Strategic Opportunities
- Modular Tank Farms:Interconnectable above-ground systems are penetrating data center backup power installations where space constraints favor scalable footprints.
- EU Green Deal Alignment:Renewable diesel compatibility certifications open procurement channels for European construction contractors facing Scope 3 emissions targets.
- Rental Channel Expansion:Equipment rental houses are adding fuel storage to bundled offerings, displacing direct sales for short-duration construction projects.
Industry Challenges
- Welder Certification Bottlenecks:ASME Section IX-qualified pressure vessel welders command premium wages, extending production backlogs for double-walled units.
- Cross-Border Compliance Friction:DOT UN31A certification for transportable tanks requires retesting for Canadian TDG compliance, fragmenting North American distribution.
- Legacy Fleet Integration:New EPA-compliant tanks often interface poorly with existing single-wall dispensing infrastructure, forcing ancillary equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Fuel Storage Tank Market |
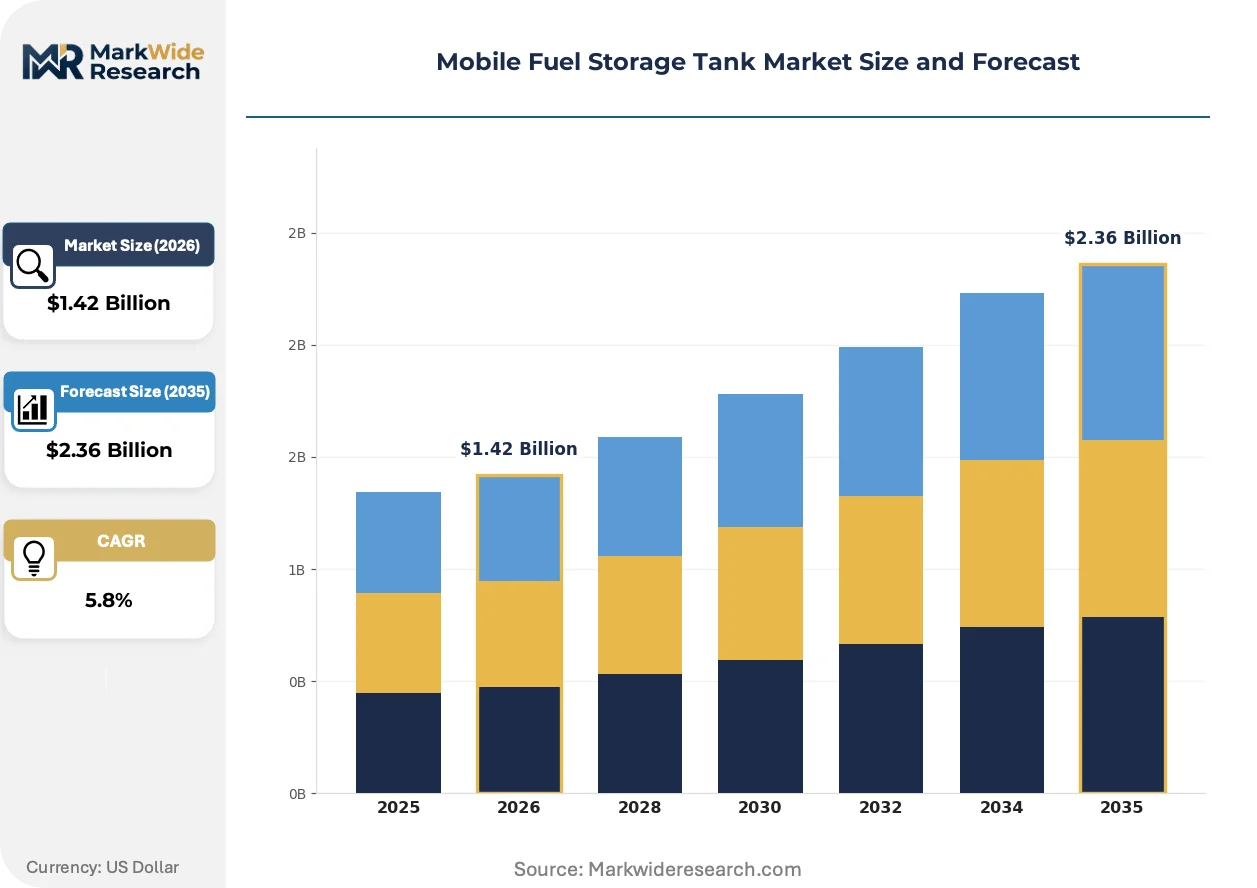
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground Tanks, Below Ground Tanks, Portable Tanks, Rectangular Tanks Fuel Type: Diesel, Gasoline, Aviation Fuel, Biofuels End User: Agriculture, Construction, Logistics, Emergency Services Installation Type: Mobile Units, Fixed Units, Temporary Installations, Permanent Installations |
| Companies Covered | Air Liquide, GEI Works, Western Global, Transitank Group, CST Industries, Guardian Tanks, Rain for Rent International UK, Morrow Industries, Westeel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Fuel Storage Tank Market Emerging Trajectories
Fabrication technology and regulatory stringency are converging to reshape tank design priorities, with material substitution and compliance automation emerging as decisive competitive differentiators.
Polyethylene double-wall construction is supplanting carbon steel in sub-500-gallon portable tanks for landscaping and light construction fleets. These rotational-molded units slash empty weight by sixty percent, enabling smaller tow vehicles and reducing DOT bridge formula complications. The shift is compressing order backlogs for steel fabricators while opening rental channel penetration for polymer specialists.
EPA's 2024 SPCC guidance clarifications are mandating continuous electronic leak detection for bulk storage exceeding threshold volumes. Tank OEMs are integrating fiber-optic sensor arrays as standard features, passing certification costs to buyers but reducing insurance premiums for high-volume operators. California Air Resources Board is mirroring these provisions, creating a de facto national standard for emission-sensitive jurisdictions.
Equipment-as-a-service contracting is displacing outright purchase for construction fleets managing distributed job sites. Rental providers bundle tank delivery, fuel monitoring, and compliance documentation into monthly rates, capturing maintenance revenue streams previously lost to third-party service shops. This model concentrates most visibly in Texas shale plays and Florida infrastructure corridors where project durations resist capital deployment.
Mobile Fuel Storage Tank Market Segmentation
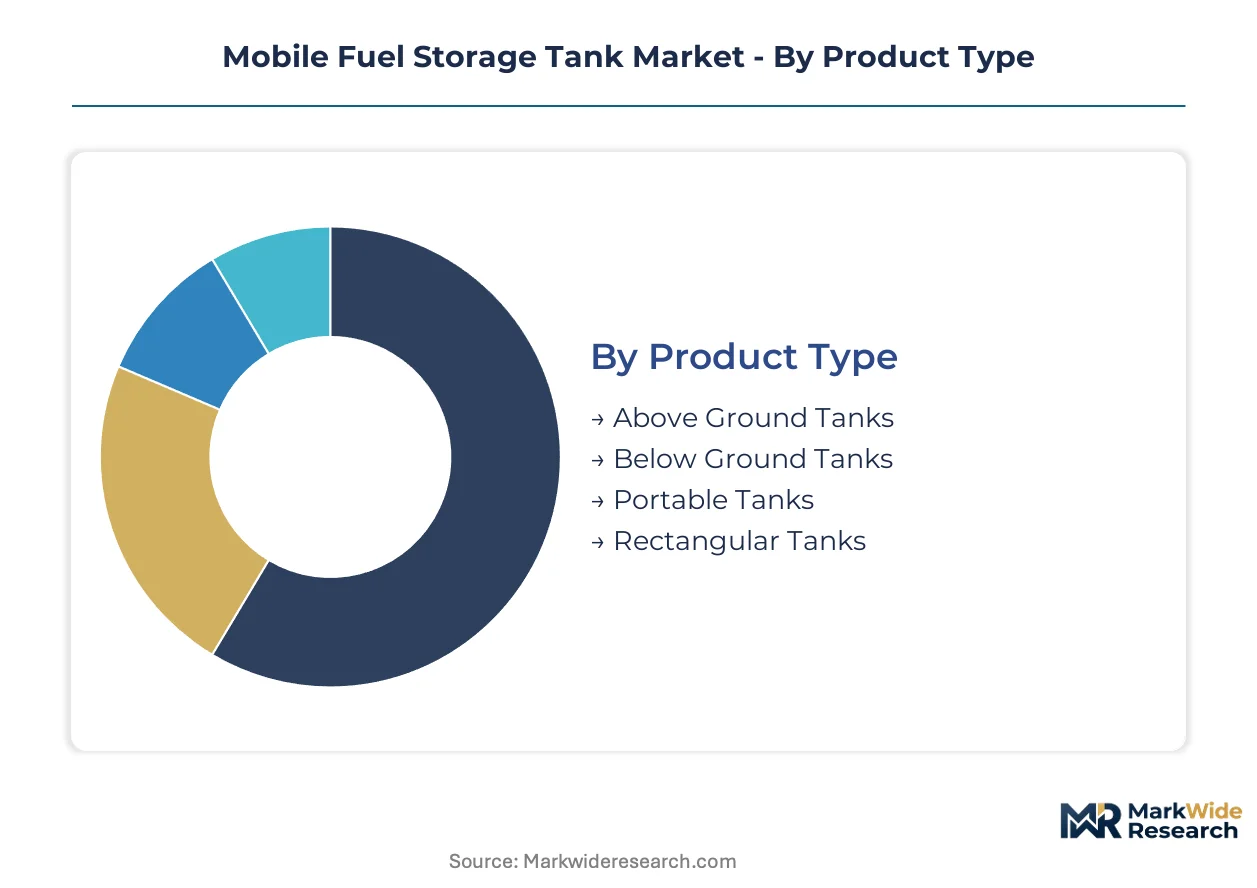
Segmentation in mobile fuel storage tanks exposes where fabrication complexity, regulatory compliance burdens, and fleet procurement patterns concentrate margin capture. Product geometry and fuel compatibility specifications create divergent competitive arenas that reward specialized engineering over commodity volume.
Product Type:
Margin pools concentrate in double-walled portable configurations where DOT certification and EPA secondary containment requirements erect fabrication barriers.
- Above Ground Tanks:These vessels dominate fabrication volumes through simplified spill prevention compliance and lower site preparation costs. Construction fleets across Texas and Louisiana corridors are accelerating procurement of skid-mounted above-ground systems as project timelines compress and permanent infrastructure investments become untenable.
- Portable Tanks:DOT UN31A-certified transportable units command premium pricing through integrated dispensing systems and highway-legal chassis designs. Mining operators in Western Australia and agricultural contractors across the US Great Plains are eliminating downstream refueling downtime through on-site portable diesel deployment.
- Below Ground Tanks:Buried installations require extensive excavation and cathodic protection systems, limiting adoption to permanent industrial facilities with space constraints.
- Rectangular Tanks:Specialized geometries optimize cubic capacity within constrained construction site footprints, differentiating fabricators serving urban infrastructure corridors.
Above Ground Tanks hold installed capacity. Portable Tanks is rotating up the share rankings.
Fuel Type:
Application-driven compatibility requirements split the market between established hydrocarbon specifications and emerging biofuel-resistant lining technologies.
- Diesel:The dominant fuel category across all end-use segments, with tank specifications standardized around ASTM D975 compatibility and cold-weather flow properties. Remote mining and agricultural logistics in Australia's Pilbara region and the US Midwest sustain concentrated demand for high-capacity diesel storage.
- Biofuels:B20 biodiesel and ethanol blends above E10 require specialized elastomer linings and corrosion-resistant coatings that command 15-25% fabrication premiums. California and Oregon state-level renewable fuel standards are creating margin-rich specialization opportunities for certified fabricators.
- Gasoline:Vapor recovery mandates and Reid Vapor Pressure compliance constrain tank design for retail and fleet applications.
- Aviation Fuel:Jet A and Avgas storage demands stringent water separation and filtration integration, limiting qualified fabricators to aviation-certified specialists.
Diesel anchors current revenue. Biofuels is climbing the fastest as blend mandates proliferate across coastal states.
End User:
Procurement scale and replacement frequency create divergent customer economics across sector-specific deployment patterns.
- Construction:Project-based demand cycles favor rental channel penetration and temporary installation configurations. Florida infrastructure corridors and Texas shale plays are concentrating equipment-as-a-service contracting for distributed job site fuel logistics.
- Agriculture:Seasonal harvest windows drive peak procurement of portable tanks for field refueling of combines and tractors across the US Great Plains and Australian wheat belts.
- Logistics:Fleet operators managing distributed truck terminals prioritize interconnectable above-ground systems with automated fuel monitoring.
- Emergency Services:Disaster response agencies require rapid-deployment specifications with self-contained pumping and filtration for grid-independent operations.
Construction commands replacement velocity. Agriculture maintains seasonal volume concentration.
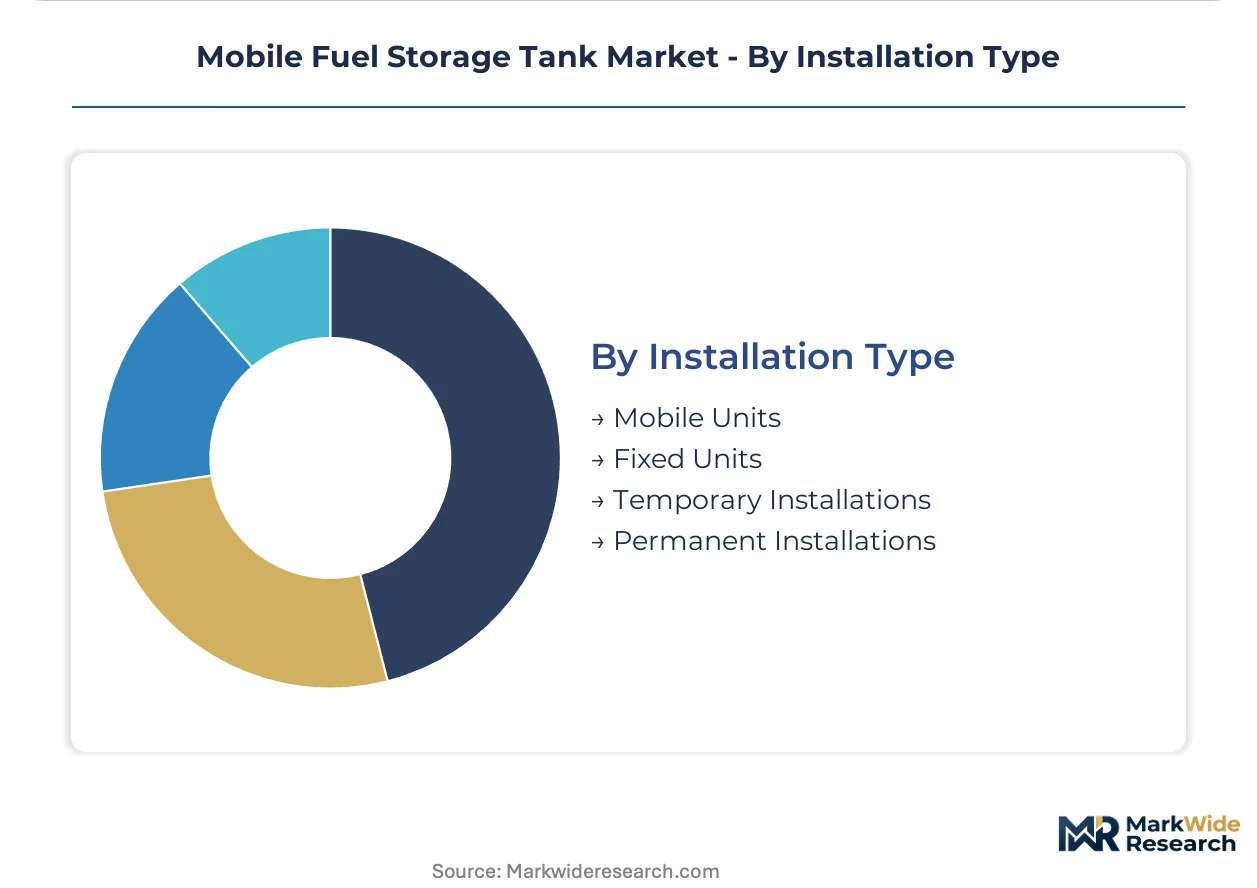
Installation Type:
Mobility specifications determine regulatory jurisdiction and insurance classification, with mobile units capturing accelerated interest from fleet operators.
- Mobile Units:Highway-transportable configurations with integrated chassis and braking systems face DOT weight restrictions that cap per-unit capacity. Equipment rental houses in North American shale regions are bundling mobile tank delivery with compliance documentation into monthly service rates.
- Temporary Installations:Semi-permanent above-ground deployments for construction projects under 24 months avoid capital depreciation while satisfying EPA SPCC secondary containment mandates ahead of schedule.
- Fixed Units:Permanently anchored installations serve industrial facilities with predictable fuel consumption profiles and long-term site control.
- Permanent Installations:Below-ground or substantial above-ground infrastructure with 20+ year depreciation horizons dominate utility and municipal procurement.
Fixed Units retain legacy base. Mobile Units is gaining share fastest through rental channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Australia's mining corridors demonstrate the lowest price elasticity, absorbing premium fabrication costs for corrosion-resistant specifications, while agricultural contractors across the US Great Plains negotiate aggressively on per-gallon storage economics.
United States
Construction fleets in Texas and Louisiana shale plays are accelerating procurement of skid-mounted above-ground systems as project timelines compress. EPA's Spill Prevention, Control, and Countermeasure rules mandate secondary containment for bulk storage, compelling fleet managers to retire aging single-wall assets. Houston-Galveston fabrication clusters concentrate double-walled tank production, exposing lead times to Gulf Coast weather disruptions.
Australia
Mining operators across Western Australia's Pilbara region are eliminating downstream refueling downtime through on-site portable diesel deployment. The country's national environmental regulator enforces strict spill prevention protocols for remote site fuel logistics. Perth-based equipment distributors are bundling tank delivery with compliance documentation into monthly service rates.
Germany
Construction contractors facing Scope 3 emissions targets are procuring renewable diesel-compatible tank systems. EU Green Deal alignment requirements and REACH chemical safety standards govern fabrication certification for transportable units. Industrial fabricators in North Rhine-Westphalia are specializing in modular interconnectable systems for data center backup power installations.
Canada
Agricultural contractors across the Prairie Provinces are deploying portable tanks for seasonal field refueling of combines and tractors. Transport Canada TDG compliance requires retesting of DOT-certified units, fragmenting North American distribution channels. Calgary-based rental houses are expanding fuel storage into bundled equipment offerings.
United Arab Emirates
Data center developers in Dubai and Abu Dhabi are specifying scalable above-ground tank farms for backup power redundancy. The country's federal environmental authority mandates spill prevention systems for bulk fuel storage in industrial zones. Sharjah fabrication facilities are capturing regional demand for rectangular tank geometries optimized for constrained urban footprints.
Mobile Fuel Storage Tank Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the mobile fuel storage tank sector. Integrated fabricators with captive steel-coating capabilities command premium positioning in corrosive-environment applications, while regional assemblers compete on delivery velocity for standard portable configurations. The vendor base separates into three strategic archetypes: transatlantic-scale specialists with multi-plant footprints, corrosion-technology anchor firms with proprietary coating systems, and geometry-focused niche players serving constrained-site deployments. Dominant competitive moves include backward integration into raw material supply and rental channel partnerships that displace direct sales for short-duration projects.
Among transatlantic-scale fabricators, Western Global and CST Industries exemplify divergent technology-cost positioning. Western Global leverages its multi-continental manufacturing footprint to sustain pricing power in above-ground portable systems. CST Industries anchors the corrosion-resistance tier through proprietary steel-coating technology that extends tank life cycles. Guardian Tanks occupies the geometry-specialist position, with rectangular tank configurations purpose-built for constrained construction sites. Rain for Rent International UK represents the rental-channel archetype, bundling fuel storage into equipment-as-a-service contracting models.
| Leading Market Players |
|---|
| Air Liquide |
| GEI Works |
| Western Global |
| Transitank Group |
| CST Industries |
| Guardian Tanks |
| Rain for Rent International UK |
| Morrow Industries |
| Westeel |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between mining operators and fabricators lock in both carbon steel coil supply and price visibility across the analysis window. These agreements insulate procurement teams from scrap metal index volatility while committing fabricators to volume floors that shape capacity planning.
Pricing Analysis
After-sales service revenue from leak detection maintenance and recertification drives lifetime value for tank OEMs. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA SPCC compliance grade and DOT UN31A certification status. Pricing pressure stems from polyethylene substitution in sub-500-gallon portable segments. Agricultural contractors across the US Great Plains demonstrate highest price sensitivity, while Australian mining operators absorb corrosion-resistant fabrication premiums.
Supply Chain Analysis
Texas and Louisiana anchor double-walled tank fabrication through Houston-Galveston manufacturing clusters. Raw material draws from domestic carbon steel coil producers, rotational-molding resin suppliers, and cathodic protection system vendors. Single-source vulnerability concentrates in ASME Section IX-qualified welder pools. Distribution runs through equipment rental houses and direct OEM sales to fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from rotational-molded polyethylene tanks displacing carbon steel in light construction segments. Defense requires securing fabrication capabilities that polymer competitors cannot replicate.
For Market Incumbents: Secure captive steel-coating technology to extend tank life cycles in corrosive environments against polyethylene substitution. Lock in ASME-certified welder pipelines through apprenticeship partnerships to relieve production bottlenecks. Prioritize EPA SPCC pre-certification investments that rental channels demand for bundled service offerings. For New Entrants and Emerging Players: Lead with biofuel-compatible lining specializations for B20 and higher ethanol blends in California and Oregon markets. Target data center backup power installations where modular interconnectable systems address space constraints. Partner with equipment rental houses for equipment-as-a-service channel access. For Investors and Strategic Acquirers: Capital is best deployed toward corrosion-technology anchor firms with proprietary coating systems and transatlantic manufacturing footprints. Long-term viability hinges on regulatory compliance automation capabilities. Watch for EPA electronic leak detection mandate expansion as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coating | CST Industries' proprietary technology extends tank life cycles in Pilbara mining conditions. |
| Rental Channel Partnership | Rain for Rent bundles fuel storage into monthly rates displacing direct sales. |
| Biofuel Compatibility Certification | California CARB provisions create margin-rich specialization for certified fabricators. |
| Modular Tank Farm Expansion | Interconnectable systems penetrate data center backup power in Dubai and Abu Dhabi. |
| ASME Welder Pipeline Development | Certified pressure vessel welders command premium wages extending production backlogs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers, EPA compliance officers, equipment rental channel heads, and fabrication plant engineers. Secondary validation drew from EPA SPCC guidance documents, DOT hazardous materials transport codes, SEC filings of listed tank manufacturers, and customs trade data on carbon steel coil imports. Bottom-up unit economics triangulated against top-down market sizing across product type, fuel compatibility, and end-use segments.
Across the analysis window, volume and value outputs reflect modeled projections through segmented demand curves and replacement cycle assumptions. Segmentation dimensions span product geometry, fuel type specifications, installation mobility class, and regional regulatory clusters. CAGRs were derived from historical procurement patterns and forward-looking fleet expansion schedules. Industry-specific inputs include mining production forecasts from Western Australia's Pilbara region and construction project pipelines across Texas shale plays.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement stringency or prolonged steel price volatility would require recalibration. Forecasts reflect assumptions around double-walled mandate adoption timelines and biofuel blend mandate geographic expansion. Recalibration cycles align with material shifts in SPCC guidance clarifications and DOT transport code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Anthracite Coal Mining Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
High-Temperature Industrial Burner Market
Fuels
North America Aviation Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
Diesel As Fuel Market
Fuels
Liquefied Helium Tanks Market
Fuels
United States Bunker Fuel Market
Fuels
Briquette Market
Fuels
Fuel Quality Testing Market
Fuels
Global Chemical Logistics Market
Fuels
China LNG Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
India City Gas Distribution (CGD) Market