
 Briquette Market | 2026-2036
Briquette Market Size, Share, and Industry Trends Forecast 2026-2036
Briquette Market Intelligence
Direct procurement contracts between briquette producers and industrial energy buyers are reshaping how fuel-grade compressed biomass reaches power plants and metallurgical facilities. Enviva leverages long-term offtake agreements with European utilities to sustain volume commitments across Atlantic shipping routes. Drax Group plc anchors its position through in-house pellet and briquette production integrated with converted coal-fired generation capacity. Pfeifer Group differentiates via vertical integration from sawmill residue collection through finished wood briquette distribution in Central European heating markets.
A briquette is a compressed block of combustible material, typically measuring 50-150 mm in diameter and formed under pressures exceeding 100 MPa without chemical binders, designed for controlled combustion in industrial boilers, residential stoves, and metallurgical processes. Biomass briquettes derived from agricultural residues and wood waste command expanding share as coal substitution accelerates in EU power generation and district heating systems. Charcoal briquettes retain dominance in recreational cooking and emerging-market household energy, though margin pools are shifting toward industrial-grade wood briquettes certified for automated stoker systems. Coal briquettes face structural decline outside legacy steel and cement applications where blend consistency requirements persist.
The EPA enforces emissions thresholds for industrial solid fuel combustion under the Clean Air Act, while the EU Green Deal and F-Gas Regulation tighten carbon intensity benchmarks for imported biomass fuels. India's MNRE mandates BIS certification for biomass briquettes sold under national renewable energy obligations, creating compliance barriers for uncertified suppliers. Stakeholders must monitor evolving sustainability certification schemes and carbon border adjustment mechanisms to secure market access across jurisdictions.
Market Dynamics
Steel manufacturers in Germany and India are accelerating briquette purchases for blast furnace injection, substituting compressed biomass for coking coal as emissions compliance tightens. This procurement pivot is compressing legacy coal supply chains while concentrating volume commitments around certified producers with Atlantic shipping capabilities.
Growth Catalysts
- EU Green Deal Emissions Standards:The tightening carbon intensity benchmarks for imported solid fuels are redirecting industrial procurement toward certified biomass briquettes across European power generation and district heating systems.
- Blast Furnace Injection Technology:Steel producers are deploying briquette injection systems that maintain metallurgical performance while reducing reliance on metallurgical coal in high-temperature reduction processes.
- Brazilian Industrial Clustering:Sugarcane bagasse briquette plants in São Paulo state serve captive demand from ethanol distilleries and food processors seeking waste-to-energy闭环.
Market Restraints
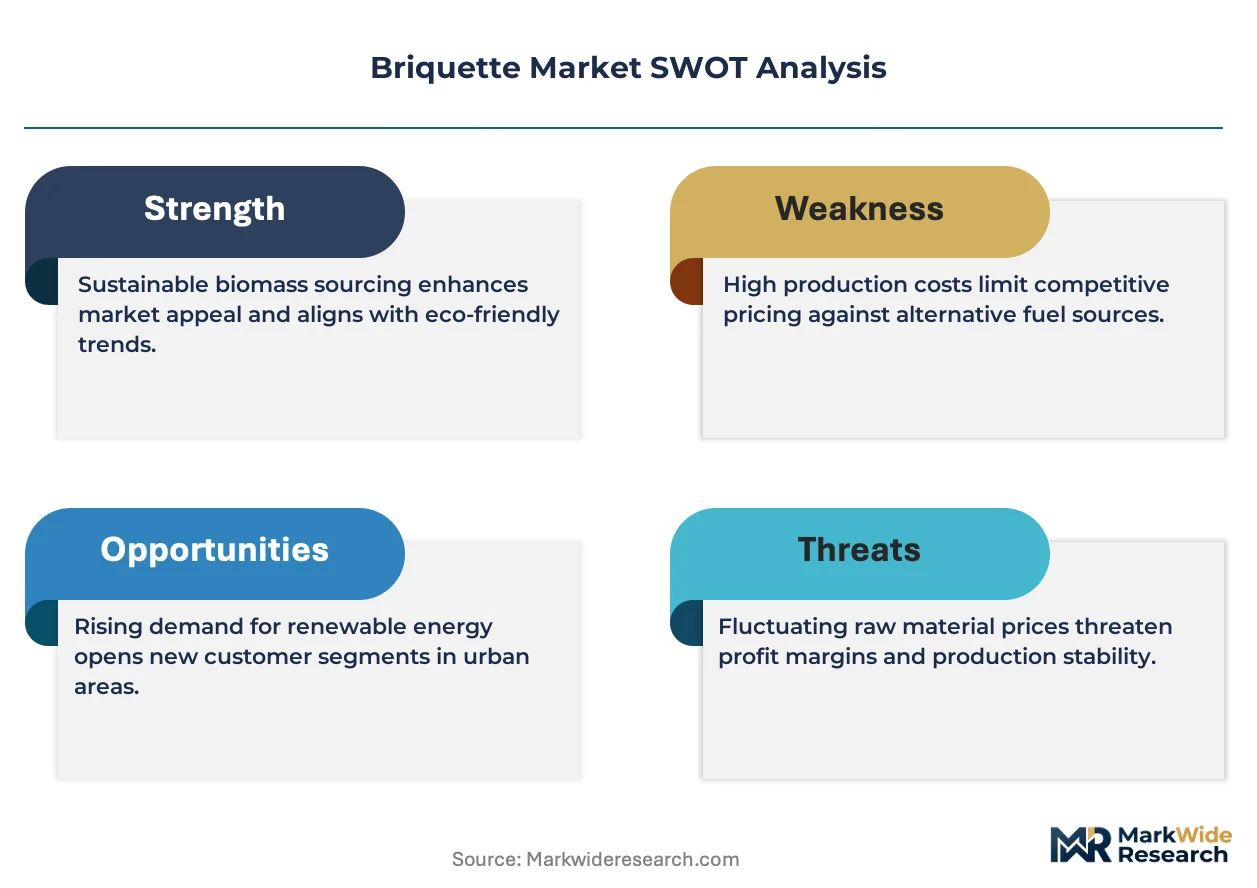
- Agricultural Residue Supply Volatility:Seasonal availability of rice husk, straw, and sawmill waste creates input cost swings that compress producer margins during harvest gaps.
- Atlantic Shipping Concentration:Bulk briquette flows depend on specialized pellet vessel capacity concentrated in Baltic and US Gulf ports, exposing buyers to freight rate spikes.
- Automated Stoker Compatibility Limits:Residential and small commercial heating systems require precise briquette density and ash content specifications that exclude lower-grade production.
Strategic Opportunities
- Carbon Border Adjustment Mechanism:The EU CBAM creates price advantages for certified low-carbon briquettes entering European industrial markets against uncertified competitors.
- India BIS Certification Gap:Domestic producers achieving Bureau of Indian Standards certification for biomass briquettes gain preferential access to national renewable energy obligation procurement pools.
- Torrefaction-Briquetting Convergence:Combining thermal pretreatment with densification produces hydrophobic, high-energy fuel suitable for overseas shipment without degradation.
Industry Challenges
- Continuous Pyrolysis Operator Shortage:Industrial-scale briquette production requires skilled technicians for high-pressure densification and moisture control systems that remain scarce in emerging production regions.
- Sustainability Certification Timeline Compression:Producers seeking FSC or SBP chain-of-custody documentation face audit backlogs that delay market access for 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Briquette Market |
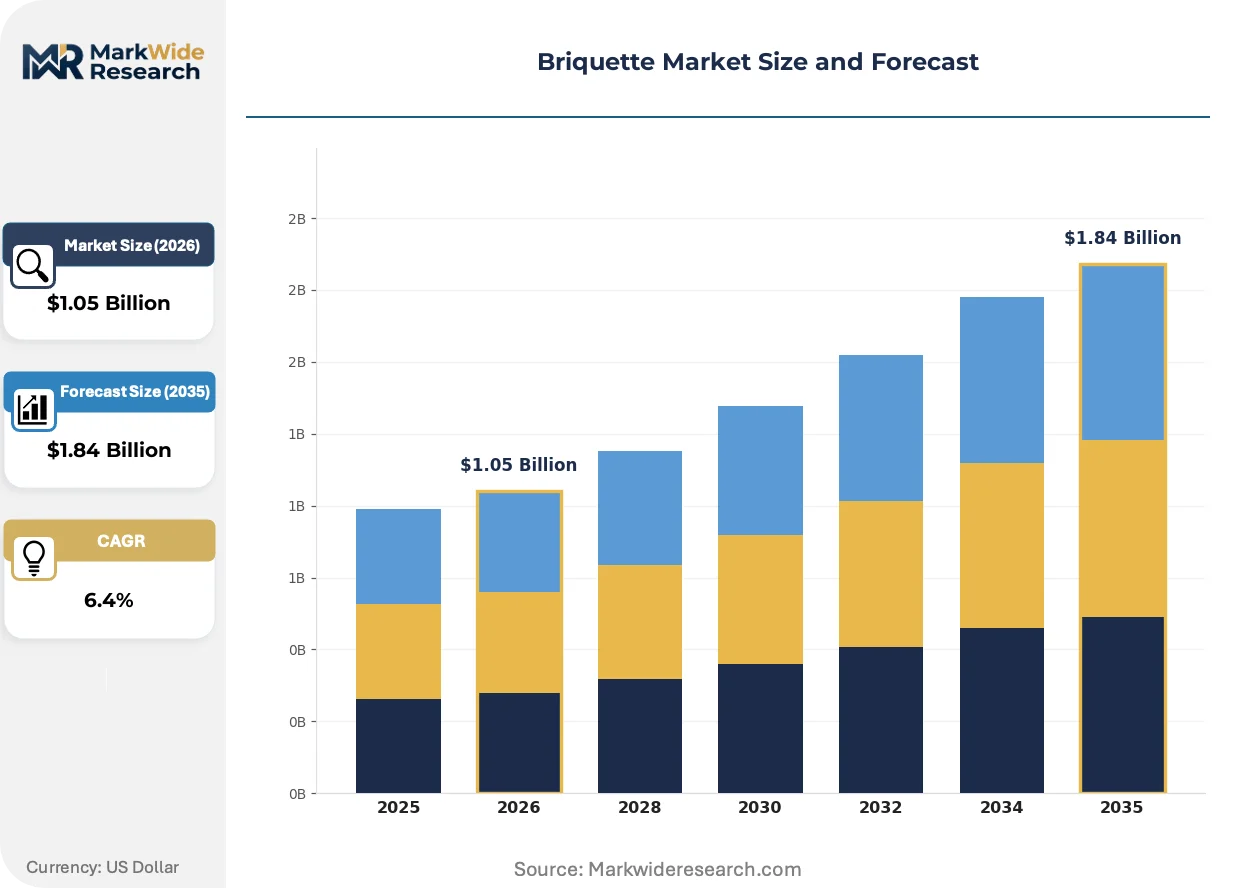
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charcoal Briquettes, Biomass Briquettes, Coal Briquettes, Wood Briquettes Material: Wood, Agricultural Residues, Organic Waste, Paper Application: Heating, Cooking, Industrial Fuel, Power Generation Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Biomass Secure Power Inc., BIOMAC Energy Ltd, Enviva, Pfeifer Group, German Pellets GmbH, Drax Group plc, Premium Pellet Ltd., Green Circle Bio Energy, Pinnacle Renewable Energy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Briquette Market Strategic Shifts & Innovations
Compression technologies and emissions monitoring systems are converging to reshape how industrial buyers evaluate fuel-grade biomass. Three developments are compressing the gap between agricultural residue collection and automated combustion performance.
Torrefied biomass briquettes are collapsing the energy density disadvantage that previously limited agricultural residue fuels to local markets. Steel mills in Rotterdam and power utilities in Copenhagen are accepting torrefied briquettes as direct coal replacements in pulverized fuel systems. The process enables rice husk and straw to achieve grindability and moisture resistance comparable to sub-bituminous coal.
The EU F-Gas Regulation and delegated acts under the Green Deal are tightening lifecycle carbon accounting for biomass imports. Industrial buyers must now document supply chain emissions from field to furnace gate. German district heating operators and Swedish CHP plants are restructuring procurement contracts around verified carbon intensity scores rather than simple calorific value.
Direct offtake contracting is displacing spot market purchasing among European utilities and Asian steel producers. Long-term volume commitments with price escalation clauses now govern three-quarters of industrial-grade briquette movement across the Atlantic. Enviva and Drax have pioneered this structure, but mid-scale producers in the Baltics and US Southeast are replicating the model to secure project finance for capacity expansion.
Briquette Market Segmentation
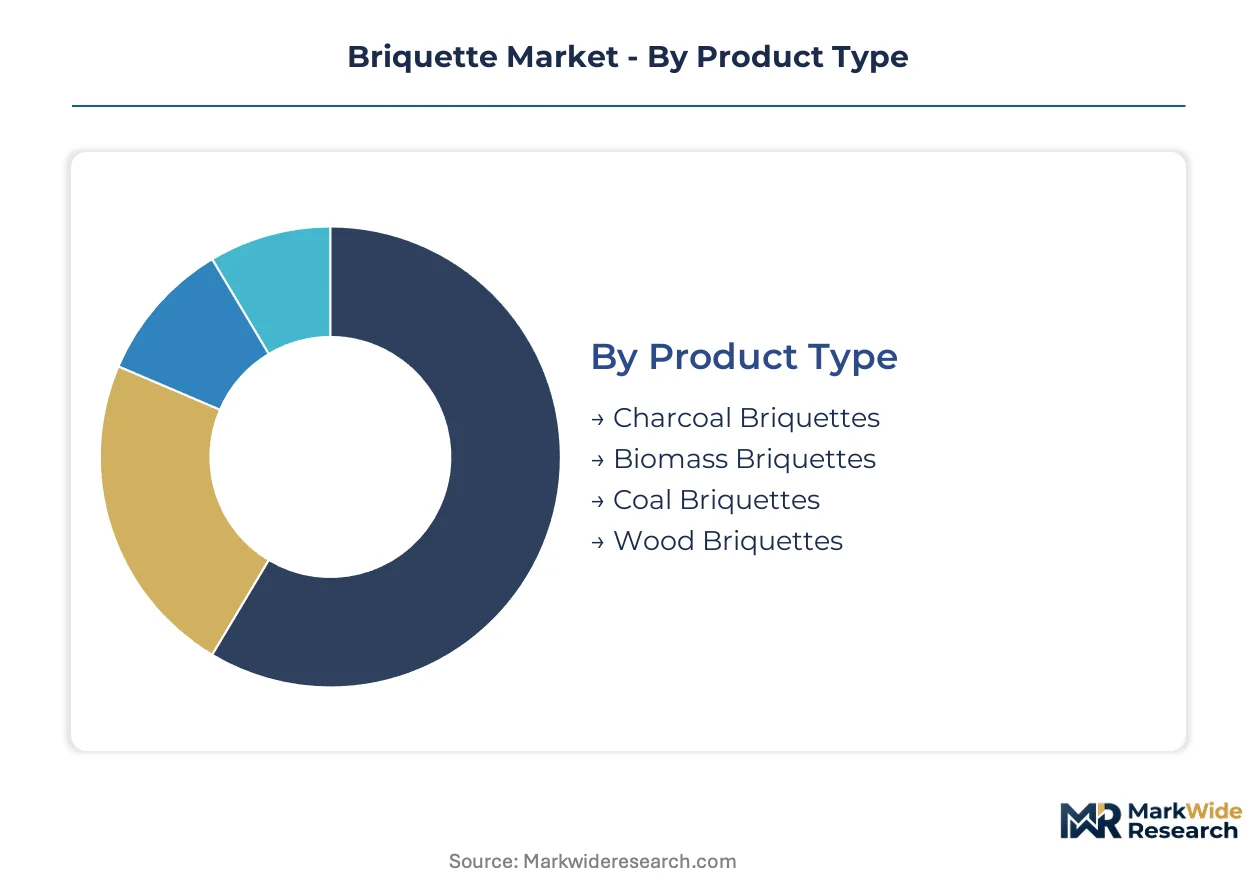
Briquette classification determines combustion system compatibility, emissions profiles, and procurement contract structures across industrial and consumer channels. Material sourcing geography and application heat requirements drive divergent margin pools and certification demands.
Product Type:
The use-case spectrum spans recreational cooking through blast furnace injection, with density specifications and ash content thresholds determining addressable market boundaries.
- Biomass Briquettes:Compressed agricultural residues and wood waste meeting EU sustainability certification for automated stoker systems in district heating networks. German utilities and Swedish CHP operators anchor procurement volume around verified carbon intensity scores rather than calorific value alone.
- Wood Briquettes:Densified softwood and hardwood residues with moisture content below 10%, dimensioned for residential stoves and small commercial boilers. Central European heating markets concentrate demand around Pfeifer Group and similar vertically integrated producers controlling sawmill residue collection.
- Charcoal Briquettes:Carbonized biomass formed for recreational grilling and emerging-market household energy, with margin compression from industrial-grade fuel competition.
- Coal Briquettes:Compressed coal fines retaining structural relevance only in legacy steel and cement applications where blend consistency requirements persist against biomass substitution.
The dominant share belongs to Biomass Briquettes, while Wood Briquettes is closing the gap fastest.
Material:
Input cost volatility and collection radius economics segment producer margin structures across residue categories.
- Agricultural Residues:Rice husk, straw, and bagasse subject to seasonal availability swings that compress margins during harvest gaps. Brazilian sugarcane bagasse plants serve captive ethanol distillery demand in São Paulo state.
- Wood:Sawmill residues and forest thinning commanding premium pricing in EU heating markets through FSC chain-of-custody documentation. Baltic producers leverage Atlantic shipping routes to reach Rotterdam and Copenhagen utilities.
- Organic Waste:Municipal and industrial biomass streams requiring preprocessing to meet combustion system specifications.
- Paper:Recycled fiber and pulp residues with limited energy density restricting application to low-temperature industrial boilers.
Agricultural Residues supply the largest volume base, though Wood commands the steepest price premiums.
Application:
Heat intensity requirements and emissions compliance thresholds stratify procurement contract structures and certification burdens.
- Industrial Fuel:Blast furnace injection and cement kiln firing demanding precise density and ash fusion temperatures. German and Indian steel manufacturers substitute compressed biomass for coking coal as emissions standards tighten.
- Power Generation:Co-firing and dedicated biomass combustion in converted coal plants requiring sustained volume commitments. Drax Group plc anchors demand through in-house production integrated with generation capacity.
- Heating:Residential stoves and district heating networks requiring automated stoker compatibility and low particulate emissions.
- Cooking:Emerging-market household energy and recreational grilling with lower specification thresholds but price-sensitive demand.
Industrial Fuel captures the highest value per tonne, while Power Generation is expanding most quickly through long-term offtake contracting.
Distribution Channel:
Customer scale and procurement sophistication determine channel economics and working capital intensity.
- Direct Sales:Long-term offtake agreements between producers and industrial energy buyers governing Atlantic bulk movements. Enviva structures volume commitments with European utilities across multi-year contracts.
- Wholesale:Regional distributors aggregating supply for commercial heating and small industrial accounts.
- Supermarkets:Consumer packaged goods retail for residential heating and recreational cooking segments.
- Online Retail:Direct-to-consumer channels with limited penetration due to shipping cost disadvantages for dense fuel products.
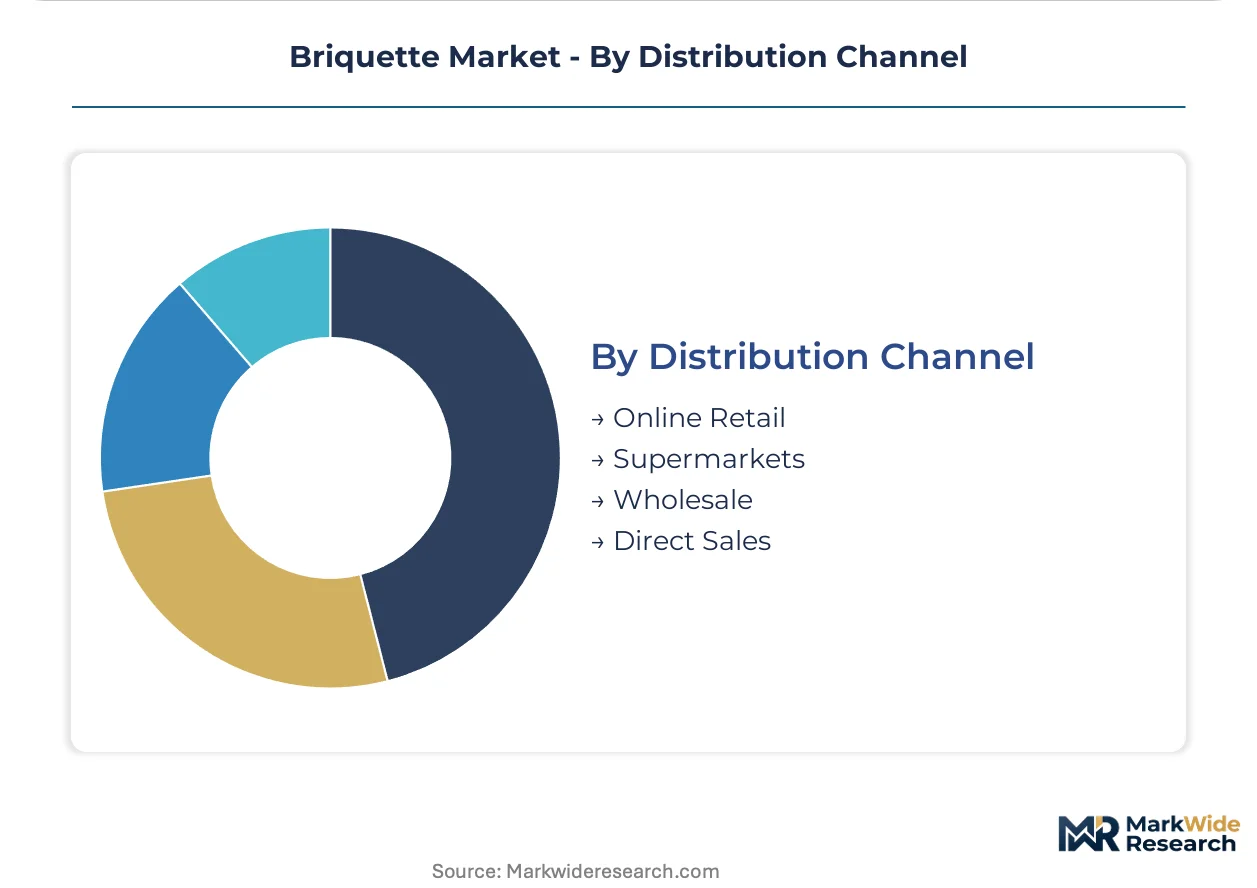
Direct Sales commands the dominant revenue share, though Wholesale is gaining traction among mid-scale commercial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities command premium pricing leverage over Baltic producers, while Indian steel mills absorb cost volatility from agricultural residue supply gaps. This asymmetry shapes procurement contract structures and capacity investment decisions across both regions.
Germany
Steel manufacturers in the Ruhr region and Lower Saxony accelerate briquette purchases for blast furnace injection, substituting compressed biomass for coking coal. The EU Green Deal's tightening emissions standards redirect industrial procurement toward certified biomass briquettes. District heating operators in Hamburg and Berlin restructure contracts around verified carbon intensity scores.
India
MNRE mandates BIS certification for biomass briquettes sold under national renewable energy obligations, creating compliance barriers for uncertified suppliers. Steel producers in Odisha and Jharkhand deploy briquette injection systems to reduce metallurgical coal dependence. Sugarcane bagasse plants in Maharashtra serve captive demand from ethanol distilleries.
Brazil
São Paulo state hosts sugarcane bagasse briquette plants supplying ethanol distilleries and food processors seeking waste-to-energy integration. ANVISA oversees industrial emissions compliance for solid fuel combustion. The industrial heartland around Campinas concentrates production capacity for regional distribution.
United States
EPA emissions thresholds under the Clean Air Act govern industrial solid fuel combustion in power generation and steel applications. Enviva leverages long-term offtake agreements with European utilities from Gulf Coast and Southeast production clusters. Drax Group plc anchors demand through in-house production integrated with converted coal-fired capacity.
Sweden
CHP plants in Stockholm and Gothenburg restructure procurement around verified carbon intensity scores rather than calorific value alone. The EU F-Gas Regulation tightens lifecycle carbon accounting for biomass imports. Baltic Sea shipping routes concentrate bulk briquette flows through specialized pellet vessel capacity.
Briquette Market Key Industry Players
Integrated energy conglomerates and specialized biomass producers split the market between long-term offtake contracting and regional heating distribution. The structure concentrates around Atlantic shipping corridors and Central European sawmill networks. Two archetypes dominate: utilities with captive production capacity, and independent producers securing volume commitments through certification. Competitive moves center on torrefaction-briquetting technology licensing and backward integration into residue collection.
Within the utility-integrated tier, Drax Group plc and Enviva exemplify the offtake-contracting model, securing multi-year volume commitments across Atlantic routes. Among specialized European producers, Pfeifer Group occupies a position representing vertical control from sawmill residue through finished distribution. German Pellets GmbH sits within the premium certification tier, anchoring supply relationships through FSC chain-of-custody documentation.
| Leading Market Players |
|---|
| Biomass Secure Power Inc. |
| BIOMAC Energy Ltd |
| Enviva |
| Pfeifer Group |
| German Pellets GmbH |
| Drax Group plc |
| Premium Pellet Ltd. |
| Green Circle Bio Energy |
| Pinnacle Renewable Energy Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in Baltic pellet vessel fleets is compressing spot freight rates while concentrating pricing power among producers with dedicated long-term offtake contracts. This utilization squeeze forces uncertified suppliers toward distressed spot sales while FSC-documented producers capture premium spreads through guaranteed Atlantic volume commitments.
Pricing Analysis
Configured-to-order torrefied briquettes for Rotterdam blast furnace injection command spreads over standard wood briquettes bound for Hamburg district heating. Contract-based long-term offtake dominates industrial procurement, with price differentiation driven by sustainability certification tier and volume scale commitments. Pricing pressure stems from agricultural residue supply gaps in Indian monsoon seasons, squeezing margins for uncertified domestic producers. Small commercial heating operators exhibit highest price sensitivity, while German steel mills absorb premiums for verified carbon intensity documentation.
Supply Chain Analysis
EU Green Deal carbon border adjustment mechanisms function as export-control equivalents, restricting uncertified biomass flows into European industrial markets. Supply concentrates in the United States, Brazil, and the Baltic states, with raw material dependencies on sawmill residues, sugarcane bagasse, and rice husk collections. Single-source vulnerability runs through specialized pellet vessel capacity anchored in Baltic and US Gulf ports. Distribution runs through direct producer-to-utility contracting for industrial volumes, with wholesale channels serving fragmented commercial heating demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The briquette market is cycling through a recovery phase as EU emissions compliance deadlines force accelerated coal substitution in steel and power generation. This cyclical upswing is anchored to the EU Green Deal's tightening carbon intensity benchmarks across the analysis window.
For Market Incumbents: Harden certification moats by accelerating FSC and SBP chain-of-custody documentation to exploit audit backlogs delaying competitor market access. Deepen backward integration into sawmill residue collection in the Baltics and US Southeast to secure input cost predictability against agricultural supply volatility. This consolidation responds to torrefaction-briquetting technology licensing threats from European equipment specialists.
For New Entrants and Emerging Players: Establish a beachhead in Maharashtra's captive sugarcane bagasse-to-ethanol distillery supply chains, where waste-to-energy闭环 integration creates defensible local demand. Target BIS certification gaps in India's national renewable energy obligation procurement pools, where domestic compliance barriers exclude uncertified imports. A direct sales contracting model with price escalation clauses secures project finance for initial capacity buildout.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among producers with multi-year Atlantic offtake agreements and integrated generation capacity. Five-to-ten year viability favors vertically integrated specialists controlling residue collection through finished distribution, with carbon border adjustment mechanism exposure as the primary inflection signal to monitor for margin compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Torrefaction Technology Licensing | Enables rice husk and straw to achieve coal-equivalent grindability for Rotterdam steel mills. |
| Backward Integration into Residue Collection | Pfeifer Group's sawmill network control secures input cost predictability across Central European heating markets. |
| Long-term Offtake Agreement Structuring | Enviva's multi-year European utility contracts anchor Atlantic shipping route utilization and project finance access. |
| Sustainability Certification Acceleration | FSC and SBP documentation unlocks EU Green Deal procurement pools ahead of audit backlog resolution. |
| Blast Furnace Injection System Deployment | German and Indian steel producers substitute certified biomass for coking coal under tightening emissions standards. |
Research Approach
Desk research of customs trade databases, EU ETS emissions registries, and national renewable energy obligation filings preceded structured interviews with biomass procurement officers at European utilities, steel plant fuel managers in Germany and India, torrefaction technology licensors, and sustainability certification auditors. Primary fieldwork with Baltic pellet vessel operators and São Paulo bagasse plant engineers combined with secondary validation from EPA Clean Air Act enforcement records and BIS certification rosters. Bottom-up production capacity modeling triangulated against top-down fuel substitution demand estimates across power generation and metallurgical applications.
Analytical assumptions held EU Green Deal implementation timelines and carbon border adjustment mechanism coverage fixed while varying agricultural residue yield forecasts and Atlantic freight rate scenarios across the projection horizon. Segmentation dimensions modeled include briquette product type, material source category, application heat intensity tier, and distribution channel structure. CAGRs were derived from production capacity expansion pipelines weighted against regulatory-driven coal substitution mandates. Industry-specific forecast inputs incorporated blast furnace injection technology adoption curves and torrefaction-briquetting convergence timelines.
Sensitivities concentrate around EU F-Gas Regulation delegated act revisions, Indian monsoon patterns affecting rice husk availability, and Baltic Sea shipping route congestion. Forecasts reflect documented assumptions on certification audit clearance rates and steel sector emissions compliance deadlines. Material shifts in EU carbon border adjustment mechanism coverage scope or torrefaction technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Fuel Oil Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
White Coal Market
Fuels
Charcoal Briquette Market
Fuels
India Coal Market
Fuels
Europe Firewood Market
Fuels
Renewable Heating Fuels Market
Fuels
Liquefied Helium Tanks Market
Fuels
Europe Black and Wood Pellets Market
Fuels
CNG Dispenser Market
Fuels
Global Fuel Ethanol Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Brazil LNG Market
Fuels
Wood Pellet Market
Fuels
No.4 Fuel Oil Market