
 China LNG Market | 2026-2036
China LNG Market Size, Share, and Industry Trends Forecast 2026-2036
China LNG Market Analysis
Long-term procurement contracting is consolidating how LNG gets sold in China, shifting volume risk from buyers to portfolio suppliers. PetroChina Company Limited leverages its pipeline network to anchor inland demand beyond coastal terminals. CNOOC sustains dominant import terminal capacity along the eastern seaboard. Sinopec competes through downstream petrochemical integration that absorbs liquefied natural gas feedstock.
Liquefied natural gas is natural gas cooled to minus 162 degrees Celsius for volume reduction, enabling intercontinental marine transport and seasonal peak shaving. Its primary purpose is to bridge supply geography gaps between producing basins and consuming markets lacking pipeline connectivity. Regasification infrastructure leads capital deployment among product type segments, absorbing the largest share of infrastructure spending as import dependency rises. Vehicle fuel application represents the fastest-growing demand pool, driven by heavy trucking fleet conversions seeking lower particulate emissions than diesel.
NMPA oversight of gas quality specifications and GB standards for terminal safety shape equipment procurement and operational compliance across China's LNG value chain. MIIT mandates on transport emissions intensify fleet conversion timelines that pull liquefied natural gas into road fuel markets. The dual carbon policy framework from Beijing dictates the pace of coal-to-gas switching that underwrites demand growth. Stakeholders must monitor provincial pipeline tariff reforms that could restructure terminal access economics and reshape regional competition.
Market Dynamics
China's dual carbon policy framework is compressing coal-to-gas switching timelines and forcing power utilities to accelerate LNG offtake contracting ahead of infrastructure buildout. This regulatory pressure is restructuring procurement patterns across coastal and inland demand centers.
Growth Catalysts
- MIIT emissions mandates:Heavy trucking fleet conversions to LNG fuel are accelerating under transport sector decarbonization rules, pulling volume into road fuel applications.
- Guangdong-Jiangsu terminal clustering:Regasification infrastructure concentration in these provinces creates demand density that justifies long-term supply contracting.
- Coal substitution policy:Beijing's dual carbon goals are forcing power generation utilities to expand gas-fired capacity, underwriting baseload LNG demand growth.
Market Restraints
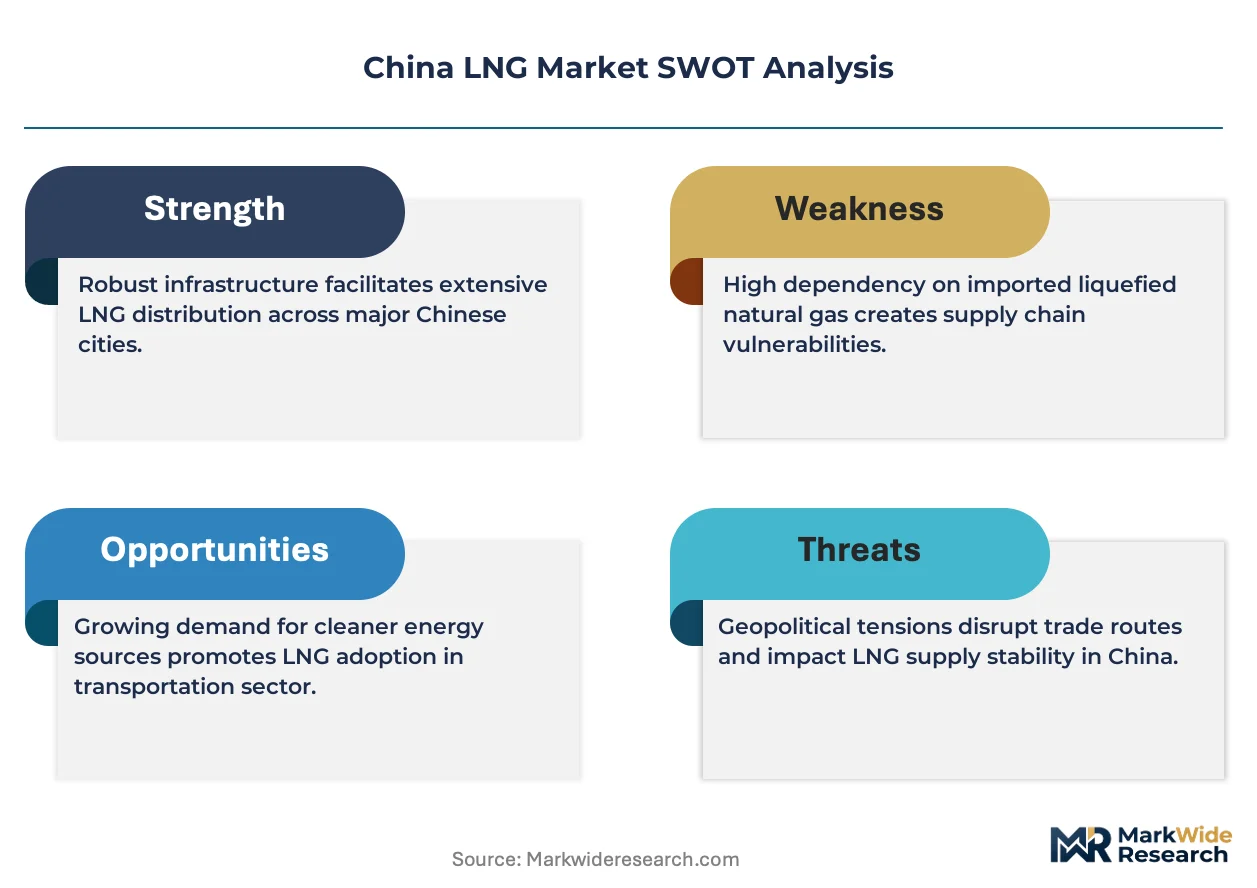
- Import terminal concentration:CNOOC's dominance along the eastern seaboard creates supply-side bottlenecks if geopolitical disruptions affect maritime routes.
- NMPA gas quality compliance:Tightening GB standards for terminal safety and gas specifications raise equipment procurement costs and operational complexity.
- Pipeline tariff uncertainty:Provincial reforms to third-party access pricing could restructure terminal economics and deter new infrastructure investment.
Strategic Opportunities
- Inland demand penetration:PetroChina's pipeline network enables LNG delivery beyond coastal terminals to central and western provinces lacking direct import access.
- Petrochemical feedstock integration:Sinopec's downstream chemical complexes can absorb LNG as process input, creating demand insulation from power sector volatility.
- Vehicle fuel infrastructure:Dedicated LNG refueling corridors along major freight corridors offer channel expansion beyond traditional utility offtake.
Industry Challenges
- Regasification capex intensity:Cryogenic storage and vaporization equipment requires substantial capital deployment with decade-long payback horizons.
- GB standard certification timelines:Terminal safety approvals under national standards create construction delays and cost overruns.
- Seasonal demand balancing:Peak shaving requirements strain storage capacity and create operational complexity during winter heating seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China LNG Market |
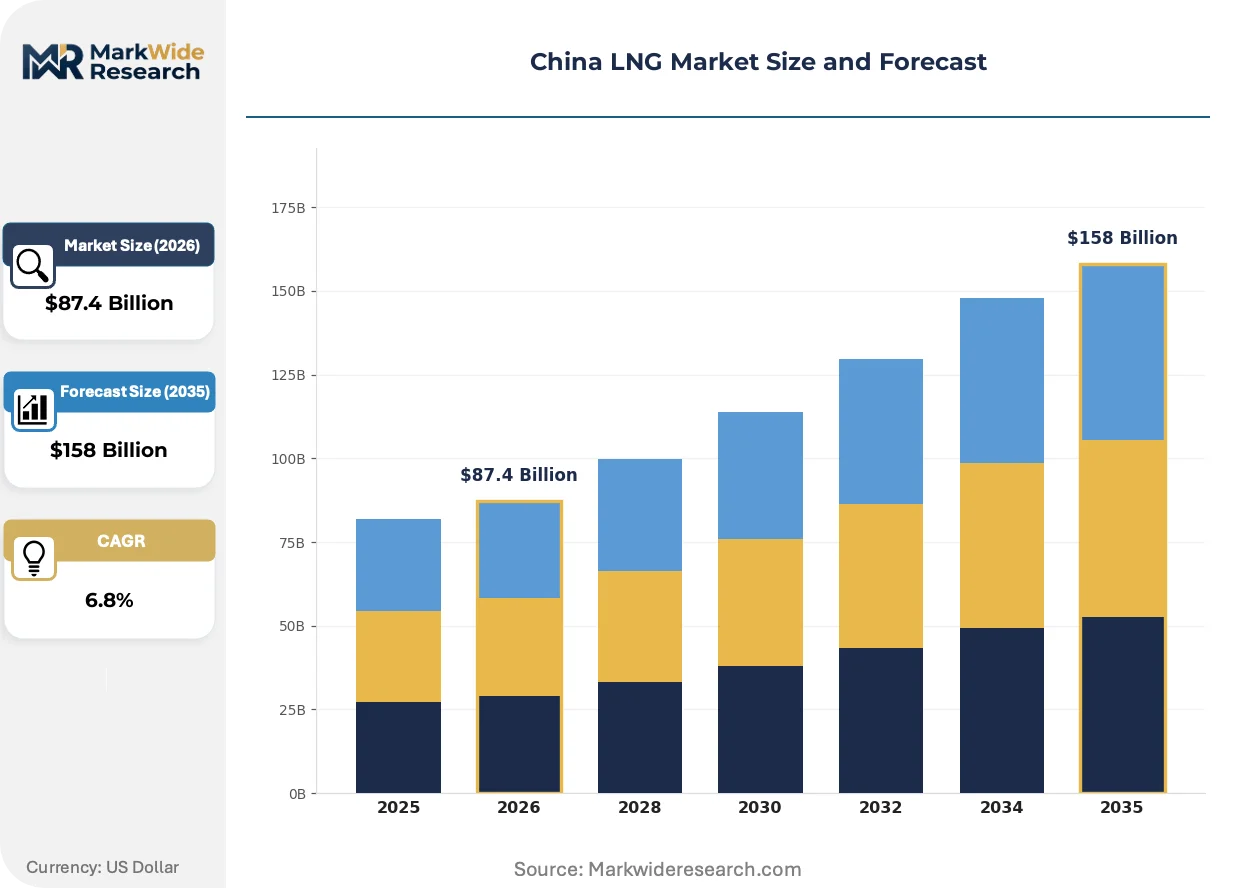
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefaction, Regasification, Storage, Transportation Application: Power Generation, Industrial Use, Residential Heating, Vehicle Fuel End User: Utilities, Manufacturing, Commercial, Domestic Distribution Channel: Direct Sales, Wholesale, Retail, Others |
| Companies Covered | PetroChina Company Limited, CNOOC, Sinopec, China National Petroleum Corporation, China Suntien Green Energy, Sinopec Shanghai Petrochemical Co., Ltd., Jereh Oil & Gas Engineering Corporation, Shell plc, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China LNG Market Emerging Trajectories
Marine transport economics and terminal digitization are reshaping how LNG moves through China's import infrastructure. Technology adoption is accelerating at coastal facilities while regulatory pressure tightens operational standards.
Floating storage and regasification units (FSRUs) are expanding terminal capacity without greenfield construction. Port authorities in Jiangsu and Guangdong are deploying these vessels to bridge supply gaps during infrastructure buildout. FSRU technology is converging with onshore terminal operations to compress project timelines and reduce capital intensity.
MIIT mandates on transport emissions are tightening fleet conversion deadlines and reshaping fuel procurement. The regulations force logistics operators to accelerate LNG truck adoption or face operational restrictions. Heavy freight corridors between manufacturing hubs and port cities are most affected, with fleet operators restructuring fuel supply contracts.
Long-term procurement contracting is displacing spot market purchasing among major offtakers. Power utilities and industrial gas buyers are locking in decade-long supply agreements to secure volume certainty. This pattern concentrates in coastal provinces where regasification infrastructure underpins delivery reliability.
China LNG Market Segmentation
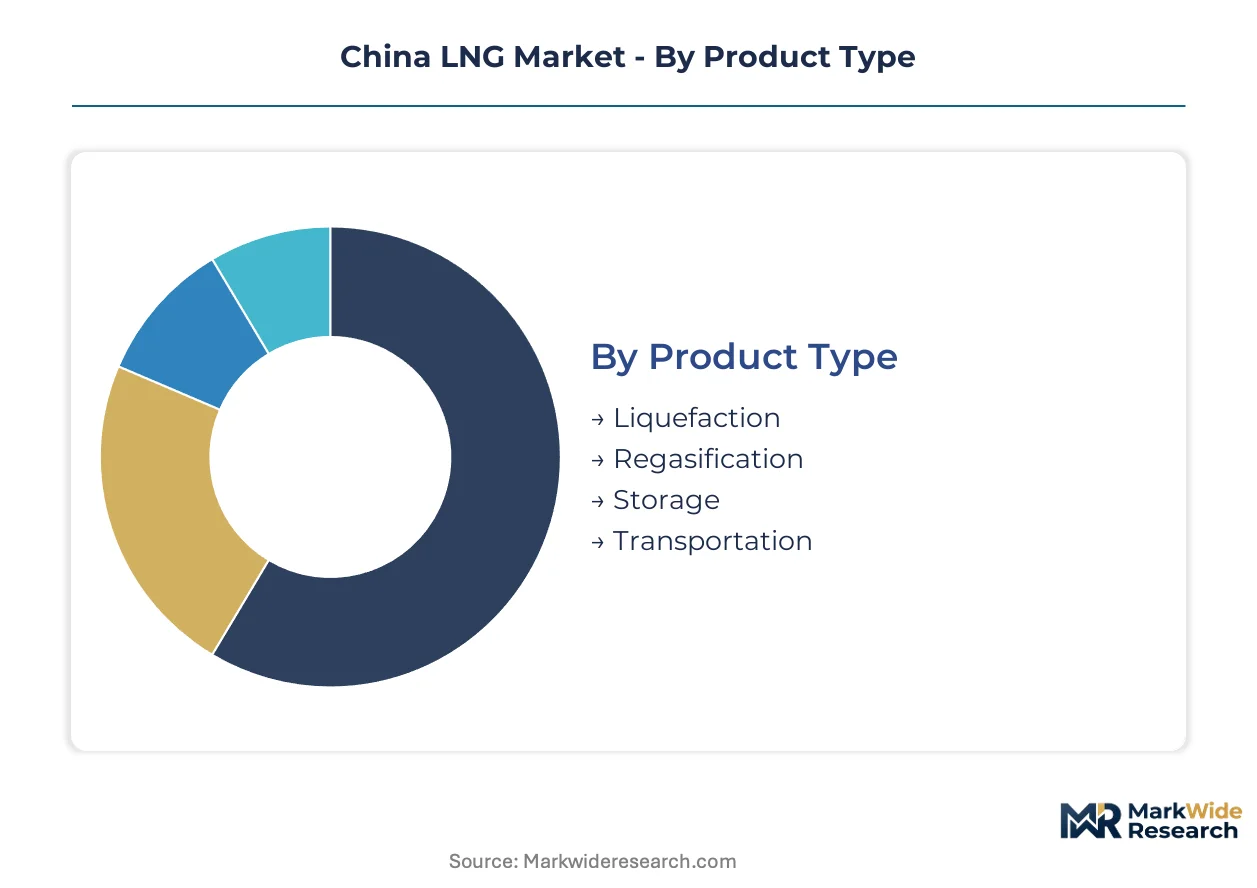
China's LNG market structure reflects infrastructure-led deployment patterns where regasification terminals anchor coastal demand while pipeline networks extend reach inland. Segment boundaries blur as power utilities diversify into vehicle fuel procurement and industrial offtakers integrate storage assets. Understanding these cross-cutting flows is essential for positioning across the value chain.
Product Type:
Standalone infrastructure segments dominate capital deployment, while embedded processing systems within integrated terminals represent a lower-integration alternative for new market entrants.
- Liquefaction:Baseload liquefaction trains at coastal terminals convert pipeline gas and associated gas from offshore fields into export-grade LNG. Capacity concentrates at CNOOC-operated facilities in Guangdong and Fujian where domestic production supplements import volumes.
- Regasification:Cryogenic vaporization systems at import terminals transform LNG back to gaseous state for pipeline injection. Guangdong and Jiangsu terminal clusters under NMPA safety oversight absorb the largest infrastructure spending as import dependency deepens.
- Storage:Full-containment tanks and in-ground caverns buffer seasonal demand swings. Peak shaving requirements during winter heating seasons strain working capacity at northern terminals.
- Transportation:Cryogenic road tankers and dedicated LNG carriers bridge terminal-to-user gaps. MIIT emissions mandates accelerate fleet conversion timelines for heavy trucking corridors.
Regasification leads volumes today; vehicle fuel transportation infrastructure is gaining share fastest.
Application:
Cost-tier stratification separates baseload utility contracting from premium-priced peak shaving and spot industrial procurement.
- Power Generation:Combined-cycle gas turbines at coastal utilities displace coal capacity under Beijing's dual carbon framework. Baseload offtake contracts concentrate in Guangdong and Jiangsu where grid interconnection supports gas-fired dispatch.
- Industrial Use:Process heat and feedstock applications at petrochemical complexes absorb steady LNG volumes. Sinopec's downstream integration captures cost advantages through captive regasification.
- Residential Heating:City gas distribution networks in northern provinces substitute LNG for coal during winter peaks. Seasonal demand strains storage and vaporization capacity at terminal gates.
- Vehicle Fuel:Cryogenic storage systems on heavy trucks replace diesel under MIIT transport decarbonization rules. Freight corridors between manufacturing hubs and port cities show steepest fleet conversion trajectories.
Power generation anchors demand volume; vehicle fuel applications are expanding most quickly.
End User:
Customer-type concentration shapes contracting structures, with large-volume utilities commanding term flexibility unavailable to fragmented domestic consumers.
- Utilities:State-owned power generators and city gas distributors negotiate long-term supply agreements. Portfolio suppliers absorb volume risk through take-or-pay structures.
- Manufacturing:Steel, cement, and chemical producers procure LNG for process energy and feedstock. Industrial buyers balance spot purchases against term contracts based on production schedules.
- Commercial:Hotels, hospitals, and district cooling systems require reliable gas delivery with limited storage backup. These users pay premium tariffs for interruptible supply guarantees.
- Domestic:Residential consumers access LNG through city gate stations and localized distribution networks. Pricing reforms to third-party pipeline access could reshape household supply economics.
Utilities dominate contracted volumes; manufacturing offtake is climbing the fastest as industrial coal substitution accelerates.
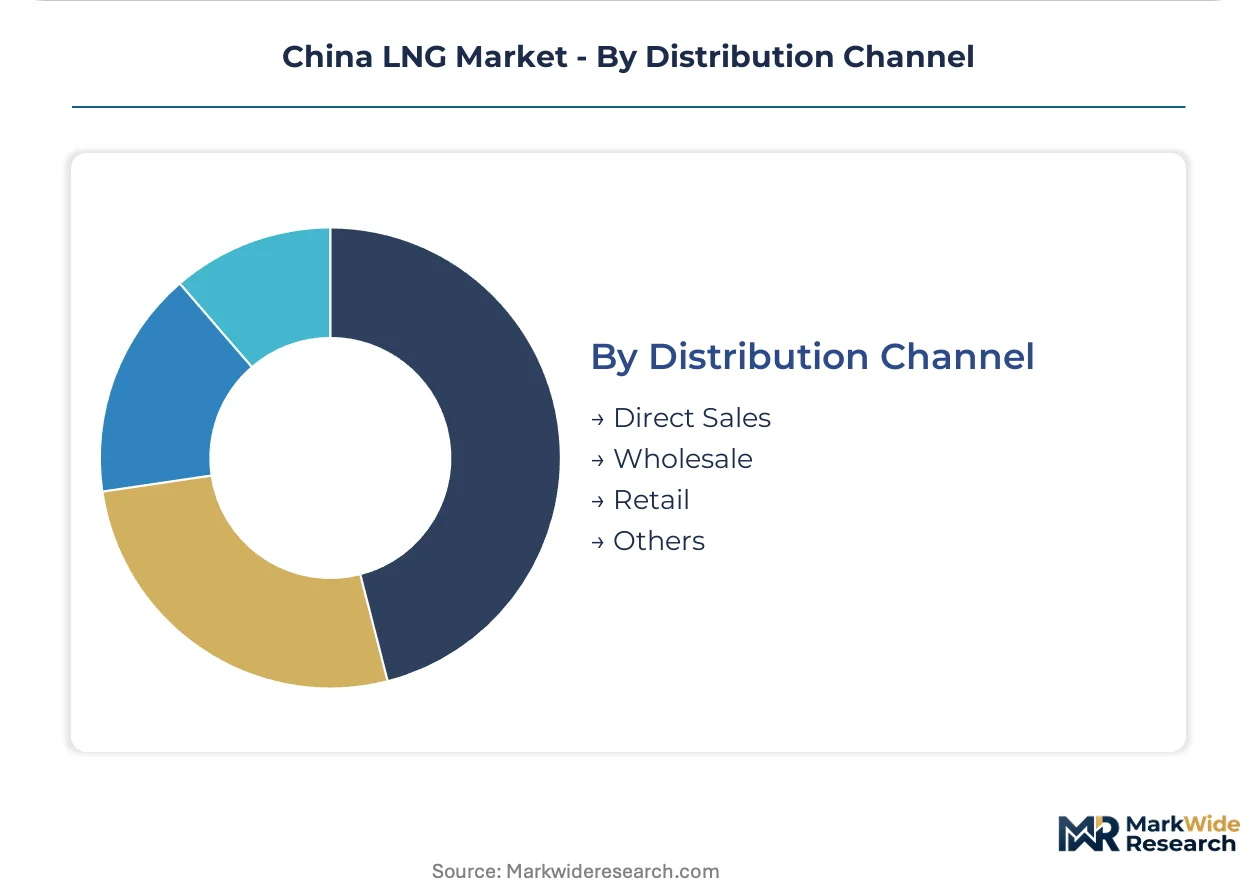
Distribution Channel:
Supply concentration favors direct terminal-to-user linkages, with wholesale intermediaries filling geographic and temporal gaps in infrastructure coverage.
- Direct Sales:Terminal operators deliver regasified gas through dedicated pipeline connections to anchor customers. This channel captures the largest margin share by eliminating intermediary markups.
- Wholesale:Aggregators pool fragmented demand from industrial parks and city gas companies. Wholesale traders manage seasonal arbitrage between summer storage injections and winter withdrawals.
- Retail:Local distributors serve vehicle fuel stations and small commercial accounts. Retail margins compress where terminal access is constrained by pipeline tariff disputes.
- Others:Spot market transactions and swap arrangements balance portfolio positions. This channel handles volume imbalances when term contract nominations diverge from actual consumption.
Direct sales command volume leadership; wholesale channels are gaining share fastest as third-party terminal access expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's LNG demand density varies sharply between coastal import corridors and inland pipeline networks, with terminal clustering in the east contrasting against supply extension challenges in central provinces.
Guangdong Province
Power generation utilities and industrial parks drive Guangdong's LNG consumption, with the province hosting the nation's densest regasification terminal cluster. NMPA safety standards for coastal facilities shape equipment procurement timelines. The Pearl River Delta manufacturing belt absorbs steady feedstock volumes for petrochemical processing.
Jiangsu Province
Combined-cycle gas turbines and city gas distribution anchor Jiangsu demand, with the Yangtze River Delta industrial corridor requiring baseload supply certainty. MIIT transport emissions rules accelerate LNG trucking fleet conversions along Shanghai-Nanjing freight routes. Nantong and Taicang terminal zones concentrate import infrastructure under CNOOC operational control.
Shandong Province
Industrial process heat applications and residential heating peaks define Shandong's seasonal demand profile, with northern cities substituting LNG for coal during winter months. GB standards for terminal safety compliance raise capital requirements at Qingdao import facilities. The Shandong Peninsula chemical industry cluster integrates regasified gas into ammonia and methanol production.
Sichuan-Chongqing Region
Domestic shale gas production competes with imported LNG in this southwestern demand center, though pipeline constraints create price arbitrage opportunities. Dual carbon policy timelines compress coal substitution schedules for municipal utilities. Chongqing's position as a western logistics hub drives vehicle fuel station deployment along Yangtze freight corridors.
Beijing-Tianjin-Hebei Region
Air quality mandates and heating season peaks concentrate LNG demand in this northern corridor, with city gas distributors managing winter supply security. MEE environmental enforcement tightens emissions standards for industrial boilers. Tianjin's import terminal serves as the primary gateway for capital region gas supply, with storage caverns buffering seasonal swings.
China LNG Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-owned energy majors commanding terminal infrastructure while engineering contractors capture equipment procurement cycles. The market structure consolidates around three national oil companies with integrated pipeline networks. Strategic archetypes include: integrated upstream-downstream operators, specialized regasification engineering firms, and international portfolio suppliers seeking long-term offtake agreements. Competitive moves center on terminal capacity expansion and strategic partnerships for FSRU deployment.
Within the integrated operator tier, PetroChina Company Limited and CNOOC occupy positions defined by pipeline network control versus coastal terminal dominance. Sinopec represents the petrochemical integration archetype, absorbing LNG volumes as process feedstock rather than pure fuel supply. These three state-owned entities anchor procurement contracting patterns that shape pricing and volume risk allocation across the value chain.
| Leading Market Players |
|---|
| PetroChina Company Limited |
| CNOOC |
| Sinopec |
| China National Petroleum Corporation |
| China Suntien Green Energy |
| Sinopec Shanghai Petrochemical Co., Ltd. |
| Jereh Oil & Gas Engineering Corporation |
| Shell plc |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Cryogenic engineering talent concentrated in Guangdong and Jiangsu provinces commands wage premiums that compress margin spreads between premium and standard regasification service tiers. Labor-cost differentials across these coastal clusters directly shape pricing stratification as terminal operators compete for skilled technicians under MIIT compliance deadlines.
Pricing Analysis
Capacity additions in Jiangsu and Guangdong are reshaping price floors as CNOOC and PetroChina expand terminal infrastructure. Contract-based long-term offtake dominates, with price differentiation driven by volume scale and NMPA certification tier. Pricing pressure stems from third-party pipeline access reforms that threaten incumbent margin structures. Manufacturing offtakers show highest price sensitivity; utilities with dual carbon mandates absorb premium tiers.
Supply Chain Analysis
Specialized welder and cryogenic technician availability in Tianjin and Dalian manufacturing zones constrains equipment fabrication timelines. Equipment sourcing draws from China, South Korea, and Japan for vaporization trains and storage tanks. Nickel alloy and cryogenic steel dependencies create single-source vulnerability for high-pressure components. Distribution runs through direct terminal-to-utility linkages with wholesale aggregators filling inland gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's LNG market represents a late-cycle quality story where NMPA gas quality tightening shifts procurement toward premium-certified terminal capacity. This specification upgrade favors operators with advanced vaporization and storage systems.
For Market Incumbents: Hedge against pipeline tariff uncertainty by securing third-party access agreements at Nantong and Taicang terminals. Invest in GB standard certification ahead of NMPA enforcement waves to capture premium pricing tiers. Defensive consolidation through FSRU partnerships compresses capital deployment timelines.
For New Entrants and Emerging Players: MIIT transport emissions mandates in Hebei and Shandong open a window for vehicle fuel infrastructure plays along Beijing-Tianjin freight corridors. Target wholesale aggregation for fragmented industrial parks lacking direct terminal access. Go-to-market leverage rests on cryogenic road tanker fleet partnerships.
For Investors and Strategic Acquirers: State-owned petrochemical conglomerates are the most active acquirer in this space, seeking captive regasification for chemical feedstock security. Five-to-ten year viability hinges on dual carbon policy continuity. Signal to monitor: provincial pipeline tariff reform announcements that restructure terminal economics.
| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Deployment | Floating units bridge supply gaps during Guangdong greenfield construction delays. |
| Long-term Supply Agreement | Power utilities lock in decade-long offtake to secure volume certainty under dual carbon goals. |
| Backward Integration into Storage | Petrochemical complexes capture cavern capacity to buffer seasonal price swings. |
| Green Certification Program | NMPA compliance investments differentiate terminal operators in procurement bidding. |
| Joint Venture | International portfolio suppliers partner with CNOOC to access eastern seaboard terminal capacity. |
Methodological Framework
Coverage spans coastal import provinces and inland pipeline networks, with primary inputs from each. Terminal operations managers, utility procurement officers, EPC contractors, and NMPA compliance specialists contributed structured interviews. Secondary validation drew from MIIT transport emissions filings, NMPA safety bulletins, customs import data, and provincial pipeline tariff disclosures. Bottom-up project pipelines and top-down policy trajectories were triangulated to anchor volume estimates.
Rate-of-change decomposition tracked capacity additions, fleet conversion velocities, and coal substitution schedules across the modeling period. Segmentation dimensions included product type, application, end user, and distribution channel with regional regulatory cluster overlay. CAGRs were derived from infrastructure deployment timelines and policy mandate enforcement curves. Forecast inputs incorporated FSRU deployment schedules and MIIT fleet conversion deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical maritime disruptions or accelerated dual carbon timeline revisions. Forecasts reflect documented assumptions regarding NMPA certification timelines and provincial pipeline access reforms. Material deviation in Beijing's carbon neutrality enforcement or CNOOC terminal expansion delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Renewable Heating Fuels Market
Fuels
No.2 Diesel Fuel Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
China Coal Market
Fuels
Gas Pooling Mechanism Market
Fuels
Marine Fuel Optimization Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
North America LNG Bunkering Market
Fuels
Electric Fuel Heater Market
Fuels
Smart Gas Market
Fuels
Chafing Fuel Market
Fuels
Fuel Oil Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Fuel Conditioning System Market