
 Coal to Liquid Fuel (CTL) Market | 2026-2036
Coal to Liquid Fuel (CTL) Market Size, Share, and Industry Trends Forecast 2026-2036
Coal to Liquid Fuel (CTL) Market Outlook
Multi-source feedstock procurement is expanding across the CTL value chain as project developers hedge against raw coal quality variance and supply interruptions. Sasol Limited anchors southern African production through its Secunda complex, the world's largest synthetic fuels facility. China Shenhua Energy Company dominates domestic Chinese CTL output via its Ordos and Ningxia operations. Inner Mongolia Yitai Coal leverages its captive mine-mouth reserves to sustain cost-competitive liquid fuel yields.
Coal to liquid fuel refers to the thermochemical conversion of coal into synthetic hydrocarbon liquids through gasification followed by Fischer-Tropsch synthesis or direct liquefaction, typically producing fuels with cetane ratings above 70 and sulfur content below 10 ppm for diesel applications. The primary industrial purpose centers on producing transport-compatible fuels and chemical feedstocks from abundant coal reserves where petroleum economics are unfavorable. Synthesized liquid fuels and diesel occupy the dominant product positions due to established offtake agreements with military and heavy freight operators. Fischer-Tropsch technology leads the technology segment given its commercial maturity and superior product quality, though catalytic conversion routes are gaining traction for methanol-to-olefin integration. The petrochemical industry end-user segment commands the deepest margin pools through chemical feedstock offtake, while aviation applications represent the fastest-growing demand vector as airlines seek certifiable drop-in synthetic jet fuel.
China's MEE enforces stringent carbon intensity benchmarks on new CTL projects, while South Africa's Department of Mineral Resources and Energy regulates synthetic fuel output quotas through its petroleum licensing framework. The EPA in the United States imposes Tier 3 sulfur standards that limit market access for CTL diesel unless hydrocracking upgrades are implemented. Stakeholders must monitor evolving carbon border adjustment mechanisms and synthetic fuel certification pathways to preserve project bankability and offtake security.
Market Dynamics
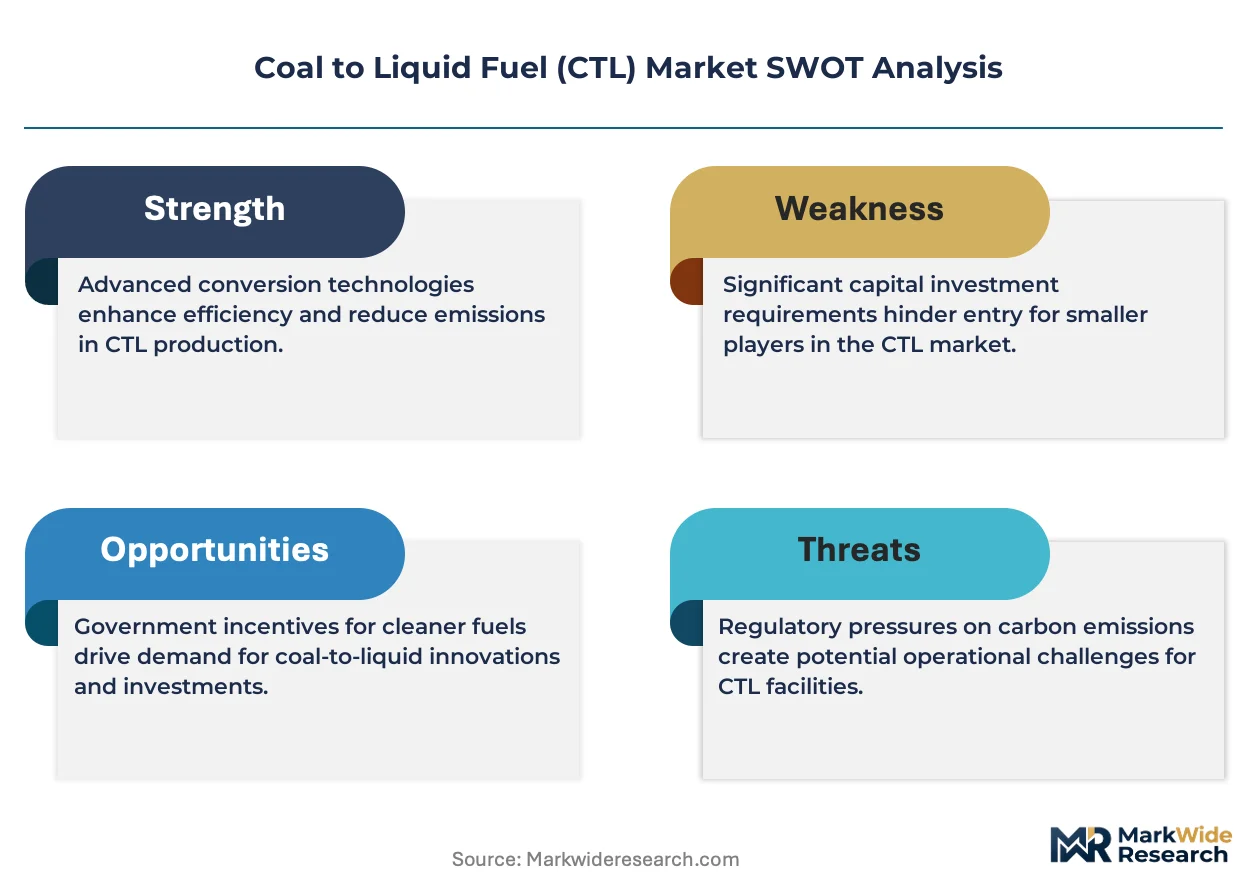
Carbon intensity benchmarks from China's MEE and South Africa's petroleum licensing framework are compressing project approval timelines while simultaneously redirecting capital toward retrofitted gasification trains and carbon capture retrofits.
Growth Catalysts
- Aviation fuel certification:Airlines in Asia-Pacific and Middle East markets are securing offtake agreements for drop-in synthetic jet fuel produced via Fischer-Tropsch synthesis, creating guaranteed demand basins for new CTL capacity.
- Dual carbon policy convergence:China's dual carbon goals are channeling state-backed financing toward integrated gasification combined cycle plants with carbon capture, lowering effective hurdle rates for brownfield expansions.
- Mine-mouth resource access:Captive coal reserves in Inner Mongolia and Mpumalanga are eliminating transport cost penalties, sustaining liquid fuel yields that compete with imported crude refining economics.
Market Restraints
- Capital intensity barriers:Greenfield CTL facilities require multi-billion dollar gasification and synthesis train investments, limiting viable sponsors to state enterprises and sovereign wealth vehicles with decade-long capital deployment horizons.
- Feedstock quality variance:High ash and sulfur content in sub-bituminous coal from specific basins degrades syngas quality, forcing costly upstream beneficiation or blended procurement strategies.
- Petroleum substitution pressure:Shale oil production economics in North American markets and expanding biofuel mandates in European transport sectors constrain CTL diesel price premiums in Atlantic basin trade.
Strategic Opportunities
- Carbon border adjustment positioning:EU CBAM implementation is creating certification premiums for low-carbon intensity synthetic fuels, rewarding CTL operators with integrated carbon capture and storage.
- Petrochemical feedstock pivot:Methanol-to-olefin integration at Chinese CTL complexes is displacing naphtha cracking for polyethylene production, opening chemical offtake contracts with higher margins than transport fuel sales.
- Military strategic reserve contracting:Defense ministries in coal-rich jurisdictions are establishing synthetic fuel stockpile agreements that guarantee floor prices and insulate production from civilian demand volatility.
Industry Challenges
- Specialized engineering talent scarcity:Fischer-Tropsch catalyst design and gasification operations expertise concentrates within a narrow cohort of retired plant operators and academic research centers, constraining operational ramp rates for new facilities.
- ISO 14064 carbon accounting complexity:Project developers face extended verification timelines for lifecycle emissions certification required by aviation fuel offtakers, delaying revenue recognition and complicating project finance structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal to Liquid Fuel (CTL) Market |
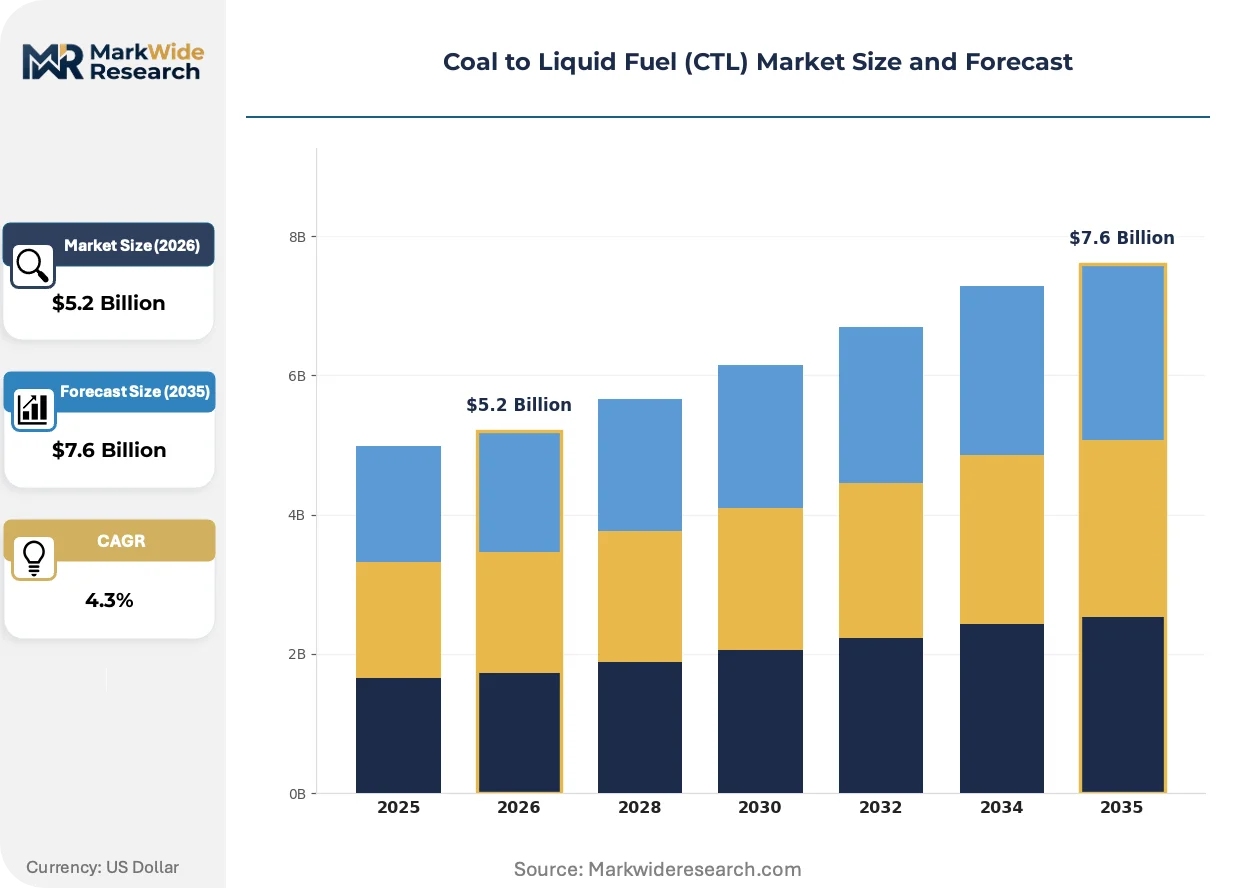
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $7.6 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthesized Liquid Fuels, Methanol, Diesel, Jet Fuel Technology: Fischer-Tropsch, Gasification, Hydrocracking, Catalytic Conversion End User: Transportation, Power Generation, Petrochemical Industry, Aviation Application: Fuel Supply, Chemical Feedstock, Energy Production, Industrial Use |
| Companies Covered | Sasol Limited, China Shenhua Energy Company, Linc Energy, DKRW Energy, Bumi plc, Monash Energy, Inner Mongolia Yitai Coal, Celanese Corporation, Envidity Energy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal to Liquid Fuel (CTL) Market Strategic Shifts
Process intensification and modular reactor designs are compressing construction schedules while carbon capture integration is redefining project bankability criteria across the synthetic fuels sector.
Slurry-phase Fischer-Tropsch reactors with cobalt-based catalysts are achieving higher per-pass conversion efficiencies than fixed-bed alternatives. Aviation fuel blenders in Southeast Asian markets are qualifying these outputs for ASTM D7566 certification at accelerated schedules. This technology is integrating carbon capture modules directly into synthesis gas cooling trains, collapsing the capital cost gap between conventional and low-carbon CTL configurations.
China's MEE has enacted carbon intensity benchmarks for new gasification projects that mandate 40% carbon capture rates or equivalent offsets. Project developers in Ningxia and Ordos are responding by engineering pre-combustion capture into front-end engineering designs, adding 15-20% to baseline capex but preserving access to state-backed green financing windows. The petrochemical end-use segment faces the steepest compliance cost escalation, driving consolidation toward integrated energy-chemical complexes.
Airlines are consolidating synthetic fuel procurement through multi-year offtake agreements with CTL operators rather than spot market purchases. This contract structure is displacing traditional refined jet fuel procurement desks at major carriers, concentrating buyer power among sustainability-linked finance teams. The behavioral shift is most visible in Chinese and South African markets where state-owned airlines coordinate directly with state-controlled CTL producers.
Coal to Liquid Fuel (CTL) Market Segmentation
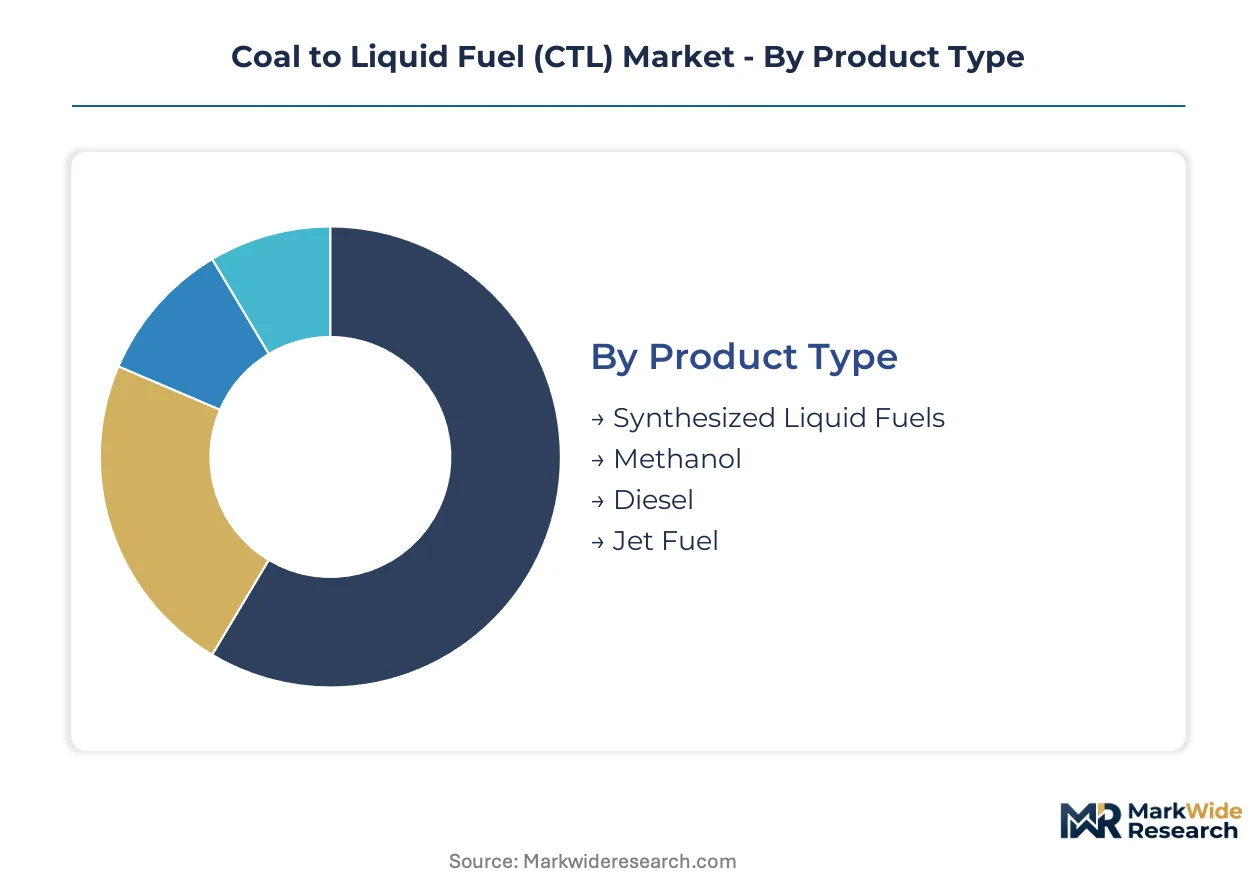
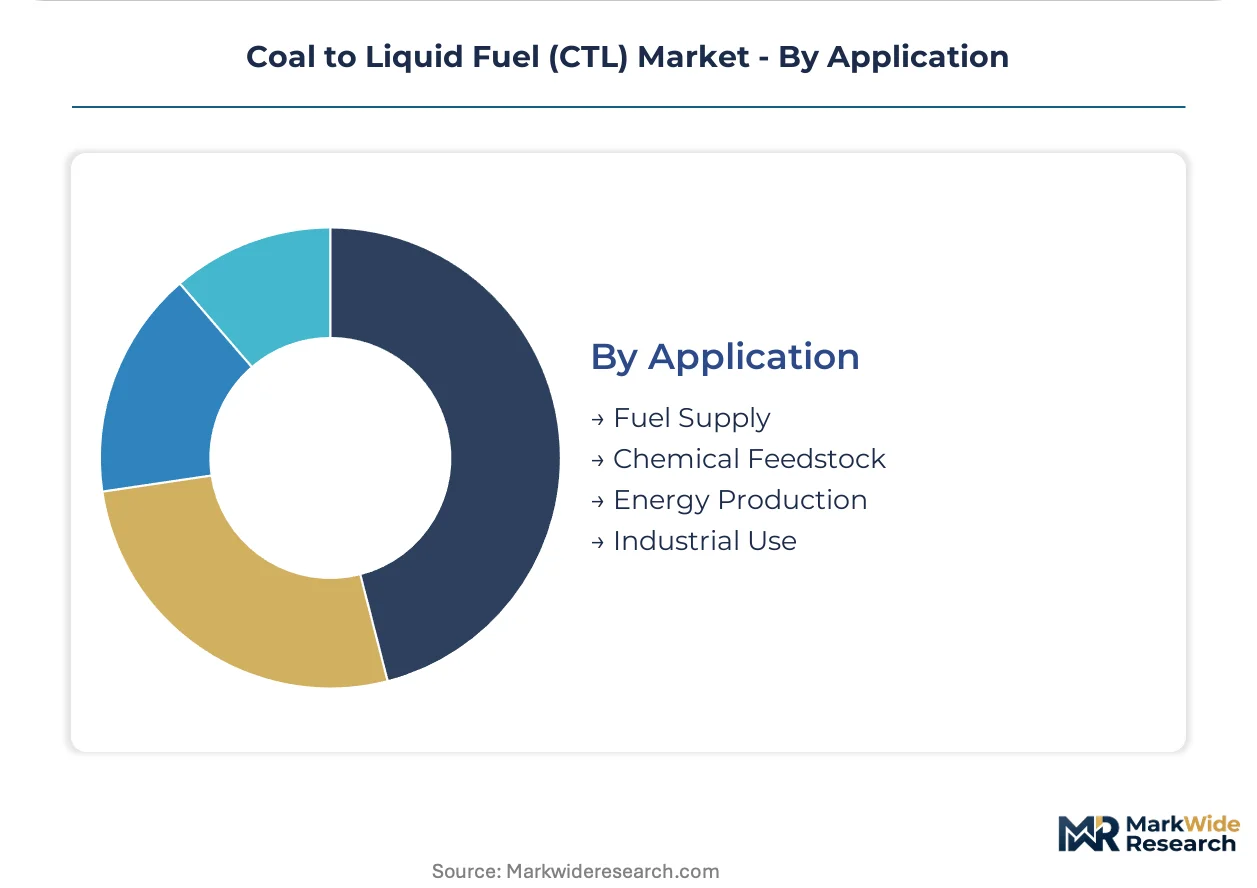
CTL product flows split between premium-certified transport fuels and bulk chemical feedstocks, with technology choice determining carbon intensity compliance and margin capture. End-use segmentation reveals divergent buyer power, from price-taking power generators to certification-demanding airlines.
Product Type:
Volume concentrates in diesel-compatible streams, while premium pricing attaches to aviation-certifiable outputs.
- Synthesized Liquid Fuels:Broad-spectrum Fischer-Tropsch outputs with cetane ratings above 70 and sub-10 ppm sulfur content serve military and heavy freight operators in South Africa and China. Demand clusters around Secunda and Ordos where integrated gasification complexes achieve economies of scale.
- Jet Fuel:ASTM D7566-certified synthetic paraffinic kerosene commands qualification premiums from Asia-Pacific carriers seeking drop-in alternatives to conventional aviation fuel. Airlines in Chinese and Middle Eastern markets are consolidating procurement through multi-year offtake agreements rather than spot purchases.
- Diesel:High-cetane distillate for heavy transport and mining equipment.
- Methanol:Intermediate chemical platform for olefin production and fuel blending.
Today's leader: Synthesized Liquid Fuels. Tomorrow's challenger: Jet Fuel.
Technology:
Commercial maturity separates bankable proven routes from emerging catalytic alternatives.
- Fischer-Tropsch:Slurry-phase reactors with cobalt-based catalysts achieve superior per-pass conversion efficiencies versus fixed-bed configurations. Southeast Asian aviation fuel blenders are qualifying these outputs for accelerated ASTM certification schedules.
- Gasification:Pre-combustion carbon capture integration at Chinese facilities adds 15-20% to baseline capex but preserves access to state-backed green financing windows under MEE benchmarks.
- Hydrocracking:Downstream upgrading for sulfur reduction and distillate yield optimization.
- Catalytic Conversion:Methanol-to-olefin routes displacing naphtha cracking for polyethylene production.
Established dominance: Fischer-Tropsch. Emerging disruptor: Catalytic Conversion.
End User:
Margin depth varies sharply between commodity-exposed power generators and specification-locked aviation buyers.
- Petrochemical Industry:Methanol-to-olefin integration at Chinese CTL complexes opens chemical offtake contracts with higher margins than transport fuel sales. Polyethylene producers in Ningxia and Ordos are displacing naphtha feedstocks with coal-derived olefins.
- Aviation:Airlines consolidating synthetic fuel procurement through sustainability-linked finance teams rather than traditional refined jet fuel desks. State-owned Chinese and South African carriers coordinate directly with state-controlled CTL producers.
- Transportation:Heavy freight and military diesel demand.
- Power Generation:Backup fuel supply for grid stabilization.
Deepest margins: Petrochemical Industry. Steepest expansion: Aviation.
Application:
Certification requirements distinguish fuel supply contracts from chemical feedstock specifications.
- Chemical Feedstock:Methanol and olefin outputs for polyethylene and synthetic rubber production.
- Fuel Supply:Transport-compatible diesel and jet fuel meeting military and civilian specifications.
- Energy Production:Peaking power and strategic reserve stockpiling.
- Industrial Use:Process heat and captive power for mining and metallurgy.
Current revenue anchor: Fuel Supply. Margin migration target: Chemical Feedstock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Secunda complex in South Africa anchors global synthetic fuel production capacity. State-backed financing in China and captive coal reserves in Inner Mongolia sustain project economics. Regulatory divergence across jurisdictions is fragmenting approval timelines and carbon intensity benchmarks.
China
Aviation fuel offtake agreements and methanol-to-olefin integration drive capacity expansion in Ningxia and Ordos. The MEE enforces 40% carbon capture mandates for new gasification projects under dual carbon policy frameworks. Inner Mongolia autonomous region concentrates mine-mouth CTL operations where Shenhua Energy and Yitai Coal leverage captive reserves.
South Africa
Synthetic diesel demand from military stockpiling and heavy freight operators sustains output at the Secunda complex. The Department of Mineral Resources and Energy regulates production quotas through petroleum licensing frameworks. Mpumalanga coal belt hosts the world's largest synthetic fuels facility where Sasol Limited maintains operational dominance.
United States
Shale oil economics constrain CTL diesel price competitiveness in domestic transport markets. The EPA imposes Tier 3 sulfur standards that limit market access without hydrocracking upgrades. Wyoming and North Dakota coal basins host stranded resource evaluations where project developers assess carbon capture integration for export-oriented synthetic fuel production.
India
Strategic petroleum reserve diversification and defense fuel security priorities stimulate pilot project evaluations. The Ministry of Coal coordinates with the Ministry of Petroleum and Natural Gas on gasification-linked synthetic fuel roadmaps. Jharkhand and Odisha coal belts concentrate feasibility studies for mine-mouth CTL complexes targeting military aviation offtake.
Australia
Export-oriented synthetic fuel evaluations target Asian aviation markets seeking ASTM D7566-certified drop-in alternatives. State environmental regulators in Queensland and New South Wales impose greenhouse gas assessment requirements on coal-to-liquids proposals. Surat Basin coal deposits support pre-feasibility studies for Fischer-Tropsch integration with carbon capture and storage infrastructure.
Coal to Liquid Fuel (CTL) Market Competitive Environment
Global majors compete with regional champions across technology licensing and captive resource access. The market structure concentrates around state-controlled energy conglomerates with decade-long capital deployment horizons and sovereign-backed financing. Two strategic archetypes dominate: integrated energy-chemical complexes with backward coal mining control, and technology licensors supplying catalyst and reactor systems to third-party developers. Competitive moves center on carbon capture retrofit integration and petrochemical feedstock pivot strategies that displace naphtha cracking economics.
Among African and Asia-Pacific producers, Sasol Limited, China Shenhua Energy Company, and Inner Mongolia Yitai Coal occupy positions representing the integrated complex archetype. Sasol Limited exemplifies the vertically controlled model through its Secunda operations. China Shenhua Energy Company anchors Chinese domestic capacity via Ordos and Ningxia facilities. Inner Mongolia Yitai Coal represents the captive mine-mouth configuration leveraging autonomous region coal reserves. These entities sit within a competitive set where state ownership confers financing advantages and offtake security unavailable to privately capitalized developers.
| Leading Market Players |
|---|
| Sasol Limited |
| China Shenhua Energy Company |
| Linc Energy |
| DKRW Energy |
| Bumi plc |
| Monash Energy |
| Inner Mongolia Yitai Coal |
| Celanese Corporation |
| Envidity Energy Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ASTM D7566 aviation fuel and bulk synthetic diesel creates parallel pricing architectures that feed directly into procurement strategies. Premium jet fuel offtakers in Asia-Pacific markets absorb cost premiums for lifecycle carbon accounting, while military and heavy freight operators in South Africa and China negotiate long-term contracts indexed to coal input costs.
Pricing Analysis
Input-cost pass-through from coal procurement to liquid fuel output dominates contract structures, with mine-mouth operations in Inner Mongolia and Mpumalanga eliminating transport penalties that otherwise compress margins. Price differentiation hinges on certification tier—ASTM D7566 qualification commands substantial premiums over uncertified diesel—and volume scale, with state-backed buyers securing preferential terms through multi-year offtake agreements. Pricing pressure stems from shale oil economics in Atlantic basin markets, where imported crude refining undercuts CTL diesel competitiveness. Military stockpiling programs exhibit lowest price sensitivity due to strategic reserve mandates, while independent petrochemical buyers negotiate aggressively on methanol-to-olefin feedstock contracts.
Supply Chain Analysis
Dual-sourcing requirements from aviation fuel blenders mandate qualified supply from both Chinese and South African production complexes, preventing single-dependency vulnerabilities. Geographic supply concentration centers on China, South Africa, and emerging evaluations in Australia, with Fischer-Tropsch catalyst systems drawing from specialized German and Japanese engineering houses. Raw material dependencies encompass sub-bituminous coal feedstocks, cobalt-based catalyst metals, and hydrogen supply for synthesis gas upgrading. Supply chain risk manifests through carbon border adjustment exposure for export-oriented synthetic fuel, as EU CBAM implementation threatens market access for uncaptured emissions. Distribution runs through state-controlled pipeline networks and dedicated tanker fleets serving military and aviation offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Coal to Liquid Fuel market compounds steadily as aviation decarbonization mandates institutionalize synthetic jet fuel procurement, creating durable demand basins resistant to petroleum price volatility.
For Market Incumbents: Acquire carbon capture infrastructure assets at existing gasification complexes to preserve access to green financing windows under tightening MEE benchmarks. Consolidate catalyst engineering capabilities through partnerships with retired Fischer-Tropsch operators to address specialized talent scarcity threatening operational ramp rates. Defensive positioning requires retrofitting Secunda and Ordos facilities with pre-combustion capture before regulatory deadlines harden. For New Entrants and Emerging Players: Defense ministry fuel security programs represent the most penetrable buyer archetype, with stockpiling agreements offering guaranteed floor prices and insulation from civilian demand swings. Target Australian Surat Basin evaluations for ASTM D7566-certified export production serving Southeast Asian aviation markets. White-space exists in methanol-to-olefin integration for polyethylene producers seeking naphtha displacement. Go-to-market positioning should emphasize ISO 14064 lifecycle certification to unlock sustainability-linked finance. For Investors and Strategic Acquirers: Consolidation pressure builds where state-backed financing advantages concentrate project ownership among sovereign entities, marginalizing privately capitalized developers with shorter capital deployment horizons. Long-term viability favors integrated energy-chemical complexes with captive coal reserves and backward control over gasification operations. Acquisition targets should display proven Fischer-Tropsch operational track records and established aviation fuel certification pathways. Watch for carbon border adjustment mechanism expansion as the inflection signal determining export market access.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Integration | Preserves MEE compliance eligibility and green financing access for Chinese facilities. |
| Aviation Fuel Certification Investment | Unlocks ASTM D7566 premiums from Asia-Pacific carriers consolidating procurement. |
| Methanol-to-Olefin Capacity Expansion | Displaces naphtha cracking for polyethylene producers in Ningxia and Ordos. |
| Military Strategic Reserve Contracting | Secures floor-price guarantees from defense ministries in coal-rich jurisdictions. |
| Catalyst Engineering Partnership | Addresses Fischer-Tropsch expertise scarcity constraining new facility ramp rates. |
Study Parameters
Coverage spans China, South Africa, the United States, India, and Australia, with primary inputs from each market informing demand and supply assessments. The approach combines structured interviews with gasification plant managers, aviation fuel procurement officers at state-owned carriers, petrochemical feedstock buyers, and carbon capture engineering specialists, validated against secondary sources including MEE regulatory filings, EPA Tier 3 standards documentation, EIA energy data, and IEA synthetic fuel roadmaps. Bottom-up facility capacity assessments and top-down demand projections were triangulated to establish market sizing.
Granularity-level modeling disaggregated volume and value across product type, technology route, end-user industry, and regional regulatory framework throughout the projection horizon. Segmentation dimensions encompassed diesel versus jet fuel versus methanol outputs, Fischer-Tropsch versus catalytic conversion processes, and petrochemical versus aviation versus transport applications. CAGRs were derived from facility expansion timelines, offtake contract durations, and carbon intensity benchmark implementation schedules. Industry-specific inputs included coal reserve quality variance, syngas conversion efficiency curves, and aviation fuel certification pipeline data.
Underlying measurement precision varies by segment; established production complexes in China and South Africa carry tighter precision than pre-feasibility evaluations in Australia and India. Forecasts reflect assumptions regarding carbon capture cost trajectories, dual carbon policy enforcement intensity, and aviation fuel blend rate mandates. Specific risks that could revise projections include accelerated petroleum substitution from biofuel mandates, breakthroughs in green hydrogen electrolysis economics, and unilateral carbon border adjustment expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America Aviation Fuel Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Global Fuel Ethanol Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Aviation Fuel Additives Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
LNG Fueling Station Market
Fuels
Charcoal Briquette Market
Fuels
Bunker Fuel Market
Fuels
LNG Filling Station Market
Fuels
Global Methane Hydrate Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Turbine Drip Oil Market
Fuels
Coal Briquettes Market